
 Pharma Robots Market | 2026-2036
Pharma Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Robots Market Analytics
Buyer concentration among contract manufacturing organizations is realigning procurement patterns across the pharmaceutical automation landscape. Marchesini Group S.p.A leverages its Italian manufacturing base to dominate packaging and handling lines for European pharma clients. ABB Ltd. anchors its position through deep integration of collaborative robots into sterile filling operations. Fanuc Corporation competes on manufacturing scale, sustaining high-volume output of cleanroom-certified articulated arms for global drug producers.
Pharma robots encompass programmable electromechanical systems engineered for aseptic manipulation, precision dispensing, and material transport within regulated pharmaceutical environments, typically achieving repeatability tolerances below 0.1 millimeter to meet cGMP contamination-control requirements. Their primary commercial purpose centers on eliminating human intervention in sterile processes, reducing particulate generation, and enforcing batch-record traceability. Manufacturing robots within the product type dimension command the largest installed base, though robotic surgery systems capture disproportionate margin pools due to capital intensity and service attach rates. Collaborative robots under the technology dimension represent the fastest-expanding adoption curve, as pharmaceutical manufacturers retrofit existing cleanrooms without full isolation infrastructure.
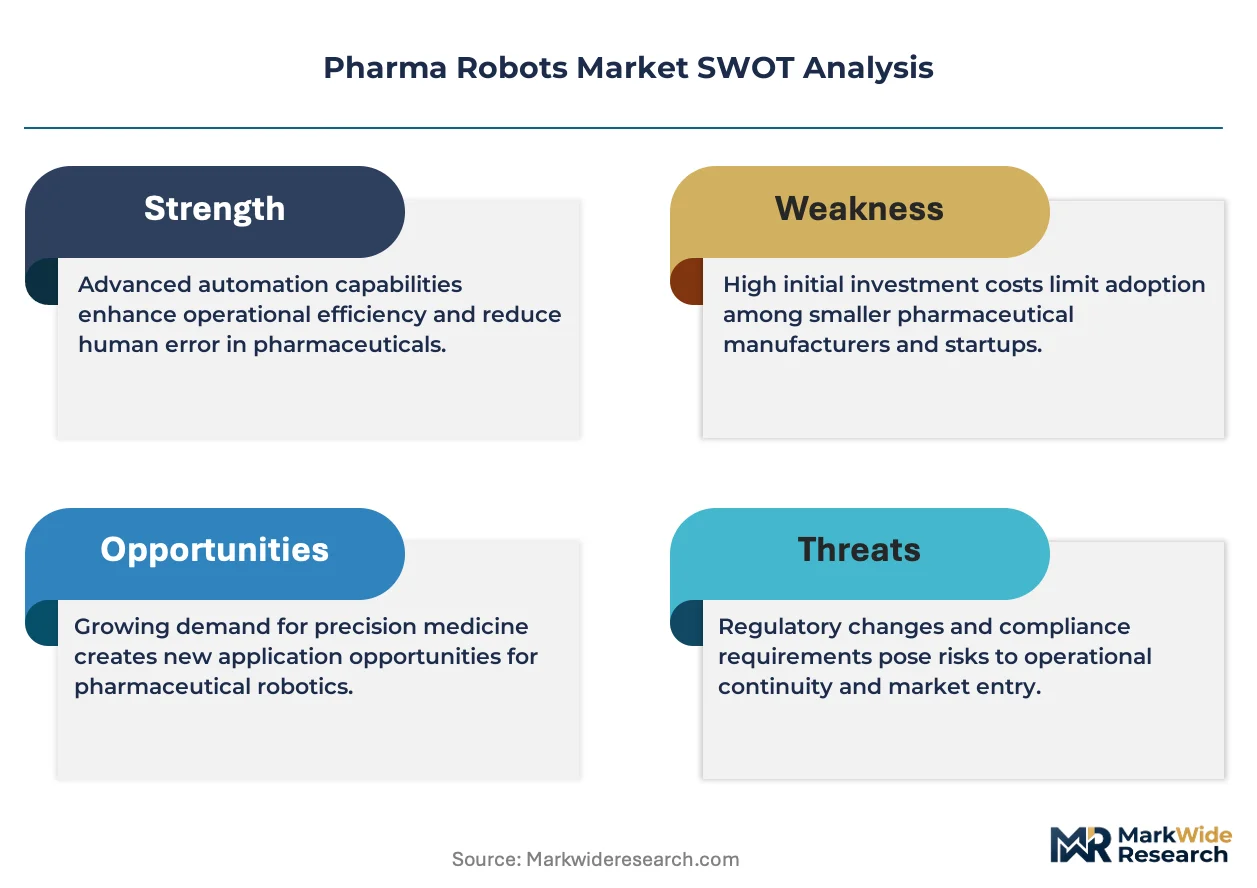
FDA 21 CFR Part 11 compliance requirements and EU MDR device classification frameworks shape software validation burdens and market access timelines for robot OEMs serving pharmaceutical end users. ISO 14644 cleanroom classifications and GAMP 5 lifecycle guidelines further constrain hardware design choices, filtering out suppliers lacking documented quality management systems. Stakeholders must monitor evolving FDA guidance on artificial intelligence in manufacturing equipment, as algorithm-based process control triggers new premarket review pathways distinct from traditional mechanical automation.
Market Dynamics
FDA software validation requirements for 21 CFR Part 11 compliance are compressing vendor qualification timelines while biologics manufacturers accelerate robot deployments for aseptic processing.
Growth Catalysts
- EU MDR Device Classification:Stricter conformity assessment pathways for automated manufacturing equipment are forcing pharmaceutical producers to upgrade legacy systems with validated robotic platforms.
- Biologics Manufacturing Expansion:Cell and gene therapy facilities in Germany, Switzerland, and the United States are installing collaborative robots for sterile filling to meet batch consistency requirements.
- Contamination Control Protocols:ISO 14644-1 cleanroom standards revisions are mandating reduced human intervention in Grade A environments, directly accelerating articulated arm adoption.
Market Restraints
- Stainless Steel Component Costs:Specialized alloys for pharmaceutical-grade robot construction face price volatility tied to nickel supply disruptions from Indonesian export restrictions.
- Validation Service Concentration:Third-party software qualification providers cluster in Germany and Switzerland, creating geographic bottlenecks for FDA submission support.
- Mechanical Precision Limits:Sub-0.05 millimeter repeatability requirements for micro-dosing applications exceed current collaborative robot architectures without full isolation infrastructure.
Strategic Opportunities
- India CDMO Expansion:Contract manufacturing organizations in Hyderabad and Mumbai are retrofitting existing facilities with collaborative robots to capture biologics outsourcing contracts.
- AI-Enabled Process Control:Machine vision integration with robotic arms creates predictive maintenance capabilities that reduce unplanned downtime in continuous manufacturing lines.
- Modular Cleanroom Architecture:Prefabricated isolator systems allow pharmaceutical producers to deploy robotic cells without conventional facility construction timelines.
Industry Challenges
- Mechatronics Talent Scarcity:Pharmaceutical manufacturers compete with automotive and electronics sectors for engineers capable of integrating servo systems with GAMP 5 validation protocols.
- Legacy System Integration:Brownfield facilities face protocol translation complexity when connecting modern robotic controllers to established SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Robots Market |
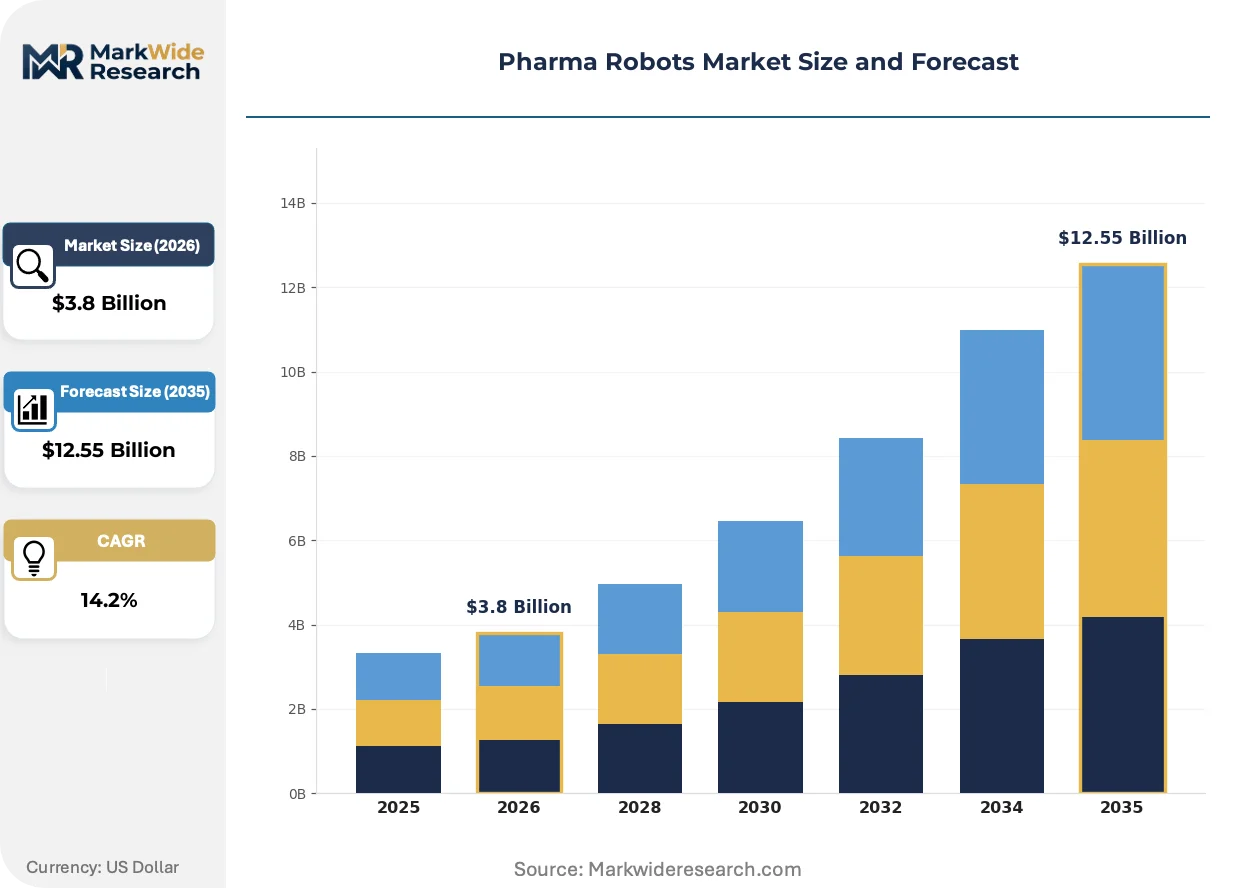
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensing Systems, Robotic Surgery Systems, Inventory Management Robots, Manufacturing Robots Application: Drug Manufacturing, Hospital Pharmacy Automation, Laboratory Automation, Drug Delivery End User: Pharmaceutical Manufacturers, Hospitals, Research Laboratories, Contract Manufacturing Organizations Technology: Artificial Intelligence, Machine Learning, Vision Systems, Collaborative Robots |
| Companies Covered | ABB Ltd., Fanuc Corporation, Yaskawa Electric Corporation, Universal Robots A/S, Kawasaki Heavy Industries Ltd., Marchesini Group S.p.A, Seiko Epson Corporation, Denso Wave Inc., KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Robots Market Evolving Landscape
Robotic platforms are fragmenting into application-specific configurations as pharmaceutical automation moves from standardized cells toward process-integrated deployments.
Collaborative robot hardware is modularizing around interchangeable end-effector architectures that accommodate vial handling, syringe assembly, and lyophilized cake inspection without full line reconfiguration. Mid-sized biologics manufacturers in Switzerland and the Netherlands are adopting these platforms to avoid capital-intensive isolator investments. The structural consequence is compressing deployment timelines from eighteen months to under six months for retrofit installations.
EU AI Act risk classification frameworks are extending to manufacturing equipment algorithms, triggering new conformity assessment requirements for process control software in robotic systems. Pharmaceutical OEMs must now document training data provenance and algorithmic decision pathways for notified body review. High-volume parenteral drug producers in Germany are responding by segregating AI-enabled quality inspection functions from primary process control to limit regulatory exposure.
Service contract unbundling is separating hardware maintenance from software validation support, allowing contract manufacturing organizations to source technical expertise from specialized regional providers. Traditional robot OEMs face margin pressure as Indian and South Korean third-party service firms capture calibration and requalification work. This pattern is most pronounced among CDMOs operating multi-product facilities in Singapore and Ireland where equipment utilization rates demand rapid response capabilities.
Pharma Robots Market Segmentation
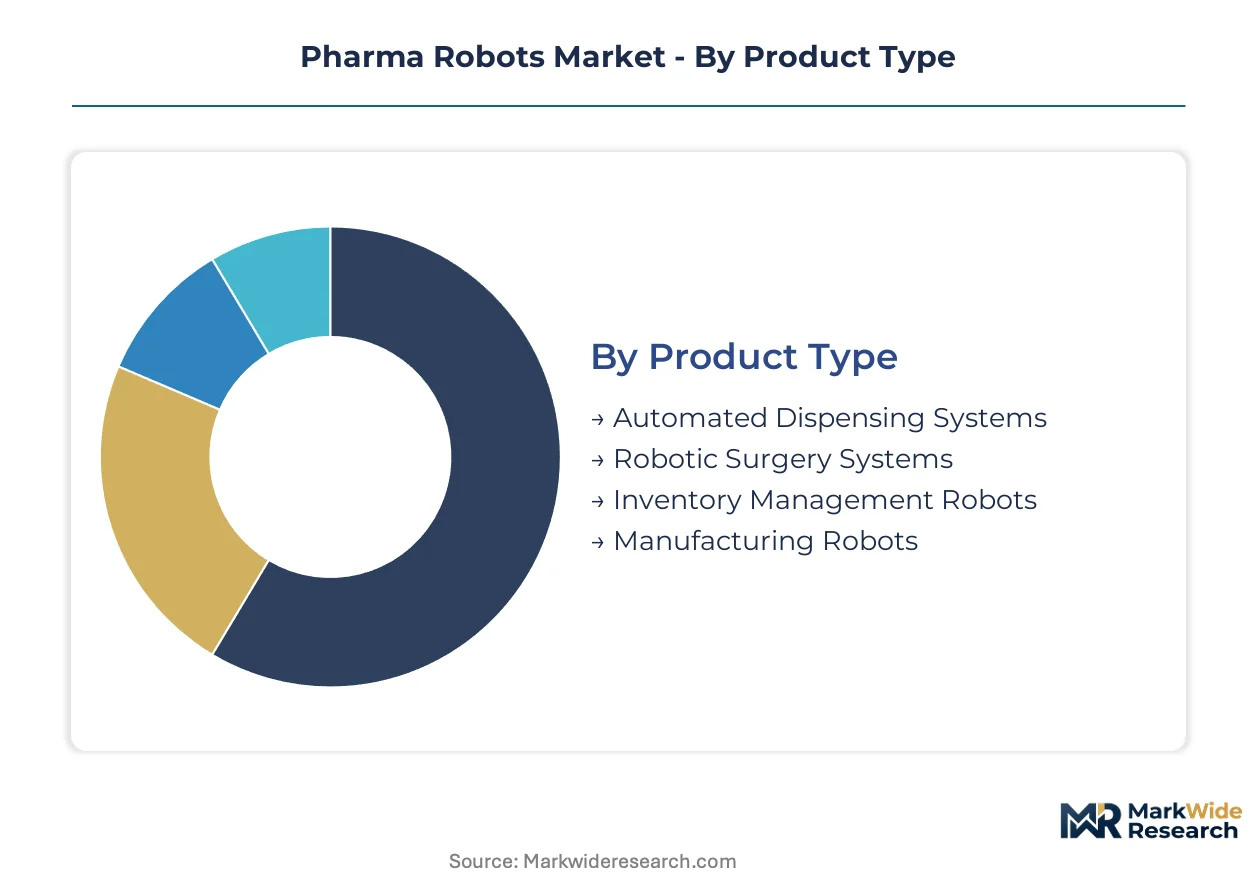
Pharmaceutical automation procurement splits sharply between high-volume manufacturing deployments and premium surgical platforms, with each segment carrying distinct regulatory burdens and margin profiles. Understanding these fault lines reveals where capital allocation concentrates and which technologies command pricing power.
Product Type:
Volume concentration sits with manufacturing hardware while premium capture belongs to surgical systems requiring intensive service attach rates.
- Manufacturing Robots:Articulated arms and SCARA configurations engineered for aseptic filling, packaging, and material handling achieve sub-0.1 millimeter repeatability under ISO 14644-1 Grade A conditions. Demand clusters in Germany and Switzerland where Bosch and KUKA anchor pharmaceutical automation clusters, driven by biologics manufacturers retrofitting legacy facilities for cell and gene therapy production.
- Robotic Surgery Systems:Capital-intensive platforms for minimally invasive procedures command disproportionate margin pools through proprietary instrument ecosystems and long-term service contracts. Swiss and German hospital networks concentrate procurement, constrained by EU MDR conformity assessment timelines and specialized training requirements for surgical staff.
- Automated Dispensing Systems:Pharmacy automation for unit-dose packaging and medication distribution.
- Inventory Management Robots:Autonomous mobile platforms for warehouse and cold-chain logistics.
Today's leader: Manufacturing Robots. Tomorrow's challenger: Robotic Surgery Systems.
Application:
Drug manufacturing absorbs the majority of installed base while laboratory automation climbs fastest on precision requirements.
- Drug Manufacturing:Aseptic processing, sterile filling, and packaging operations dominate robot deployment counts across parenteral drug facilities. German biologics producers drive specification standards, requiring stainless steel construction and FDA 21 CFR Part 11 software validation for batch record traceability.
- Laboratory Automation:High-throughput screening, sample preparation, and analytical testing integrate collaborative robots with machine vision. Dutch and Swiss contract research organizations retrofit existing cleanrooms without full isolator infrastructure, compressing deployment timelines.
- Hospital Pharmacy Automation:Medication dispensing and compounding in clinical settings.
- Drug Delivery:Patient-facing applications including autoinjector assembly and personalized dosing systems.
Drug Manufacturing holds installed base dominance. Laboratory Automation gains share fastest on retrofit economics.
End User:
Contract manufacturing organizations are realigning procurement patterns through unbundled service contracts and rapid requalification demands.
- Pharmaceutical Manufacturers:Integrated biologics and small-molecule producers specify validated robotic platforms for internal capacity expansion. German facilities anchor demand concentration, with FDA validation requirements compressing vendor qualification timelines for software-heavy systems.
- Contract Manufacturing Organizations:Multi-product facilities in Singapore and Ireland prioritize modular robotic cells with rapid changeover capabilities. Indian CDMOs in Hyderabad and Mumbai are retrofitting existing infrastructure to capture biologics outsourcing contracts.
- Hospitals:Clinical settings deploying pharmacy automation and surgical robotics.
- Research Laboratories:Academic and commercial R&D facilities integrating automation for reproducibility.
Pharmaceutical Manufacturers retain specification authority. Contract Manufacturing Organizations are expanding procurement fastest on outsourcing trends.
Technology:
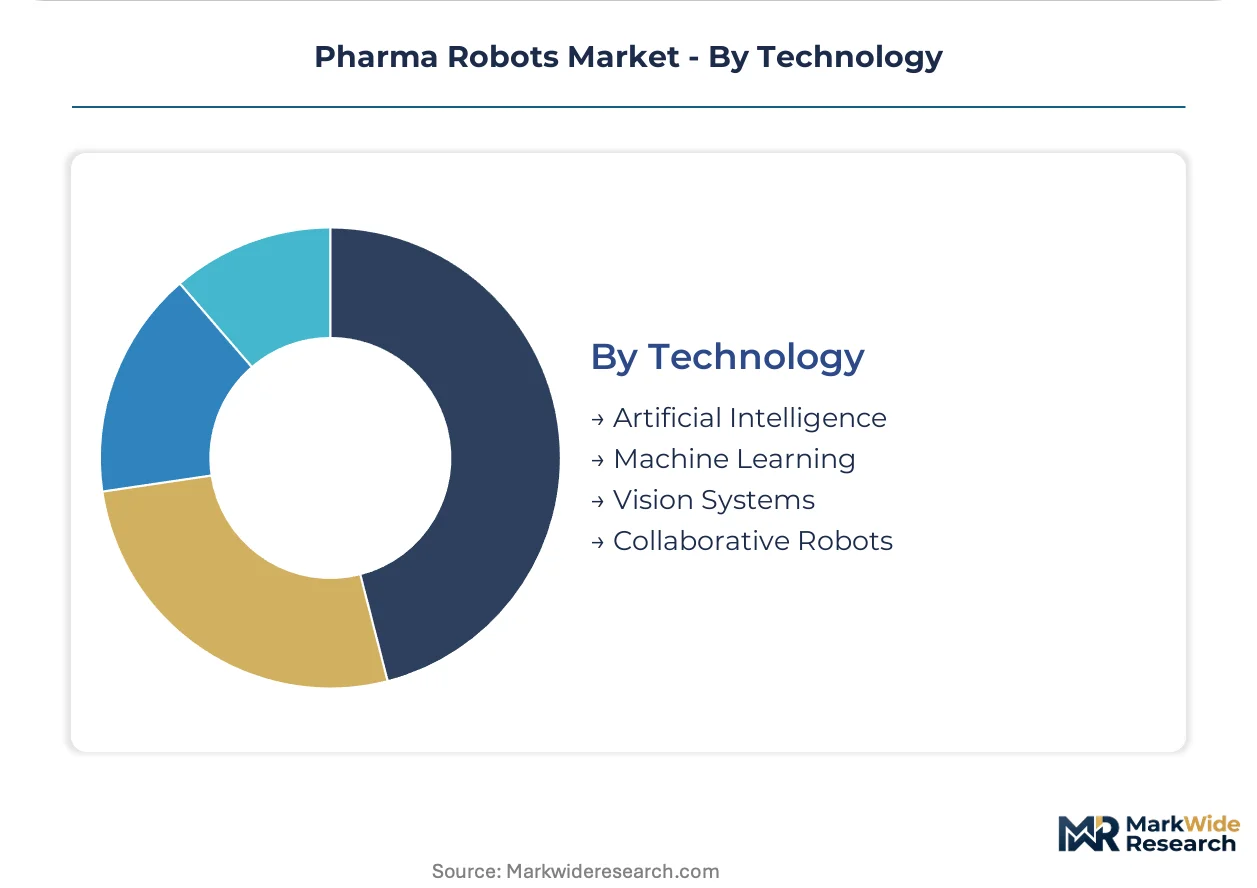
Collaborative architectures are displacing traditional isolation while AI integration triggers new regulatory exposure under EU conformity frameworks.
- Collaborative Robots:Force-limited articulated arms designed for human-robot interaction without full safety enclosures enable retrofit deployment in existing cleanrooms. Mid-sized Swiss and Dutch biologics manufacturers adopt these platforms to avoid capital-intensive isolator investments, compressing deployment timelines from eighteen months to under six months.
- Artificial Intelligence:Algorithm-based process control and predictive maintenance capabilities reduce unplanned downtime in continuous manufacturing lines. EU AI Act risk classification frameworks extend to manufacturing equipment algorithms, triggering new conformity assessment requirements that German producers address by segregating AI-enabled quality inspection from primary process control.
- Machine Learning:Pattern recognition for process optimization and anomaly detection.
- Vision Systems:Machine vision integration for inspection, guidance, and quality verification.
Collaborative Robots dominate retrofit economics. Artificial Intelligence faces regulatory headwinds but promises the steepest capability expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized mechatronics talent pools concentrate in German industrial clusters, Swiss precision engineering corridors, and emerging Indian pharmaceutical manufacturing zones, anchoring regional deployment patterns for validated robotic systems.
Germany
Biologics manufacturers in Baden-Württemberg and Bavaria drive specification standards for stainless steel articulated arms with sub-0.1 millimeter repeatability. KBA and FDA dual-validation requirements compress vendor qualification timelines for software-heavy systems. The Stuttgart automation cluster anchors KUKA and Bosch pharmaceutical robotics development, with cell and gene therapy facilities retrofitting legacy infrastructure.
Switzerland
Mid-sized biologics producers in Basel and Zurich prioritize collaborative robot deployments to avoid capital-intensive isolator investments. Swissmedic oversight of automated manufacturing equipment enforces GAMP 5 lifecycle documentation for batch record traceability. The Basel pharmaceutical corridor concentrates contract manufacturing organizations adopting modular robotic cells with rapid changeover capabilities.
United States
FDA 21 CFR Part 11 compliance requirements tighten software qualification standards for aseptic processing systems across Massachusetts and North Carolina biomanufacturing hubs. The agency's evolving guidance on artificial intelligence in manufacturing equipment triggers new premarket review pathways. Greater Boston anchors cell therapy facilities installing collaborative robots for sterile filling operations.
India
Contract manufacturing organizations in Hyderabad and Mumbai retrofit existing facilities with collaborative robots to capture biologics outsourcing contracts. CDSCO alignment with FDA validation protocols accelerates qualification timelines for exported automated systems. The Hyderabad pharmaceutical cluster drives demand for rapid-deployment robotic cells serving multi-product CDMO facilities.
Japan
PMDA oversight of manufacturing equipment algorithms shapes software validation burdens for robotic systems in Osaka and Tokyo pharmaceutical zones. METI industrial automation incentives support cleanroom-certified articulated arm production for domestic drug producers. The Osaka-Kobe manufacturing corridor concentrates precision dispensing robot development for aseptic processing applications.
Pharma Robots Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with consolidated leadership in industrial automation hardware and fragmented competition in pharmaceutical-specific application engineering. The vendor base stratifies between scale-driven articulated arm producers, collaborative robot modularizers, and regional packaging system integrators. Two dominant competitive moves shape positioning: M&A activity targeting software validation capabilities and strategic partnerships with CDMOs for rapid requalification service contracts.
Within the diversified industrial automation tier, ABB Ltd. and Fanuc Corporation exemplify scale-driven architectures serving pharmaceutical-grade cleanroom requirements. Among European packaging specialists, Marchesini Group S.p.A occupies a position representing Italian manufacturing-base dominance in handling line integration. KUKA AG anchors German precision engineering concentration for aseptic processing applications. These three entities represent distinct competitive archetypes: conglomerate-scale hardware, regional application specialization, and precision automation engineering.
| Leading Market Players |
|---|
| ABB Ltd. |
| Fanuc Corporation |
| Yaskawa Electric Corporation |
| Universal Robots A/S |
| Kawasaki Heavy Industries Ltd. |
| Marchesini Group S.p.A |
| Seiko Epson Corporation |
| Denso Wave Inc. |
| KUKA AG |
| Others |
Value Network & Pricing Analysis
Nickel price volatility on the London Metal Exchange cascades through stainless steel alloy costs into pharmaceutical robot pricing tiers, with Grade 316L component expenses compressing margins for mid-tier articulated arm suppliers while premium cleanroom-certified systems maintain pricing power through validated software bundles.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for cleanroom-certified servo motors and harmonic drives. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated systems with full GAMP 5 documentation from basic ISO-certified hardware. Price differentiation hinges on software qualification depth and stainless steel construction grade. Cost compression in the standard tier is intensifying because Indian CDMOs are negotiating unbundled service contracts. Contract manufacturing organizations exhibit highest price sensitivity; integrated biologics manufacturers prioritize validation reliability over unit cost.
Supply Chain Analysis
ISO 14644-1 certification and FDA 21 CFR Part 11 software qualification act as gating mechanisms that filter supplier participation. Component manufacturing concentrates in Germany, Japan, and Switzerland for precision gearboxes and cleanroom-grade servo systems. Supply chains draw from nickel mining in Indonesia, rare earth magnet processing in China, and specialized stainless steel forging in Sweden. Single-source vulnerability sits with German third-party validation service providers clustered around Stuttgart and Munich. Distribution runs through regional automation distributors with pharmaceutical sector expertise, anchored by KUKA and Bosch service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharma robot margins expand through AI-enabled predictive maintenance attach rates and modular retrofit economics that reduce customer capital deployment. Stainless steel component cost pass-through mechanisms and unbundled software service contracts anchor the margin expansion thesis.
For Market Incumbents: Lock in long-term service contracts with multi-product CDMOs in Singapore and Ireland before Indian third-party validation firms capture requalification work. Deepen backward integration into cleanroom-grade stainless steel component production to offset nickel price volatility. Prioritize AI-enabled quality inspection modules that can be segregated from primary process control to limit EU AI Act regulatory exposure.
For New Entrants and Emerging Players: Digital-channel partnerships with pharmaceutical engineering consultancies offer the lowest-friction entry path into brownfield facility retrofit projects. Target mid-sized Dutch and Swiss biologics manufacturers adopting collaborative robots without full isolator infrastructure. Lead with rapid-deployment modular cells compressing installation timelines below six months.
For Investors and Strategic Acquirers: Asymmetric upside sits with software validation specialists possessing FDA 21 CFR Part 11 expertise and GAMP 5 lifecycle documentation capabilities. Five-to-ten year viability favors acquisition targets serving CDMOs with rapid requalification service contracts. Watch for CDSCO-FDA alignment acceleration in Indian pharmaceutical clusters as inflection signal for outsourcing contract migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Validation Capability Acquisition | FDA 21 CFR Part 11 expertise compresses vendor qualification timelines for biologics manufacturers. |
| Modular Cleanroom Cell Development | Prefabricated isolator systems bypass conventional facility construction timelines for CDMO retrofits. |
| AI-Enabled Predictive Maintenance Launch | Machine vision integration reduces unplanned downtime in continuous manufacturing lines. |
| Indian CDMO Service Partnership | Hyderabad and Mumbai facilities drive demand for rapid-deployment robotic cells. |
| Stainless Steel Component Backward Integration | In-house production of Grade 316L parts offsets nickel supply disruption exposure. |
Research Methodology
Multiple input streams — primary interviews with pharmaceutical automation directors, regulatory affairs leads at robot OEMs, and CDMO procurement managers — were reconciled against secondary validation from FDA 510(k) filings, EMA medical device registrations, and GAMP 5 guideline documentation. Bottom-up installed base estimates across Germany, Switzerland, the United States, and India were triangulated with top-down market sizing derived from capital expenditure disclosures by major biologics manufacturers.
Historical shipment data was cross-referenced against expert panel assessments of collaborative robot adoption velocity across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology, with additional stratification by regional regulatory cluster. CAGRs were derived from weighted average growth assumptions across these segments, incorporating biologics manufacturing expansion rates and EU MDR device classification implementation timelines as industry-specific forecast inputs.
Regulatory guidance evolution, nickel commodity price shocks, and AI Act conformity assessment pathway clarifications are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in FDA artificial intelligence manufacturing equipment guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Electrophysiology Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Colposcopes Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Trocars Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Cochlear Implant Systems Market