
 Osmotic Pumps Market | 2026-2036
Osmotic Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Osmotic Pumps Market Analytics
Homecare providers are reorganizing their infusion therapy portfolios around wearable and portable osmotic systems that reduce nursing visits. DURECT leverages its implantable pump platform to anchor long-acting pain therapy contracts with specialty pharmacies. ALZA competes through sustained R&D intensity in reservoir membrane chemistry. Insulet Corporation differentiates by controlling the channel between wearable insulin delivery and patient mobile apps.
Osmotic pumps are implantable or wearable drug delivery devices that use osmotic pressure differentials across semipermeable membranes to release therapeutic agents at controlled zero-order kinetics, typically achieving release rates from nanoliters to microliters per hour over days to weeks. These devices serve chronic conditions requiring steady plasma concentrations without patient intervention, spanning pain management, diabetes, and hormone replacement. Implantable pumps occupy the highest margin pool due to surgical placement requirements and specialized servicing protocols, while wearable pumps represent the fastest-expanding category as homecare reimbursement broadens. Reservoir technology leads in installed base but microchip-enabled feedback systems are displacing passive osmotic engines in premium segments.
The FDA regulates osmotic pumps as combination products, requiring simultaneous review with the Center for Devices and Radiological Health and the Center for Drug Evaluation and Research, which extends development timelines but raises barriers against low-cost entrants. The EU MDR and EMA's notified body recertification demands are forcing manufacturers to rebuild clinical evidence packages for legacy implantable platforms. Stakeholders must monitor how FDA digital health guidance intersects with pump connectivity claims, as software-enabled dose adjustment could trigger reclassification and new predicate requirements.
Market Dynamics
The FDA's combination product reclassification and EU MDR recertification timelines are compressing development cycles while elevating clinical evidence requirements for osmotic pump manufacturers. These regulatory pressures favor firms with established predicate devices and captive biocompatibility testing infrastructure.
Growth Catalysts
- Homecare reimbursement expansion:CMS and private payers in the United States are expanding durable medical equipment coverage for wearable infusion systems, reducing hospital readmission costs for chronic pain and diabetes patients.
- EU MDR Article 117 implementation:The mandatory drug-device consultation pathway for combination products is accelerating partnerships between pump engineers and formulation scientists to streamline technical documentation.
- Silicon nitride membrane advances:Precision micromachining of ceramic reservoirs is extending implantable pump functional lifespans beyond legacy polymer-based platforms.
Market Restraints
- Platinum-catalyzed silicone oligomer supply:Medical-grade elastomer precursor concentration among German and Japanese chemical suppliers creates input cost volatility and qualification bottlenecks for new entrants.
- Zero-order kinetic limitations:Passive osmotic engines cannot accommodate variable dosing regimens required for titratable therapies, restricting addressable indications.
- FDA dual-center review timelines:Simultaneous CDRH and CDER evaluation extends premarket approval durations by 18-24 months compared to standalone device pathways.
Strategic Opportunities
- Japan's Super City integrated care zones:METI-funded regional health data platforms are creating procurement channels for connected pump systems that transmit adherence metrics to municipal care coordinators.
- Closed-loop glucose-responsive integration:Convergence of continuous glucose monitoring algorithms with osmotic insulin reservoirs enables autonomous glycemic control without patient intervention.
- Specialty pharmacy direct distribution:Bypassing wholesale distributors to ship prefilled implantable pumps directly to ambulatory surgical centers reduces cold chain handoffs and expiration risk.
Industry Challenges
- Biocompatibility toxicologist scarcity:ISO 10993-1 cytotoxicity and sensitization study design expertise concentrates among contract research organizations with decade-long FDA submission track records.
- Legacy hospital IT integration:Pump connectivity protocols must interface with fragmented electronic health record systems across Epic, Cerner, and MEDITECH installations without standardized APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osmotic Pumps Market |
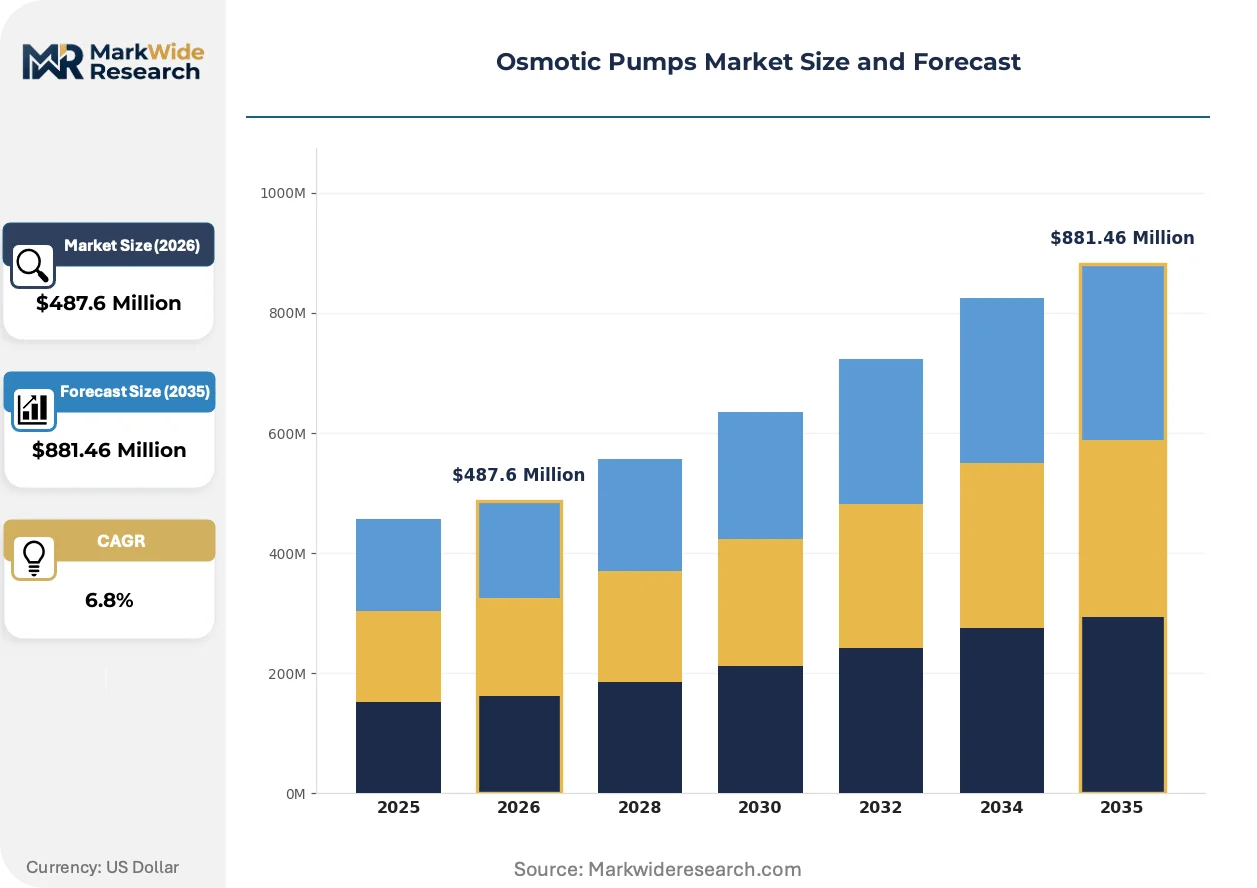
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Pumps, Portable Pumps, Wearable Pumps, Refills End User: Hospitals, Homecare, Clinics, Research Centers Application: Pain Management, Diabetes Treatment, Hormone Therapy, Vaccine Delivery Technology: Microchip Technology, Valve Technology, Reservoir Technology, Others |
| Companies Covered | DURECT, ALZA, Colorcon, RWD, ALZET, Medtronic, Becton Dickinson and Company, Insulet Corporation, Tandem Diabetes Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osmotic Pumps Market Evolving Landscape
Microchip-enabled feedback mechanisms are redefining competitive positioning in osmotic pump categories, shifting value capture from passive reservoir engineering toward algorithmic dose optimization and remote patient monitoring ecosystems.
Electro-osmotic actuation is supplanting traditional membrane-controlled diffusion in premium implantable segments. Academic medical centers in Germany and Switzerland are piloting these active systems for variable-rate pain therapy where patient-controlled analgesia demands exceed passive pump capabilities. The technology is supplanting fixed-rate ALZET-style platforms in oncology supportive care protocols where dose escalation flexibility determines formulary placement.
EMA's 2023 MDR guidance on legacy device clinical evaluation is forcing manufacturers to regenerate clinical evidence for implantable pumps approved under the Medical Device Directive. Industrial consequence includes mandatory post-market clinical follow-up studies for reservoir fracture rates and catheter occlusion events. Implantable pain therapy devices with decade-old 510(k) predicates face the steepest compliance burden as notified bodies demand prospective registries rather than literature-based equivalence arguments.
Hospital procurement committees are consolidating infusion therapy vendor lists to single-source agreements with outcome guarantees. Specialty pharmacy networks are displacing traditional durable medical equipment distributors as the primary channel for wearable pump fulfillment and patient training. This channel migration is most visible in United States Medicare Advantage plans where vertical integration between payers and pharmacy benefit managers enables direct pump deployment with remote monitoring bundled into per-member-per-month capitation rates.
Osmotic Pumps Market Segmentation
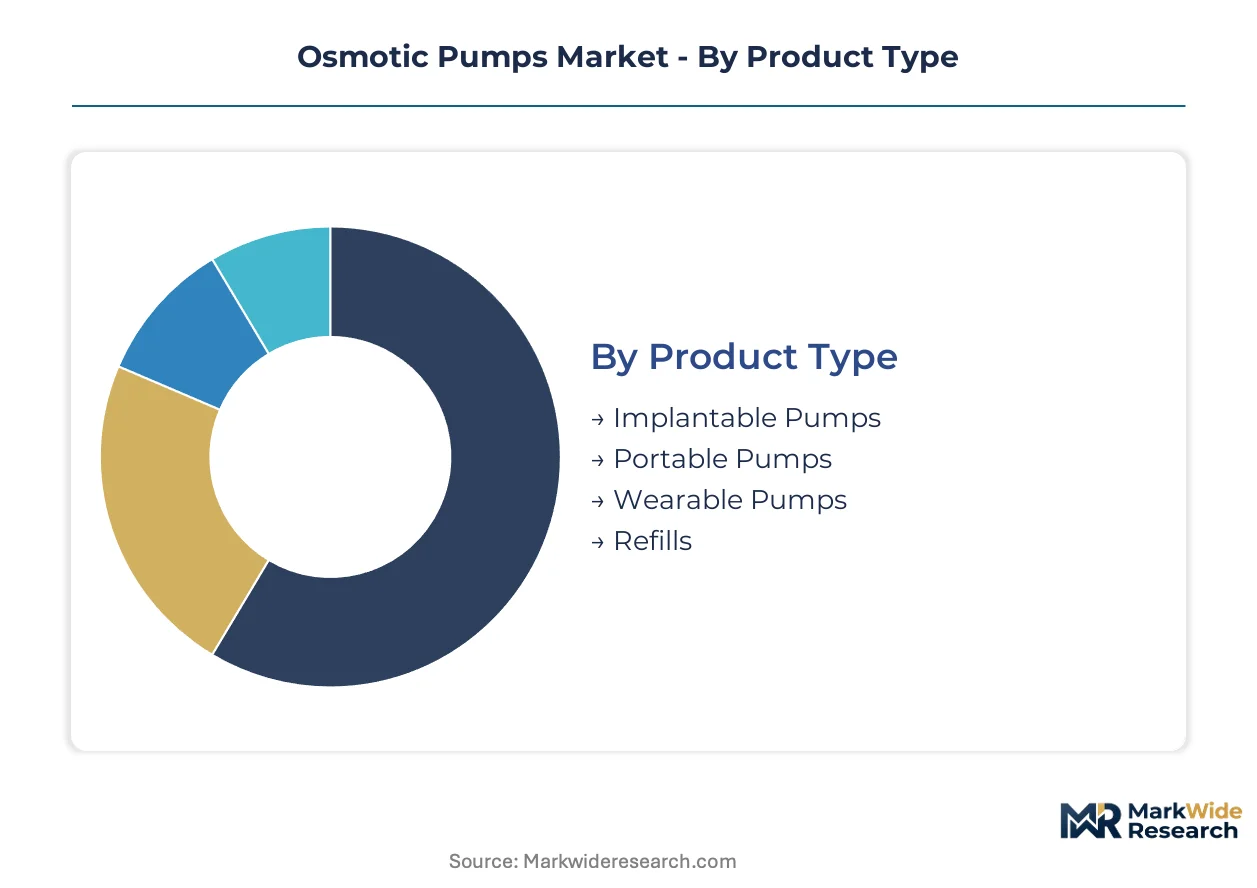
Osmotic pump manufacturers configure product portfolios across four intersecting dimensions. Each segmentation axis carries distinct margin profiles, regulatory pathways, and geographic demand concentrations that reshape competitive positioning.
Product Type:
Implantable systems dominate domestic procurement in surgical centers across the United States and Germany, while portable and wearable formats drive export volumes into Japan's homecare reimbursement zones.
- Implantable Pumps:Surgical placement devices with ceramic or polymer reservoirs deliver zero-order kinetics over weeks to months. United States Medicare reimbursement for chronic pain implantation anchors demand concentration, though FDA dual-center review extends approval timelines.
- Portable Pumps:External devices with belt-clip or carrying-case configurations enable ambulatory infusion outside clinical settings. German hospital procurement committees favor these for oncology supportive care transitions, balancing mobility against infection risk.
- Wearable Pumps:Adhesive-patch systems integrate directly with patient skin for continuous subcutaneous delivery. Japan's METI-funded Super City care zones are piloting connected variants with municipal adherence monitoring.
- Refills:Pre-filled reservoir cartridges reduce pharmacy compounding burden and cold chain handoffs. Specialty pharmacy direct distribution models in United States Medicare Advantage plans favor these for expiration risk reduction.
Implantable pumps hold the largest share; momentum sits with wearable pumps.
End User:
Cost tier stratification separates capital-intensive hospital installations from distributed homecare deployments with per-patient service revenue models.
- Hospitals:Academic medical centers in Switzerland and Germany pilot electro-osmotic actuation systems for variable-rate pain protocols where patient-controlled analgesia demands exceed passive pump capabilities.
- Homecare:Reimbursement expansion for durable medical equipment in United States CMS and private payer networks reduces nursing visit frequency for diabetes and chronic pain patients.
- Clinics:Ambulatory surgical centers receive prefilled implantable pumps through specialty pharmacy direct channels, bypassing wholesale distributors to minimize cold chain exposure.
- Research Centers:Preclinical pharmacokinetic studies utilize ALZET-style mini-pumps for rodent model standardization, with procurement concentrated among contract research organizations with decade-long FDA submission track records.
Hospitals command premium pricing; homecare represents the steepest expansion trajectory.
Application:
Volume concentration varies by therapeutic area maturity and reimbursement clarity across United States, German, and Japanese health systems.
- Pain Management:Chronic opioid delivery for cancer and non-malignant pain dominates implantable pump utilization. United States specialty pharmacy networks anchor long-acting therapy contracts with surgical placement bundled into episode-based payments.
- Diabetes Treatment:Insulin osmotic reservoirs converge with continuous glucose monitoring algorithms for closed-loop glycemic control. Japanese integrated care zones prioritize connected systems transmitting adherence metrics to municipal coordinators.
- Hormone Therapy:Testosterone and growth hormone replacement protocols utilize portable pumps for patient self-administration. German endocrinology clinics favor these for compliance monitoring in aging demographics.
- Vaccine Delivery:Extended-release antigen presentation for livestock and companion animal applications employs reservoir technology. Research demand concentrates in United States veterinary pharmaceutical development programs.
Pain management holds the largest share; diabetes treatment is gaining share fastest.
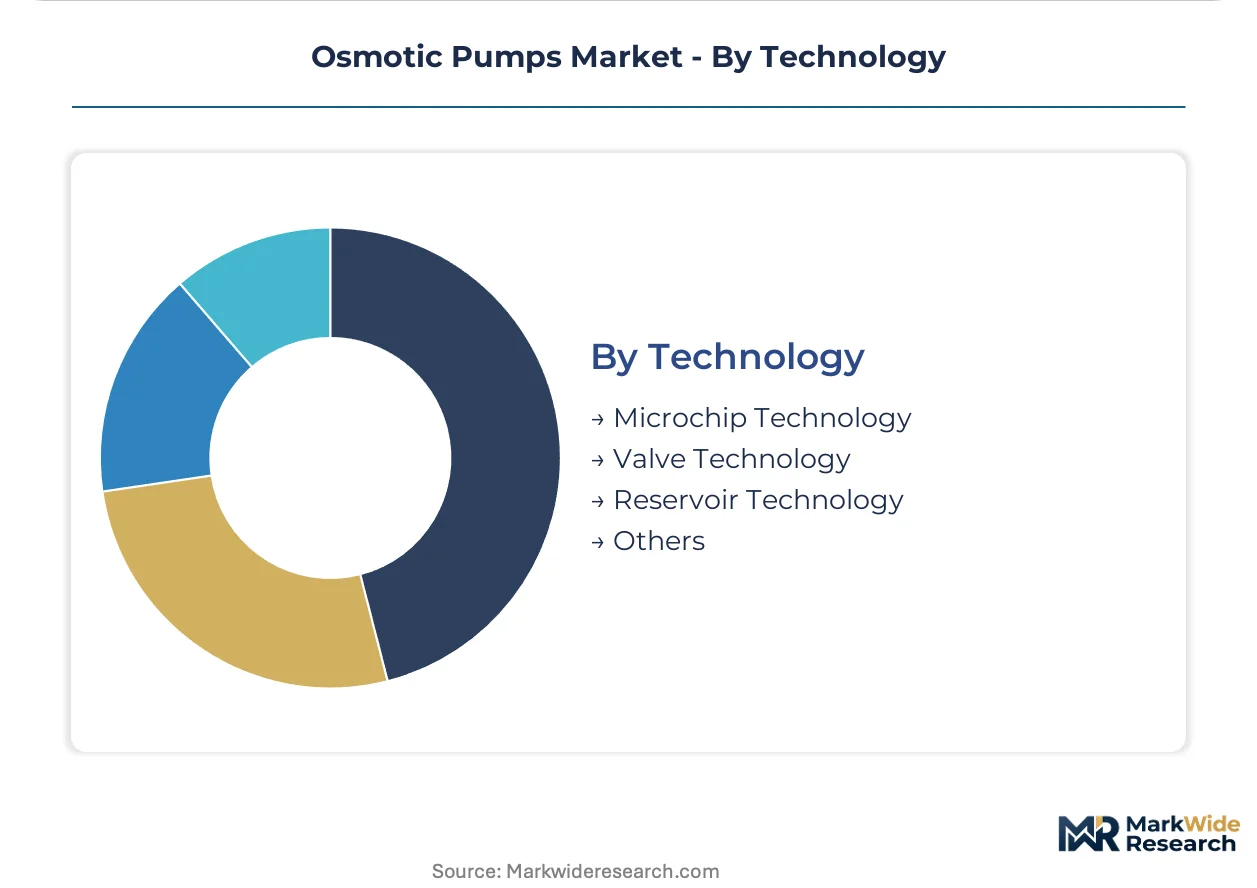
Technology:
Supply concentration for biocompatibility testing expertise shapes competitive access to premium segments with algorithmic dose optimization capabilities.
- Microchip Technology:Feedback-enabled systems with sensor integration and wireless connectivity enable remote dose adjustment. FDA digital health guidance intersecting with pump connectivity claims threatens reclassification to higher scrutiny pathways.
- Valve Technology:Mechanical flow control mechanisms provide simpler regulatory profiles but lack titration flexibility. These occupy mid-tier pricing in European markets where EU MDR recertification demands favor established predicate devices.
- Reservoir Technology:Passive osmotic engines with semipermeable membranes constitute the historical installed base. EMA MDR Article 117 implementation forces drug-device consultation partnerships to streamline technical documentation for legacy platforms.
- Others:Emerging electro-osmotic actuation and piezoelectric mechanisms pilot in German and Swiss academic centers for variable-rate applications exceeding passive engine capabilities.
Reservoir technology holds the largest share; microchip technology shows the strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution gravity for implantable pump systems requiring temperature-controlled logistics from German manufacturing clusters to surgical centers.
United States
Medicare Advantage capitation models in Florida and Arizona drive bundled reimbursement for wearable pain therapy systems. FDA dual-center review timelines for combination products extend development cycles but elevate barriers against low-cost entrants. The Boston-Cambridge corridor concentrates electro-osmotic actuation pilot programs at academic medical centers.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia consolidate infusion therapy vendor lists to single-source agreements with outcome guarantees. EU MDR Article 117 implementation accelerates drug-device consultation partnerships between pump engineers and formulation scientists. The Stuttgart region anchors precision micromachining capabilities for silicon nitride membrane production.
Japan
METI-funded Super City integrated care zones in Osaka and Fukuoka create procurement channels for connected pump systems transmitting adherence metrics to municipal coordinators. PMDA streamlined review pathways for combination products with predicate devices reduce time-to-market for reservoir technology platforms. The Kanto region dominates domestic manufacturing of medical-grade elastomer precursors.
Switzerland
Swissmedic's alignment with EMA MDR recertification timelines forces manufacturers to regenerate clinical evidence for legacy implantable platforms. Basel's pharmaceutical cluster hosts contract research organizations with decade-long FDA submission track records for biocompatibility testing. Zurich academic centers pilot variable-rate pain therapy protocols exceeding passive osmotic engine capabilities.
United Kingdom
NHS England's specialized commissioning frameworks for chronic pain services concentrate implantable pump utilization in London and Manchester tertiary centers. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for manufacturers maintaining CE marking and UKCA certification. The Cambridge-Oxford arc concentrates preclinical pharmacokinetic research utilizing mini-pump platforms.
Osmotic Pumps Market Competitive Landscape
Concentration sits with diversified medical device conglomerates and specialized drug delivery platform developers. The vendor base stratifies across three tiers: integrated hospital system suppliers with captive servicing infrastructure, specialty pharmacy network partners with direct-to-patient fulfillment capabilities, and contract research organizations with regulatory submission expertise. Competitive moves center on strategic partnerships between pump engineers and formulation scientists, alongside specialty pharmacy direct distribution channel capture.
Within the diversified device tier, Medtronic and Becton Dickinson and Company represent established predicate device holders with captive biocompatibility testing infrastructure. Among drug delivery specialists, DURECT and Insulet Corporation occupy positions at the intersection of wearable platform development and patient mobile app integration. ALZA exemplifies sustained R&D intensity in reservoir membrane chemistry.
| Leading Market Players |
|---|
| DURECT |
| ALZA |
| Colorcon |
| RWD |
| ALZET |
| Medtronic |
| Becton Dickinson and Company |
| Insulet Corporation |
| Tandem Diabetes Care |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German silicone precursor suppliers and implantable pump manufacturers lock in platinum-catalyzed elastomer access while stabilizing input cost visibility across multi-year procurement cycles. These arrangements concentrate pricing power with established device makers holding captive biocompatibility testing infrastructure, while newer entrants face qualification bottlenecks that compress their margin flexibility.
Pricing Analysis
Volume-discount tiering structures separate implantable systems commanding premium surgical-placement fees from wearable formats competing on per-patient service economics. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA predicate device status and ISO 10993-1 certification completeness. Pricing pressure stems from CMS reimbursement compression for durable medical equipment in United States Medicare Advantage plans. Homecare providers exhibit highest price sensitivity due to capitated per-member-per-month contracts, while academic medical centers in Switzerland and Germany absorb premium tiers for electro-osmotic actuation pilots.
Supply Chain Analysis
Inventory lead times for medical-grade silicon nitride membranes extend qualification cycles as precision micromachining capacity concentrates in Germany and Japan. Raw material dependencies center on platinum-catalyzed silicone oligomers from Kanto-region chemical clusters, ceramic reservoir substrates from Stuttgart-area suppliers, and biocompatibility testing services from Basel-based contract research organizations. Single-source vulnerability runs through German elastomer precursor concentration, with tariff exposure on Japanese ceramic inputs amplifying cost volatility. Distribution runs through specialty pharmacy direct channels bypassing wholesale distributors, reducing cold chain handoffs for prefilled implantable pumps shipped to ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The osmotic pump sector sits at a platform-economics inflection where closed-loop glucose-responsive integration and municipal adherence monitoring in Japan's Super City zones are redefining value capture from hardware margins toward algorithmic service ecosystems.
For Market Incumbents: Secure captive biocompatibility testing infrastructure through acquisition or exclusive partnership with Basel-based contract research organizations holding decade-long FDA submission track records. Lock in long-term offtake agreements with Kanto-region silicone precursor suppliers to defend against input cost volatility threatening standard-tier margin compression.
For New Entrants and Emerging Players: FDA's 510(k) predicate pathway for reservoir technology platforms offers fastest regulatory clearance relative to microchip-enabled feedback systems facing dual-center review delays. Target Japan's METI-funded integrated care zones where municipal procurement channels for connected pumps remain underpenetrated by Western device makers. Lead with software companion development partnerships rather than hardware manufacturing scale-up.
For Investors and Strategic Acquirers: Drug-device consultation specialists with EU MDR Article 117 technical documentation expertise represent prime acquisition targets as recertification timelines compress. Long-term viability hinges on algorithmic dose optimization capabilities displacing passive osmotic engines. Watch FDA digital health guidance intersecting with pump connectivity claims as reclassification signal that would trigger new predicate requirements and reshape competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Single-source agreements with outcome guarantees consolidate vendor lists in German procurement committees. |
| Software Companion Development | Patient mobile app integration enables remote adherence monitoring valued by Japanese municipal care coordinators. |
| CE Marking Pathway | EU MDR Article 117 drug-device consultation streamlines technical documentation for legacy reservoir platforms. |
| Reimbursement Strategy | Medicare Advantage capitation models in Florida and Arizona bundle wearable pain therapy into per-member-per-month rates. |
| Backward Integration | In-house production of silicon nitride membranes reduces dependency on Stuttgart-area precision micromachining suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers specializing in infusion therapy, specialty pharmacy network directors, and regulatory affairs leads navigating FDA dual-center review pathways. Secondary validation drew from FDA 510(k) and PMA filings, EMA MDR submission databases, CMS durable medical equipment reimbursement schedules, and hospital GPO contract repositories. Bottom-up unit economics triangulated against top-down market sizing across implantable, portable, wearable, and refill product categories.
Across the projection horizon, analytical frameworks modeled volume and value trajectories by product type, end user, application, and technology segmentation with particular attention to microchip-enabled feedback system displacement rates. CAGRs were derived from fitted growth curves anchored to reimbursement expansion timelines and regulatory approval velocity. Industry-specific forecast inputs incorporated EU MDR recertification backlog estimates and METI Super City procurement pilot scale-up assumptions.
Underlying assumptions cover stable platinum-catalyzed silicone precursor supply from Japanese chemical clusters, with deviation risk concentrated in FDA digital health guidance reclassification and NHS England specialized commissioning framework revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Kirschner Wires Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Thrombectomy System Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Disposable Thermometer Market
Medical Devices
Capsulotomy Market
Medical Devices
Global Ventilators Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
US Wearable Medical Devices Market