
 Sonohysterography Catheters Market | 2026-2036
Sonohysterography Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Sonohysterography Catheters Market Analytics
Ambulatory surgical centers and fertility clinics is redrawing procurement patterns for sonohysterography catheters, pulling volume away from traditional hospital purchasing committees. CooperSurgical leverages direct-to-clinic distribution networks across North America. Cook Group anchors its position through deep specialization in reproductive health devices. Boston Scientific Corporation competes on manufacturing scale for single-use disposable formats.
Sonohysterography catheters are specialized infusion devices, typically 5-7 French in diameter, designed to introduce sterile saline into the uterine cavity during transvaginal ultrasound imaging to enhance endometrial visualization. Single-use catheters command the largest revenue share due to infection control mandates and elimination of reprocessing costs. Fertility assessments represent the fastest-growing application segment as pre-IVF uterine cavity evaluation becomes standard protocol. Direct sales channels dominate in developed markets where manufacturer-clinic relationships determine contract renewals.
FDA 510(k) premarket notification requirements govern catheter clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for Class IIa devices entering European markets. Japan's PMDA maintains distinct biocompatibility testing protocols that add regulatory lead time for foreign manufacturers. Stakeholders must monitor evolving sterilization validation requirements and reimbursement coding changes for office-based sonohysterography procedures.
Market Dynamics
Saline-infusion sonography is displacing diagnostic hysteroscopy in fertility workups, compressing procedure time and anesthesia requirements while pulling catheter procurement toward outpatient settings and away from hospital central supply chains.
Growth Catalysts
- Pre-IVF cavity screening protocols:Fertility centers in the United States now mandate sonohysterography before embryo transfer cycles, institutionalizing catheter consumption into standardized care pathways.
- MDR clinical evidence requirements:Stricter EU Medical Device Regulation standards for Class IIa devices are accelerating manufacturer investment in biocompatibility documentation and post-market surveillance infrastructure.
- Office-based reimbursement stabilization:CPT coding recognition for sonohysterography in Germany and Japan has locked in predictable payment streams, incentivizing clinic-level capital allocation to disposable catheter inventories.
Market Restraints
- Polymer resin cost volatility:Medical-grade polyurethane and polyethylene feedstock prices fluctuate with petrochemical indices, squeezing margins on single-use catheter production.
- Regulatory friction from PMDA:Japan's distinct biocompatibility testing protocols add twelve to eighteen months to foreign manufacturer market entry timelines.
- Reusable hysteroscope substitution:Ambulatory surgical centers with established reprocessing infrastructure resist converting to disposable catheter workflows despite infection control mandates.
Strategic Opportunities
- Underpenetrated fertility markets in India:CDSCO regulatory harmonization efforts and expanding private IVF clinic networks create first-mover positioning for compliant catheter suppliers.
- Telemedicine-integrated remote interpretation:Convergence of high-resolution ultrasound transmission with cloud-based radiology platforms enables sonohysterography deployment in rural and underserved settings.
- Direct-to-clinic distribution channels:Bypassing traditional hospital purchasing committees through specialized reproductive health distributors captures margin and locks in exclusive supply agreements.
Industry Challenges
- ISO 13485 quality management certification:Small and mid-sized manufacturers face eighteen-to-twenty-four-month implementation timelines and significant audit costs to maintain European market access.
- Sterilization validation complexity:Transition from ethylene oxide to alternative sterilization methods requires extensive packaging redesign and residual testing protocols.
- Integration with legacy ultrasound systems:Catheter compatibility across heterogeneous installed bases of transvaginal probe configurations demands ongoing engineering adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sonohysterography Catheters Market |
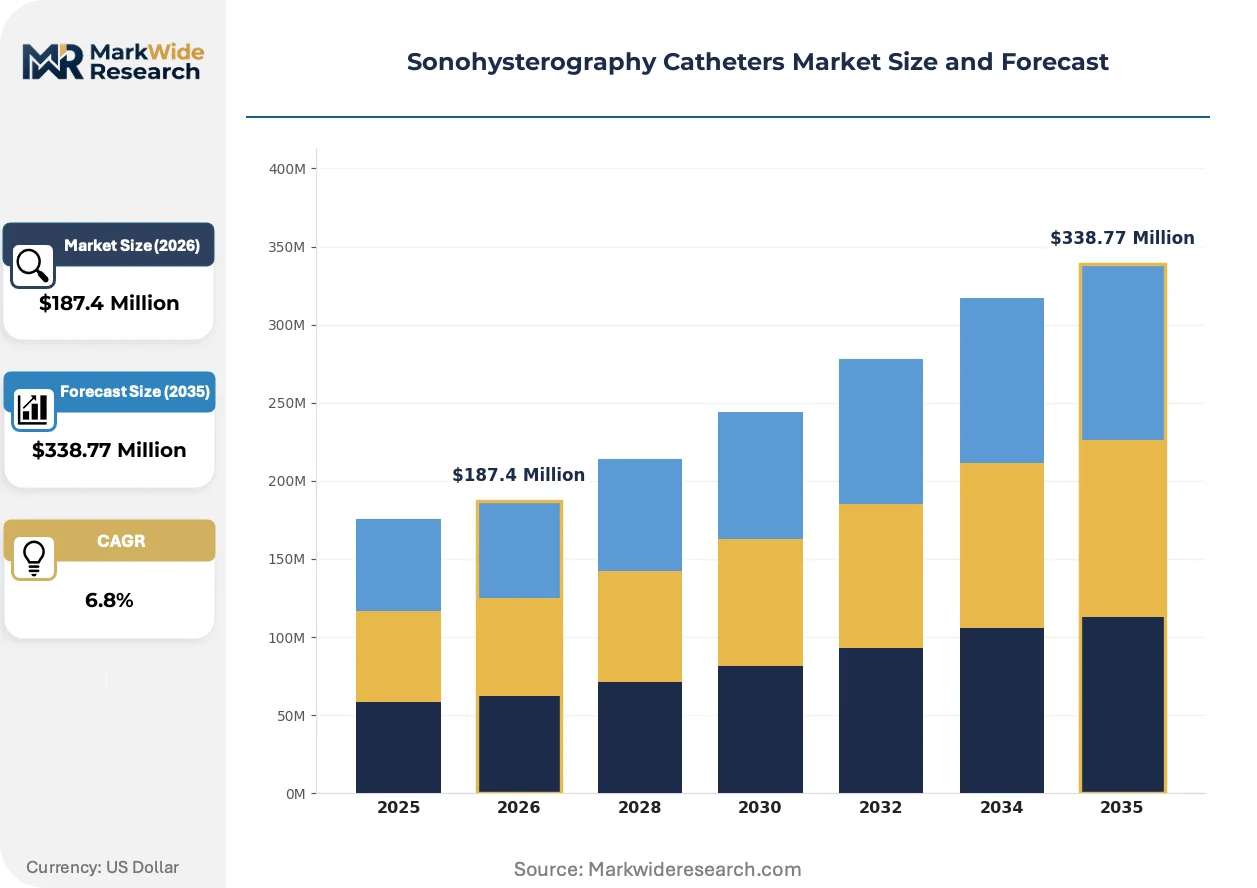
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use Catheters, Multi-use Catheters, Flexible Catheters, Rigid Catheters End User: Hospitals, Clinics, Diagnostic Laboratories, Individual Practitioners Application: Fertility Assessments, Abnormal Bleeding Diagnosis, Uterine Anomaly Evaluation, Intrauterine Procedure Assistance Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesale Suppliers |
| Companies Covered | C. R. Bard, Thomas Medical, Rocket Medical, Cook Group, CooperSurgical, Medtronic, Boston Scientific Corporation, Teleflex Incorporated, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sonohysterography Catheters Market Evolving Landscape
Catheter design and distribution models are fragmenting along fertility clinic versus hospital lines, with manufacturers racing to capture the procedural shift toward office-based diagnostics.
Balloon-tipped sonohysterography catheters is bifurcating the market between premium sealed-system designs and basic open-channel alternatives. Fertility specialists in the United States and Germany are adopting balloon systems at accelerated rates for controlled saline retention and reduced operator dependence. This technology is compressing training curves while creating tiered pricing structures that separate high-throughput IVF centers from lower-volume general gynecology practices.
EU MDR post-market surveillance requirements are forcing manufacturers to rebuild clinical evidence portfolios for legacy catheter designs. The regulation mandates systematic literature reviews and periodic safety update reports that many mid-sized suppliers lack internal capabilities to execute. Class IIa device re-certification timelines are extending, with European notified bodies prioritizing submissions from manufacturers with established reproductive health specialization.
Buying committees at fertility clinic chains are consolidating vendor relationships into multi-year sole-source agreements. CooperSurgical and Cook Group have captured this shift through dedicated reproductive health sales forces that embed directly into clinic workflow planning. The United States exhibits the most pronounced concentration, where large IVF network purchasing decisions now determine regional market share allocation.
Sonohysterography Catheters Market Segmentation
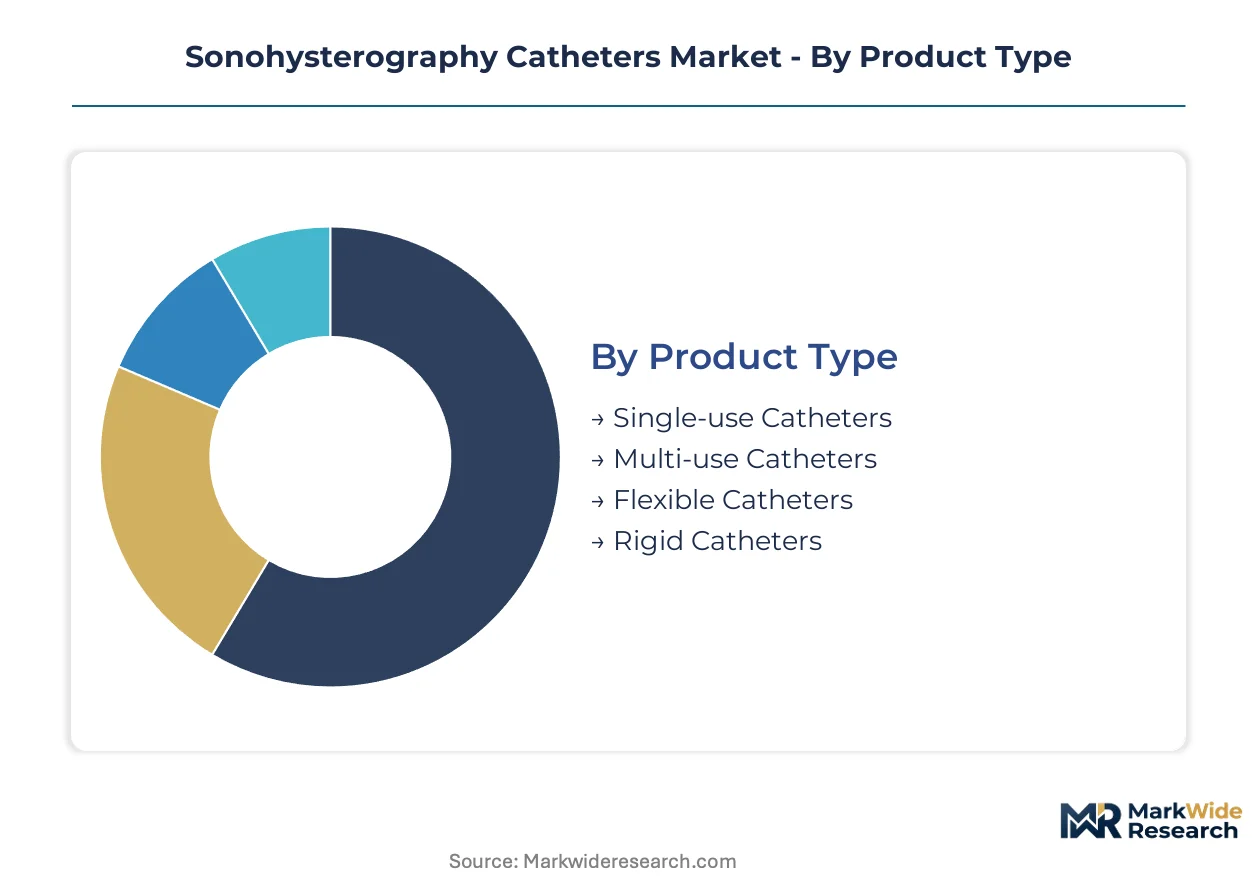
Sonohysterography catheter procurement patterns fragment sharply across product formats and clinical settings. Margin capture depends on matching catheter specifications to procedure volume, reimbursement environment, and infection control mandates at specific points of care.
Product Type:
Premium margin pools concentrate in sealed-system designs that reduce operator dependence and procedure time.
- Single-use Catheters:Polyurethane or polyethylene construction in 5-7 French diameters eliminates reprocessing costs and satisfies FDA infection control mandates. Fertility centers in the United States mandate disposable formats for pre-IVF cavity screening, locking in recurring procurement volumes through standardized care pathways.
- Multi-use Catheters:Silicone-based designs withstand repeated sterilization cycles for cost-conscious hospital systems with established reprocessing infrastructure. German university hospitals maintain these formats despite MDR documentation burdens, prioritizing capital efficiency over per-procedure disposability.
- Flexible Catheters:Navigate tortuous cervical anatomy with reduced patient discomfort during office-based procedures.
- Rigid Catheters:Deliver saline under higher pressure for complex uterine cavity evaluations requiring controlled infusion rates.
Single-use catheters hold installed capacity. Flexible catheters are rotating up the share rankings.
End User:
Procurement authority is migrating toward specialized outpatient settings with dedicated reproductive health budgets.
- Hospitals:Central supply committees manage catheter inventories through group purchasing organizations, prioritizing contract breadth over product specialization. Japanese tertiary centers face PMDA-mandated biocompatibility documentation that extends vendor qualification timelines.
- Clinics:Fertility centers and gynecology practices purchase directly from manufacturers, embedding catheter specifications into workflow protocols. United States IVF networks negotiate multi-year sole-source agreements that capture volume discounts and technical support.
- Diagnostic Laboratories:Process outsourced sonohysterography referrals with standardized catheter configurations.
- Individual Practitioners:Source small-batch supplies through medical distributors serving solo and small-group practices.
Clinics are climbing the fastest in procurement volume. Hospitals retain legacy contract structures.
Application:
Reimbursement coding recognition determines which indications sustain premium catheter pricing.
- Fertility Assessments:Pre-IVF uterine cavity evaluation has become mandatory protocol at United States fertility centers, institutionalizing catheter consumption into standardized embryo transfer pathways. CPT coding recognition locks in predictable payment streams.
- Abnormal Bleeding Diagnosis:Saline-infusion sonography displaces diagnostic hysteroscopy for postmenopausal bleeding workups, compressing procedure time and anesthesia requirements.
- Uterine Anomaly Evaluation:Congenital malformation assessment in adolescent and reproductive-age patients.
- Intrauterine Procedure Assistance:Catheter-guided saline distension facilitates polypectomy and biopsy procedures.
Fertility assessments command premium positioning. Abnormal bleeding diagnosis is gaining procedure share.
Distribution Channel:
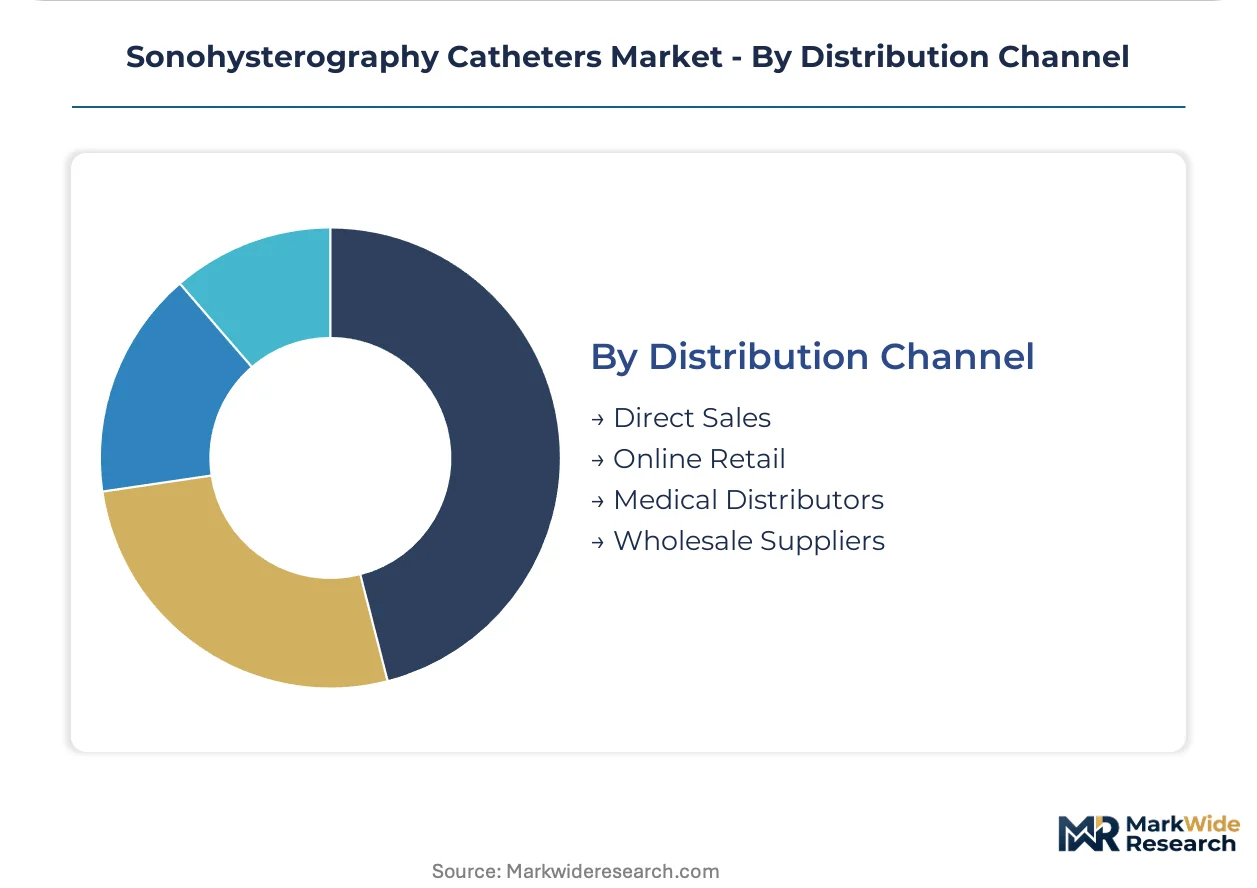
Channel selection determines margin capture and customer lock-in for manufacturers.
- Direct Sales:Manufacturer sales forces embed into fertility clinic workflow planning, capturing multi-year agreements and technical training revenue. CooperSurgical and Cook Group dominate this channel in North America through dedicated reproductive health specialization.
- Online Retail:E-commerce platforms serve individual practitioners and small clinics with immediate availability and transparent pricing.
- Medical Distributors:Specialized reproductive health distributors bypass hospital purchasing committees to reach outpatient settings.
- Wholesale Suppliers:Volume aggregators serve price-sensitive institutional buyers with generic catheter alternatives.
Direct sales holds relationship depth. Medical distributors are expanding geographic coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors catheter import throughput for North American fertility networks, while Rotterdam's medical device distribution hub consolidates EU supply chains for saline-infusion systems.
United States
Fertility clinic chains in California and New York Metro mandate pre-IVF sonohysterography protocols, institutionalizing disposable catheter consumption. FDA 510(k) clearance pathways govern device market entry, with PMA exemptions streamlining single-use format approvals. Greater Boston's reproductive health cluster houses specialized distributors embedding directly into IVF center workflow planning.
Germany
Bavarian university hospitals maintain multi-use catheter formats despite MDR documentation burdens, prioritizing capital efficiency over per-procedure disposability. EU Medical Device Regulation Class IIa standards impose systematic literature review requirements for legacy device re-certification. The Baden-Württemberg medical technology corridor concentrates notified body relationships and post-market surveillance infrastructure.
Japan
Tokyo's tertiary fertility centers drive premium catheter procurement as JIS-compliant balloon-tipped designs displace basic open-channel alternatives. PMDA biocompatibility testing protocols extend foreign manufacturer market entry timelines by twelve to eighteen months. The Osaka-Kobe medical device cluster hosts domestic sterilization validation facilities serving regional catheter suppliers.
India
Maharashtra's expanding private IVF clinic networks create procurement velocity for compliant catheter suppliers navigating CDSCO regulatory harmonization. The country's national pharmaceutical regulator aligns device classification with IMDRF guidelines, compressing approval timelines for established manufacturers. Gujarat's medical device manufacturing zone attracts contract sterilization providers serving export-oriented catheter production.
United Kingdom
London's fertility assessment centers standardize saline-infusion sonography for abnormal bleeding diagnosis, displacing diagnostic hysteroscopy volumes. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while building UKCA infrastructure for future device registrations. The Southeast England reproductive health corridor concentrates clinic chain purchasing committees negotiating multi-year supply agreements.
Sonohysterography Catheters Market Competitive Landscape
Listed leaders compete with private specialists across reproductive health device categories, creating tiered market access dynamics. The vendor base concentrates around dedicated gynecology divisions of diversified medtech conglomerates and standalone fertility-focused suppliers. Three archetypes dominate: integrated hospital supply contractors, direct-to-clinic reproductive health specialists, and disposable catheter scale manufacturers. Competitive moves center on exclusive distribution agreements and MDR compliance infrastructure investment.
Within the reproductive health specialist tier, CooperSurgical and Cook Group exemplify dedicated sales force deployment embedding into clinic workflow planning. Boston Scientific Corporation occupies a position representing diversified medtech scale manufacturing for single-use disposable formats. These three entities anchor the competitive structure through contrasting channel strategies—direct clinic relationships versus hospital supply integration—while navigating identical FDA and EU regulatory frameworks.
| Leading Market Players |
|---|
| C. R. Bard |
| Thomas Medical |
| Rocket Medical |
| Cook Group |
| CooperSurgical |
| Medtronic |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Becton Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Balloon-tipped catheter designs displacing open-channel alternatives simultaneously concentrate manufacturing in Germany and Japan while compressing pricing spreads between premium sealed systems and basic infusion formats. This substitution dynamic reshapes supply geography toward EU MDR-compliant production hubs and forces pricing economics to hinge on biocompatibility documentation rather than raw polymer costs alone.
Pricing Analysis
Volume-discount tiering structures separate high-throughput IVF networks negotiating multi-year sole-source agreements from small gynecology practices purchasing through distributors. Price differentiation rests on FDA 510(k) clearance tier and balloon-seal reliability certification, with German fertility centers paying premiums for MDR Class IIa documentation. Cost compression in standard open-channel formats is intensifying because polymer resin feedstock prices fluctuate with petrochemical indices. Hospital central supply committees exhibit highest price sensitivity, while United States clinic chains prioritize technical support and training over per-unit cost.
Supply Chain Analysis
Germany and Japan anchor precision polymer extrusion for balloon-tipped catheter production, while the United States concentrates sterile packaging and final assembly operations. Medical-grade polyurethane and polyethylene feedstock draws from petrochemical complexes in the US Gulf Coast and Rotterdam, with sterilization validation services clustering in Osaka-Kobe. Single-source vulnerability runs through ethylene oxide sterilization facilities facing regulatory phase-out pressures. Distribution runs through specialized reproductive health distributors embedding directly into fertility clinic workflow planning, bypassing hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where technical training revenue and sterilization validation consulting expand faster than disposable catheter hardware sales. The recurring-revenue layer of MDR post-market surveillance documentation and clinic workflow integration services now determines vendor profitability.
For Market Incumbents: Fortify exclusive supply agreements with United States IVF networks by embedding dedicated field technical specialists into embryo transfer pathway planning. Invest in backward integration into medical-grade polymer compounding to offset feedstock cost volatility squeezing margins on single-use formats. Defend against emerging Indian manufacturers by accelerating CE marking renewals ahead of MDR Class IIa re-certification deadlines.
For New Entrants and Emerging Players: Differentiate on telemedicine-integrated catheter designs enabling remote ultrasound interpretation for rural fertility access. Target Maharashtra's expanding private IVF clinic networks navigating CDSCO regulatory harmonization as the most penetrable geography. Pursue direct-to-clinic distribution partnerships with specialized reproductive health distributors rather than competing through hospital GPO contracts.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors reproductive health specialists with established MDR compliance infrastructure over diversified hospital supply contractors. Long-term viability hinges on capturing clinic-level workflow integration rather than manufacturing scale alone. Monitor PMDA biocompatibility testing protocol changes as the signal indicating foreign manufacturer entry timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class IIa Re-certification | European notified bodies prioritize reproductive health specialists, extending legacy device timelines for mid-sized suppliers. |
| Direct-to-Clinic Distribution Partnership | CooperSurgical and Cook Group capture margin and lock in exclusive agreements through dedicated sales forces. |
| Balloon-Tipped Design Launch | Controlled saline retention reduces operator dependence, creating tiered pricing separating high-throughput IVF centers. |
| Telemedicine Integration Development | Cloud-based radiology platforms enable deployment in rural settings, expanding addressable clinic base. |
| Sterilization Validation Investment | Transition from ethylene oxide to alternative methods requires extensive packaging redesign and residual testing protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body submission databases, and hospital procurement contract records. Interviews with fertility clinic medical directors, biomedical engineers, GPO contracts managers, and reproductive health distributor principals informed demand-side assumptions. Bottom-up catheter consumption estimates triangulated against top-down market sizing derived from CMS Medicare procedure coding data and Japanese Ministry of Health reimbursement schedules.
Segmentation dimensions modeled include catheter format, end-user setting, application indication, and distribution channel across the projection horizon. CAGRs were derived from procedure volume trajectories, reimbursement coding stability, and regulatory approval timeline assumptions. Forecast inputs incorporated fertility center expansion rates in underpenetrated markets and polymer feedstock price elasticity effects on manufacturer margin structures.
Decision-makers should treat outputs as directional under assumptions of stable CPT coding recognition for office-based sonohysterography; material deviation in reimbursement policy would warrant model refresh. Specific risk factors include PMDA protocol harmonization delays, ethylene oxide sterilization facility closures, and IVF clinic network consolidation altering procurement authority concentration. Recalibration cycles align with material shifts in regulatory clearance timelines and fertility center capital expenditure planning seasons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Wheelchair Market
Medical Devices
Implantable Drug Delivery Devices Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Airway Management Devices Market
Medical Devices
Global Surgical Visualization Products Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Medical Smart Wearable Devices Market