
 Zygomatic and Pterygoid Implants Market | 2026-2036
Zygomatic and Pterygoid Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Zygomatic and Pterygoid Implants Market Outlook
Academic medical centers and specialized oral surgery institutes are rotating toward zygomatic and pterygoid protocols as first-line alternatives to bone grafting for edentulous maxilla reconstruction. Straumann Holding AG leverages its Swiss precision manufacturing heritage to sustain premium positioning in titanium implant surfaces. Nobel Biocare anchors European clinical training networks that drive protocol standardization across teaching hospitals. Zimmer Biomet Holding Inc. competes through its orthopedic-to-dental technology transfer capabilities in porous titanium architectures.
Zygomatic and pterygoid implants are extra-maxillary titanium fixtures, typically 30–55 mm in length with machined or moderately rough surface topographies, designed to engage the zygomatic bone or pterygoid plate when native maxillary bone is insufficient for conventional endosseous support. Their primary purpose is to enable immediate functional loading of fixed prostheses without staged bone augmentation. Titanium material formulations dominate the value pool due to established osseointegration evidence and favorable fatigue resistance profiles, while zirconia variants occupy a narrower aesthetic-driven niche for thin gingival biotypes. CAD/CAM technology segments are expanding fastest as surgical guide accuracy reduces pterygoid placement morbidity, though traditional surgery retains volume leadership in cost-sensitive dental clinics.
FDA 510(k) clearance pathways and EU MDR Class III device requirements impose substantial clinical evidence burdens on manufacturers seeking market access, effectively filtering smaller entrants from commercialization. ISO 13485 quality management systems and ASTM F136 titanium alloy specifications form the baseline compliance architecture for global distribution. Stakeholders must monitor evolving reimbursement codes for zygomatic procedures across national health systems and private payer networks.
Market Dynamics
ISO 5832 titanium traceability mandates and EU MDR Class III device requirements are compressing manufacturer margins while elevating entry barriers, forcing consolidation among implant producers who lack capital reserves for clinical evidence generation.
Growth Catalysts
- Edentulous Maxilla Protocol Adoption:Oral and maxillofacial surgical centers in the United States are rotating zygomatic and pterygoid implants toward first-line status, displacing staged bone grafting for immediate functional loading cases.
- FDA 510(k) Pathway Refinements:Streamlined predicate device recognition for titanium alloy formulations is accelerating clearance timelines for machined surface topography variants.
- CAD/CAM Surgical Guide Penetration:Digital planning workflows are reducing pterygoid placement morbidity, expanding addressable patient pools to include thin gingival biotype candidates previously excluded from extra-maxillary fixation.
Market Restraints
- Titanium Grade 4 Feedstock Concentration:ASTM F136 alloy supply chains cluster among a limited set of European and Japanese metallurgical processors, exposing manufacturers to input price volatility.
- EU MDR Clinical Evidence Burden:Class III device requirements impose multi-year post-market surveillance obligations that filter smaller entrants from commercialization.
- Zirconia Substitution Ceiling:Aesthetic-driven niches for ceramic alternatives face fatigue resistance limitations that cap penetration in load-bearing posterior applications.
Strategic Opportunities
- Brazilian Private Dental Clinic Expansion:São Paulo and Rio de Janeiro surgical centers are building dedicated zygomatic protocol units to capture outbound medical tourism from neighboring Latin American markets.
- ISO 13485 Certification Arbitrage:Swiss precision manufacturing heritage confers quality management credibility that commands premium positioning in German and Austrian teaching hospital procurement.
- Immediate Loading Protocol Standardization:Convergence of surface roughness optimization with digital impression technology is compressing chair time requirements for full-arch rehabilitation.
Industry Challenges
- Pterygoid Anatomy Surgical Skill Gap:Pterygomaxillary fissure navigation requires specialized training that outpaces current oral surgery fellowship curriculum coverage.
- Reimbursement Code Fragmentation:National health systems and private payer networks maintain inconsistent zygomatic procedure coding that complicates patient access financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zygomatic and Pterygoid Implants Market |
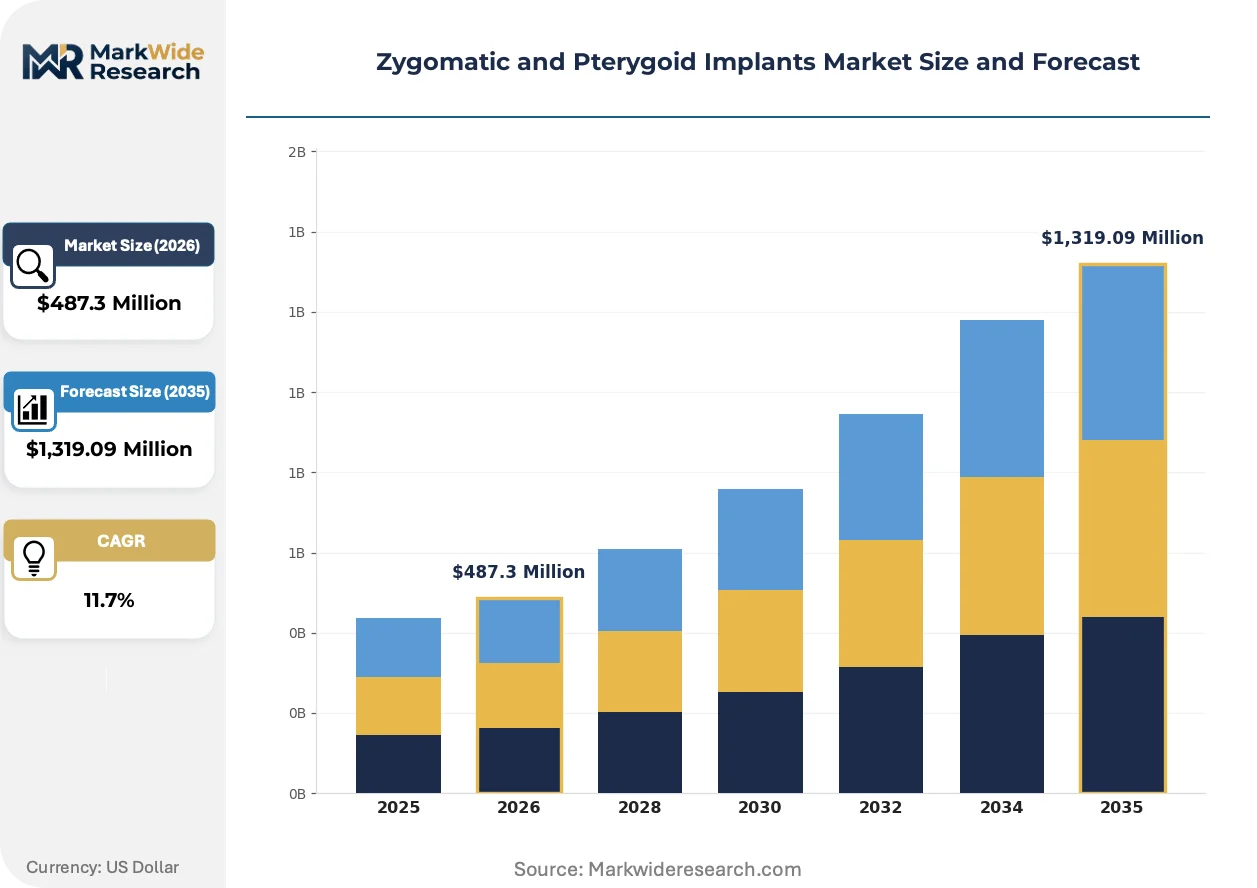
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zygomatic Implants, Pterygoid Implants, Mini Implants, Conventional Implants End User: Dental Clinics, Hospitals, Research Laboratories, private Practices Material: Titanium, Zirconia, Stainless Steel, Polymer Technology: 3D Printing, CAD/CAM, Traditional Surgery, Digital Impressions |
| Companies Covered | Southern Implants, S.I.N. Implant System, Straumann Holding AG, BioHorizons Implant Systems Inc., IDC Implant & Dental Co., Nobel Biocare, Noris Medical, MIS Implants Technologies Ltd., Zimmer Biomet Holding Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zygomatic and Pterygoid Implants Market Strategic Shifts
Digital surgical planning ecosystems are compressing treatment timelines while surface engineering advances expand immediate loading candidacy, reshaping how extra-maxillary fixtures integrate into comprehensive rehabilitation protocols.
Patient-specific titanium implant geometries are miniaturizing through additive manufacturing adoption, enabling anatomically contoured fixtures that engage zygomatic bone with reduced palatal intrusion. German maxillofacial institutes are deploying these geometries for severe atrophy cases previously requiring bilateral zygomatic placement. The technology is miniaturizing surgical invasiveness while preserving prosthodontic function.
EU MDR post-market surveillance requirements are tightening clinical evidence obligations for titanium surface modifications, compelling manufacturers to maintain prospective implant registries. Swiss and German notified bodies are applying heightened scrutiny to moderately rough topography claims. European teaching hospitals are responding by centralizing procedure data capture to satisfy periodic safety update report mandates.
After-sales technical support unbundling is fragmenting traditional distributor value pools, with specialized oral surgery institutes in the United States contracting directly with manufacturers for surgical training and complication management. Independent dental service organizations are displacing full-line distributors in major metropolitan clusters. This pattern concentrates most visibly in California and Texas implantology corridors where group practice consolidation accelerates procurement centralization.
Zygomatic and Pterygoid Implants Market Segmentation
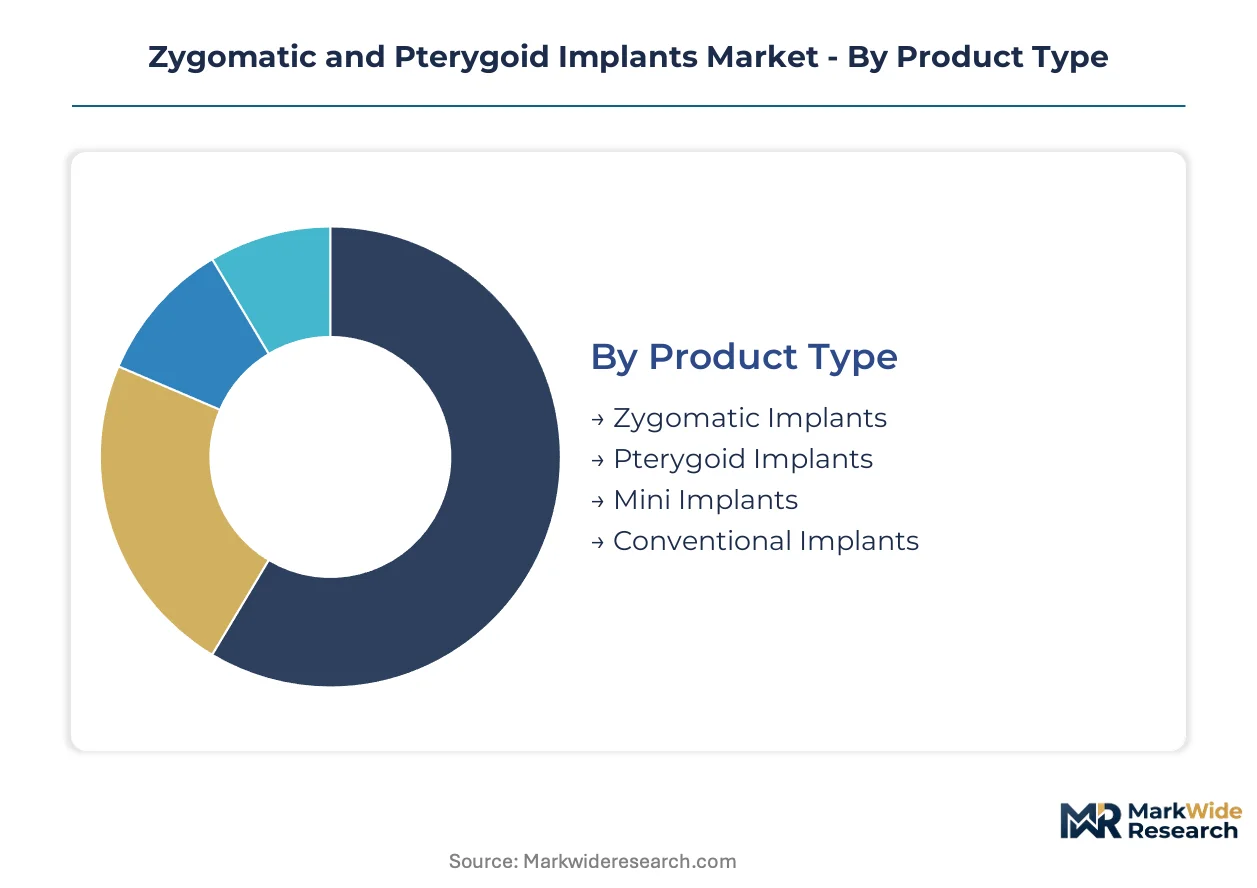
Segmentation in the zygomatic and pterygoid implants market reveals how clinical specialization, material science advances, and digital workflow integration create distinct procurement patterns across surgical centers. Understanding these divisions exposes where premium pricing power concentrates versus where cost competition dominates.
Product Type:
Zygomatic and pterygoid implant demand spreads unevenly across domestic surgical centers and export-led manufacturing hubs, with certain fixture geometries commanding international premium positioning while others serve localized cost-sensitive markets.
- Zygomatic Implants:These 30–55 mm titanium fixtures engage the zygomatic bone to bypass maxillary atrophy, with machined or moderately rough surfaces enabling immediate loading protocols. Demand concentrates in United States academic medical centers and German maxillofacial institutes where severe atrophy cases drive bilateral placement protocols. FDA 510(k) predicate device recognition for titanium alloy formulations sustains premium positioning against grafting alternatives.
- Pterygoid Implants:Shorter extra-maxillary fixtures anchor in the pterygoid plate, requiring navigational precision through the pterygomaxillary fissure. Brazilian private clinics in São Paulo and Rio de Janeiro are building dedicated protocol units to capture Latin American medical tourism, though surgical skill gaps in fellowship training constrain expansion.
- Mini Implants:Reduced-diameter temporary anchorage devices serve orthodontic and provisional prosthodontic applications in South Korean and Japanese dental clinics.
- Conventional Implants:Standard endosseous fixtures retain volume leadership in cost-sensitive Indian and Mexican dental service organizations where bone grafting remains economically viable.
Zygomatic implants command the established base. The steepest expansion runs through pterygoid protocols as digital surgical planning reduces placement morbidity.
End User:
Procurement patterns across end-user categories track reimbursement code availability and surgical complexity authorization tiers, with institutional purchasing power reshaping distributor relationships.
- Dental Clinics:Independent and group practice settings in California and Texas implantology corridors drive CAD/CAM surgical guide adoption, with dental service organizations centralizing procurement to displace full-line distributors. Immediate loading protocol standardization compresses chair time requirements for full-arch rehabilitation.
- Hospitals:Academic medical centers and oral and maxillofacial surgical institutes in Germany, Austria, and Switzerland rotate toward extra-maxillary protocols as first-line alternatives to staged bone grafting. EU MDR Class III device requirements filter purchasing toward ISO 13485-certified manufacturers with established clinical evidence portfolios.
- Research Laboratories:Maxillofacial surgery training programs in Swedish and Dutch universities validate patient-specific geometries and surface modifications under post-market surveillance mandates.
- Private Practices:Solo practitioner models in Spain and Italy retain traditional surgery volumes where digital infrastructure investment remains prohibitive.
Hospitals anchor premium technology adoption. Private practices represent the most price-elastic demand pool.
Material:
Material selection stratifies across load-bearing requirements and aesthetic indications, with metallurgical supply chain concentration creating input cost volatility that propagates through finished device pricing.
- Titanium:ASTM F136 titanium alloy formulations dominate the value pool due to established osseointegration evidence and favorable fatigue resistance profiles. Grade 4 feedstock supply chains cluster among European and Japanese metallurgical processors, exposing manufacturers to price volatility.
- Zirconia:Ceramic alternatives occupy aesthetic-driven niches for thin gingival biotypes in French and Italian anterior rehabilitation cases, though fatigue resistance limitations cap penetration in posterior load-bearing applications.
- Stainless Steel:Cost-sensitive provisional fixtures serve temporary anchorage in Turkish and Polish dental clinics.
- Polymer:Resorbable and permanent polymer formulations remain experimental in Australian and Canadian research settings.
Titanium anchors the commercial base. Zirconia is gaining share fastest in anterior aesthetic segments.
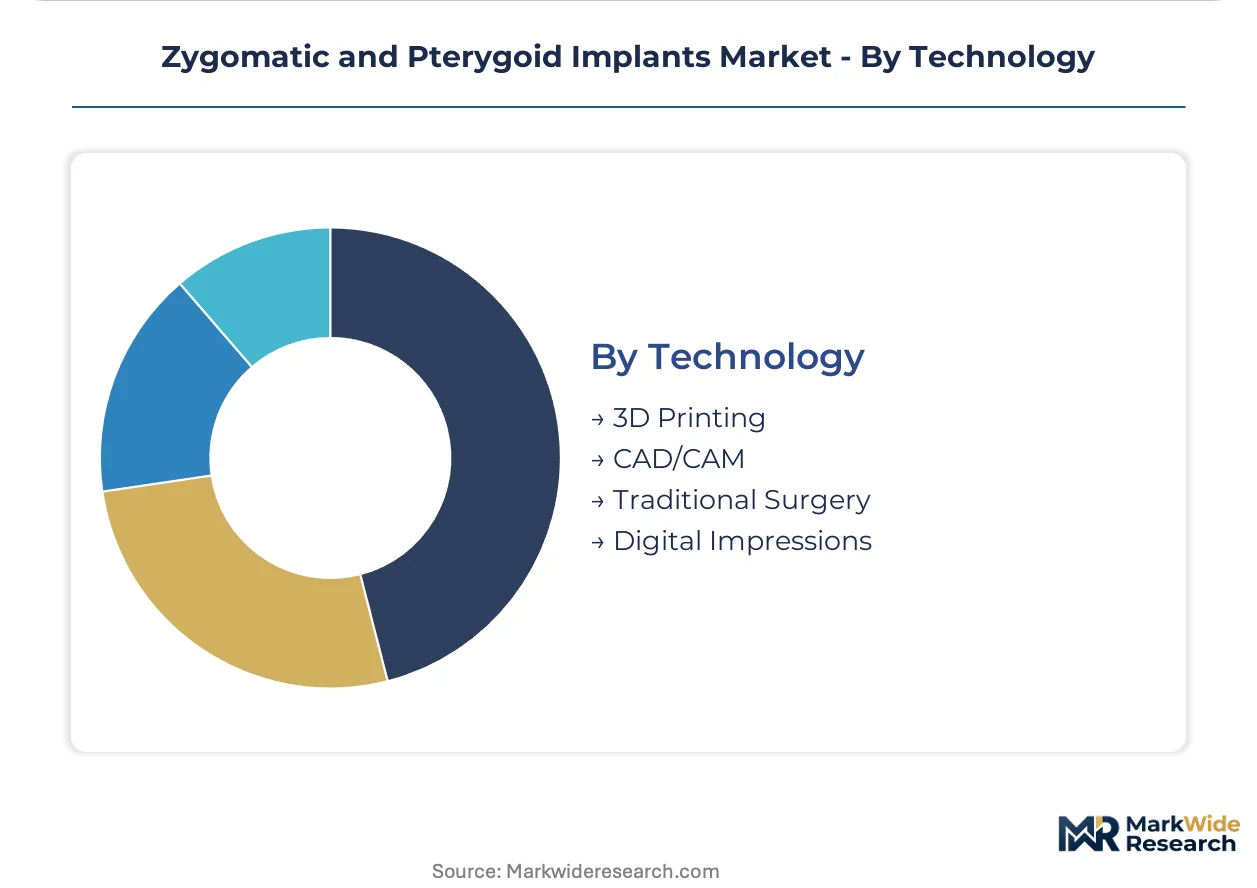
Technology:
Technology segmentation reveals a bifurcation between digital workflow investments that reduce surgical morbidity and traditional methods that retain cost advantages in reimbursement-constrained environments.
- CAD/CAM:Computer-aided design and manufacturing workflows are expanding fastest as surgical guide accuracy reduces pterygoid placement morbidity and expands addressable patient pools to thin gingival biotype candidates. German maxillofacial institutes deploy these systems for severe atrophy cases.
- 3D Printing:Additive manufacturing enables patient-specific titanium implant geometries that miniaturize surgical invasiveness while preserving prosthodontic function. Swiss precision manufacturing heritage commands premium positioning in teaching hospital procurement.
- Digital Impressions:Intraoral scanning integration with implant planning software streamlines full-arch rehabilitation in United Kingdom dental service organizations.
- Traditional Surgery:Freehand placement protocols retain volume leadership in Brazilian and Mexican cost-sensitive clinics where digital infrastructure investment lags.
Traditional surgery commands the established base. CAD/CAM systems are climbing the fastest as EU MDR clinical evidence burdens favor manufacturers with digital validation capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized oral surgery institutes concentrate procurement authority for zygomatic and pterygoid implants in the United States, Germany, and Brazil, where advanced dental rehabilitation infrastructure supports complex implantology protocols.
United States
Oral and maxillofacial surgical centers in California and Texas implantology corridors are rotating toward extra-maxillary protocols as first-line alternatives to staged bone grafting. FDA 510(k) clearance pathways for titanium alloy formulations sustain premium positioning against grafting alternatives. Dental service organizations in metropolitan clusters centralize procurement to displace full-line distributors.
Germany
German maxillofacial institutes deploy patient-specific titanium implant geometries for severe atrophy cases previously requiring bilateral zygomatic placement. EU MDR Class III device requirements filter purchasing toward ISO 13485-certified manufacturers with established clinical evidence portfolios. Bavarian teaching hospitals anchor European clinical training networks that drive protocol standardization.
Brazil
Private dental clinics in São Paulo and Rio de Janeiro are building dedicated zygomatic protocol units to capture outbound medical tourism from neighboring Latin American markets. ANVISA regulatory frameworks impose clinical evidence requirements that favor established international suppliers. Surgical centers concentrate in southeastern metropolitan corridors where digital infrastructure investment accelerates.
Switzerland
Swiss precision manufacturing heritage confers quality management credibility that commands premium positioning in German and Austrian teaching hospital procurement. Swissmedic oversight maintains stringent post-market surveillance obligations for titanium surface modifications. Basel and Zurich clusters anchor European notified body interactions for moderately rough topography claims.
Japan
ASTM F136 titanium alloy feedstock supply chains cluster among Japanese metallurgical processors, exposing manufacturers to input price volatility. PMDA regulatory pathways require substantial clinical documentation for immediate loading protocol recognition. Tokyo and Osaka surgical centers represent emerging demand pools for CAD/CAM surgical guide adoption.
Zygomatic and Pterygoid Implants Market Competitive Environment
Player mix skews toward precision manufacturing specialists with orthopedic-to-dental technology transfer capabilities. Market structure exhibits tiered consolidation around Swiss and German precision engineering heritage, with mid-scale specialists competing on ISO 13485 certification arbitrage. Two strategic archetypes dominate: vertically integrated metallurgical processors controlling titanium feedstock quality, and digital workflow integrators bundling surgical planning software with fixture supply. Competitive moves concentrate on M&A activity targeting CAD/CAM surgical guide developers, and strategic partnerships with academic medical centers for clinical evidence generation.
Among Swiss- and German-based precision manufacturers, Straumann Holding AG and Nobel Biocare exemplify the premium-tier archetype anchored in European clinical training networks. Zimmer Biomet Holding Inc. represents the orthopedic-to-dental technology transfer model, leveraging porous titanium architectures developed in reconstructive surgery applications. Southern Implants occupies a position within the specialized extra-maxillary fixture segment, serving severe atrophy protocols where conventional endosseous support fails.
| Leading Market Players |
|---|
| Southern Implants |
| S.I.N. Implant System |
| Straumann Holding AG |
| BioHorizons Implant Systems Inc. |
| IDC Implant & Dental Co. |
| Nobel Biocare |
| Noris Medical |
| MIS Implants Technologies Ltd. |
| Zimmer Biomet Holding Inc. |
| Others |
Value Chain & Pricing Dynamics
EU MDR Class III device requirements and ISO 13485 certification standards gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified manufacturers while enabling Swiss and German precision engineering heritage to command premium positioning in teaching hospital procurement.
Pricing Analysis
CAD/CAM surgical guide systems carry 40-60% premiums over traditional freehand protocols, while machined surface topography variants price 15-25% below moderately rough alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified Swiss manufacturers from mid-tier European specialists and cost-sensitive Asian producers. Price differentiation centers on surface engineering sophistication and immediate loading protocol validation. Cost compression in economy tiers intensifies as Brazilian and Mexican clinics consolidate procurement through dental service organizations. Group practice buyers in California and Texas implantology corridors exhibit lowest price sensitivity due to reimbursement code advantages, while solo practitioners in Spain and Italy remain most elastic.
Supply Chain Analysis
ASTM F136 titanium alloy feedstock concentration among Japanese and European metallurgical processors creates single-source vulnerability for Grade 4 material traceability. Manufacturing draws from Swiss precision machining clusters, German maxillofacial institute partnerships, and emerging Brazilian assembly operations. Raw material dependencies center on titanium sponge from Ukrainian and Russian sources, vacuum arc remelting capacity in Japan, and surface treatment chemicals from German specialty chemical producers. Supply chain risk propagates through EU MDR post-market surveillance obligations that extend inventory holding periods. Distribution runs through specialized oral surgery institutes contracting directly with manufacturers, displacing full-line distributors in United States metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The zygomatic and pterygoid implants market is recovering from pandemic-deferred elective surgical volumes, with cyclical momentum building through backlog clearance in United States academic medical centers and German maxillofacial institutes.
For Market Incumbents: Fortify ISO 13485-certified manufacturing capacity in Swiss and German clusters to defend against mid-tier European specialists arbitraging quality management credibility. Deepen backward integration into ASTM F136 titanium alloy feedstock to mitigate Japanese and European metallurgical processor concentration risk. Anchor hospital system partnerships in Bavarian and Austrian teaching networks to secure post-market surveillance data flows required by EU MDR Class III obligations.
For New Entrants and Emerging Players: After-sales technical support unbundling presents white-space opportunity where Straumann and Nobel Biocare maintain bundled distributor relationships. Target pterygoid protocol training services for Brazilian private clinics in São Paulo and Rio de Janeiro, where surgical skill gaps outpace fellowship curriculum coverage. Pursue CAD/CAM surgical guide software partnerships as the most penetrable entry vector, leveraging digital workflow integration to bypass titanium metallurgy barriers.
For Investors and Strategic Acquirers: EU MDR Class III device requirements reshape the acquisition landscape toward clinical evidence-rich targets with established implant registries. Long-term viability favors vertically integrated precision manufacturers with orthopedic-to-dental technology transfer capabilities over pure-play dental specialists. Watch FDA 510(k) predicate device recognition patterns for titanium surface modifications as the inflection signal indicating clearance timeline compression for digital-native entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Surgical Guide Development | Reduces pterygoid placement morbidity and expands addressable patient pools in German institutes. |
| ISO 13485 Certification Investment | Enables premium positioning in Swiss and Austrian teaching hospital procurement frameworks. |
| Immediate Loading Protocol Standardization | Compresses chair time requirements for full-arch rehabilitation in United States dental service organizations. |
| Patient-Specific Implant Geometry Manufacturing | Miniaturizes surgical invasiveness through additive manufacturing adoption in severe atrophy cases. |
| Post-Market Surveillance Registry Establishment | Satisfies EU MDR Class III periodic safety update report mandates for moderately rough topography claims. |
Study Parameters
A spread of perspectives from oral and maxillofacial surgeons, hospital purchasing committee members, biomedical engineers at implant manufacturers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and ISO certification registries. Bottom-up demand modeling from procedure volumes and top-down market sizing from manufacturer revenue disclosures were triangulated to establish consistency bounds.
Segmentation dimensions modeled include implant type, end-user category, material formulation, and technology adoption tier across the analysis window. CAGRs were derived from growth rate convergence analysis applied to historical procedure data and forward-looking reimbursement code expansion patterns. Analytical framework incorporated surface engineering innovation curves, digital workflow penetration rates, and regulatory approval timeline distributions specific to extra-maxillary fixture categories.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR Class III frameworks; material policy shifts would require re-modeling. Specific risk factors include titanium feedstock price volatility from geopolitical disruption, reimbursement code fragmentation across national health systems, and pterygoid protocol training capacity constraints. Practitioners should keep alternative scenarios live as CAD/CAM surgical guide adoption curves and immediate loading protocol validation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Global Otoscopes Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Stool Management Systems Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Embolization Plugs Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Lacrimal Devices Market