
 IOL Delivery Systems Market | 2026-2036
IOL Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
IOL Delivery Systems Market Foresight
The EU Medical Device Regulation is shifting the cost-of-entry calculus for IOL delivery system manufacturers seeking European market access. Johnson & Johnson leverages its diversified ophthalmology portfolio to sustain R&D intensity across mechanized injector platforms. Alcon Laboratories anchors North American distribution through direct hospital and ambulatory surgery center channels. Hoya Surgical Optics competes in Asia-Pacific markets with specialized pre-loaded injector designs optimized for premium intraocular lenses.
IOL delivery systems are precision-engineered devices designed to insert foldable intraocular lenses through sub-3mm corneal incisions using controlled plunger mechanisms or gas-assisted injection, ensuring lens integrity during cataract and refractive surgical procedures. Pre-loaded injectors dominate commercial volume by eliminating manual lens loading errors and reducing operative time, while smart injector technology represents the fastest-growing segment as sensor-enabled delivery feedback improves surgical outcomes. Ambulatory surgery centers now constitute the highest-margin end-user channel as outpatient cataract migration accelerates procedure throughput requirements.
The FDA 510(k) pathway and EU MDR conformity assessment create divergent compliance burdens that reshape product development priorities for manufacturers serving both markets. ISO 13485 quality management systems and IEC 60601 electrical safety standards further constrain design choices for smart injector platforms with integrated electronic components. Stakeholders must monitor evolving reimbursement thresholds for premium IOL categories that directly influence delivery system upgrade cycles and capital equipment purchasing decisions.
Market Dynamics
Ambulatory surgery centers are compressing procedure turnaround times, forcing injector manufacturers to prioritize pre-loaded systems that eliminate intraoperative assembly steps and reduce nursing labor per case.
Growth Catalysts
- EU MDR pre-market certification:Stricter conformity assessment timelines are accelerating consolidation among manufacturers with established quality management systems, favoring incumbents with ISO 13485 infrastructure.
- Pre-loaded injector platforms:Elimination of manual lens loading errors in high-throughput surgical environments is driving capital replacement cycles at freestanding ophthalmic surgery facilities.
- Japan's aging surgical population:Cataract procedural volumes in Japanese tertiary centers are sustaining demand for precision-engineered delivery mechanisms compatible with premium toric and multifocal lenses.
Market Restraints
- Silicone polymer feedstock volatility:Fluctuating prices for medical-grade silicone elastomers used in plunger seals and cartridge housings compress gross margins on disposable injector components.
- Supply concentration in German precision molding:Reliance on Bavarian and Baden-Württemberg-based contract manufacturers for high-tolerance injection-molded parts creates geographic vulnerability to energy cost shocks.
- FDA 510(k) predicate device limitations:Narrowing availability of acceptable predicate devices for novel smart injector submissions extends regulatory timelines and elevates clinical data requirements.
Strategic Opportunities
- India's tier-2 city surgical networks:Underpenetrated cataract service lines in secondary metropolitan markets present whitespace for pre-loaded injector distribution partnerships with regional hospital chains.
- Sensor-enabled delivery feedback:Convergence of micro-force sensing technology with disposable injector platforms enables real-time insertion pressure monitoring, differentiating premium product tiers.
- Direct-to-ambulatory center procurement:Bypassing traditional distributor markups through manufacturer-managed inventory programs at high-volume surgery centers captures margin and locks in volume commitments.
Industry Challenges
- Biocompatibility testing bottlenecks:Extended ISO 10993 cytotoxicity and sensitization study timelines for novel polymer formulations delay product launches by 12-18 months.
- Legacy hospital IT integration:Smart injector platforms with embedded electronics face interoperability friction with proprietary electronic medical record systems, complicating adoption at integrated delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IOL Delivery Systems Market |
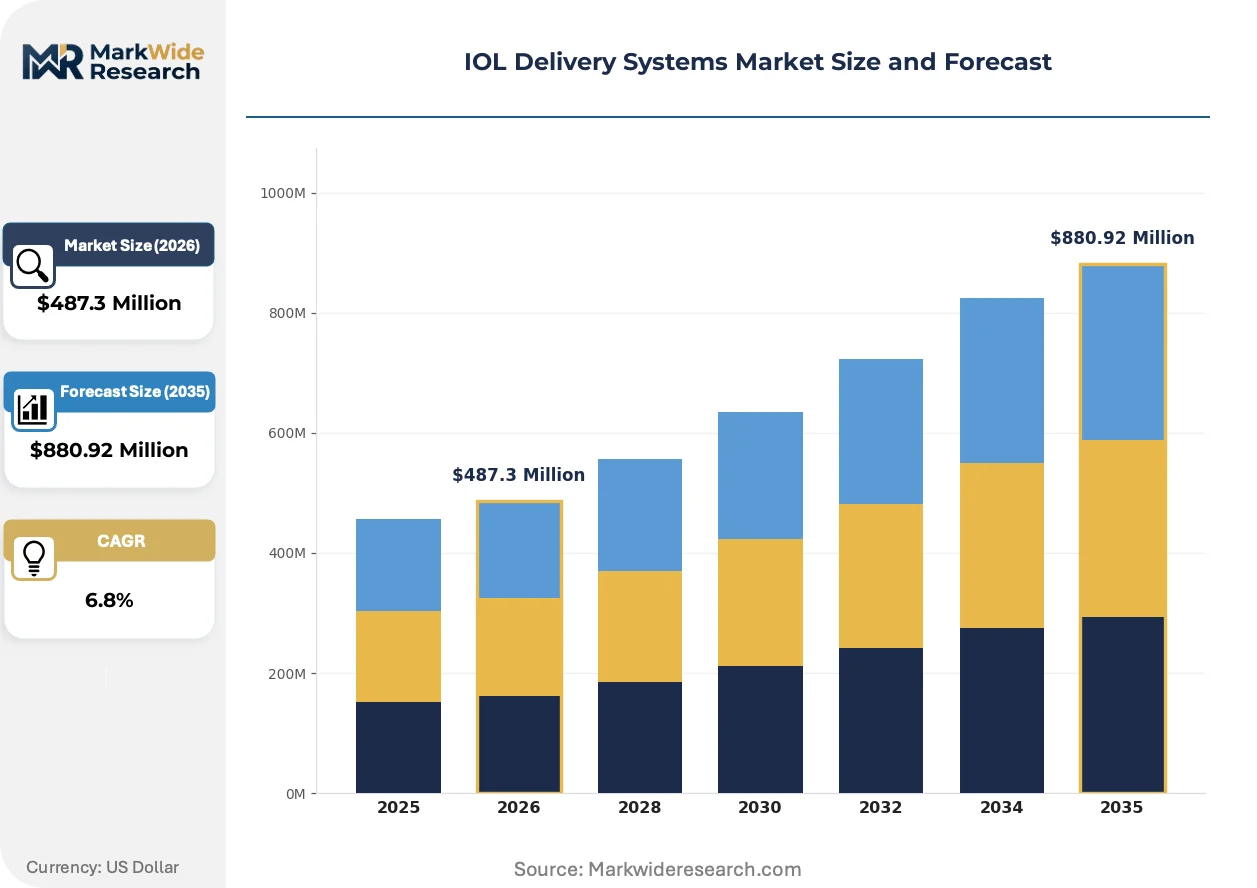
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-loaded Injectors, Disposable Systems, Hand-held Devices, Surgical Instruments Application: cataract Surgery, Refractive Surgery, Therapeutic Procedures, Eye Trauma End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgery Centers, Research Institutions Technology: Mechanized Systems, Manual Delivery, Smart Injectors, Fiber Optic Devices |
| Companies Covered | Hoya Surgical Optics, AST Products, Johnson & Johnson, Hanita Lenses Ltd., Medline Industries, Alcon Laboratories, Rayner Surgical Group, Medicel AG, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IOL Delivery Systems Market Shifts & Advancements
Device intelligence and disposable-to-reusable hybrid architectures are redefining capital equipment economics in ophthalmic surgery suites, compressing the traditional trade-off between per-case cost and surgical control precision.
Gas-assisted injection technology is rewriting performance benchmarks for foldable intraocular lens insertion. This mechanism uses controlled inert gas pressure rather than mechanical plungers to advance lenses through sub-2.2mm incisions. High-volume ambulatory surgery centers in the United States are standardizing on these platforms to minimize endothelial cell trauma. The technology is compressing the performance gap between premium and standard injector categories, forcing price repositioning across product tiers.
EU MDR technical documentation requirements are reshaping product development resource allocation. Manufacturers must now maintain clinical evaluation reports and post-market surveillance systems that exceed prior Medical Device Directive obligations. Smart injector platforms with integrated electronics face disproportionate scrutiny under IEC 60601 electrical safety assessments, diverting engineering talent from feature innovation toward compliance documentation.
Surgeon preference for single-use disposability is displacing reusable metal injector handpieces in North American and Western European markets. This pattern concentrates purchasing authority at materials management departments rather than individual surgeons, standardizing device selection across health system networks. The shift is most visible in United States integrated delivery networks where centralized procurement contracts favor disposable platforms with predictable per-case costing.
IOL Delivery Systems Market Segmentation
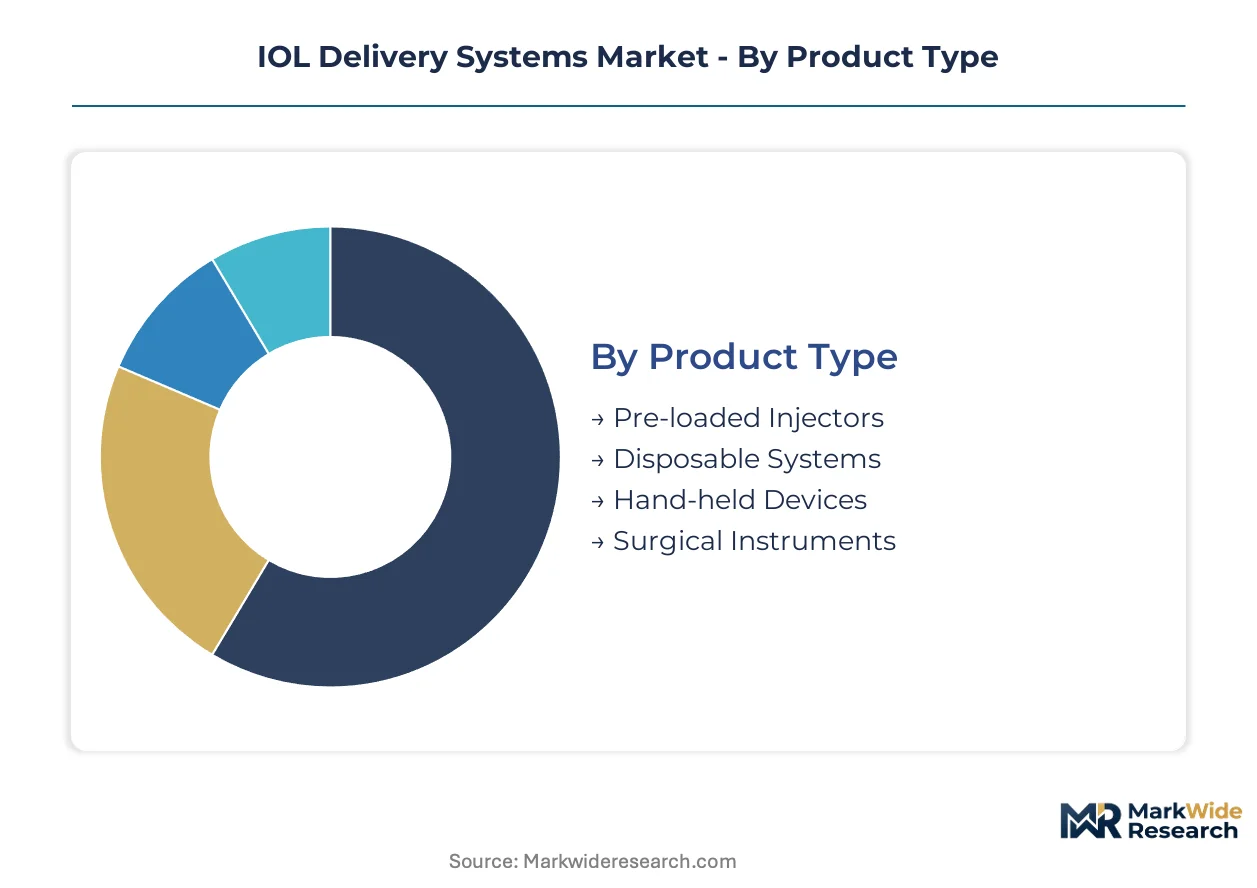
IOL delivery systems fragment across four intersecting dimensions that determine procurement authority, regulatory pathway, and pricing power. Product architecture and end-user channel together dictate whether purchasing decisions sit with surgeons, materials managers, or health system executives.
Product Type:
Customization intensity spans from fully pre-configured disposable cartridges to modular reusable handpieces requiring intraoperative assembly.
- Pre-loaded Injectors:Factory-sealed cartridges integrate the IOL with lubricated delivery channels, eliminating manual loading errors. United States ambulatory surgery centers are standardizing on these platforms to compress nursing labor per case and accelerate room turnover.
- Disposable Systems:Single-use injector assemblies with integrated plungers and nozzles dominate European procurement contracts where sterilization infrastructure costs deter reusable alternatives. German hospital networks favor these for predictable per-procedure costing under DRG reimbursement.
- Hand-held Devices:Reusable titanium or stainless steel injector bodies with replaceable cartridges persist in Japanese tertiary centers with established central sterilization departments.
- Surgical Instruments:Forceps-style lens insertion tools without cartridge mechanisms retain niche use in complex trauma cases requiring manual lens manipulation.
Leading the category by volume: Pre-loaded Injectors. Expanding most quickly: Disposable Systems.
Application:
Procedure complexity and reimbursement tier separate high-value therapeutic interventions from high-volume standard-of-care surgeries.
- Cataract Surgery:Phacoemulsification with IOL implantation constitutes the procedural backbone, driving injector demand through Medicare and commercial reimbursement in the United States. Aging demographics in Germany and Japan sustain procedural volume growth.
- Refractive Surgery:Clear lens exchange and phakic IOL procedures for myopia correction command premium injector pricing due to precision requirements for toric and multifocal lenses.
- Therapeutic Procedures:IOL exchange for dislocated lenses or uveitis management requires specialized injectors with enhanced grasping mechanisms.
- Eye Trauma:Open-globe injuries with concurrent lens damage demand rapid-access injector systems stocked in emergency ophthalmology suites.
Dominating revenue concentration: Cataract Surgery. Steepest expansion trajectory: Refractive Surgery.
End User:
Purchasing authority migrates from individual surgeons toward centralized procurement as facility scale and network integration increase.
- Ophthalmology Clinics:Independent practices and small group settings maintain surgeon-driven device selection with preference for pre-loaded platforms minimizing staff training.
- Hospitals:Integrated delivery networks in the United States negotiate enterprise contracts standardizing injector choice across affiliated facilities.
- Ambulatory Surgery Centers:Freestanding ophthalmic facilities constitute the highest-margin channel, prioritizing disposability and throughput over capital equipment amortization.
- Research Institutions:Academic medical centers drive adoption of experimental smart injector platforms requiring investigational device exemptions from FDA.
Capturing greatest volume: Ambulatory Surgery Centers. Gaining share fastest: Ophthalmology Clinics consolidating into regional chains.
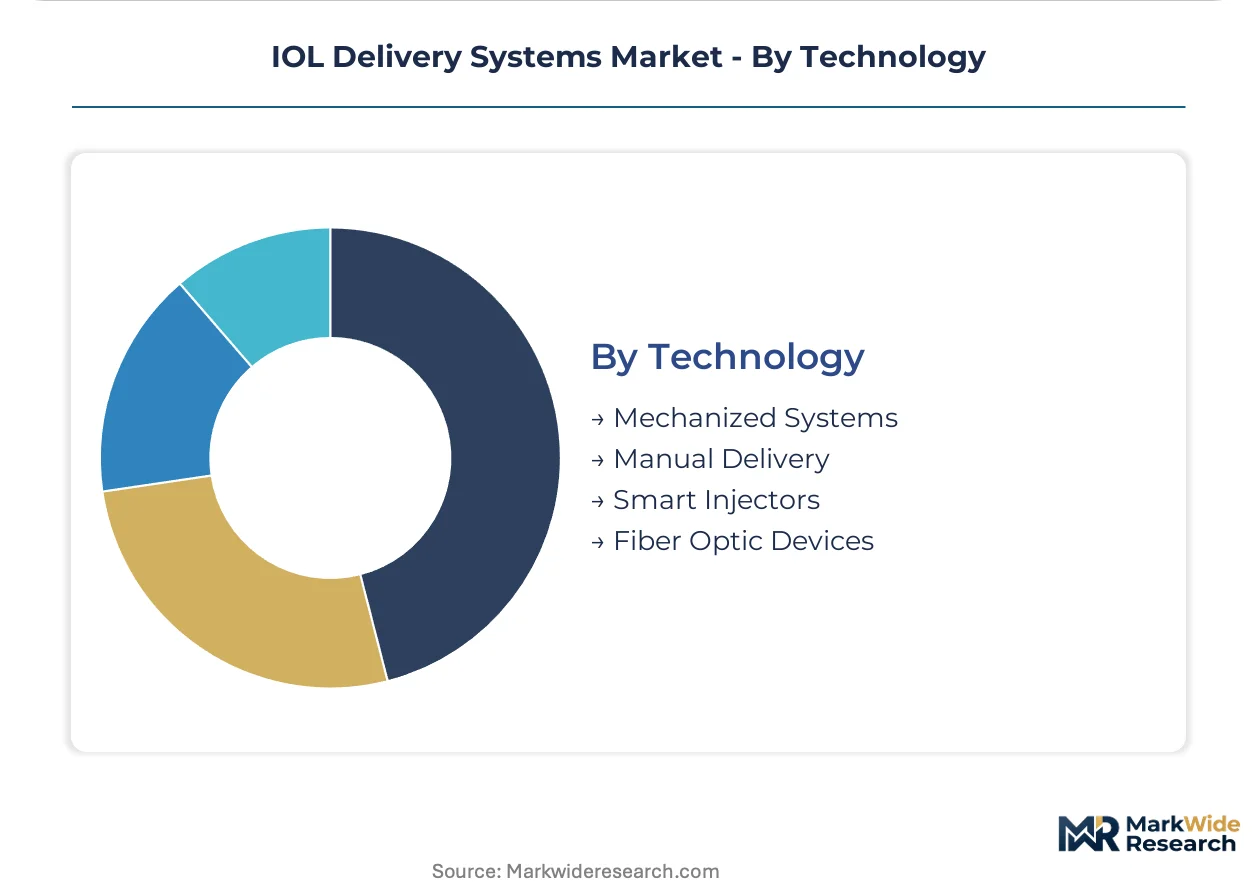
Technology:
Automation depth separates commodity disposable platforms from capital-intensive systems with embedded sensing and feedback capabilities.
- Mechanized Systems:Motorized plunger advancement with programmable insertion speed profiles enables consistent lens delivery through sub-2.2mm incisions. Japanese manufacturers lead in miniaturization of drive mechanisms.
- Manual Delivery:Spring-loaded or screw-type plungers without electronic components dominate cost-sensitive markets and emergency backup inventories.
- Smart Injectors:Micro-force sensors and real-time pressure feedback differentiate premium tiers, though IEC 60601 electrical safety compliance extends development timelines.
- Fiber Optic Devices:Illuminated delivery channels enhance visualization during complex cases with compromised anterior chamber clarity.
Holding largest installed base: Manual Delivery. Climbing the fastest: Smart Injectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech special economic zones in Bavaria and Baden-Württemberg concentrate precision molding capacity for IOL delivery components. These German clusters anchor European supply chains while FDA-cleared manufacturers in Massachusetts and California serve North American ambulatory networks.
United States
Medicare reimbursement for outpatient cataract procedures drives demand at freestanding surgery centers in Florida and Arizona. FDA 510(k) predicate device requirements constrain novel smart injector submissions, extending regulatory timelines for sensor-enabled platforms. Boston-area medical device clusters house mechanized injector R&D operations serving integrated delivery networks.
Germany
DRG reimbursement structures favor predictable per-procedure costing at hospital networks in North Rhine-Westphalia. EU MDR conformity assessment timelines accelerate consolidation among manufacturers with established ISO 13485 quality systems. Stuttgart precision engineering firms supply high-tolerance injection-molded cartridges for pre-loaded injector platforms.
Japan
Aging demographics sustain cataract procedural volumes at tertiary centers in Tokyo and Osaka. PMDA medical device reviews prioritize clinical data for premium toric and multifocal lens compatibility. Nagoya-based manufacturers lead miniaturization of motorized plunger drive mechanisms for sub-2.2mm incision systems.
India
Tier-2 metropolitan markets in Gujarat and Tamil Nadu present underpenetrated cataract service lines for pre-loaded injector distribution. CDSCO medical device registration requirements are harmonizing with international standards for foreign manufacturers. Hyderabad medical device parks attract contract manufacturing for disposable injector components serving Asian markets.
IOL Delivery Systems Market Competitive Landscape
United States producers anchor one tier; Japanese and German specialists hold precision-engineering positions in mechanized and pre-loaded segments. The vendor base concentrates around diversified ophthalmology portfolios and dedicated surgical device houses. Three archetypes dominate: integrated multinationals with cataract-to-refractive coverage, regional disposable specialists, and precision-component contract manufacturers. Competitive moves center on direct-to-ambulatory procurement programs and sensor-enabled delivery feedback differentiation.
Among diversified ophthalmology portfolios, Johnson & Johnson and Alcon Laboratories exemplify integrated multinationals spanning mechanized injector platforms through direct hospital and surgery center channels. Hoya Surgical Optics occupies a position within Asia-Pacific-focused specialists optimized for premium intraocular lens compatibility.
| Leading Market Players |
|---|
| Hoya Surgical Optics |
| AST Products |
| Johnson & Johnson |
| Hanita Lenses Ltd. |
| Medline Industries |
| Alcon Laboratories |
| Rayner Surgical Group |
| Medicel AG |
| Novartis |
| Others |
Supply & Pricing Matrix
Gas-assisted injection technology is compressing cost economics across premium and standard injector tiers while concentrating supply relationships among Bavarian precision molding specialists capable of sub-micron tolerance manufacturing.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations at United States ambulatory surgery centers, where spot inventory discounts from German contract manufacturers attract price-sensitive hospital networks. Three-tier pricing structure across premium smart injectors, standard pre-loaded systems, and economy manual platforms separates sensor-enabled feedback systems from disposable cartridges. Pricing pressure stems from silicone polymer feedstock volatility compressing margins on elastomeric plunger seals. Hospital materials managers exhibit highest price sensitivity, while refractive surgery clinics prioritize precision over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Baden-Württemberg-based precision molders supplying high-tolerance cartridge housings for pre-loaded platforms. Manufacturing concentrates in Germany, Japan, and Massachusetts, with each cluster feeding distinct regulatory zones. Raw material dependencies span medical-grade silicone elastomers, titanium alloys for reusable handpieces, and optical-grade polymers for lubricated delivery channels. Tariff exposure on Chinese-sourced electronic components for smart injector platforms threatens cost predictability. Distribution runs through manufacturer-managed inventory programs at high-volume surgery centers and traditional medical device distributors serving hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IOL Delivery Systems Market functions as a cost-of-compliance arena where EU MDR certification timelines erect formidable barriers against undercapitalized entrants, entrenching incumbents with established ISO 13485 quality infrastructure.
For Market Incumbents: Lock in ambulatory surgery center procurement relationships through direct inventory management programs that bypass distributor markups and secure multi-year volume commitments. Deepen backward integration into silicone polymer compounding to defend margins against feedstock volatility threatening disposable component economics.
For New Entrants and Emerging Players: CDSCO harmonization with international standards in India opens a window for pre-loaded injector partnerships with regional hospital chains in Gujarat and Tamil Nadu. Target tier-2 metropolitan cataract networks where penetration remains shallow and surgeon training requirements favor simplified pre-loaded platforms over complex mechanized systems.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap disposable specialists with established FDA 510(k) predicates and EU MDR technical documentation. Long-term viability hinges on sensor-enabled delivery feedback differentiation capturing premium tier pricing. Watch PMDA accelerated review pathways for smart injector platforms as inflection signal for Japanese market access timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access timelines for manufacturers with pre-established ISO 13485 infrastructure. |
| Direct-to-Ambulatory Procurement Program | Captures margin and locks volume commitments at high-throughput United States surgery centers. |
| Sensor-Enabled Delivery Feedback Development | Differentiates premium tiers through real-time insertion pressure monitoring compliant with IEC 60601. |
| Silicone Polymer Backward Integration | Stabilizes input costs for elastomeric plunger seals amid feedstock price volatility. |
| India Tier-2 Distribution Partnership | Accesses underpenetrated cataract service lines in Gujarat and Tamil Nadu surgical networks. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract records formed the secondary backbone, supplemented by primary interviews with cataract surgeons, ambulatory surgery center administrators, biomedical engineers, and GPO contracts managers. Bottom-up demand modeling triangulated against top-down reimbursement trend analysis validated volume projections across the analysis window.
Historical procedural volume trendlines from Medicare claims data and Japanese Ministry of Health statistics anchored the forecast framework, with CAGR derivation reflecting product type segmentation across pre-loaded injectors, disposable systems, hand-held devices, and smart injector platforms. Modeled inputs incorporated ambulatory surgery center migration rates, premium IOL adoption curves, and regulatory pathway timelines for sensor-enabled platforms.
The model assumes a particular technology adoption path; alternative pathways for gas-assisted injection mechanisms would alter the outlook if endothelial cell trauma data shifts surgeon preference. Deviation in EU MDR conformity assessment timelines or FDA 510(k) predicate availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Digital Intraoral Camera Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Contact Lenses Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Depression Devices Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Intubation Accessories Market