
 Smart Sweeper Market | 2026-2036
Smart Sweeper Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sweeper Market Insights
Modular subscription pricing for software-enabled fleet management is decoupling hardware ownership from operational control in municipal procurement. iRobot leverages its mapping algorithm heritage to anchor premium positioning in North American facility maintenance contracts. Ecovacs Robotics sustains manufacturing scale through captive component plants in Dongguan and Suzhou. Roborock differentiates via LIDAR navigation precision that commands price premiums in European commercial channels.
Smart sweepers integrate brush assemblies, vacuum extraction systems, and autonomous guidance platforms to remove debris from paved surfaces without human operation. Industrial-grade units deploy 48V lithium-ion battery packs delivering eight-hour continuous runtime at noise levels below 75 decibels. Robotic sweepers occupy the fastest-expanding margin pool as airports and logistics parks mandate overnight autonomous cleaning cycles. Battery-Powered technology leads unit shipments while Hybrid Models capture premium pricing in cold-climate municipalities where range anxiety persists.
EPA Tier 4 Final regulations and the EU Green Deal's municipal fleet electrification timelines are forcing diesel sweeper obsolescence across OECD markets. China's MIIT dual carbon goals and GB standards for electric sanitation equipment accelerate domestic OEM consolidation while restricting import access. Stakeholders must monitor NHTSA autonomous vehicle classification rulings that could reclassify street-operating sweepers under commercial trucking safety regimes, altering liability and certification burdens.
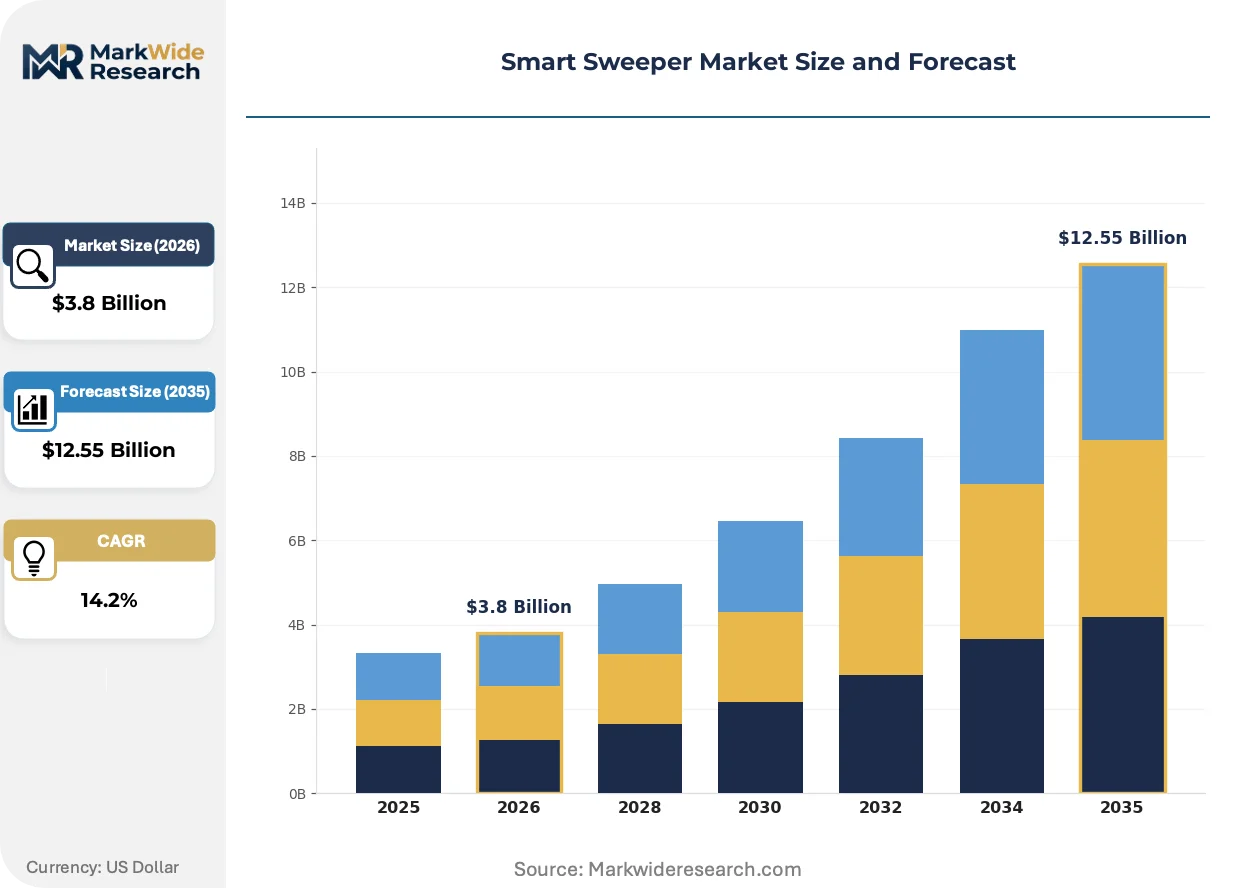
Market Dynamics
Municipal fleet electrification mandates are compressing diesel sweeper replacement cycles while autonomous navigation software redefines operational labor models across sanitation procurement.
Growth Catalysts
- EPA Tier 4 Final:The US emissions framework is accelerating municipal diesel sweeper phase-outs, forcing budget allocations toward battery-electric replacements before 2027 compliance deadlines.
- Logistics parks:Overnight autonomous cleaning cycles in air cargo facilities and distribution centers are creating dedicated demand for robotic units with eight-hour continuous runtime specifications.
- LIDAR navigation:Precision mapping capabilities are expanding addressable applications from controlled indoor environments to complex outdoor streetscapes with variable debris profiles.
Market Restraints
- Lithium-ion cell supply:Battery pack cost volatility and cathode material concentration in Chinese processing facilities create input cost uncertainty for 48V drivetrain manufacturers.
- Autonomous classification ambiguity:NHTSA has not issued definitive rulings on whether street-operating sweepers fall under commercial trucking safety regimes, delaying liability framework clarity.
- Manual sanitation labor:Low-wage human sweepers in emerging economies remain cost-competitive against capital-intensive robotic alternatives, constraining price elasticity.
Strategic Opportunities
- India smart cities:The country's urban infrastructure mission is allocating dedicated budgets for automated sanitation systems in 100 designated metropolitan areas.
- Subscription fleet management:Software-enabled operational control without hardware ownership is opening municipal procurement to vendors lacking balance-sheet capacity for outright purchase.
- GB standards alignment:China's domestic electric sanitation equipment certification is creating technical barriers that favor local OEM consolidation over import competition.
Industry Challenges
- Autonomous systems integration:Municipal maintenance departments lack technician pipelines trained in simultaneous repair of mechanical brush assemblies and AI navigation platforms.
- Multi-jurisdiction certification:Street-operating units must satisfy divergent safety protocols across city, state, and federal transportation authorities, extending commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sweeper Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Sweepers, Robotic Sweepers, Industrial Sweepers, Manual Sweepers Technology: Battery-Powered, Autonomous Navigation, Sensor-Based, Hybrid Models Application: Street Cleaning, Facility Maintenance, Parking Lots, Airport Runways End User: Municipalities, Industrial Facilities, Airports, Commercial Businesses |
| Companies Covered | iRobot, Ecovacs Robotics, Roborock, Dyson, Vorwerk, ILIFE, LG Electronics, Samsung Electronics, Nilfisk Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sweeper Market Trends and Innovations
Edge computing architectures are relocating navigation processing from cloud dependencies to onboard units, reducing latency for real-time obstacle avoidance in dynamic street environments.
Solid-state LIDAR is decentralizing high-precision mapping from premium European commercial channels to mid-tier municipal procurement segments by collapsing sensor cost curves below five-hundred-dollar unit economics. Airport authorities in Germany and the Netherlands are deploying these sensors for overnight tarmac debris removal, compressing the performance gap between facility-grade and street-grade autonomous platforms.
The EU Green Deal's municipal fleet electrification timeline is mandating fifty-percent zero-emission sanitation vehicle procurement by 2030, forcing Nordic and Benelux municipalities to accelerate hybrid and battery-electric sweeper adoption ahead of technical readiness for full electrification in sub-zero operating conditions.
Outcome-based service contracting is displacing capital expenditure procurement in North American facility maintenance, with logistics park operators paying per-cleaned-square-meter rather than acquiring hardware. This shift concentrates vendor selection criteria on operational uptime guarantees rather than equipment specifications, favoring suppliers with captive technical service networks across the US Sun Belt distribution corridor.
Smart Sweeper Market Segmentation
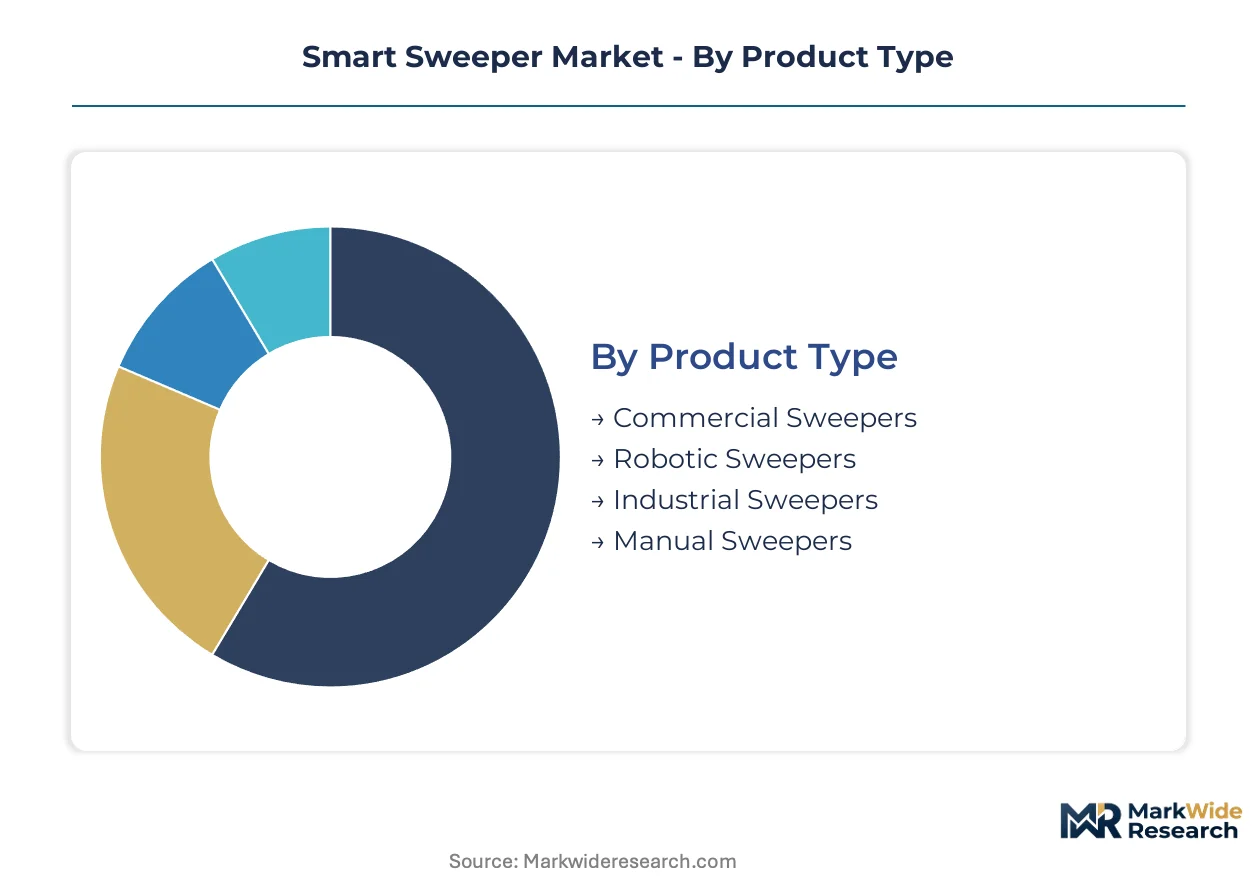
Smart sweeper procurement diverges sharply between integrated fleet deployments and standalone unit sales. Municipal buyers prioritize drivetrain electrification and autonomous navigation bundles, while facility operators segment purchases by runtime specifications and debris handling capacity.
Product Type:
Integration depth varies from fully embedded robotic systems to standalone manual equipment requiring no software infrastructure.
- Robotic Sweepers:These units combine autonomous guidance platforms with brush assemblies and vacuum extraction in unified architectures. Demand concentrates in German and Dutch airport authorities deploying overnight tarmac cleaning cycles under EU Green Deal fleet mandates. LIDAR navigation precision commands price premiums in European commercial channels where eight-hour continuous runtime specifications are mandatory.
- Industrial Sweepers:Heavy-duty platforms deploy 48V lithium-ion battery packs delivering sustained operation at noise levels below 75 decibels. US logistics parks across the Sun Belt distribution corridor specify these units for autonomous overnight cleaning, with procurement criteria shifting toward operational uptime guarantees rather than equipment specifications.
- Commercial Sweepers:Mid-tier units serve facility maintenance contracts with modular subscription pricing decoupling hardware ownership from operational control.
- Manual Sweepers:Low-capital equipment remains cost-competitive in emerging economies where human sanitation labor operates at wage structures below robotic alternatives.
Volume placements concentrate in Industrial Sweepers; the faster expansion belongs to Robotic Sweepers.
Technology:
Cost tiering separates premium autonomous systems from budget battery-electric platforms, with hybrid configurations occupying intermediate price bands.
- Battery-Powered:48V lithium-ion drivetrains dominate unit shipments under EPA Tier 4 Final mandates accelerating diesel phase-outs before compliance deadlines. Cell supply volatility and cathode material processing concentration in Chinese facilities create input cost uncertainty for manufacturers.
- Autonomous Navigation:Edge computing architectures are relocating navigation processing from cloud dependencies to onboard units, reducing latency for real-time obstacle avoidance in dynamic street environments. NHTSA classification ambiguity delays liability framework clarity for street-operating units.
- Sensor-Based:Solid-state LIDAR is collapsing sensor cost curves below five-hundred-dollar unit economics, decentralizing high-precision mapping from premium to mid-tier segments.
- Hybrid Models:Dual-power configurations capture premium pricing in Nordic and Benelux municipalities where sub-zero operating conditions persist, accelerating adoption ahead of full electrification technical readiness.
Cost tiering places Battery-Powered at volume leadership; Autonomous Navigation claims the steepest expansion trajectory.
Application:
Customer type determines specification intensity, with infrastructure-scale buyers demanding higher integration than discrete facility operators.
- Street Cleaning:Municipal fleet procurement spans autonomous street-cleaning units as labor costs escalate across US cities. Multi-jurisdiction certification requirements across city, state, and federal transportation authorities extend commercialization timelines.
- Facility Maintenance:Outcome-based service contracting is displacing capital expenditure procurement, with logistics park operators paying per-cleaned-square-meter rather than acquiring hardware. iRobot leverages mapping algorithm heritage to anchor premium positioning in North American contracts.
- Airport Runways:German and Dutch authorities deploy solid-state LIDAR sensors for overnight tarmac debris removal, compressing the performance gap between facility-grade and street-grade platforms.
- Parking Lots:Smaller-scale autonomous units serve commercial real estate with reduced debris complexity compared to street environments.
Facility Maintenance holds current volume dominance; Airport Runways demonstrate the most rapid share gain.
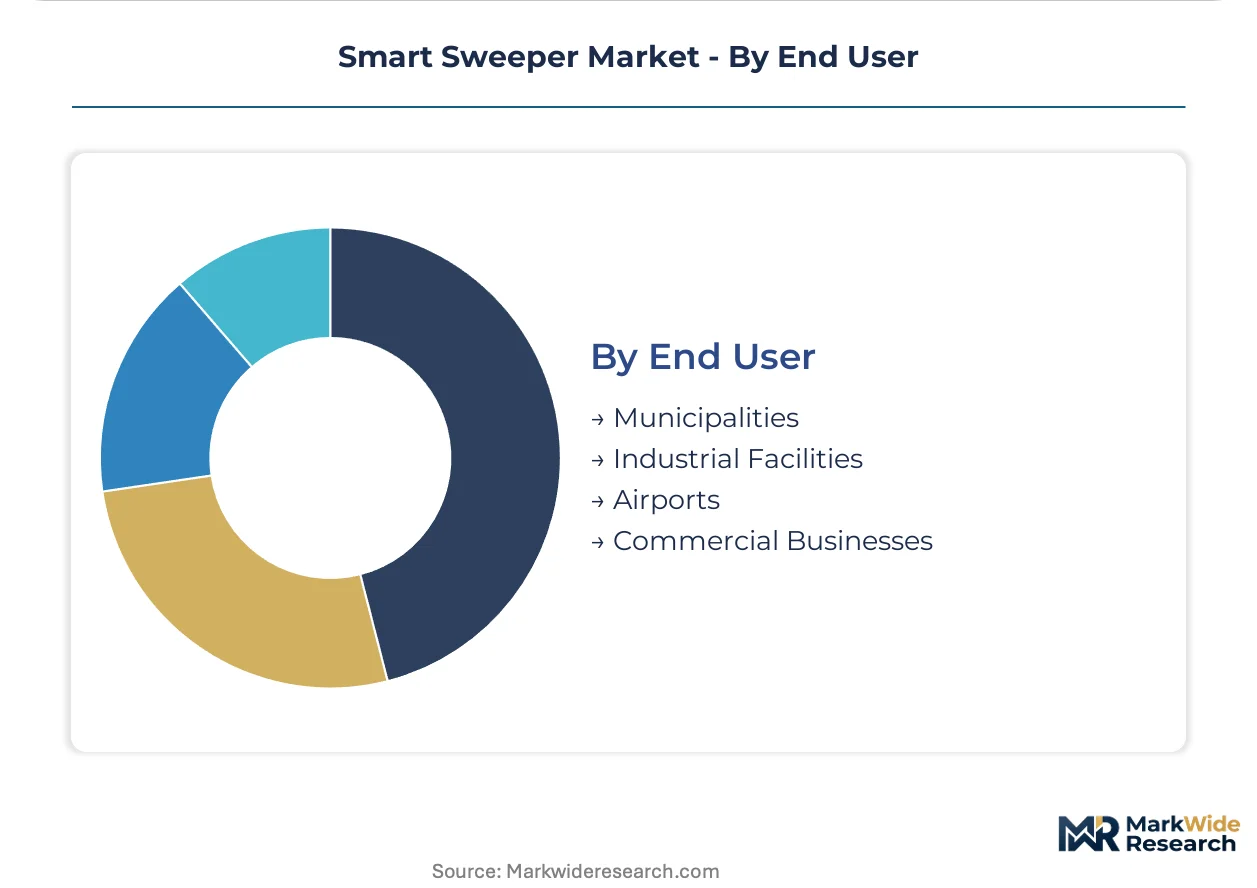
End User:
Supply concentration favors captive manufacturing scale, with vendor selection criteria weighting technical service network density.
- Municipalities:China's urban infrastructure mission allocates dedicated budgets for automated sanitation systems in metropolitan areas, with MIIT dual carbon goals and GB standards accelerating domestic OEM consolidation. Subscription fleet management models open procurement to vendors lacking balance-sheet capacity for outright purchase.
- Industrial Facilities:Maintenance departments lack technician pipelines trained in simultaneous repair of mechanical brush assemblies and AI navigation platforms, creating service network dependencies.
- Airports:Overnight autonomous cleaning cycles mandate eight-hour continuous runtime specifications with precision debris detection.
- Commercial Businesses:Smaller operators prioritize capital flexibility through operational leasing rather than equipment ownership.
Municipalities anchor procurement volume; Industrial Facilities expand most quickly as technician training pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters dominate component supply while consumption concentrates in US and European municipal procurement. Battery cell processing and LIDAR sensor fabrication anchor production in Dongguan and Suzhou. Demand-side procurement flows through EPA Tier 4 Final compliance deadlines and EU Green Deal fleet mandates.
United States
Municipal fleet managers in Los Angeles and New York City are accelerating diesel sweeper replacements ahead of EPA Tier 4 Final deadlines. NHTSA autonomous vehicle classification rulings remain pending for street-operating units. The Sun Belt distribution corridor from Dallas to Atlanta generates concentrated demand for logistics park cleaning contracts.
Germany
Airport authorities in Frankfurt and Munich deploy solid-state LIDAR-equipped units for overnight tarmac debris removal under EU Green Deal timelines. The KBA maintains certification protocols for autonomous street-operating equipment. Bavarian industrial clusters around Nuremberg supply precision brush assemblies to European OEMs.
China
MIIT dual carbon goals and GB standards for electric sanitation equipment are consolidating domestic OEM capacity in Shenzhen and Beijing. Municipal budgets in Shanghai and Guangzhou prioritize smart-city infrastructure with automated sanitation systems. Dongguan and Suzhou host captive component plants serving global supply chains.
Netherlands
Amsterdam Schiphol and Rotterdam port authorities mandate zero-emission cleaning cycles under national fleet electrification targets. The EU Green Deal's fifty-percent zero-emission procurement deadline by 2030 compresses adoption timelines. Eindhoven's sensor technology cluster supplies solid-state LIDAR modules below five-hundred-dollar unit economics.
India
The Smart Cities Mission allocates dedicated budgets for automated sanitation across 100 metropolitan areas including Mumbai and Bangalore. BIS certification requirements for electric sanitation equipment are evolving alongside municipal procurement frameworks. Tamil Nadu and Karnataka industrial corridors are developing component assembly capacity for regional supply.
Smart Sweeper Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price bands. The vendor base stratifies between captive manufacturing scale and software-enabled fleet management platforms. Three archetypes dominate: robotics heritage players leveraging mapping algorithms, appliance conglomerates with distribution density, and industrial equipment specialists with service network coverage. Competitive moves center on subscription pricing models and backward integration into battery pack assembly.
Within the robotics heritage tier, iRobot and Roborock occupy positions anchored by navigation platform development. Ecovacs Robotics exemplifies manufacturing-scale competition through captive component plants. Among appliance conglomerates, Dyson and Samsung Electronics sit within premium positioning vectors. LG Electronics represents the diversified electronics house approach. Nilfisk Group anchors the industrial equipment specialist archetype with service network dependencies.
| Leading Market Players |
|---|
| iRobot |
| Ecovacs Robotics |
| Roborock |
| Dyson |
| Vorwerk |
| ILIFE |
| LG Electronics |
| Samsung Electronics |
| Nilfisk Group |
| Others |
Pricing and Supply Chain Analysis
Solid-state LIDAR cost curves collapsing below five-hundred-dollar unit economics are simultaneously compressing sensor procurement costs and redistributing manufacturing scale toward Chinese component clusters in Dongguan and Suzhou.
Pricing Analysis
Margin tightening in mid-tier municipal procurement reflects solid-state LIDAR penetration from premium European commercial channels. Three-tier pricing structure across premium autonomous, standard battery-electric, and economy manual equipment segments stratifies buyer access. Price differentiation hinges on GB standards certification for Chinese municipal contracts and after-sales service network density. Municipalities exhibit highest price sensitivity due to budget constraint rigidity, while airport authorities demonstrate lowest sensitivity given operational uptime premiums.
Supply Chain Analysis
Regional distribution centers in the US Sun Belt corridor and Benelux logistics hubs coordinate hub-and-spoke patterns for 48V lithium-ion battery pack deployment. Manufacturing concentrates in China, South Korea, and Germany for LIDAR sensors, cathode materials, and precision brush assemblies respectively. Raw material dependencies span lithium carbonate, rare-earth magnets, and high-tensile polymer composites. Single-source vulnerability in Chinese cathode processing facilities threatens input cost stability. Distribution runs through OEM-direct channels for municipal fleets and third-party logistics partners for facility maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive component manufacturing as EPA Tier 4 Final deadlines and MIIT dual carbon goals force balance-sheet-constrained competitors toward exit.
For Market Incumbents: Deepen backward integration into 48V battery pack assembly to offset cathode material volatility from Chinese processing concentration. Anchor channel control through subscription fleet management platforms that lock municipal procurement into operational uptime guarantees, defending against emerging robotics specialists lacking service network density. For New Entrants and Emerging Players: The premium-economy price gap in Indian smart cities creates white-space entry points where BIS certification requirements remain unsettled. Target Tamil Nadu and Karnataka industrial corridors for component assembly partnerships. Pursue outcome-based per-cleaned-square-meter contracting with logistics park operators to bypass capital-intensive hardware ownership barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in industrial equipment specialists with captive technical service networks across the US Sun Belt distribution corridor. Long-term viability favors vendors with simultaneous mechanical brush assembly and AI navigation platform repair capabilities. Monitor NHTSA autonomous vehicle classification rulings as inflection indicator for liability framework clarity and valuation multiple compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captive 48V lithium-ion production insulates margin from Chinese cathode processing volatility. |
| Subscription Fleet Management Platform Launch | Software-enabled operational control decouples hardware ownership from municipal procurement access. |
| GB Standards Certification Investment | Chinese MIIT dual carbon alignment creates technical barriers favoring domestic OEM consolidation. |
| Service Network Expansion in Sun Belt Corridor | Density across Dallas-Atlanta logistics parks anchors outcome-based contract viability. |
| Solid-State LIDAR Cost Curve Compression | Sub-five-hundred-dollar sensor economics decentralize precision mapping to mid-tier segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with municipal fleet managers, airport maintenance directors, OEM procurement leads, and aftermarket service heads. EPA Tier 4 Final compliance databases, MIIT equipment certification registries, and EU Green Deal municipal procurement disclosures provided demand-side validation. Bottom-up unit shipment estimates triangulated against top-down municipal budget allocation analysis.
Data-stream reconciliation across product type, technology tier, application intensity, and end-user procurement capacity dimensions shaped the analytical framework. CAGRs derived from slope-intercept modeling of replacement cycle compression and electrification mandate timelines. Forecast inputs incorporated NHTSA autonomous classification uncertainty bands and lithium-ion cell supply volatility scenarios across the projection horizon.
Inputs from Chinese MIIT certification registries and US municipal procurement databases were available through the study window; gaps in real-time NHTSA ruling timelines introduce uncertainty bands around street-operating unit commercialization trajectories. Forecasts reflect documented assumptions regarding electrification compliance deadlines and technician training pipeline maturation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Global Delivery Robots Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market
Robotics and Automation
Europe Logistics Robotics Market