
 Robotics Sweeper Market | 2026-2036
Robotics Sweeper Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics Sweeper Market Analytics
Multi-source procurement for navigation sensors is repositioning supply relationships across the robotics sweeper value chain. Ecovacs Robotics leverages its domestic manufacturing base to control cost structures in the consumer tier. iRobot Corporation anchors its position through sustained R&D intensity in mapping algorithms. Samsung Electronics competes by extending its semiconductor expertise into proprietary sensor fusion systems.
A robotics sweeper is an autonomous or semi-autonomous mobile platform equipped with rotating brushes, suction mechanisms, and debris collection chambers, typically operating on battery-electric powertrains with runtime capacities between four and eight hours. These machines perform programmed or real-time-directed cleaning of floors, pavements, and industrial surfaces without continuous human operation. Vacuuming robots currently dominate unit shipments in residential settings, while scrubbing robots command higher margin pools in commercial facilities where water-recovery and detergent-dispensing functions justify premium pricing. AI-driven navigation systems represent the fastest-expanding technology segment, displacing simpler sensor-based architectures as lidar costs decline and simultaneous localization and mapping capabilities standardize.
The EU F-Gas Regulation and REACH chemical standards constrain coolant and battery material choices for equipment sold in Europe, while the EPA's emissions benchmarks for outdoor power equipment shape product development for North American deployment. China's GB standards for service robots and MIIT connectivity requirements create a dual compliance burden for manufacturers sourcing components domestically but exporting globally. Stakeholders must monitor how divergent energy-efficiency certification schemes fragment platform architectures and force region-specific product variants.
Market Dynamics
Battery-electric powertrain maturation is compressing platform development cycles while EU Green Deal machinery mandates force simultaneous diesel fleet retirement across municipal sanitation departments.
Growth Catalysts
- EU Green Deal efficiency mandates:Municipal procurement specifications in Germany and France now require zero-emission certification for new street-cleaning equipment, accelerating electric robotic platform adoption.
- Lidar cost deflation:Component ecosystems around Shenzhen and Seoul have reduced sensor procurement costs below legacy ultrasonic architectures, democratizing SLAM navigation across price tiers.
- East Asian manufacturing clustering:Dense supplier networks for battery management systems and brush motor assemblies enable rapid prototype-to-production scaling for original equipment manufacturers.
Market Restraints
- Lithium-ion cell price volatility:Raw material concentration in South American brine deposits and Indonesian nickel processing creates input cost instability for runtime-dependent platform economics.
- REACH chemical compliance friction:ECHA substance restrictions on coolant formulations and battery electrolyte additives force dual chemistry formulations for European-bound versus domestic Chinese production.
- Autonomous navigation liability ambiguity:Absence of standardized fault attribution frameworks for pedestrian collision incidents limits uninsured deployment in dense urban environments.
Strategic Opportunities
- Industrial facility water-recovery integration:Scrubbing robot architectures with closed-loop detergent systems command premium positioning in pharmaceutical cleanrooms and food processing plants where contamination protocols are stringent.
- Japan METI carbon-neutrality subsidies:Domestic manufacturers accessing green innovation funding can offset R&D capitalization for hydrogen fuel cell sweeper variants targeting 2030 municipal fleet targets.
- Equipment-as-a-service channel emergence:Third-party fleet operators in Singapore and Dubai are bundling maintenance, software updates, and performance guarantees into subscription contracts that displace capital purchase decisions.
Industry Challenges
- SLAM algorithm talent scarcity:Recruitment competition from autonomous vehicle developers constrains robotics sweeper engineering teams seeking simultaneous localization expertise.
- Multi-jurisdiction certification timelines:Divergent GB standards, CE marking requirements, and FCC electromagnetic compliance testing extend product launch windows by 8-14 months for globally intended platforms.
- Legacy sweeper fleet integration complexity:Municipal procurement departments face technical debt from decades-old diesel infrastructure that lacks standardized telematics interfaces for mixed-fleet management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotics Sweeper Market |
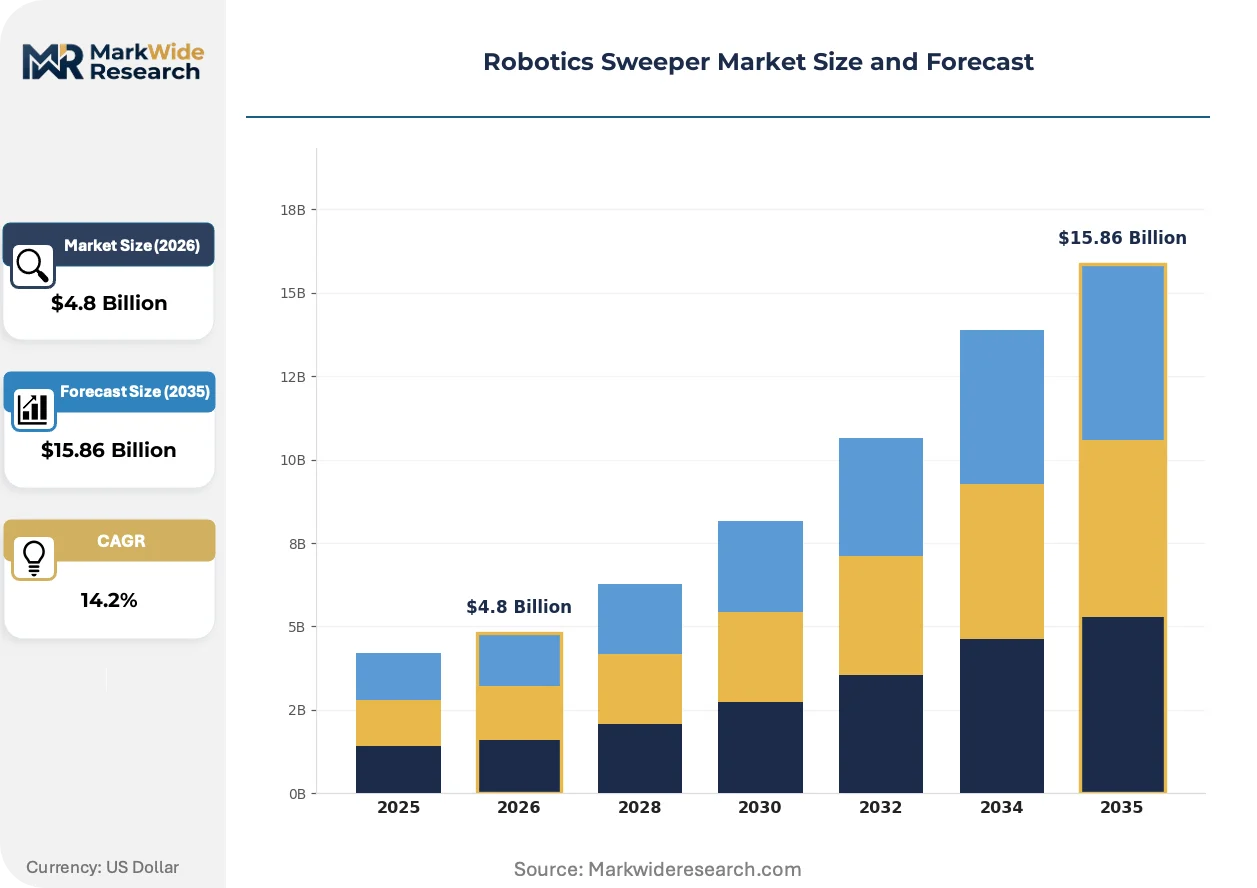
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brooming Robots, Vacuuming Robots, Scrubbing Robots, Multi-Function Robots Technology: Autonomous Navigation, Sensor-Based, Teleoperation, AI-Driven End User: Commercial Facilities, Industrial Sites, Airports, Shopping Malls Operating Environment: Indoor Spaces, Outdoor Grounds, Streets, Warehouses |
| Companies Covered | Roborock, iRobot Corporation, Ecovacs Robotics, Xiaomi Corporation, Samsung Electronics, SharkNinja Operating, Dyson, LG Electronics, Neato Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics Sweeper Market Evolving Landscape
Solid-state lidar architectures are collapsing the cost-performance frontier for navigation systems, while regulatory pressure on embodied carbon is rewriting material selection criteria across the value chain.
Solid-state lidar with MEMS beam-steering is consolidating the mid-tier navigation market previously served by mechanical spinning units. German municipal operators now specify solid-state minimums for new procurements, citing vibration tolerance and maintenance interval advantages. The technology compression is eliminating tier-two mechanical lidar suppliers and concentrating procurement relationships around semiconductor-integrated sensor platforms.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing brush material substitutions in equipment sold across European Economic Area member states. Manufacturers are pivoting to bio-based polymer bristles and ceramic composite alternatives that satisfy chemical compliance without degrading debris capture efficiency. The regulatory pressure is most acute for scrubbing robot variants where detergent compatibility testing adds 4-6 months to product validation cycles.
Municipal sanitation departments are fragmenting their vendor relationships to avoid single-source dependency in critical subsystems. Procurement officers in Seoul and Amsterdam now require dual-qualified suppliers for battery management systems and navigation compute modules, with penalty clauses for sole-source component failures. The behavior shift is most visible in contracts above 50-unit annual volumes where risk-weighted total cost of ownership models have displaced upfront price minimization criteria.
Robotics Sweeper Market Segmentation
Robotics sweeper segmentation reveals divergent margin architectures across product tiers. Technology choices determine platform economics, while end-user concentration shapes regional deployment patterns and procurement specifications.
Product Type:
Volume shipments concentrate in residential-grade vacuuming units, while premium margins accrue to commercial scrubbing platforms with water-recovery systems.
- Vacuuming Robots:Suction-dominant platforms with cyclonic debris separation and HEPA filtration dominate residential unit volumes. Demand clusters in German and Japanese metropolitan households where compact form factors suit high-density living. Runtime limitations below six hours constrain deployment in facilities exceeding 500 square meters.
- Scrubbing Robots:Water-based cleaning platforms integrate detergent dosing, brush agitation, and vacuum recovery for hard surface maintenance. Pharmaceutical cleanrooms in Basel and food processing plants near Seoul specify closed-loop variants where contamination protocols mandate zero discharge. Premium positioning reflects 3-4x hardware cost versus vacuuming equivalents.
- Brooming Robots:Rotating brush mechanisms target coarse debris on uneven surfaces. Municipal procurement in Amsterdam favors these units for cobblestone street maintenance where suction systems clog.
- Multi-Function Robots:Modular architectures swap cleaning heads between vacuum, scrub, and sweep modes. Singapore facility managers deploy single-platform fleets to reduce spare parts inventory.
Today's leader: Scrubbing Robots. Tomorrow's challenger: Multi-Function Robots.
Technology:
Navigation sophistication now separates price tiers more decisively than mechanical cleaning performance.
- AI-Driven:Deep learning architectures process camera and lidar inputs for dynamic obstacle avoidance and coverage optimization. Shenzhen manufacturing clusters supply neural network accelerators at cost points displacing legacy rule-based systems. Deployment concentrates in Dubai airport terminals where pedestrian density varies unpredictably.
- Autonomous Navigation:SLAM-based platforms without predictive path planning occupy the commercial mid-tier. Seoul municipal fleets specify these units for predetermined route coverage where map updates occur quarterly.
- Sensor-Based:Ultrasonic and infrared bumper systems dominate entry-level residential units. Price compression from Shenzhen component ecosystems maintains sub-$200 retail positioning.
- Teleoperation:Human-in-the-loop control persists in hazardous environments like chemical spill response. Osaka industrial safety regulations mandate remote oversight for outdoor robotic sweepers near traffic.
AI-Driven platforms are climbing the fastest, while Sensor-Based units defend volume share through cost minimization.
End User:
Procurement sophistication varies sharply across facility types, with airports and pharmaceutical sites driving specification intensity.
- Commercial Facilities:Office complexes and hospitality venues prioritize nighttime autonomous operation with minimal supervision. Frankfurt facility managers specify noise levels below 60 decibels for daytime deployment.
- Industrial Sites:Manufacturing floors demand explosion-proof certifications and chemical-resistant chassis. BASF Ludwigshafen operations require ATEX-compliant units for solvent vapor environments.
- Airports:24-hour operation mandates and foreign object debris detection dominate procurement. Incheon International specifies millimeter-wave radar integration for runway perimeter sweepers.
- Shopping Malls:Aesthetic integration and crowd navigation shape purchasing decisions. Dubai Mall operators favor transparent debris chambers for visible cleaning confirmation.
Industrial Sites command the steepest specification requirements. Shopping Malls represent the most price-sensitive volume pool.
Operating Environment:
Environmental exposure determines chassis durability ratings and navigation sensor selection more than cleaning mechanism choice.
- Outdoor Grounds:IP65+ sealing and temperature tolerance from -20°C to 50°C define platform viability. Munich municipal contracts specify snow-load brush motor torque for year-round deployment.
- Streets:Curb-climbing capability and traffic interaction protocols dominate design. Amsterdam requires V2X communication modules for sweepers sharing roads with cyclists.
- Indoor Spaces:Controlled lighting and flat surfaces enable lower-cost sensor configurations. Tokyo office towers prioritize elevator integration for multi-floor coverage.
- Warehouses:Narrow aisle navigation and pallet rack clearance constraints shape form factors. Amazon fulfillment centers in Leipzig specify sub-1.2-meter width for racking proximity.
Outdoor Grounds platforms carry the highest technical barriers. Indoor Spaces sustain the largest addressable unit base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging compliance costs by routing production through jurisdictions with streamlined certification pathways while maintaining sales presence in regulated markets. Shenzhen and Seoul component ecosystems absorb REACH and F-Gas regulatory burdens at the subassembly stage, preserving margin for finished goods destined for European municipal procurement.
Germany
Municipal sanitation departments in Munich and Berlin are replacing diesel sweeper fleets under EU Green Deal machinery mandates. The country's national environmental regulator enforces zero-emission certification for new street-cleaning equipment through tiered compliance deadlines. Bavaria's industrial corridor hosts testing facilities where solid-state lidar suppliers validate vibration tolerance for cobblestone deployment.
China
Domestic demand concentrates in Shenzhen manufacturing clusters where component ecosystems for battery management systems and brush motor assemblies enable rapid scaling. MIIT connectivity requirements and GB standards for service robots create dual compliance burdens for exporters. Pearl River Delta original equipment manufacturers supply neural network accelerators at cost points displacing legacy navigation architectures.
Japan
METI carbon-neutrality subsidies offset R&D capitalization for hydrogen fuel cell sweeper variants targeting 2030 municipal fleet targets. Osaka industrial safety regulations mandate remote oversight for outdoor robotic sweepers near traffic. Kansai region facility managers prioritize elevator integration for multi-floor coverage in high-density Tokyo office towers.
United States
EPA emissions benchmarks for outdoor power equipment shape product development for North American deployment. The Federal Communications Commission electromagnetic compliance testing extends launch windows for globally intended platforms. Amazon fulfillment centers in Illinois and Texas specify sub-1.2-meter width for narrow aisle navigation in warehouse racking proximity.
Netherlands
Amsterdam procurement officers require dual-qualified suppliers for battery management systems with penalty clauses for sole-source component failures. The country's national chemical regulator enforces REACH Annex XVII restrictions on per- and polyfluoroalkyl substances in brush materials. Randstad municipal contracts specify V2X communication modules for sweepers sharing roads with cyclists.
Robotics Sweeper Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent automation spaces to leverage overlapping component supply chains. The vendor base clusters around three strategic archetypes: consumer electronics conglomerates extending semiconductor expertise into sensor fusion, pure-play robotics specialists anchoring position through mapping algorithm intensity, and domestic manufacturing champions controlling cost structures through captive supply networks. Competitive moves concentrate on strategic partnerships for navigation compute modules and geographic expansion into municipal procurement markets with subsidy-aligned product variants.
Among Asia-Pacific-based fabricators, Ecovacs Robotics and Roborock exemplify the domestic manufacturing champion archetype, while iRobot Corporation occupies a position representing sustained R&D intensity in algorithm development. Samsung Electronics anchors the consumer electronics conglomerate tier, extending semiconductor expertise into proprietary navigation systems. These three companies collectively represent the competitive tension between cost-controlled scaling and premium-tier technology differentiation that defines current market structure.
| Leading Market Players |
|---|
| Roborock |
| iRobot Corporation |
| Ecovacs Robotics |
| Xiaomi Corporation |
| Samsung Electronics |
| SharkNinja Operating |
| Dyson |
| LG Electronics |
| Neato Robotics |
| Others |
Value Network & Pricing Analysis
Captive integration into Shenzhen and Seoul component ecosystems anchors supply positioning for navigation sensors and battery management systems while compressing procurement costs below legacy architectures. This upstream control enables tiered pricing stratification across premium solid-state lidar configurations, standard SLAM-based commercial units, and economy sensor-based residential platforms.
Pricing Analysis
Distributor margin layers in municipal procurement channels absorb 15-25 point markups before fleet operators, while direct-to-OEM arrangements for component subassemblies bypass retail overhead. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cleanroom scrubbing robots with closed-loop water recovery from commercial vacuuming units and entry-level residential sweepers. Price differentiation hinges on certification grade for EU Green Deal zero-emission compliance and runtime capacity above six hours. Cost compression in the sensor-based tier is intensifying because Shenzhen neural network accelerator supply has democratized AI-driven navigation. Shopping mall facility managers represent the most price-sensitive buyer pool, while airport procurement officers prioritize foreign object debris detection capability over unit economics.
Supply Chain Analysis
China's MIIT domestic-content mandates for service robot connectivity modules are reshaping sourcing patterns for manufacturers exporting to European markets. Component supply concentrates in China, South Korea, and Japan for lithium-ion cells, solid-state lidar MEMS platforms, and brush motor assemblies. Raw material dependencies draw from South American brine deposits for lithium carbonate and Indonesian nickel processing facilities for cathode chemistry. Single-source vulnerability in semiconductor-integrated sensor platforms threatens procurement continuity for German municipal fleet operators specifying solid-state minimums. Distribution runs through Pearl River Delta original equipment manufacturers to regional subsystem integrators, with finished goods routing through Amsterdam and Dubai for municipal procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on lidar cost deflation collapsing the premium tier entry threshold while EU Green Deal mandates force replacement cycles in diesel-dependent municipal fleets.
For Market Incumbents: Deepen backward integration into Shenzhen battery management system supply to defend cost structures against emerging domestic manufacturing champions. Lock exclusive solid-state lidar allocation agreements with Seoul semiconductor fabs before capacity constraints tighten. Reinforce algorithm R&D intensity in SLAM navigation as autonomous vehicle developers poach talent from robotics sweeper engineering teams. For New Entrants and Emerging Players: Solid-state lidar cost-performance convergence creates entry space in the commercial mid-tier previously defended by mechanical sensor incumbents. Target pharmaceutical cleanroom scrubbing applications in Basel and Seoul where contamination protocols command 3-4x hardware premiums and incumbent presence remains thin. Pursue equipment-as-a-service subscription positioning in Singapore and Dubai to bypass capital purchase friction among third-party fleet operators. For Investors and Strategic Acquirers: Roll-up economics work for pure-play robotics specialists with captive navigation algorithm IP because municipal procurement fragmentation prevents single-vendor dominance across geographic markets. Acquisition targets should demonstrate quarterly recurring software revenue attachment and dual-qualified supplier relationships for critical subsystems. Watch for inflection when Japan METI hydrogen fuel cell subsidy disbursements accelerate R&D capitalization for 2030 fleet targets.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Lidar Integration | German municipal procurement now specifies MEMS beam-steering minimums for cobblestone vibration tolerance. |
| Closed-Loop Water Recovery Development | Pharmaceutical cleanrooms in Basel mandate zero-discharge scrubbing variants commanding premium positioning. |
| Dual-Qualified Supplier Certification | Amsterdam procurement officers penalize sole-source battery management system dependencies above 50-unit contracts. |
| Hydrogen Fuel Cell R&D Investment | Japan METI carbon-neutrality subsidies offset capitalization for 2030 municipal fleet replacement targets. |
| Equipment-as-a-Service Channel Buildout | Singapore fleet operators bundle maintenance and software updates into subscription contracts displacing capital purchases. |
Research Methodology
Bottom-up facility-type modeling reconciled against top-down component supply tracking forms the analytical core of this study. Primary interviews with municipal procurement officers, pharmaceutical facility managers, airport operations directors, and robotics OEM engineering leads combined with secondary validation from EU Green Deal machinery mandate filings, ECHA REACH Annex XVII substance restriction updates, and Shenzhen customs export records. Top-down triangulation against MIIT connectivity requirement disclosures and METI subsidy program announcements ensures supply-side coverage matches demand segmentation.
Input-output matrices map neural network accelerator cost curves and lithium-ion cell price volatility against platform runtime economics and procurement specification intensity across the projection horizon. Segmentation dimensions modeled include cleaning mechanism type, navigation technology tier, end-user facility category, and operating environment exposure. CAGRs derive from unit shipment trajectories weighted by average selling price compression rates and premium-tier mix shifts. Forecast inputs incorporate solid-state lidar adoption S-curves and EU F-Gas Regulation compliance cost pass-through assumptions.
The model holds under continued lidar cost deflation and stable lithium raw material supply; deviation in South American brine export restrictions or Indonesian nickel processing disruptions would shift platform economics. Forecasts reflect documented assumptions regarding municipal fleet replacement timelines and REACH chemical compliance phase-in schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
Global Soldering Robot Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Humanoids Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Mobile Robot Charging Station Market
Robotics and Automation
Latin America Warehouse Robotics Market