
 Japan Articulated Robot Market | 2026-2036
Japan Articulated Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Articulated Robot Market Intelligence
Japan's carbon neutrality commitments under METI's Green Growth Strategy is consolidating demand for energy-efficient articulated robot systems across domestic manufacturing. Fanuc Corporation leverages its captive servo motor and CNC controller production to sustain margin control from component to system level. Yaskawa Electric Corporation anchors the welding automation segment through deep expertise in arc welding trajectory algorithms. Kawasaki Heavy Industries competes in heavy-payload material handling with long-reach six-axis designs for automotive body shops.
An articulated robot is a robotic manipulator with multiple rotary joints—typically four to seven axes—enabling complex spatial movement for precise positioning, path following, and force-controlled operations in industrial environments. These systems execute repetitive or hazardous tasks with sub-millimeter repeatability, primarily serving automated production lines where human dexterity proves inconsistent or unsafe. Material handling applications dominate installed base volume across Japanese factories, while collaborative robots represent the fastest-expanding technology segment as SMEs seek fenceless deployment. Welding retains the densest margin pool due to specialized torch integration and seam-tracking software requirements. Electronics producers increasingly specify AI-driven solutions for high-mix, low-volume assembly of miniaturized components.
METI's Industrial Cybersecurity Framework and JIS B 8433 safety standards shape robot design requirements, forcing vendors to embed functional safety circuits and encrypted communication protocols. The Pharmaceuticals and Medical Devices Agency imposes cleanroom-compatible validation protocols that constrain market entry for non-domestic suppliers. Stakeholders must weigh integrated systems against stand-alone units based on in-house engineering depth and lifecycle service coverage expectations.
Market Dynamics
Japan's articulated robot sector faces intense pressure from METI's carbon neutrality mandates, which compel manufacturers to redesign powertrains and thermal management systems while maintaining cycle-time performance. This regulatory compression is forcing simultaneous investment in energy-efficient actuation and legacy fleet retrofitting.
Growth Catalysts
- Automotive Electrification:Battery module assembly lines in Toyota and Nissan facilities require precision torque control for cell stacking operations. Six-axis robots with force-feedback end effectors dominate new EV plant specifications.
- METI Society 5.0 Framework:Smart factory subsidies accelerate deployment of AI-integrated articulated systems with predictive maintenance capabilities. SMEs in Saitama Prefecture access grants covering installation costs.
- Collaborative Robotics:Fenceless cobot installations expand in Osaka's electronics subcontractor base. Power-and-force-limiting designs enable human-robot coexistence without physical guarding.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium-iron-boron prices fluctuate with Chinese export quotas. Servo motor manufacturers absorb margin compression or pass costs to system integrators.
- Domestic Supply Concentration:Three vendors control over two-thirds of domestic servo amplifier production. Earthquake risk in Shizuoka manufacturing clusters threatens component availability.
- JIS B 8433 Compliance Burden:Functional safety certification cycles extend 14-18 months for new collaborative robot platforms. Validation costs deter mid-tier entrants.
Strategic Opportunities
- Pharmaceutical Cleanroom Expansion:PMDA validation protocols favor domestically manufactured stainless steel robots with ISO 14644-1 Class 5 compatibility. Biologics fill-finish operations drive specification demand.
- AI-Vision Convergence:Deep learning-based defect detection merges with articulated motion planning. Semiconductor backend houses in Kumamoto pilot real-time path correction for die bonding.
- Retrofit Services:Aging 1990s-era Fanuc R-2000 series units in Nagoya automotive plants require controller upgrades and energy-efficient motor replacements. Lifecycle extension contracts capture recurring revenue.
Industry Challenges
- Mechatronics Talent Scarcity:Kinematic calibration and servo tuning expertise concentrates among engineers aged 55-plus. Technical colleges struggle to align curricula with Industry 4.0 skill requirements.
- Legacy System Integration:Proprietary fieldbus protocols from 2000s-era PLC architectures obstruct seamless data exchange with modern articulated controllers. Middleware development consumes integration project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Articulated Robot Market |
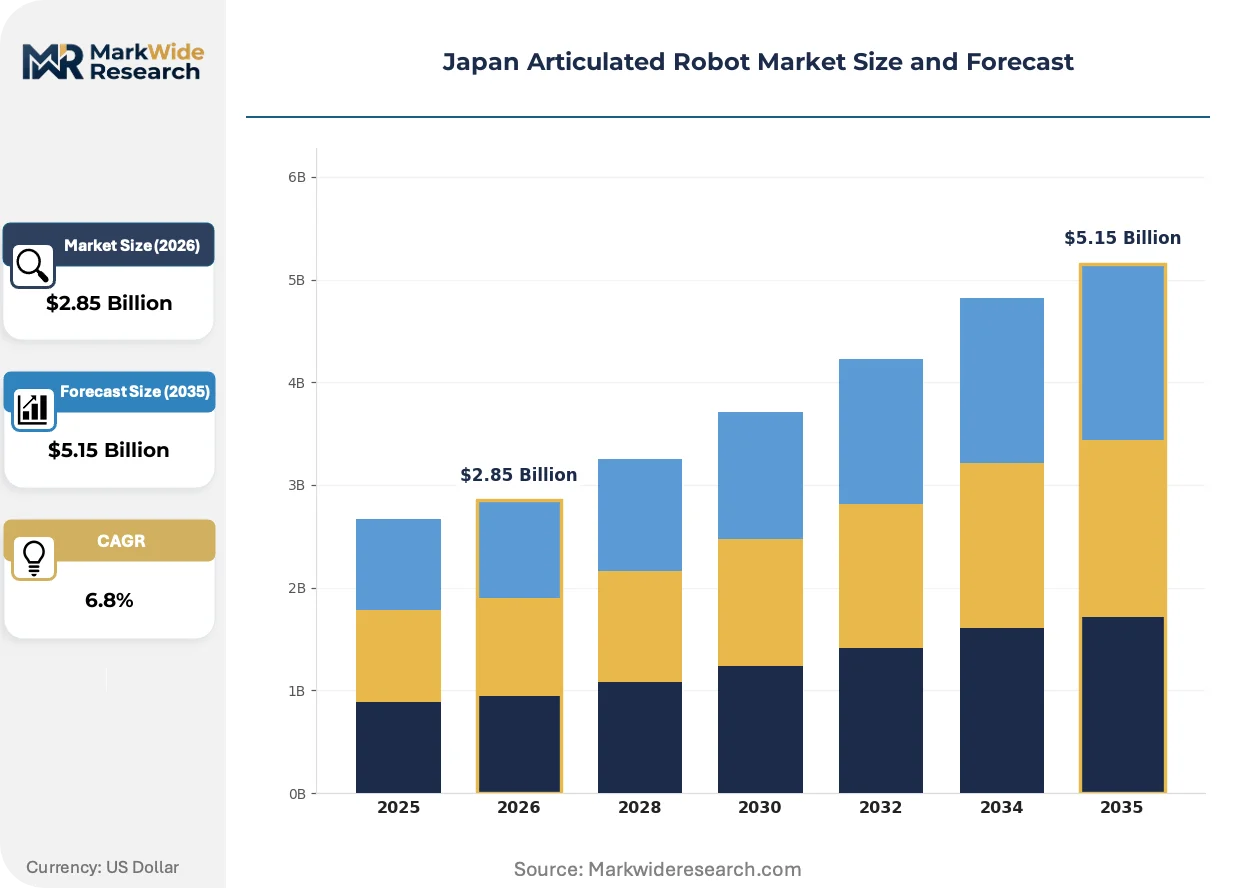
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Assembly, Material Handling, Welding, Painting End User: Automotive Manufacturers, Electronics Producers, Food Processing, Pharmaceuticals Technology: Collaborative Robots, Traditional Robots, Autonomous Mobile Robots, AI-Driven Solutions Solution: Integrated Systems, Stand-Alone Units, Custom Solutions, Retrofit Options |
| Companies Covered | Fanuc Corporation, Yaskawa Electric Corporation, Mitsubishi Electric Corporation, Kawasaki Heavy Industries, Nachi-Fujikoshi Corp, Kawada Robotics Corporation, Panasonic Corporation, Shibaura Machine Co., Ltd., Omron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Articulated Robot Market Strategic Shifts & Innovations
Direct-drive torque motors are eliminating gearbox maintenance points while raising positioning accuracy for semiconductor handling. This mechanical simplification cascades through downstream control architectures and service contract structures.
Harmonic drive alternatives with strain wave gearing are consolidating position in precision payload segments below twenty kilograms. Electronics assemblers in Kanagawa Prefecture specify these actuators for miniaturized component placement. The technology is consolidating supplier relationships around captive bearing and flexspline manufacturers with JIS-certified cleanroom production.
METI's Industrial Cybersecurity Framework mandates encrypted EtherCAT communication and safety-rated monitored stop functions. Robot OEMs embed hardware security modules and certificate-based authentication. Welding automation vendors face the steepest compliance costs due to real-time seam-tracking data transmission requirements.
Japanese manufacturers now unbundle hardware procurement from lifecycle service agreements. Automotive tier-one suppliers in Aichi Prefecture purchase articulated arms through capital expenditure budgets while contracting predictive maintenance separately. This bifurcation pressures traditional system integrators to restructure pricing transparency and performance guarantees.
Japan Articulated Robot Market Segmentation
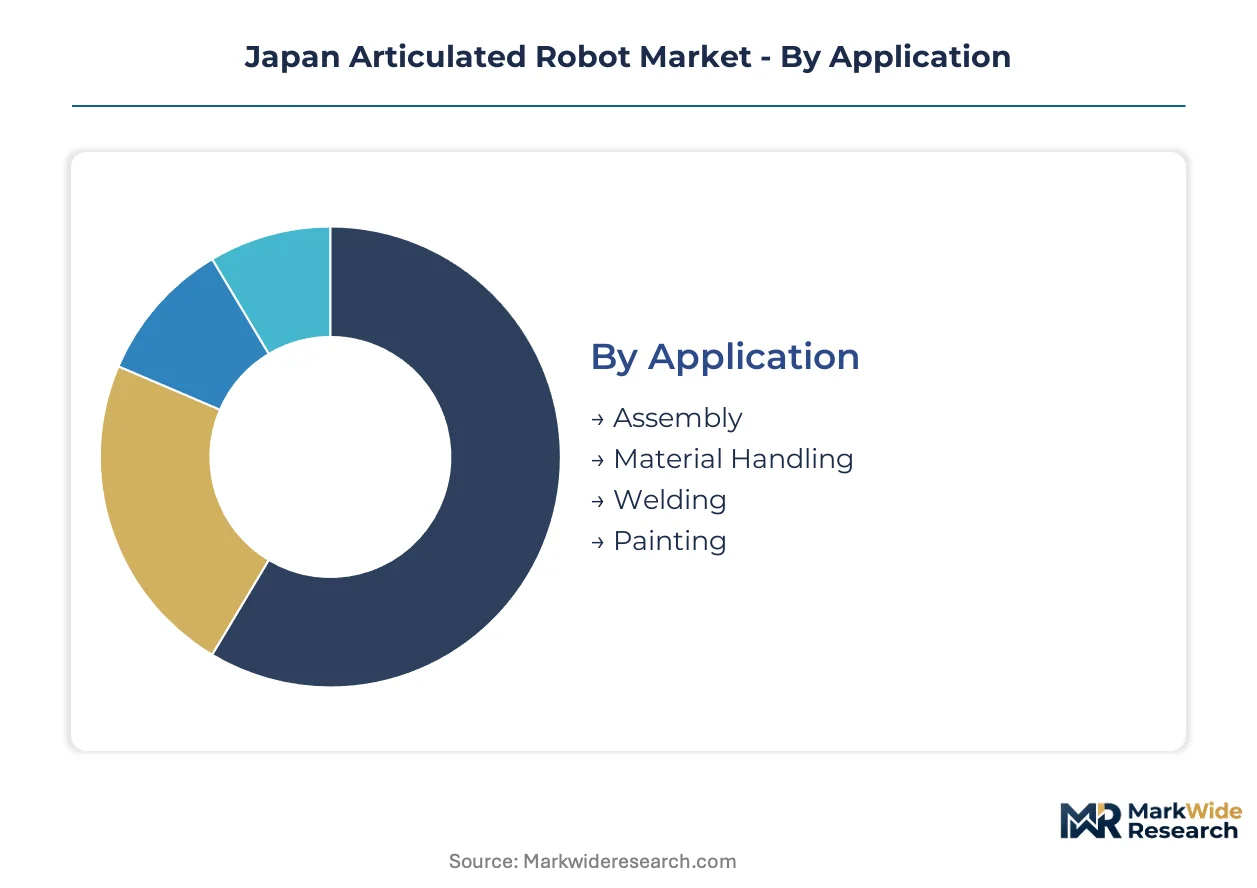
Articulated robot procurement in Japan stratifies sharply between standalone capital purchases and deeply embedded production systems. Segment boundaries determine vendor selection criteria, service contract structures, and compliance pathways under METI's industrial frameworks.
Application:
Standalone deployments dominate in low-integration environments where robots execute discrete tasks without upstream process coupling. Embedded systems require seamless coordination with conveyors, vision stations, and quality gates.
- Material Handling:Palletizing and machine tending applications utilize six-axis arms with vacuum or mechanical grippers for repetitive pick-and-place cycles. Toyota and Nissan battery plants in Aichi Prefecture specify force-limited end effectors for cell module transfer operations under METI carbon efficiency mandates.
- Welding:Arc and spot welding configurations integrate torch-mounted seam-tracking sensors with real-time trajectory correction algorithms. Automotive body shops in Kanagawa Prefecture drive specification demand for synchronized multi-robot cells handling complex joint geometries.
- Assembly:Precision insertion tasks for electronics and automotive components employ compliance-controlled motion.
- Painting:Explosion-proof manipulators with atomizer integration serve automotive and appliance finishing lines.
Volume placements concentrate in Material Handling; the faster expansion belongs to Welding as EV architectures multiply joint complexity requirements.
End User:
Cost tier stratification separates mass-production automotive buyers from mid-volume electronics and batch-process pharmaceutical operators. Procurement sophistication varies dramatically across these tiers.
- Automotive Manufacturers:Tier-one suppliers and OEMs deploy synchronized robot fleets exceeding fifty units per facility with centralized cell controllers. New EV battery assembly lines in Toyota City and Oppama require sub-millimeter repeatability for cell stacking and module welding under PMDA-adjacent quality protocols.
- Electronics Producers:High-mix, low-volume assemblers in Osaka Prefecture specify compact six-axis arms with vision-guided flexibility for miniaturized component placement. AI-integrated solutions are climbing the fastest as product lifecycles compress below eighteen months.
- Pharmaceuticals:Cleanroom-validated stainless steel robots serve aseptic fill-finish operations with ISO 14644-1 Class 5 compatibility.
- Food Processing:Washdown-rated manipulators with IP67 protection handle primary and secondary packaging tasks.
Revenue concentration sits with Automotive Manufacturers; steepest expansion trajectory belongs to Pharmaceuticals as biologics manufacturing scales domestically.
Technology:
Maturity differentiation separates proven traditional architectures from emerging collaborative and AI-augmented platforms. Safety certification burdens and integration complexity create distinct adoption timelines.
- Traditional Robots:Caged six-axis designs with proprietary controllers dominate high-speed, high-payload operations in established automotive facilities. Fanuc and Yaskawa captive production of servo motors and amplifiers sustains margin control across Nagoya industrial clusters.
- Collaborative Robots:Power-and-force-limiting arms enable fenceless human-robot coexistence for SMEs with limited safety infrastructure. Electronics subcontractors in Saitama Prefecture access METI Society 5.0 subsidies covering installation costs, gaining share fastest among technology categories.
- AI-Driven Solutions:Deep learning-based path planning and defect detection merge with articulated motion control.
- Autonomous Mobile Robots:Articulated manipulators mounted on mobile platforms extend reach across unstructured factory environments.
Installed base dominance remains with Traditional Robots; Collaborative Robots capture the steepest adoption curve as workforce constraints intensify.
Solution:
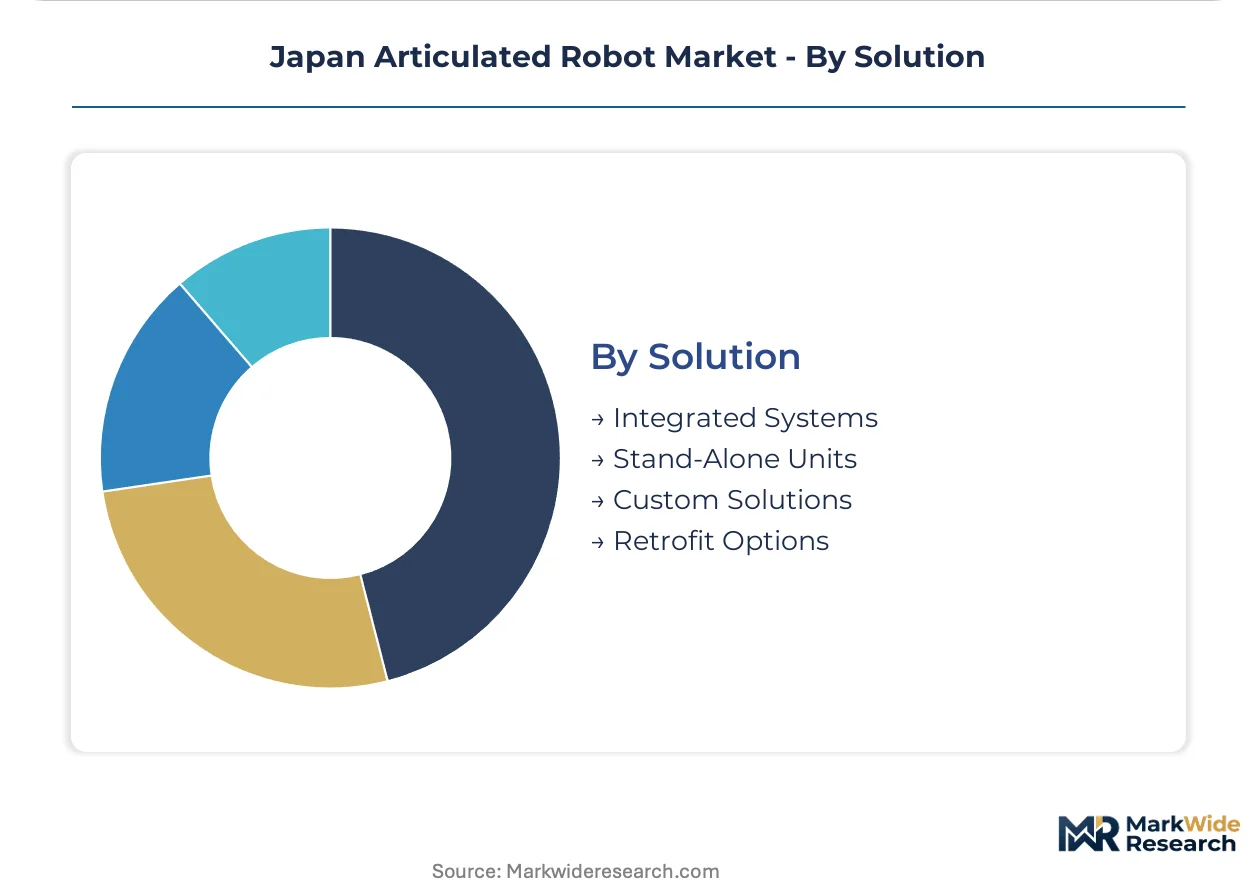
Supply concentration around integrated system providers versus component vendors shapes procurement risk profiles and lifecycle cost structures.
- Integrated Systems:Turnkey cells combining robot arms, controllers, end effectors, and safety enclosures reduce in-house engineering requirements. Automotive tier-one suppliers in Aichi Prefecture favor single-source accountability for throughput guarantees and predictive maintenance contracts.
- Stand-Alone Units:Robot arm purchases separate from peripheral integration allow capital expenditure flexibility for engineering-capable buyers. Mid-tier electronics assemblers in Kanagawa Prefecture self-integrate with existing PLC architectures, though proprietary fieldbus protocols from 2000s-era systems obstruct seamless data exchange.
- Custom Solutions:Application-specific configurations address non-standard payload or reach requirements.
- Retrofit Options:Controller upgrades and energy-efficient motor replacements extend 1990s-era fleet service life.
Revenue weighting favors Integrated Systems; Retrofit Options expand most quickly as aging Nagoya automotive installations face METI efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan manufactures substantially more articulated robots than it deploys domestically, with export volumes concentrated in Southeast Asian automotive markets. Domestic absorption concentrates in the Kanto industrial corridor where METI's Society 5.0 subsidies accelerate smart factory retrofits.
Kanto Region
Toyota and Nissan EV battery assembly lines in Tokyo, Kanagawa, and Saitama prefectures drive precision torque-controlled robot demand. METI Green Growth Strategy subsidies cover installation costs for SMEs adopting fenceless collaborative systems. The Keihin industrial belt hosts dense concentrations of electronics subcontractors piloting AI-vision integration for miniaturized component handling.
Chubu Region
Nagoya automotive clusters anchor heavy-payload material handling deployments across Aichi Prefecture body shops. JIS B 8433 functional safety certification requirements extend procurement cycles for tier-one suppliers retrofitting 1990s-era Fanuc R-2000 series units. Toyota City facilities specify synchronized multi-robot cells with centralized controllers for complex joint geometries in EV architectures.
Kansai Region
Osaka electronics assemblers deploy compact six-axis arms for high-mix, low-volume production with compressed product lifecycles. METI Industrial Cybersecurity Framework mandates encrypted EtherCAT communication for new installations. The Osaka-Kobe manufacturing corridor concentrates demand for power-and-force-limiting cobot designs enabling human-robot coexistence without physical guarding.
Kyushu Region
Semiconductor backend houses in Kumamoto pilot deep learning-based defect detection merged with real-time path correction for die bonding operations. PMDA cleanroom validation protocols constrain market entry for non-domestic suppliers in biologics fill-finish applications. The region's pharmaceutical manufacturing expansion drives specification demand for ISO 14644-1 Class 5 compatible stainless steel robots.
Tohoku Region
Automotive component suppliers in Miyagi Prefecture absorb servo motor cost fluctuations from neodymium-iron-boron price volatility tied to Chinese export quotas. Earthquake risk in Shizuoka manufacturing clusters threatens component availability for regional integrators. Sendai-based engineering firms face acute mechatronics talent scarcity as kinematic calibration expertise concentrates among engineers aged 55-plus.
Japan Articulated Robot Market Key Industry Players
The competitive structure tilts toward integrated system providers with captive component production. Three domestic vendors control over two-thirds of servo amplifier manufacturing, creating supply-side concentration around Nagoya and Yamanashi production clusters. Strategic archetypes separate full-stack robot OEMs from specialized welding automation vendors and collaborative platform specialists. Dominant competitive moves include lifecycle service agreement unbundling from hardware procurement and predictive maintenance contract expansion for aging fleet retrofits.
Within the full-stack tier, Fanuc Corporation and Yaskawa Electric Corporation anchor positions through in-house production of servo motors and CNC controllers. Kawasaki Heavy Industries occupies a distinct position in heavy-payload material handling for automotive body shops. These three entities exemplify the integrated manufacturing archetype that sustains margin control from component through system level, while mid-tier entrants face JIS B 8433 certification burdens extending 14-18 months for collaborative platforms.
| Leading Market Players |
|---|
| Fanuc Corporation |
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Kawasaki Heavy Industries |
| Nachi-Fujikoshi Corp |
| Kawada Robotics Corporation |
| Panasonic Corporation |
| Shibaura Machine Co., Ltd. |
| Omron Corporation |
| Others |
Cost & Logistics Intelligence
Direct-drive torque motor adoption across Japanese semiconductor handling lines simultaneously compresses gearbox maintenance costs and consolidates supplier relationships around captive flexspline manufacturers with JIS-certified cleanroom production. This mechanical simplification cascades through controller architectures while concentrating procurement power among integrated system providers with in-house servo motor production.
Pricing Analysis
Price erosion across traditional six-axis configurations traces to unbundling of hardware procurement from lifecycle service agreements, with automotive tier-one suppliers in Aichi Prefecture now purchasing robot arms through capital expenditure budgets while contracting predictive maintenance separately. Pricing stratifies across integrated turnkey cells, stand-alone units for self-integration, and retrofit packages for aging fleet upgrades. Buyers in the electronics subcontractor base exhibit highest price sensitivity due to compressed product lifecycles below eighteen months, while pharmaceutical operators accepting PMDA validation protocols demonstrate lowest sensitivity given cleanroom compatibility requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand across Toyota and Nissan facilities, while system integrators serve mid-tier electronics assemblers in Osaka and Kanagawa prefectures. Component manufacturing concentrates in Japan's Nagoya and Yamanashi production clusters for servo amplifiers, with neodymium-iron-boron magnet supply drawing from Chinese export quotas. Single-source vulnerability in Shizuoka manufacturing clusters threatens component availability following seismic events. Distribution runs through captive production networks for full-stack vendors and third-party integrators for specialized welding and collaborative platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's articulated robot sector sits at a technology-transition inflection where AI-vision convergence and collaborative platforms displace legacy caged architectures across SME manufacturing bases.
For Market Incumbents: Acquire kinematic calibration and servo tuning expertise through targeted recruitment or specialist firm purchase to address mechatronics talent scarcity concentrated among engineers aged 55-plus. Secure backward integration into rare earth magnet supply through long-term offtake agreements with Chinese suppliers to mitigate neodymium-iron-boron price volatility. Defend against mid-tier collaborative robot entrants by accelerating JIS B 8433 certification cycles below the standard 14-18 month window.
For New Entrants and Emerging Players: Enter via pharmaceutical cleanroom applications where PMDA validation protocols favor domestically manufactured stainless steel robots with ISO 14644-1 Class 5 compatibility, creating barriers for non-domestic suppliers. Target biologics fill-finish operations in Kyushu as the fastest-expanding specification demand segment. Pursue METI Society 5.0 subsidy alignment for fenceless cobot installations in Saitama Prefecture electronics subcontractors.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-stack robot OEMs seeking AI-vision capabilities or collaborative platform technology. Long-term viability favors integrated manufacturers with captive servo motor production sustaining margin control from component through system level. Watch for inflection in retrofit contract volumes signaling aging fleet replacement cycles across Nagoya automotive clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Vision Platform Integration | Merges deep learning defect detection with real-time path correction for die bonding in Kumamoto semiconductor backend houses. |
| Collaborative Robot Certification Acceleration | Compresses JIS B 8433 functional safety validation cycles below 14 months to capture SME fenceless deployment demand. |
| Pharmaceutical Cleanroom Validation | Secures PMDA-compliant stainless steel robot supply for biologics fill-finish expansion in Kyushu manufacturing corridors. |
| Rare Earth Magnet Supply Agreement | Locks neodymium-iron-boron pricing through long-term Chinese offtake to protect servo motor margin structures. |
| Predictive Maintenance Service Unbundling | Separates lifecycle contracts from hardware procurement to match automotive tier-one buyer capital expenditure preferences in Aichi Prefecture. |
Research Approach
Multi-period observation of METI subsidy disbursement patterns, JIS B 8433 certification timelines, and collaborative robot installation rates anchored the trend analysis, supplemented by interviews with plant engineers at automotive tier-one suppliers, maintenance directors at Nagoya body shops, procurement leads at Osaka electronics assemblers, and aftermarket service heads at system integrators. Secondary validation drew from METI industrial statistics, PMDA validation protocol filings, customs records for servo motor component trade, and SEC disclosures from listed robot manufacturers. Bottom-up unit deployment estimates triangulated against top-down manufacturing value-added projections.
Segment-weighting across application categories, end-user industries, technology platforms, and solution types informed the analytical framework throughout the projection horizon. CAGRs derived from installed base growth rates, replacement cycle acceleration, and EV battery assembly line expansion trajectories. Forecast inputs incorporated rare earth magnet price elasticity, Society 5.0 subsidy uptake curves, and semiconductor capital expenditure cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese export quota disruptions, seismic events in Shizuoka manufacturing clusters, or delays in JIS B 8433 certification cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
France Cloud Robotics Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Palletizing Robots Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Commercial Robots Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Intelligent Parcel Delivery Lockers Market