
 Solar Panel Cleaning Robot Market | 2026-2036
Solar Panel Cleaning Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Cleaning Robot Market Insights
Market Context
The EU Green Deal is consolidating procurement criteria around solar asset efficiency, compelling operators to automate cleaning cycles. Ecoppia leverages dry-electrostatic technology to eliminate water use in desert installations. Boson Robotics sustains competitive advantage through AI-driven terrain adaptation for uneven panel arrays. SolarCleano anchors European market presence with compact units designed for rooftop commercial segments.
Technical Definition and Segments
Solar panel cleaning robots are electromechanical systems equipped with brush assemblies, vacuum extraction, or electrostatic films, typically operating at 0.5–2.5 meters per second across photovoltaic surfaces to restore transmittance degraded by soiling. Fully automated systems command premium positioning due to labor substitution in remote utility installations, while semi-automated variants retain share where capital constraints persist among commercial end users. Sensor-based technology leads deployment volume through lower unit complexity, though AI-powered navigation is gaining traction where terrain variability demands path optimization.
Regulatory Frame
The EU F-Gas Regulation and REACH compliance frameworks constrain solvent-based cleaning chemistries, indirectly favoring robotic dry-cleaning adoption across European solar portfolios. Saudi Arabia's national renewable energy regulator mandates performance ratio guarantees that incentivize frequent, automated maintenance. Stakeholders must weigh water-scarcity exposure against automation capex when selecting between hybrid and fully automated product architectures.
Market Dynamics
Water scarcity across desert solar belts is compressing the competitive window for wet-cleaning alternatives, forcing operators toward dry-electrostatic and brush-based autonomous systems that eliminate consumables entirely.
Growth Catalysts
- EU F-Gas Regulation:Solvent-based cleaning chemistries face phase-down mandates, redirecting European solar portfolios toward robotic dry-cleaning architectures that bypass chemical compliance burdens entirely.
- Performance ratio guarantees:Saudi Arabia's national renewable energy regulator mandates output thresholds that penalize soiling losses, compelling gigawatt-scale desert operators to automate maintenance frequencies.
- Brush assembly innovation:Microfiber and electrostatic film technologies now restore transmittance without water, opening deployment in water-stressed solar corridors from Rajasthan to Atacama.
Market Restraints
- Capital intensity:Fully automated systems require upfront investment multiples exceeding semi-automated variants, excluding capital-constrained commercial rooftop operators from premium-tier adoption.
- Supply concentration:Brush assembly and sensor component manufacturing clusters in East Asian electronics corridors expose procurement timelines to single-source vulnerability.
- Technical limitation:Terrain variability on uneven panel arrays degrades navigation accuracy for sensor-based units, limiting addressable market share where ground settlement or tracking misalignment prevails.
Strategic Opportunities
- Underpenetrated rooftop commercial:Compact unit architectures designed for distributed generation sites remain underserved relative to utility-scale deployments, offering white space for form-factor specialization.
- AI-path optimization convergence:Integration of machine learning with brush kinematics enables adaptive cleaning pressure and speed modulation, differentiating premium offerings in variable-soiling environments.
- Outcome-based service models:Performance-linked contracts that guarantee transmittance restoration levels shift buyer risk profiles and extend vendor revenue visibility across multi-year asset lifecycles.
Industry Challenges
- Skill scarcity in mechatronics:Field maintenance of autonomous systems requires cross-functional expertise spanning robotics, photovoltaics, and desert-environment engineering that remains concentrated in narrow talent pools.
- Certification timeline compression:IEC 61215 and IEC 61730 compliance pathways for cleaning robot-to-panel contact interfaces lag product development cycles, delaying commercialization in regulated European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Cleaning Robot Market |
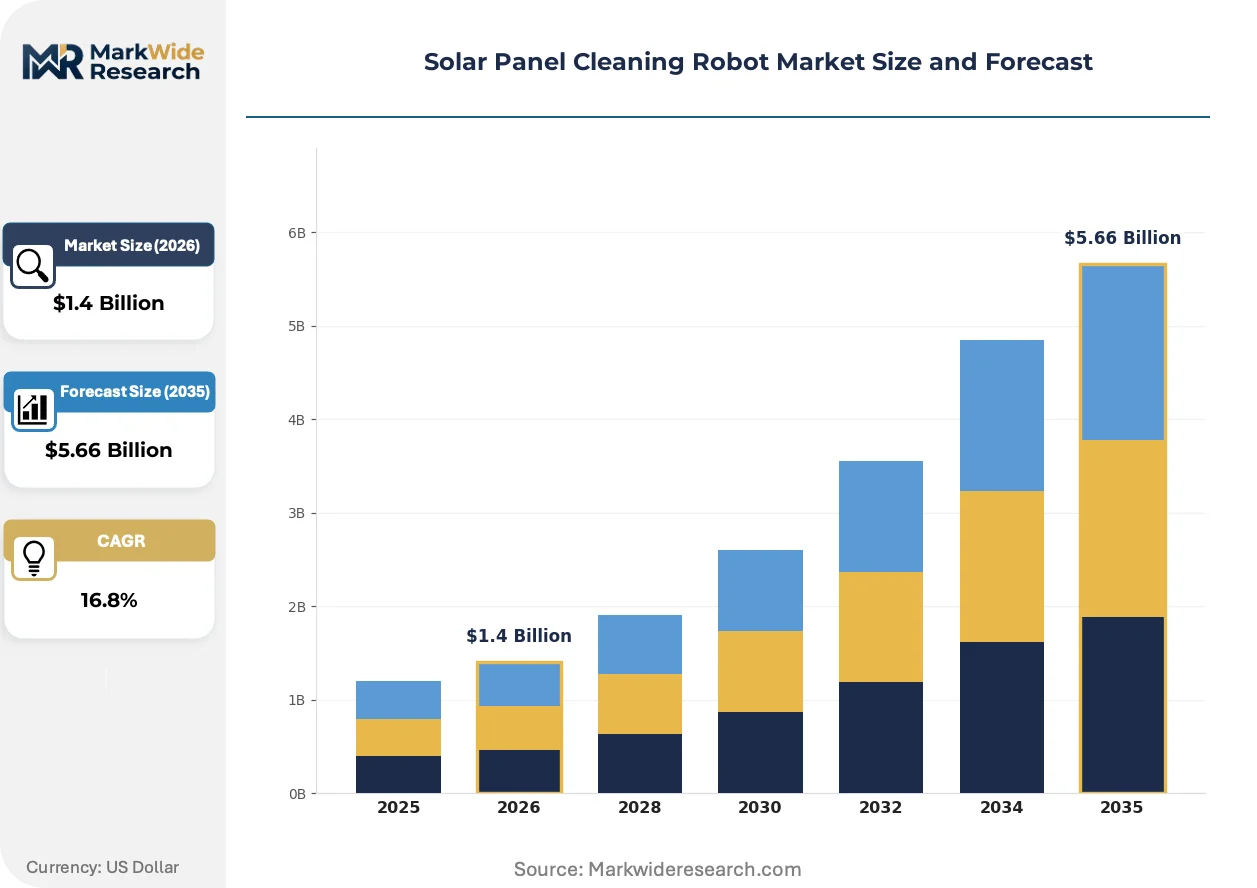
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $5.66 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automated, Semi-Automated, Manual, Hybrid Technology: Robotic Arm, Autonomous Navigation, AI-Powered, Sensor-Based End User: Residential, Commercial, Industrial, Utility Service Type: Installation, Maintenance, Consulting, Support |
| Companies Covered | Ecoppia, Boson Robotics, SolarCleano, SunBrush mobil, BladeRanger, hyCLEANER, Hecsolar, AirTouch Solar, Sunbotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Cleaning Robot Market Trends and Innovations
Dry-electrostatic cleaning architectures are displacing water-dependent systems across water-stressed solar corridors, while regulatory chemistry bans and procurement model evolution reshape competitive positioning.
Electrostatic film technology is consolidating its position as the dominant waterless cleaning modality for desert utility installations. Saudi Aramco's renewable energy division and Neom gigawatt projects have standardized on these systems for dust-prone environments. The technology is consolidating supplier margins by eliminating consumables logistics and reducing operational expenditure structures to energy and labor alone.
REACH and EU F-Gas Regulation constraints on solvent chemistries are redirecting European solar asset operators toward robotic dry-cleaning procurement. The industrial consequence is a compliance-driven technology lock-in that disadvantages wet-cleaning service incumbents. Utility-scale portfolios in Spain and Italy are responding with accelerated autonomous system tenders that explicitly exclude chemical-based alternatives.
Buyer contracting is pivoting from capital equipment purchase toward performance-guaranteed service agreements. Distributed generation operators and commercial rooftop aggregators are displacing outright ownership with transmittance-level contracts. This shift is most visible in Germany's Mittelstand manufacturing sector, where energy cost pressures favor operational expenditure models over balance-sheet robot deployment.
Solar Panel Cleaning Robot Market Segmentation
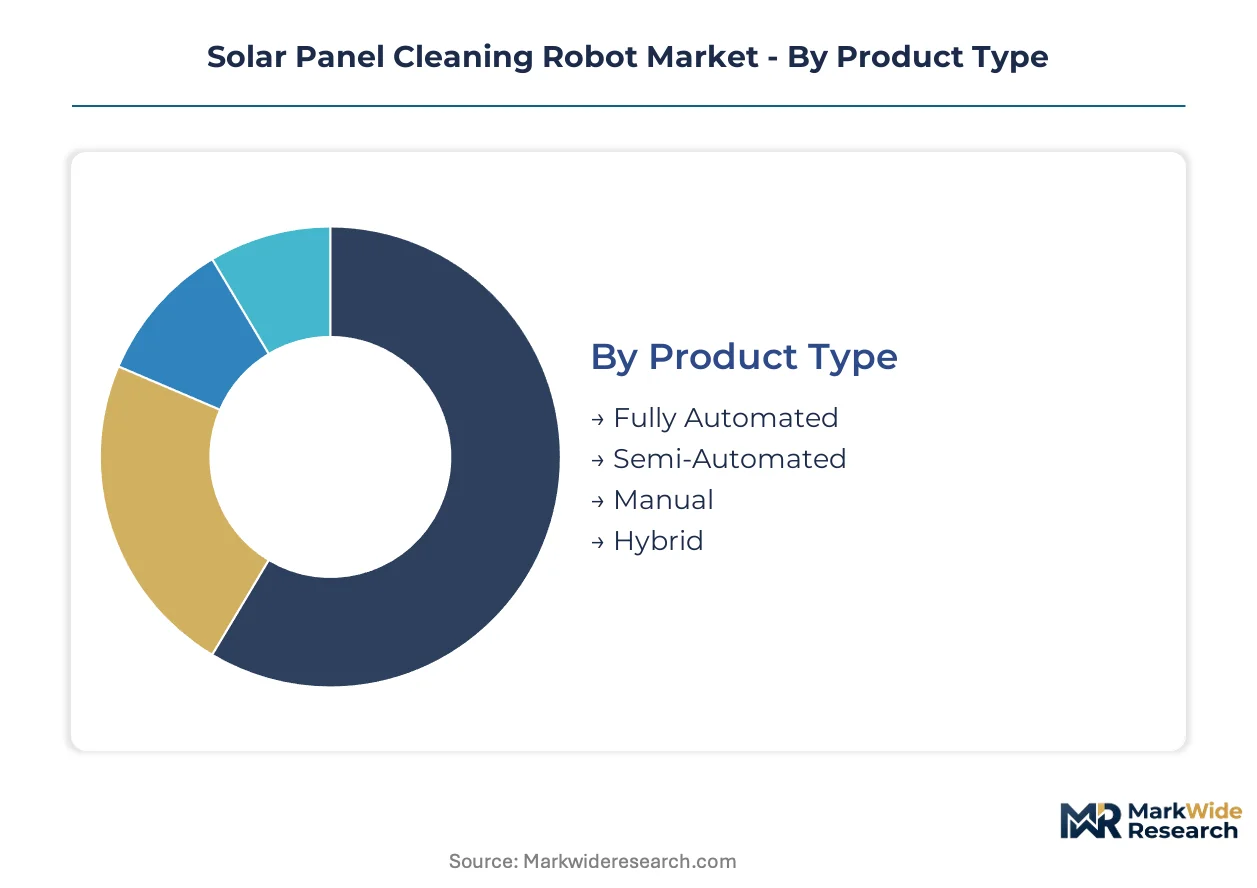
Segmentation in solar panel cleaning robots reveals how automation depth, intelligence layers, and procurement models split addressable demand across divergent buyer capabilities and site constraints. Each dimension carries distinct margin profiles and vendor specialization requirements.
Product Type:
Fully automated systems operate as standalone deployments requiring no human intervention during cleaning cycles, while semi-automated and hybrid architectures embed into existing maintenance workflows with varying degrees of operator involvement.
- Fully Automated:Self-propelled units with onboard power, navigation, and debris handling operate across utility-scale arrays without tethering. Demand concentrates in Saudi Arabia's gigawatt desert installations where labor costs and dust frequency make continuous autonomous operation essential. The EU Green Deal's tightening performance ratio requirements accelerate procurement in Spanish and Italian utility portfolios.
- Semi-Automated:Operator-supervised platforms reduce physical labor while retaining human oversight for path planning and obstacle response. Commercial rooftop aggregators in Germany's Mittelstand manufacturing belt favor this tier where capital constraints limit full automation deployment but labor substitution remains valuable.
- Manual:Hand-guided cleaning tools with motorized brush attachments serve residential installations and small commercial sites below the automation threshold.
- Hybrid:Systems switching between autonomous and manual modes address variable terrain conditions where full automation risks panel damage.
Volume placements concentrate in Semi-Automated systems; the faster expansion belongs to Fully Automated.
Technology:
Technology segmentation tracks the intelligence stack depth from basic sensor feedback through predictive path optimization, with cost and capability expanding across each tier.
- AI-Powered:Machine learning algorithms adapt brush pressure, speed, and cleaning patterns to soiling density maps built from historical performance data. Rajasthan's utility operators deploy these systems where dust composition varies seasonally and predictive maintenance extends asset life.
- Sensor-Based:Lidar, ultrasonic, and optical sensors enable obstacle detection and edge-following without predictive capabilities. This tier dominates current deployment volume due to lower unit complexity and faster certification timelines under IEC standards.
- Robotic Arm:Articulated manipulators reach fixed-tilt and tracking arrays from centralized service vehicles, common in concentrated solar power plants with elevated mirror structures.
- Autonomous Navigation:GPS-denied positioning systems using visual SLAM operate in repetitive grid patterns without AI adaptation, serving uniform panel layouts.
Sensor-Based units claim the largest installed base; AI-Powered configurations are climbing the fastest as terrain variability demands rise.
End User:
End user segmentation separates capital intensity, procurement sophistication, and performance guarantee requirements across the solar asset ownership spectrum.
- Utility:Gigawatt-scale operators with dedicated O&M budgets and long-term power purchase agreements drive premium-tier automation. Neom and Saudi Aramco renewable divisions mandate electrostatic dry-cleaning to meet water-scarcity constraints and performance ratio guarantees.
- Commercial:Distributed generation portfolios and rooftop aggregators balance automation capex against energy cost pressures. Outcome-based service contracts are displacing equipment ownership in this tier.
- Industrial:On-site solar installations at manufacturing facilities prioritize uptime and integration with existing maintenance schedules over maximum cleaning frequency.
- Residential:Single-system owners represent minimal automation penetration due to panel count economics, retaining manual and semi-automated tool demand.
Utility deployments absorb the highest unit volumes; Commercial segment expansion is steepest as service models mature.
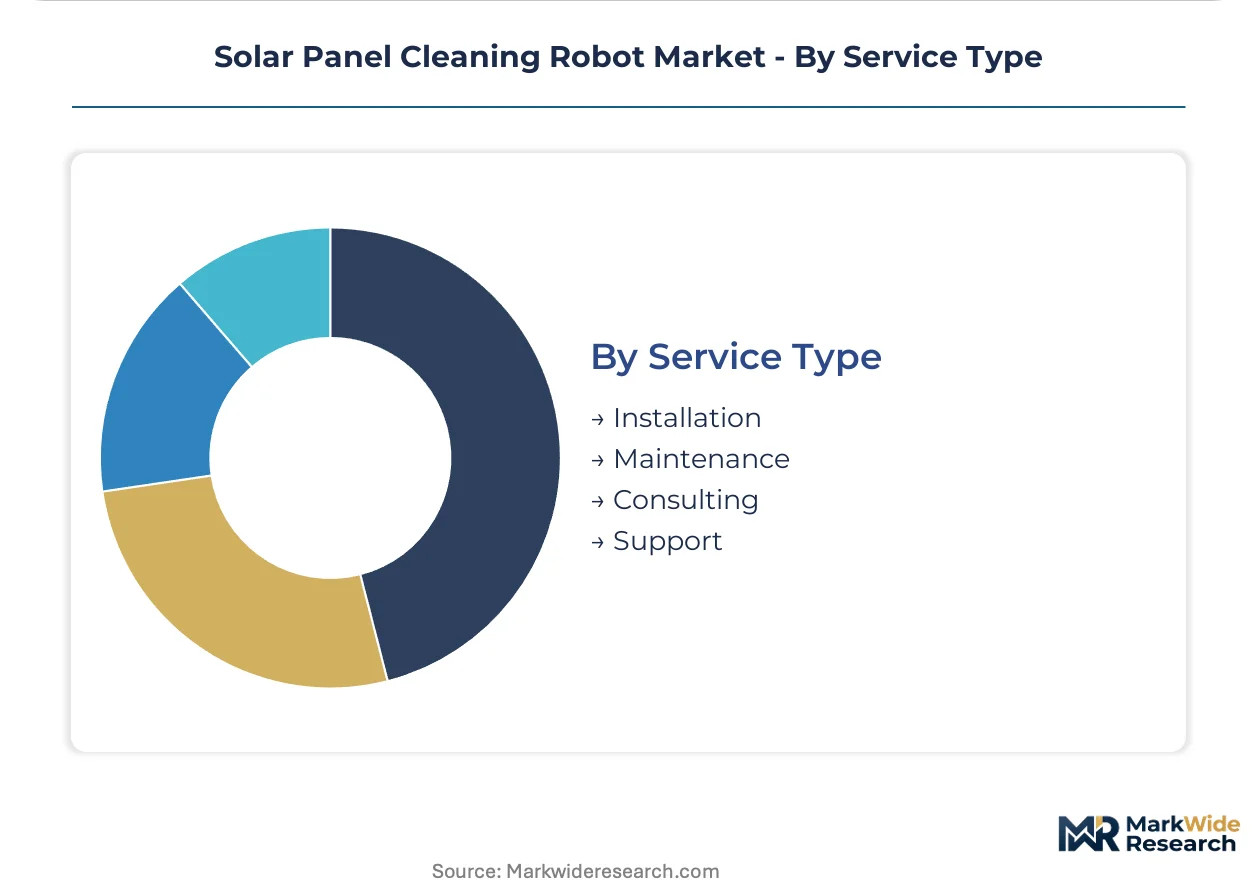
Service Type:
Service segmentation captures the shift from capital equipment transactions toward recurring revenue relationships and performance accountability.
- Installation:Site assessment, mounting system integration, and commissioning of robotic infrastructure. This segment concentrates in new-build utility projects across the Atacama and Middle East desert belts.
- Maintenance:Scheduled servicing, component replacement, and software updates extend operational life. EU F-Gas Regulation compliance adds complexity to European maintenance protocols.
- Consulting:Soiling analysis, cleaning frequency optimization, and technology selection advisory for operators navigating water-scarcity and automation trade-offs.
- Support:Remote monitoring, troubleshooting, and spare parts logistics complete the service envelope.
Installation revenue dominates current service flows; Maintenance contracts are gaining share fastest as installed base expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's gigawatt-scale desert installations command the highest density of autonomous cleaning robot deployments, with Neom and Saudi Aramco renewable divisions establishing procurement templates that ripple across Middle Eastern solar corridors.
Saudi Arabia
Neom's gigawatt projects and Saudi Aramco's renewable division drive concentrated demand for waterless cleaning systems. The national renewable energy regulator mandates performance ratio guarantees that penalize soiling losses. Riyadh-based operators are standardizing on electrostatic dry-cleaning architectures to meet water-scarcity constraints.
Spain
Utility-scale portfolios in Andalusia and Extremadura accelerate autonomous system tenders to meet EU Green Deal performance standards. The EU F-Gas Regulation phases down solvent-based cleaning chemistries, redirecting operators toward robotic dry-cleaning procurement. Seville's solar corridor hosts the densest concentration of automated maintenance deployments in Southern Europe.
Germany
Mittelstand manufacturing belt aggregators favor outcome-based service contracts over equipment ownership. The EU Green Deal tightens efficiency requirements for distributed generation assets. Bavaria's commercial rooftop clusters represent the fastest-expanding addressable base for compact cleaning units.
India
Rajasthan's utility operators deploy adaptive systems where dust composition varies seasonally across the Thar Desert. The Ministry of New and Renewable Energy prioritizes performance-linked maintenance standards for national solar missions. Jaipur-Ajmer industrial corridor installations require frequent automated cleaning cycles during pre-monsoon dust accumulation periods.
United States
California's utility-scale desert installations in the Mojave and Imperial Valley face water-use restrictions that favor dry-cleaning alternatives. The Inflation Reduction Act extends tax credit eligibility to solar asset maintenance automation. Kern County solar farms represent the densest concentration of robotic cleaning trials outside the Middle East.
Solar Panel Cleaning Robot Market Competitive Landscape
The competitive structure tilts toward technology-specialist archetypes with differentiated cleaning modalities rather than diversified industrial conglomerates. Sensor-based and AI-powered navigation capabilities split the vendor base into capability tiers. Three archetypes dominate: dry-electrostatic specialists eliminating water dependency, brush-assembly innovators optimizing transmittance restoration, and compact-form-factor designers targeting distributed generation sites. Geographic expansion through regional service partnerships and technology licensing for local manufacturing represent the dominant competitive moves.
Among Israeli technology developers, Ecoppia and AirTouch Solar exemplify the dry-electrostatic archetype with waterless cleaning architectures purpose-built for desert utility installations. Ecoppia occupies a position as the reference supplier for Saudi gigawatt-scale deployments. Boson Robotics, with its Chinese nomenclature structure, represents the AI-powered navigation tier where terrain adaptation differentiates premium offerings. BladeRanger anchors the European specialist segment with Belgium-origin positioning in compact unit design for commercial rooftop applications.
| Leading Market Players |
|---|
| Ecoppia |
| Boson Robotics |
| SolarCleano |
| SunBrush mobil |
| BladeRanger |
| hyCLEANER |
| Hecsolar |
| AirTouch Solar |
| Sunbotics |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price volatility cascades through brush motor and battery pack costs, compressing margins for mid-tier robot manufacturers while premium electrostatic specialists pass through value-based premiums to desert utility operators in Saudi Arabia and Spain.
Pricing Analysis
Transmittance-restoration guarantees anchor value-based pricing for fully automated desert installations. Three-tier pricing structure across premium AI-powered, standard sensor-based, and economy semi-automated levels separates Ecoppia's electrostatic systems from Boson Robotics' terrain-adaptive units and compact European rooftop variants. Pricing pressure stems from East Asian component cost compression and buyer consolidation around performance-linked service contracts. Commercial rooftop aggregators in Germany exhibit highest price sensitivity; Saudi Aramco renewable divisions show lowest.
Supply Chain Analysis
Brush assembly and sensor component manufacturing rests on Chinese, South Korean, and Taiwanese electronics corridors. Lithium-ion battery packs, microfiber cleaning films, and precision servo motors feed from East Asian suppliers. Single-source vulnerability in brush motor controllers exposes procurement timelines to disruption. Distribution runs through regional EPC contractors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar panel cleaning robot sector sits in a technology-transition phase where dry-electrostatic architectures displace water-dependent legacy systems across water-stressed solar belts from the Atacama to Rajasthan.
For Market Incumbents: Cement dominance in Saudi gigawatt-scale deployments through backward integration into electrostatic film manufacturing, insulating margins from raw material volatility. Deepen certification investment under IEC 61215 contact-interface standards to delay European competitive entry. Counter emerging AI-navigation entrants by locking multi-year performance-guaranteed contracts with Neom and Saudi Aramco renewable divisions. For New Entrants and Emerging Players: Capture white space in Germany's Mittelstand commercial rooftop segment where outcome-based service models displace equipment ownership. Penetrate Rajasthan's seasonal dust-variability installations with adaptive AI-powered systems. Pursue technology licensing partnerships with Indian EPC contractors for localized brush assembly production. For Investors and Strategic Acquirers: Distressed-cycle entries favor electrostatic-technology specialists with Saudi deployment track records during capital-constrained financing windows. Long-term viability hinges on water-scarcity intensification across solar corridors and regulatory chemistry bans tightening in Europe. Watch for EU F-Gas Regulation enforcement acceleration as inflection signal for dry-cleaning procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electrostatic Film Manufacturing Integration | Captures margin from consumables elimination in Saudi desert installations. |
| AI-Path Optimization Platform Development | Differentiates premium offerings where Rajasthan dust composition varies seasonally. |
| Performance-Guaranteed Service Contract Expansion | Shifts German Mittelstand buyers from capex to opex procurement models. |
| Regional EPC Partnership Network | Accelerates Spanish utility-scale deployment under EU Green Deal standards. |
| IEC 61215 Contact Interface Certification | Unlocks regulated European market access for autonomous navigation systems. |
Research Methodology
Document review covered SEC filings from robotics manufacturers, EU regulatory impact assessments, and Middle East renewable energy procurement databases, complemented by interviews with utility O&M directors, EPC project developers, and solar asset managers. Secondary validation drew from Saudi renewable energy regulator mandates, EU F-Gas Regulation compliance frameworks, and customs data on brush motor imports. Bottom-up unit deployment estimates triangulated against top-down addressable solar capacity calculations.
Market size outputs reflect segment-level modeling across automation depth, intelligence tier, and procurement model dimensions throughout the forecast period. CAGRs derive from regression analysis of historical adoption curves in comparable industrial automation categories, adjusted for water-scarcity exposure and regulatory chemistry restriction intensity. Forecast inputs incorporate solar capacity build-out pipelines from Saudi Arabia, Spain, and India alongside electrostatic technology cost-down trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium supply constraints, EU regulatory enforcement timing, and desert solar project financing availability. Projections assume continued water-use restriction tightening and performance ratio guarantee standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Smart Lawn Robot Market