
 Articulated Robots for Injection Molding Machine Market | 2026-2036
Articulated Robots for Injection Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Articulated Robots for Injection Molding Machine Market Insights
Medical device manufacturing is repositioning articulated robots from automotive-dominant deployment toward cleanroom-compatible material handling and packaging operations. FANUC Corporation leverages its CNC heritage to sustain precision control in high-cycle injection molding cells. KUKA AG anchors European automation demand through deep integration with Engel Austria GmbH machine platforms. Yaskawa Electric Corporation dominates Asian supply chains with force-controlled handling systems for delicate medical components.
Articulated robots for injection molding machines are multi-axis manipulators with six or more rotary joints, typically offering payload capacities from 3 kg to 700 kg and repeatability within ±0.05 mm, designed to extract molded parts, perform secondary operations, and interface with downstream automation. Their primary purpose centers on reducing cycle times, ensuring consistent part quality, and eliminating manual intervention in high-volume polymer processing environments. Medium scale units lead installed base volumes across automotive tier suppliers, while collaborative variants represent the fastest-expanding category as manufacturers seek fenceless human-robot collaboration in mixed-model production. Vision systems technology commands premium positioning where inline quality control replaces offline inspection stations, compressing total process time.
ISO 10218 governs robot safety design and integration requirements, while the EU Machinery Directive mandates conformity assessment for automated production systems entering European markets. The US Occupational Safety and Health Administration enforces lockout and safeguarding protocols that influence robot cell architecture and retrofit economics. China's national GB standards for industrial robot safety create parallel compliance obligations for suppliers serving domestic molders. Stakeholders must monitor evolving collaborative robot certification pathways and energy efficiency regulations that will determine next-generation product development priorities and regional market access conditions.
Market Dynamics
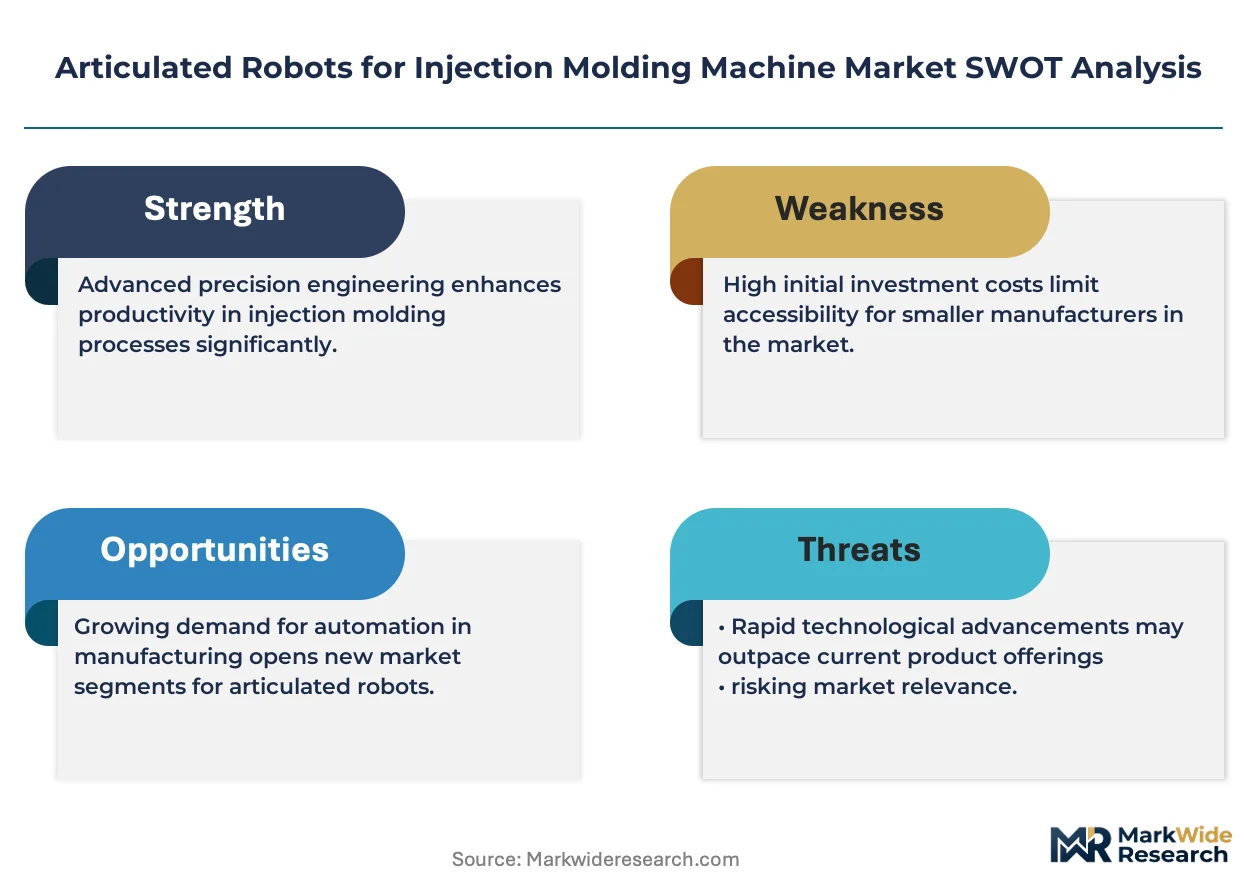
Force-controlled handling systems are compressing cycle times in medical component production while ISO 10218-2 compliance costs reshape capital deployment timelines for tier suppliers.
Growth Catalysts
- EU Machinery Directive conformity mandates:Automated production systems entering European markets must complete conformity assessment, accelerating replacement of legacy unguarded cells with certified articulated platforms.
- Automotive lightweighting programs:OEMs deploy six-axis extractors for carbon fiber-reinforced polymer handling where manual intervention risks fiber damage.
- Cleanroom-compatible robotics:ISO 14644-1 Class 7 and 8 medical molding facilities adopt stainless steel variants with sealed joints for sterile packaging operations.
Market Restraints
- Servo motor and harmonic drive cost volatility:Rare earth magnet supply concentration in Chinese processing facilities creates input price instability for precision actuator assemblies.
- Integration complexity with legacy PLCs:Proprietary communication protocols in aging injection molding machines demand costly middleware development for seamless robot coordination.
- Substitution by Cartesian systems:Three-axis linear modules capture simple extraction tasks below 5 kg payload where six-axis flexibility remains underutilized.
Strategic Opportunities
- India PLI scheme for medical devices:Production-linked incentives for domestic manufacturing create first-mover advantage for cleanroom robot suppliers establishing local assembly.
- Vision-guided bin-picking convergence:3D structured light systems paired with force-torque sensors enable unsorted component handling without dedicated fixture investment.
- Remanufacturing service channels:Certified rebuild programs for end-of-life FANUC and KUKA units unlock secondary market revenue in cost-sensitive Southeast Asian molders.
Industry Challenges
- Collaborative robot safety certification delays:ISO/TS 15066 pilot-to-full standard transition creates timeline uncertainty for fenceless cell deployments.
- Multi-generational control architecture integration:EtherCAT-to-DeviceNet protocol bridging demands specialized automation engineering talent scarce in Central European manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Articulated Robots for Injection Molding Machine Market |
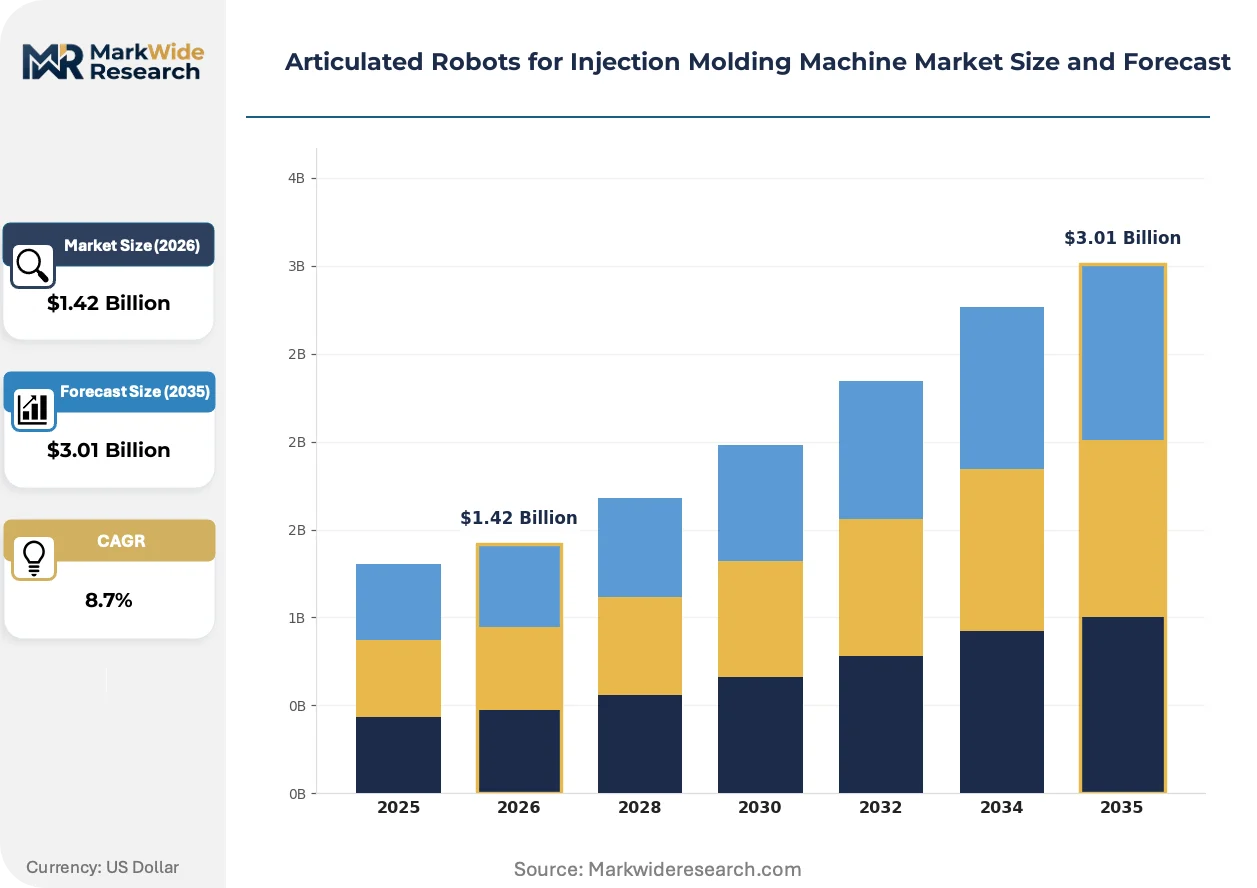
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Scale, Medium Scale, Large Scale, Collaborative End User: Aerospace, Automotive OEMs, Consumer Electronics, Medical Devices Technology: Vision Systems, Force Control, AI Integration, Automation Software Application: Assembly, Material Handling, Quality Control, Packaging |
| Companies Covered | ABB Ltd, FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, Kawasaki Heavy Industries Ltd, Sepro Group, Engel Austria GmbH, Wittmann Battenfeld Group, Star Seiki Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Articulated Robots for Injection Molding Machine Market Trends and Innovations
Digital twin simulation is compressing commissioning timelines while predictive maintenance algorithms shift service revenue from reactive to subscription models.
AI-powered vision systems with embedded edge computing are overtaking traditional template-matching approaches in inline defect detection. Tier-one automotive suppliers deploy these systems at 50-millisecond cycle synchronization. Quality control labor is compressing as vision-guided robots handle dimensional verification without dedicated metrology stations.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing lubricant reformulation in food-contact molding applications. European machinery builders accelerate dry-running joint designs to eliminate grease contamination risks. Medical packaging OEMs in Germany and Switzerland prioritize certified PFAS-free robot variants for regulatory pre-compliance.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts. Mold makers in Japan now procure spare parts through direct manufacturer portals rather than distributor networks. Component-level pricing transparency is most advanced in automotive supply chains where total cost of ownership modeling dominates vendor selection.
Articulated Robots for Injection Molding Machine Market Segmentation
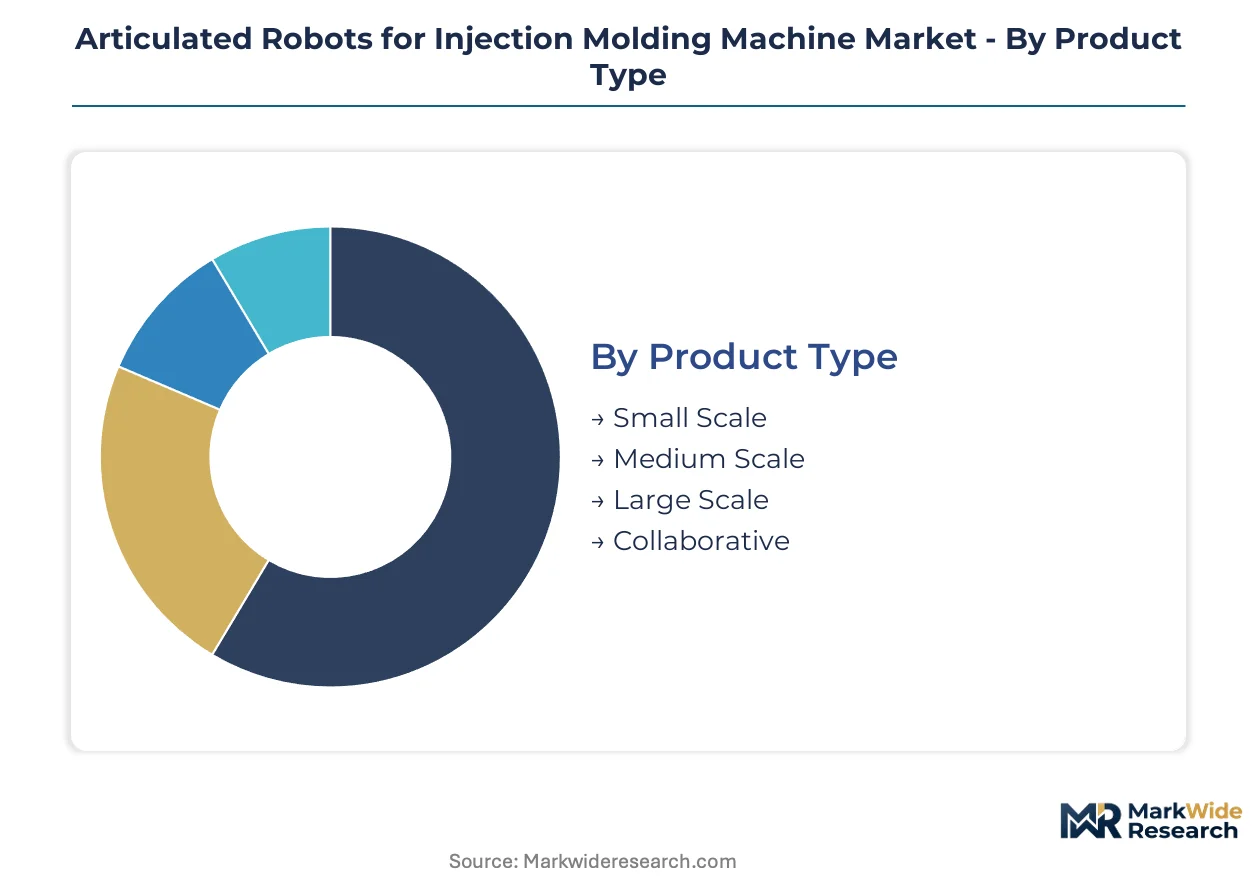
Articulated robot specification varies sharply with cycle time demands and cleanroom requirements across injection molding operations. Segment selection determines capital recovery timelines and regulatory compliance pathways for molders expanding automation.
Product Type:
Replacement cycles accelerate as legacy pneumatic extractors face EU Machinery Directive conformity deadlines.
- Medium Scale:Six-axis units with 20-200 kg payload dominate automotive tier supplier installations. BMW and Volkswagen Group contract molders in Germany and China favor these units for bumper and dashboard extraction where reach and repeatability balance capital cost.
- Collaborative:Fenceless cobot variants with force-limited joints and ISO/TS 15066 certification enable mixed-model cells. Medical device manufacturers in Switzerland and Japan deploy these for sterile packaging where human intervention remains necessary.
- Small Scale:Compact 3-10 kg payload units serve consumer electronics micro-molding in Shenzhen and Seoul clusters.
- Large Scale:Heavy-duty 300-700 kg systems handle automotive structural foam and appliance cabinet extraction.
Volume placements concentrate in Medium Scale; the faster expansion belongs to Collaborative.
End User:
Customer procurement patterns diverge between cost-driven automotive tier suppliers and margin-protected medical device OEMs.
- Automotive OEMs:Lightweighting programs demand carbon fiber-reinforced polymer handling where six-axis flexibility prevents fiber damage. Stellantis and Toyota Motor Corporation specify force-controlled extraction for Class A surface components.
- Medical Devices:ISO 14644-1 Class 7 cleanroom mandates drive stainless steel robot adoption. Becton Dickinson and Baxter International contract manufacturers prioritize sealed-joint designs for sterile packaging validation.
- Consumer Electronics:High-mix, low-volume production in Taiwan and Vietnam favors rapid-changeover collaborative cells.
- Aerospace:Thermoplastic composite handling for interior panels and ducting requires specialized ESD protection and extended reach configurations.
Procurement scale peaks with Automotive OEMs; Medical Devices command the steepest expansion trajectory.
Technology:
Technology selection tracks the shift from mechanical fixturing toward adaptive, sensor-driven handling architectures.
- Vision Systems:3D structured light and embedded edge computing enable unsorted bin-picking without dedicated fixtures. Tier-one automotive suppliers achieve 50-millisecond cycle synchronization for inline dimensional verification.
- Force Control:Six-axis force-torque sensing protects delicate medical components during extraction and transfer. Yaskawa Electric Corporation dominates this segment in Asian supply chains.
- AI Integration:Machine learning defect classification reduces false-positive rates in quality control applications.
- Automation Software:Digital twin commissioning and predictive maintenance platforms compress deployment timelines and shift service revenue to subscription models.
Deployment density clusters on Vision Systems; AI Integration gains share fastest.
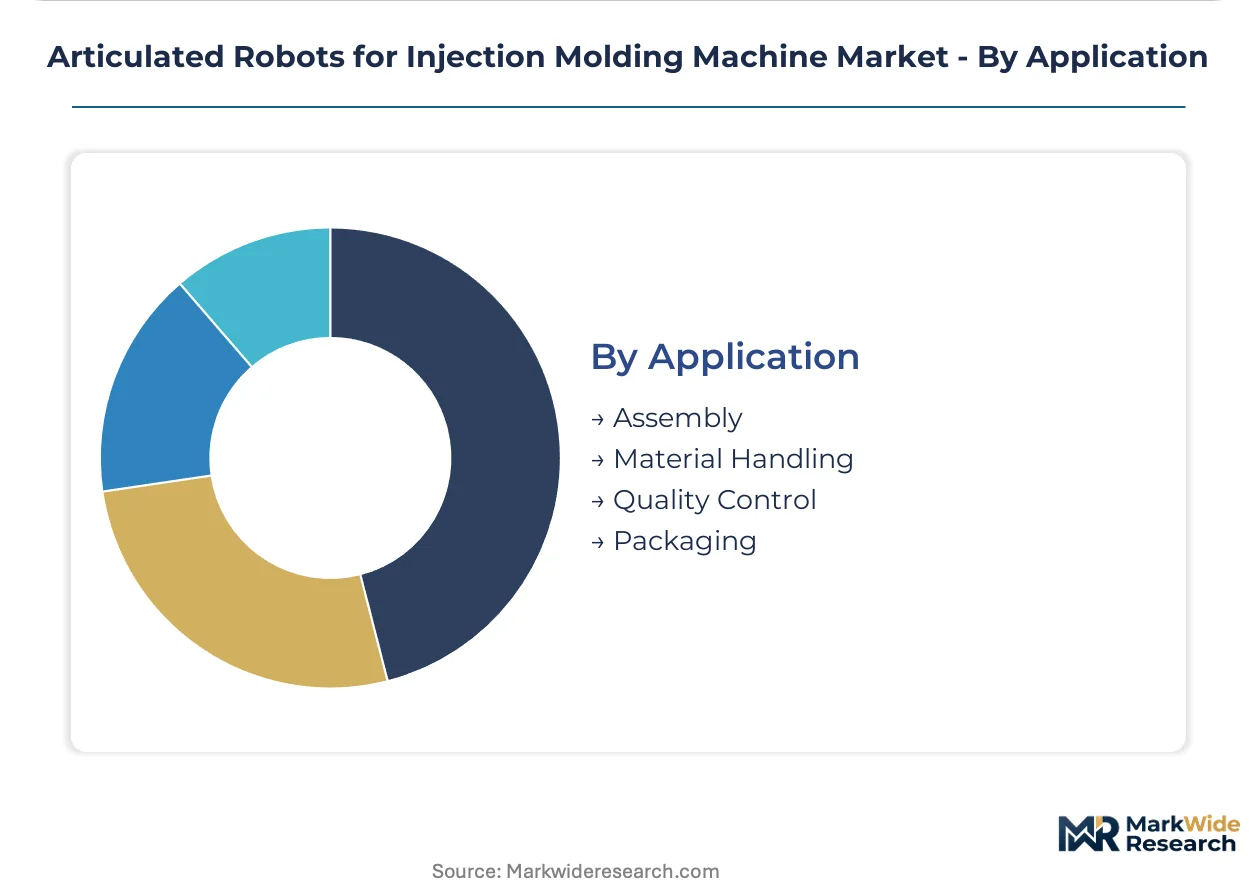
Application:
Application mix reflects the progression from simple extraction toward fully integrated downstream automation.
- Material Handling:Core extraction and transfer operations remain the installed base majority. FANUC Corporation and KUKA AG compete on cycle time optimization for high-volume automotive production.
- Quality Control:Vision-guided dimensional verification replaces offline metrology stations. Inline inspection compresses total process time and reduces WIP inventory.
- Assembly:Insert molding and overmolding operations require precise insert placement and core handling.
- Packaging:End-of-line bagging, boxing, and palletization for medical and food-contact applications demands PFAS-free lubricant certification.
Material Handling anchors current volumes; Quality Control climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in China and India's PLI corridors are concentrating articulated robot deployment for injection molding automation. Germany's Industrie 4.0 clusters and Japan's precision manufacturing belts sustain premium demand. Mexico's IMMEX program accelerates nearshoring of automotive component molding.
China
Carbon fiber-reinforced polymer demand from BYD and NIO drives six-axis extractor procurement in Shenzhen and Ningbo molding clusters. MIIT's GB standards for industrial robot safety mandate conformity assessment for domestic suppliers. Yangtze River Delta concentration centers on medical device packaging automation for export markets.
Germany
BMW and Volkswagen Group lightweighting programs consume medium-scale units for bumper and dashboard extraction. EU Machinery Directive conformity deadlines force replacement of legacy pneumatic systems in Baden-Württemberg supplier parks. Stuttgart-Tübingen corridor hosts the densest concentration of Engel-integrated automation cells.
Japan
Force-controlled handling systems for delicate medical components dominate Yaskawa's domestic order book. METI's JIS standards for collaborative robot safety shape fenceless cell architecture in Osaka pharmaceutical molding. Nagoya automotive belt sustains FANUC's precision control heritage in high-cycle production.
United States
OSHA lockout and safeguarding protocols influence robot cell architecture for tier-one automotive suppliers in Michigan and Ohio. FDA cleanroom requirements for medical device packaging drive stainless steel variant adoption in Massachusetts and Minnesota. Texas petrochemical corridor expands large-scale structural foam extraction for appliance manufacturing.
India
PLI scheme production-linked incentives for domestic medical device manufacturing create first-mover opportunities in Maharashtra and Gujarat. CDSCO regulatory alignment pressures cleanroom validation standards for sterile packaging operations. Chennai automotive supplier parks pilot collaborative cells for mixed-model component production.
Articulated Robots for Injection Molding Machine Market Competitive Landscape
Top-tier vendors anchor precision automation for automotive and medical tiers, while mid-scale specialists serve regional molders with standardized extraction platforms. The vendor base clusters around CNC heritage, European machine integration, and Asian supply chain dominance. Three archetypes define competitive positioning: precision control heritage players, machine-builder-integrated suppliers, and force-sensing specialists. Strategic moves concentrate on digital twin service unbundling and PFAS-free lubricant certification for regulatory pre-compliance.
Among Japanese precision automation houses, FANUC Corporation and Yaskawa Electric Corporation exemplify divergent specialization vectors—CNC-derived cycle optimization versus force-controlled medical handling. KUKA AG occupies the European integration tier through its machine-platform alignment with Engel Austria GmbH. These three anchors represent the structural competition between heritage control systems, force-sensing architectures, and deep machine integration.
| Leading Market Players |
|---|
| ABB Ltd |
| FANUC Corporation |
| KUKA AG |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries Ltd |
| Sepro Group |
| Engel Austria GmbH |
| Wittmann Battenfeld Group |
| Star Seiki Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive servo motor production in Japanese and German manufacturing clusters anchors pricing power for precision actuator assemblies, insulating tier-one vendors from rare earth magnet volatility while forcing spot-market-dependent competitors into margin compression. This integration choice separates premium-positioned FANUC and KUKA units from price-competitive Asian challengers sourcing harmonic drives through distributor networks.
Pricing Analysis
Lead-time-driven pricing stratification rewards short-cycle delivery commitments with premium positioning, particularly for EU Machinery Directive-certified cells facing conformity assessment deadlines. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10218-2 compliance grade and after-sales service bundling intensity. Cost compression in standard-tier units intensifies because Chinese suppliers are flooding Southeast Asian markets with unbundled hardware. Automotive tier suppliers exhibit highest price sensitivity, while medical device OEMs prioritize PFAS-free lubricant certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing facilities concentrating neodymium magnet supply for servo motors. Precision actuator assembly draws from Japan, Germany, and China, with harmonic drive gearheads sourcing primarily from HDSI in Japan and domestic Chinese alternatives. Tariff exposure runs through US-China trade restrictions on industrial automation components. Distribution runs through Engel-integrated machine-builder channels in Europe and direct manufacturer portals penetrating Japanese mold-making clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over servo motor and harmonic drive supply determines margin sustainability. Players pursuing backward integration into precision gearhead manufacturing secure cost structures unavailable to assembly-only competitors.
For Market Incumbents: Cement control over cleanroom-certified stainless steel variant supply through captive forging partnerships in Switzerland and Germany. Cartesian system substitution for sub-5 kg extraction tasks threatens medium-scale unit volumes; defend through force-control technology bundling that linear modules cannot replicate. Prioritize PFAS-free lubricant certification investment ahead of REACH restriction finalization to lock medical packaging OEM procurement specifications.
For New Entrants and Emerging Players: AI-powered vision systems with embedded edge computing offer technology-first entry into quality control applications where incumbents lack software-native architectures. India's PLI scheme corridors for medical device manufacturing represent the most penetrable geography, with CDSCO regulatory alignment creating barrier-protected niches. Pursue hospital system partnership go-to-market angles bypassing traditional distributor markups in Maharashtra and Gujarat clusters.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated automation specialists with digital twin service revenue exceeding hardware margins. Long-term viability across the analysis window hinges on software subscription attach rates and predictive maintenance algorithm performance. Watch ISO/TS 15066 full standard publication as inflection indicator for collaborative robot certification timelines and fenceless cell deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Lubricant Certification | REACH pre-compliance locks medical packaging OEM procurement specifications ahead of restriction enforcement. |
| Digital Twin Service Unbundling | Predictive maintenance subscriptions shift FANUC and KUKA revenue from reactive repair to recurring software models. |
| India PLI Corridor Assembly | Local production qualifies cleanroom robot suppliers for CDSCO-aligned medical device manufacturing incentives. |
| Vision-Guided Bin-Picking Integration | 3D structured light convergence with force-torque sensing eliminates dedicated fixture investment for high-mix molders. |
| Remanufacturing Service Channel | Certified rebuild programs unlock secondary market revenue in cost-sensitive Vietnamese and Indonesian molding clusters. |
Research Methodology
Document review covered customs/trade data from injection molding machinery import registries, complemented by interviews with plant engineers at automotive tier suppliers, biomedical engineers at medical device contract manufacturers, aftermarket service heads at European automation distributors, and procurement leads at Engel-integrated machine platforms. Secondary validation drew from SEC filings of listed automation vendors, MIIT GB standard publications, EU Machinery Directive conformity assessment databases, and IHS Markit industrial robot installation tracking. Bottom-up unit placement estimates triangulated against top-down market value reconstruction across product type, end user, technology, and application dimensions.
Historical shipment trajectories cross-referenced against panel input from automation OEM sales directors and molding cell integrators informed the analytical framework across the projection horizon. Segmentation modeling incorporated payload capacity tier, cleanroom certification grade, force-control architecture presence, and regional regulatory cluster alignment. CAGRs were derived from curve-fitting approaches applied to disclosed vendor backlog data and machine-builder order intake patterns, with medical device automation intensity and automotive lightweighting program commitments serving as primary demand-side inputs.
Several conditions sit outside the modeled scope, including abrupt rare earth export restrictions, ISO/TS 15066 standard revision delays, and unanticipated collaborative robot safety incident liability rulings. Forecasts reflect documented assumptions about polymer processing cycle time compression rates and medical packaging validation timeline norms. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Commercial Robots Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Internet of Robotic Things Market