
 Rotary Gripper Module Market | 2026-2036
Rotary Gripper Module Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Gripper Module Market Analytics
Japanese precision component producers is shifting capacity toward compact electric rotary gripper modules for semiconductor handling. Festo Corporation leverages its pneumatic heritage to anchor European factory automation channels. SCHUNK GmbH & Co. KG dominates collaborative robot end-effector integration with its modular jaw systems. ZIMMER GROUP specializes in customized vacuum and mechanical gripper combinations for automotive tier-one suppliers.
A rotary gripper module integrates rotational actuation with grasping functionality, typically achieving angular displacements of 90 to 180 degrees through rack-and-pinion or direct-drive mechanisms to orient and transfer workpieces within automated cells. Parallel grippers lead unit shipments due to standardized jaw interfaces across automotive and electronics sectors, while electric motor actuation captures expanding margin pools as manufacturers replace pneumatic infrastructure for energy efficiency and programmable force control. Pneumatic actuation sustains volume in food and beverage processing where washdown ratings and explosive atmosphere certifications remain prevalent.
The EU Machinery Directive and ISO 10218 shape product safety mandates for collaborative deployment, while FCC Part 15 governs electromagnetic emissions from integrated servo drives in US installations. Japan's METI circular economy guidelines are pressuring manufacturers to design gripper modules for disassembly and component reuse. Stakeholders must weigh electric actuation migration costs against long-term total cost of ownership advantages as energy pricing and carbon accounting intensify.
Market Dynamics
Electric actuation is automating rotary gripper module procurement as automotive and electronics manufacturers phase out pneumatic infrastructure to meet carbon accounting mandates and programmable force requirements.
Growth Catalysts
- EU Machinery Directive compliance:Collaborative robot deployments in Germany's Baden-Württemberg cluster require certified end-effectors, tightening safety specifications and expanding replacement demand.
- Semiconductor handling precision:Japanese producers are shifting capacity toward compact electric rotary grippers for wafer orientation in advanced packaging lines.
- Food and beverage washdown ratings:Explosive atmosphere certifications sustain pneumatic gripper volumes in processing facilities requiring IP69K-rated equipment.
Market Restraints
- Copper and rare-earth magnet costs:Electric servo motors depend on neodymium and copper windings, exposing margins to commodity volatility and supply concentration in Chinese processing.
- ISO 10218 certification timelines:Collaborative robot end-effector validation requires extensive third-party testing, extending product launch cycles by 8-14 months.
- Pneumatic infrastructure lock-in:Existing factory air compressor networks create switching costs that delay electric migration in established automotive plants.
Strategic Opportunities
- India's PLI scheme for automation:Production-linked incentives for electronics manufacturing are attracting gripper module suppliers to contract with mobile phone assembly contractors.
- Dual-carbon goals in China:National energy efficiency mandates are accelerating electric gripper adoption in export-oriented component factories.
- Convergence of servo drives and condition monitoring:Integrated torque sensing and predictive maintenance algorithms enable outcome-based service models for tier-one automotive suppliers.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of mechanical design, servo control, and safety software requires specialized talent concentrated in Stuttgart, Nagoya, and Detroit metro areas.
- Legacy PLC integration complexity:Electric grippers with advanced force control must interface with decades-old programmable logic controllers through protocol converters, increasing commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Gripper Module Market |
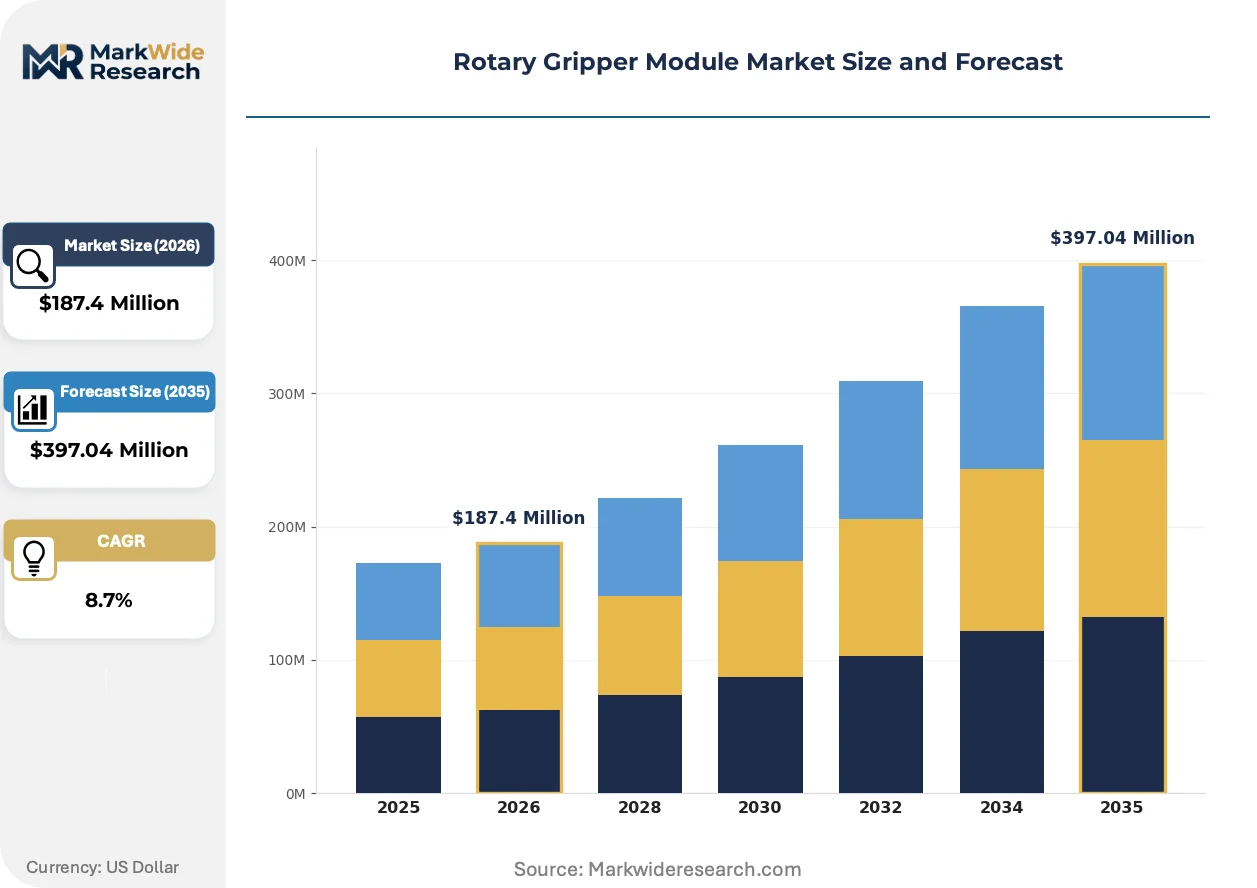
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angular Grippers, Parallel Grippers, Customized Grippers, Pneumatic Grippers Technology: Electric Motors, Pneumatic Actuation, Hydraulic Systems, Robotic Integration End User: Automotive Manufacturers, Electronics Producers, Food & Beverage Processors, Pharmaceutical Companies Application: Assembly Automation, Pick and Place, Material Handling, Quality Control |
| Companies Covered | Festo Corporation, SCHUNK GmbH & Co. KG, ZIMMER GROUP, Effecto Group S.P.A., PHD, Project Automation & Engineering GmbH, Perfecta Schneidemaschinenwerk GmbH, Advanced Gripper Innovations Inc, Dynamic Actuation Solutions Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Gripper Module Market Evolving Landscape
Direct-drive torque motors and integrated force-torque sensors are compressing rotary gripper form factors while enabling collaborative applications that were previously restricted to fenced automation cells.
Direct-drive rotary actuation is automating workpiece orientation in electric vehicle battery module assembly. Tesla's Gigafactory Berlin and Hyundai's Georgia Metaplant are specifying zero-backlash direct-drive units for tab welding positioning. This architecture eliminates rack-and-pinion maintenance while reducing cycle times in high-volume pouch cell handling.
Japan's METI circular economy guidelines are mandating design-for-disassembly in industrial equipment sold to domestic manufacturers. Gripper module producers must now document component separation procedures and material recovery pathways. European exporters to Japan are reformulating adhesive bonds and snap-fit enclosures to maintain market access.
Automotive tier-one suppliers are consolidating vendor relationships from component-level to subsystem-level procurement. Buyers now specify complete end-of-arm tooling packages rather than sourcing rotary grippers, vacuum generators, and force sensors separately. This pattern is most pronounced in Germany's automotive supply chain, where Continental and Bosch have reduced their pneumatic component vendors by 40 percent since 2022.
Rotary Gripper Module Market Segmentation
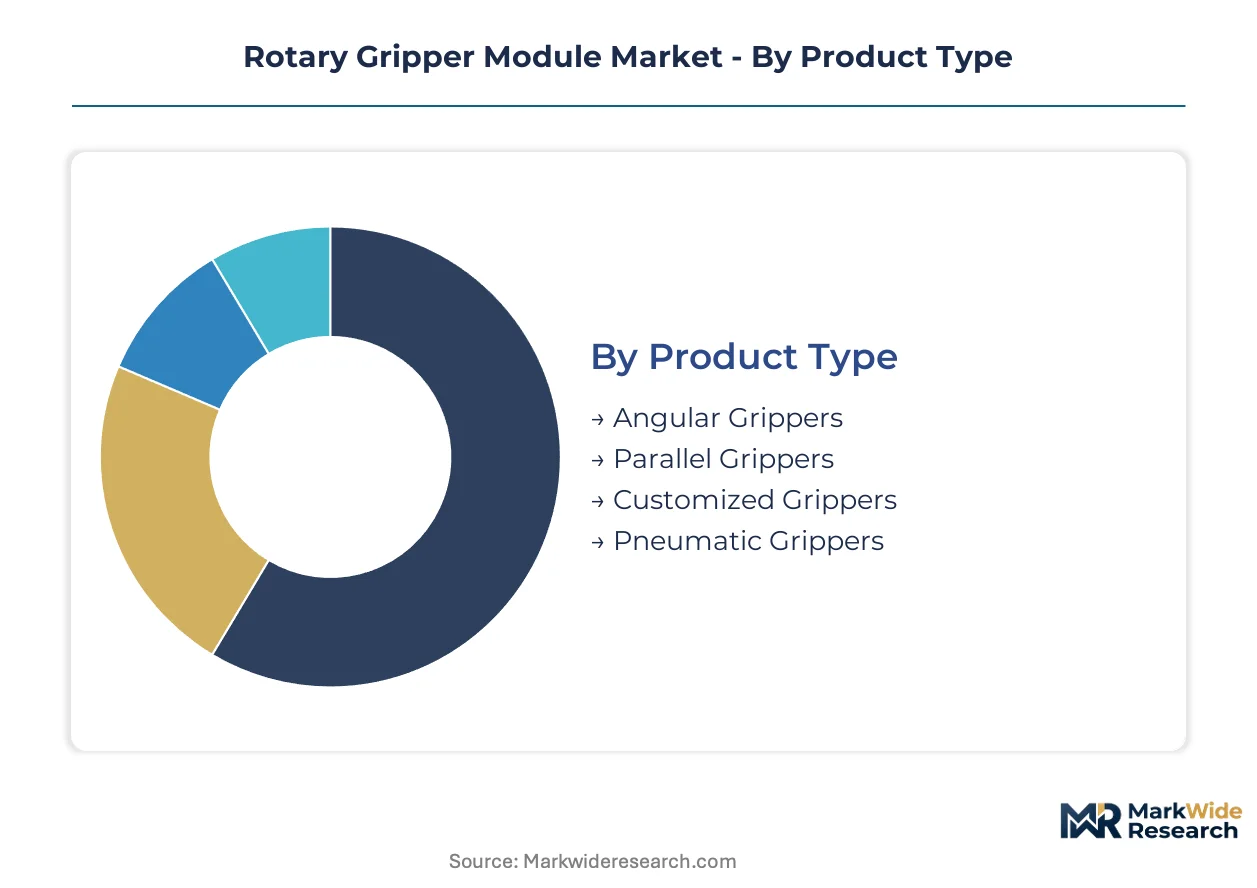
Rotary gripper module procurement varies sharply across technical specifications, actuation methods, and end-use environments. Buyers select configurations based on force precision requirements, washdown ratings, and integration complexity with existing automation infrastructure.
Product Type:
Mechanical jaw geometry determines gripping force distribution, cycle speed, and interchangeability with standardized tooling interfaces.
- Parallel Grippers:Two synchronized jaws move linearly to grasp workpieces from opposing sides. Automotive assembly lines in Germany's Baden-Württemberg cluster specify these for engine component handling where jaw quick-change systems reduce changeover downtime.
- Angular Grippers:Pivoting jaws converge at an angle to grip cylindrical or irregular geometries. Electronics manufacturers in Japan deploy compact angular variants for semiconductor wafer orientation where space constraints dominate cell design.
- Pneumatic Grippers:Compressed air drives piston-actuated jaw movement for high-speed repetitive cycles. Food and beverage processors favor these in washdown environments where IP69K ratings and explosive atmosphere certifications take precedence over energy efficiency.
- Customized Grippers:Application-specific jaw profiles and actuation configurations address unique workpiece geometries. Pharmaceutical companies commission these for aseptic handling of vials and syringes where standard interfaces risk contamination.
Parallel grippers lead on scale; customized grippers lead on momentum.
Technology:
Actuation architecture shapes energy consumption, force programmability, and maintenance intervals across deployment environments.
- Electric Motors:Servo-driven rotary actuation enables programmable torque curves and position feedback. Automotive manufacturers phase these in for electric vehicle battery module assembly to meet carbon accounting mandates and precision welding positioning requirements.
- Pneumatic Actuation:Compressed air systems deliver rapid cycle times with simple mechanical reliability. Food processing facilities retain these where existing compressor infrastructure and explosion-proof ratings outweigh electric migration benefits.
- Robotic Integration:Embedded servo drives and communication protocols enable direct robot controller interfacing. Collaborative robot deployments in Germany require ISO 10218-certified integration packages with force-limiting algorithms.
- Hydraulic Systems:Fluid power delivers extreme gripping forces for heavy workpiece handling. Foundry and metal forging applications specify these where pneumatic force proves insufficient.
Electric motors dominate new installations; robotic integration commands premium positioning.
End User:
Industry-specific regulatory pressures and production volumes dictate gripper specification priorities.
- Automotive Manufacturers:Tier-one suppliers consolidate procurement around complete end-of-arm tooling packages rather than discrete components. Electric vehicle assembly lines in Germany and the United States specify direct-drive rotary units for zero-backlash battery tab welding.
- Electronics Producers:Semiconductor packaging lines demand sub-millimeter positioning repeatability. Japanese producers shift capacity toward compact electric rotary grippers for advanced wafer handling in cleanroom environments.
- Food & Beverage Processors:Hygienic design and washdown compatibility override force precision. IP69K-rated pneumatic grippers sustain volumes where stainless steel construction and sealed housings prevent bacterial harborage.
- Pharmaceutical Companies:Regulatory compliance with FDA and EMA validation protocols drives specification. Aseptic processing applications require grippers with smooth surfaces, minimal particulate generation, and documented material traceability.
Automotive manufacturers anchor volume demand; electronics producers drive technology advancement.
Application:
Functional deployment context determines cycle time requirements, force control sophistication, and safety system complexity.
- Assembly Automation:Multi-step joining operations require coordinated rotary orientation and gripping force modulation. Electric vehicle battery module assembly integrates rotary grippers with torque sensing for precise tab alignment before welding.
- Pick and Place:High-speed transfer between stations prioritizes cycle time and reliability. Electronics surface-mount lines specify lightweight electric rotary grippers for component placement at sustained throughput rates.
- Material Handling:Bulk workpiece transport emphasizes payload capacity and durability. Automotive stamping facilities deploy heavy-duty pneumatic rotary grippers for sheet metal transfer between press stations.
- Quality Control:Inspection stations require gentle handling and precise orientation for sensor access. Pharmaceutical visual inspection systems use force-limited electric grippers to prevent vial damage during rotation.
Assembly automation captures the steepest expansion trajectory; pick and place sustains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting rotary gripper module procurement toward jurisdictions where EU Machinery Directive compliance costs less than the productivity gains from collaborative automation. Manufacturers exploit gaps between German certification rigor and emerging market incentive structures.
Germany
Baden-Württemberg's automotive automation cluster drives precision gripper demand for electric vehicle battery assembly. The EU Machinery Directive and ISO 10218 certification requirements tighten safety specifications for collaborative robot end-effectors. Stuttgart-based tier-one suppliers consolidate procurement around complete end-of-arm tooling packages, reducing pneumatic component vendors by 40 percent since 2022.
United States
Electric vehicle manufacturers specify direct-drive rotary grippers for zero-backlash battery tab welding at Tesla's Gigafactory Berlin and Hyundai's Georgia Metaplant. FCC Part 15 governs electromagnetic emissions from integrated servo drives in domestic installations. Detroit metro area engineering talent scarcity complicates mechatronics recruitment for advanced force-control integration.
Japan
Semiconductor packaging lines demand sub-millimeter positioning repeatability for wafer orientation in advanced packaging. METI circular economy guidelines mandate design-for-disassembly documentation for industrial equipment sold domestically. Nagoya-area precision component producers shift capacity toward compact electric rotary grippers for cleanroom handling applications.
China
National dual-carbon goals accelerate electric gripper adoption in export-oriented component factories seeking energy efficiency compliance. MIIT and GB standards shape local certification requirements for factory automation equipment. Yangtze River Delta manufacturing hubs integrate rotary grippers with legacy programmable logic controllers through protocol converters.
India
Production-linked incentive schemes for electronics manufacturing attract gripper module suppliers to contract with mobile phone assembly contractors. BIS standards and DGFT regulations govern industrial equipment import and certification. Karnataka and Tamil Nadu automation corridors concentrate demand from contract electronics manufacturers expanding capacity.
Rotary Gripper Module Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric actuation specialization and collaborative robot certification. The vendor base stratifies between pneumatic heritage manufacturers defending installed base and servo-drive specialists capturing new electric infrastructure deployments. Three archetypes dominate: diversified factory automation conglomerates, modular end-effector system integrators, and application-specific custom fabricators. Competitive moves center on subsystem-level procurement consolidation by automotive tier-ones and vertical integration into servo drive manufacturing.
Among German-based fabricators, Festo Corporation and SCHUNK GmbH & Co. KG exemplify contrasting strategic positions. Festo occupies a heritage-anchored role leveraging pneumatic expertise for European factory automation channels. SCHUNK represents the modular integration archetype dominating collaborative robot end-effector systems. ZIMMER GROUP sits within the customization tier, specializing in vacuum-mechanical gripper combinations for automotive supply chains. These three entities collectively illustrate the market's segmentation between standardized platforms and engineered-to-order solutions.
| Leading Market Players |
|---|
| Festo Corporation |
| SCHUNK GmbH & Co. KG |
| ZIMMER GROUP |
| Effecto Group S.P.A. |
| PHD |
| Project Automation & Engineering GmbH |
| Perfecta Schneidemaschinenwerk GmbH |
| Advanced Gripper Innovations Inc |
| Dynamic Actuation Solutions Inc |
| Others |
Value Network & Pricing Analysis
Captive in-house production of servo drives anchors pricing power for electric rotary gripper specialists while pneumatic heritage manufacturers defend margin pools through aftermarket service bundling. Tier-one automotive suppliers in Germany's Baden-Württemberg cluster exploit this supplier stratification to extract volume discounts on standardized parallel grippers while paying premiums for ISO 10218-certified collaborative robot integration packages.
Pricing Analysis
Distributor margin layers in European factory automation channels absorb 15-25 points before end-user pricing, while direct-to-OEM contracts for automotive tier-ones bypass intermediaries entirely. Three-tier pricing structure across premium ISO-certified, standard CE-marked, and economy non-certified levels separates collaborative robot deployments from conventional automation retrofits. Cost compression in economy pneumatic tiers intensifies because Chinese component factories flood spot markets with unbranded rack-and-pinion units. Contract electronics manufacturers in India's PLI corridors exhibit highest price sensitivity, whereas German automotive OEMs prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive tier-ones mandate multi-supplier qualification for neodymium magnets and copper windings, forcing electric gripper producers to maintain parallel relationships with Chinese rare-earth processors and Japanese magnet fabricators. Geographic supply concentration centers on China for permanent magnet materials, Germany for precision mechanical components, and Japan for compact servo drive electronics. Raw material dependencies rest on neodymium-iron-boron alloys, high-grade copper wire, and engineered aluminum housings. Single-source vulnerability in Chinese rare-earth processing exposes margins to export quota disruptions. Distribution runs through factory automation distributors in Europe, direct OEM contracts in automotive, and systems integrators in electronics manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotary gripper module procurement operates as a geographic-arbitrage play where EU Machinery Directive compliance costs in Germany exceed India's PLI scheme subsidies by a structural margin that reshapes supplier location decisions.
For Market Incumbents: Acquire servo drive engineering capabilities to capture electric actuation margin pools migrating from pneumatic infrastructure. Consolidate position in Germany's Baden-Württemberg cluster through subsystem-level procurement relationships with Continental and Bosch. Defend against emerging Chinese electric gripper specialists by accelerating ISO 10218 certification timelines for collaborative robot integration packages. For New Entrants and Emerging Players: Launch via direct contracting with India's contract electronics manufacturers under PLI scheme coverage, bypassing entrenched European distributor networks. Target semiconductor handling applications in Japan's Nagoya precision corridor where compact electric rotary gripper supply remains constrained. Penetrate through outcome-based service models bundling predictive maintenance algorithms with hardware deployment. For Investors and Strategic Acquirers: Roll-up economics work for modular end-effector system integrators because automotive tier-one vendor consolidation has reduced pneumatic component suppliers by 40 percent since 2022, creating acquisition targets with captive customer relationships. Long-term viability over a 5-10 year window favors electric actuation specialists with in-house servo drive production. Watch for inflection in copper and rare-earth magnet price volatility as signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Manufacturing | In-house production of torque motors captures margin pools migrating from pneumatic to electric actuation in German automotive. |
| ISO 10218 Certification Acceleration | Compressed validation timelines open collaborative robot end-effector procurement previously locked by 8-14 month testing cycles. |
| Design-for-Disassembly Compliance | METI circular economy documentation requirements in Japan create competitive moat for suppliers with material recovery pathways. |
| Subsystem-Level Procurement Consolidation | Complete end-of-arm tooling packages displace discrete component sales as Continental and Bosch reduce vendor counts. |
| Outcome-Based Service Model Launch | Integrated torque sensing with predictive maintenance algorithms enables recurring revenue from tier-one automotive suppliers. |
Research Methodology
Multiple input streams — primary interviews with factory automation procurement directors, plant engineers at automotive tier-ones, and semiconductor equipment specialists; secondary validation through customs trade data, EU Machinery Directive certification registries, and SEC filings from factory automation conglomerates; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Conversations with maintenance directors at food processing facilities, aftermarket service heads at pneumatic component distributors, and collaborative robot integration specialists provided operational context on washdown requirements and force-control deployment challenges.
Data-stream reconciliation across product type, actuation technology, end-user industry, and application function produced volume and value outputs throughout the forecast period. Segmentation dimensions modeled include mechanical jaw geometry, electric versus pneumatic actuation architecture, automotive versus electronics versus food processing end-use, and assembly automation versus pick-and-place deployment context. CAGRs were derived from installed base turnover rates, electric vehicle production ramp schedules, and carbon accounting mandate implementation timelines across major manufacturing jurisdictions.
Several conditions sit outside the modeled scope, including speculative breakthroughs in soft robotics gripping technology, abrupt shifts in EU carbon border adjustment mechanisms, and geopolitical disruptions to rare-earth magnet supply chains. Forecasts reflect assumptions about gradual pneumatic-to-electric migration pacing and stable certification timeline durations. Deviation in Chinese export quota policy for neodymium would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Europe Educational Robot Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Commercial Robotics Market