
 Smart Worker Market | 2026-2036
Smart Worker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Worker Market Analysis
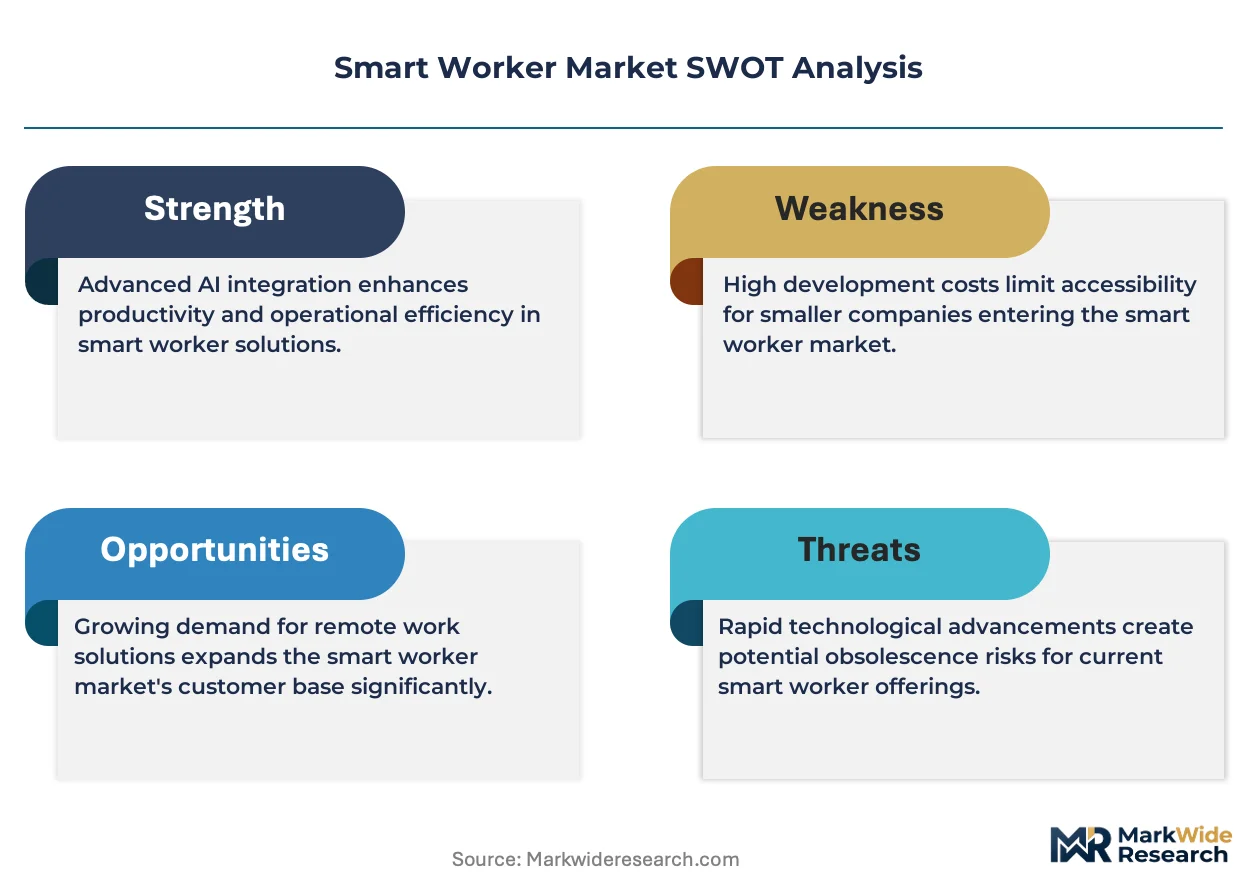
Edge-to-cloud AI orchestration is reshaping how industrial software stacks deliver real-time worker guidance and predictive hazard alerts. Honeywell International Inc leverages its embedded controls heritage to anchor high-reliability deployments in oil and gas facilities. Siemens competes through deep automation integration, while PTC differentiates via its digital thread connectivity across CAD, PLM, and field service layers.
Smart worker solutions encompass wearable, environmental, and software systems that capture biometrics, location, and equipment state to augment human decision-making in hazardous or complex workflows; typical deployments integrate accelerometers, gas sensors, and thermal cameras with sub-100ms latency requirements for emergency shutdown triggers. AR-enabled workforce training and remote monitoring applications are capturing disproportionate investment as manufacturers prioritize knowledge retention amid retiring specialist populations. IoT sensor systems and AI analytics layers are expanding fastest, though smart glasses remain margin-diluted due to optical hardware costs and fragmented software ecosystems.
OSHA, NIST, and the FDA (for healthcare-adjacent deployments) collectively set the compliance perimeter for device certification, data encryption, and incident reporting standards that determine market access. The EU AI Act and Machinery Directive are extending conformity obligations for algorithmic safety systems sold into European manufacturing and logistics chains. Stakeholders must weigh interoperability investments against the risk of proprietary platform lock-in as vendor consolidation accelerates.
Market Dynamics
Edge-to-cloud AI orchestration is compressing decision latency below 100 milliseconds, forcing industrial software vendors to re-architect their stacks around real-time worker guidance and predictive hazard detection rather than retrospective analytics.
Growth Catalysts
- OSHA workplace safety mandates:Tightening incident reporting requirements in United States manufacturing and energy facilities are accelerating procurement of connected worker platforms that automate compliance documentation and near-miss capture.
- Retiring specialist populations:Demographic turnover in German and Japanese industrial bases is driving AR-enabled knowledge transfer systems that preserve tacit operational expertise before workforce attrition erodes it.
- NIST cybersecurity frameworks:Mandatory encryption and access control standards for industrial IoT deployments are filtering out low-security vendors and concentrating procurement among certified platform providers.
Market Restraints
- Optical hardware costs:Smart glasses remain margin-diluted due to waveguide display manufacturing concentration in East Asian supply chains and limited economies of scale at sub-million-unit volumes.
- Proprietary platform lock-in:Vendor consolidation across Honeywell, Siemens, and PTC ecosystems is raising switching costs for manufacturing enterprises that standardized on incompatible data architectures.
- Fragmented software ecosystems:AR application development remains splintered across multiple SDKs and device form factors, delaying cross-platform deployment and inflating integration labor.
Strategic Opportunities
- Utility and energy sector deployment:United States power generation and transmission operators are scaling smart helmet and sensor system pilots into fleet-wide rollouts with multi-year procurement horizons.
- EU AI Act conformity:Algorithmic safety system certification requirements for European manufacturing and logistics chains create first-mover advantages for vendors pre-positioning compliant product lines.
- Biometric-thermal convergence:Integration of wearable health monitors with environmental gas sensors and thermal cameras is opening new application layers in confined space entry and hot work permitting.
Industry Challenges
- Cyber-physical integration talent:Scarce expertise in both operational technology protocols and cloud-native AI deployment is bottlenecking implementation timelines for hybrid edge-cloud architectures.
- Legacy system interoperability:Brownfield manufacturing environments running decades-old SCADA and MES layers require costly protocol translation gateways to ingest real-time worker location and biometrics.
- Multi-regulator certification timelines:Simultaneous FDA, OSHA, and EU Machinery Directive approval pathways for healthcare-adjacent deployments extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Worker Market |
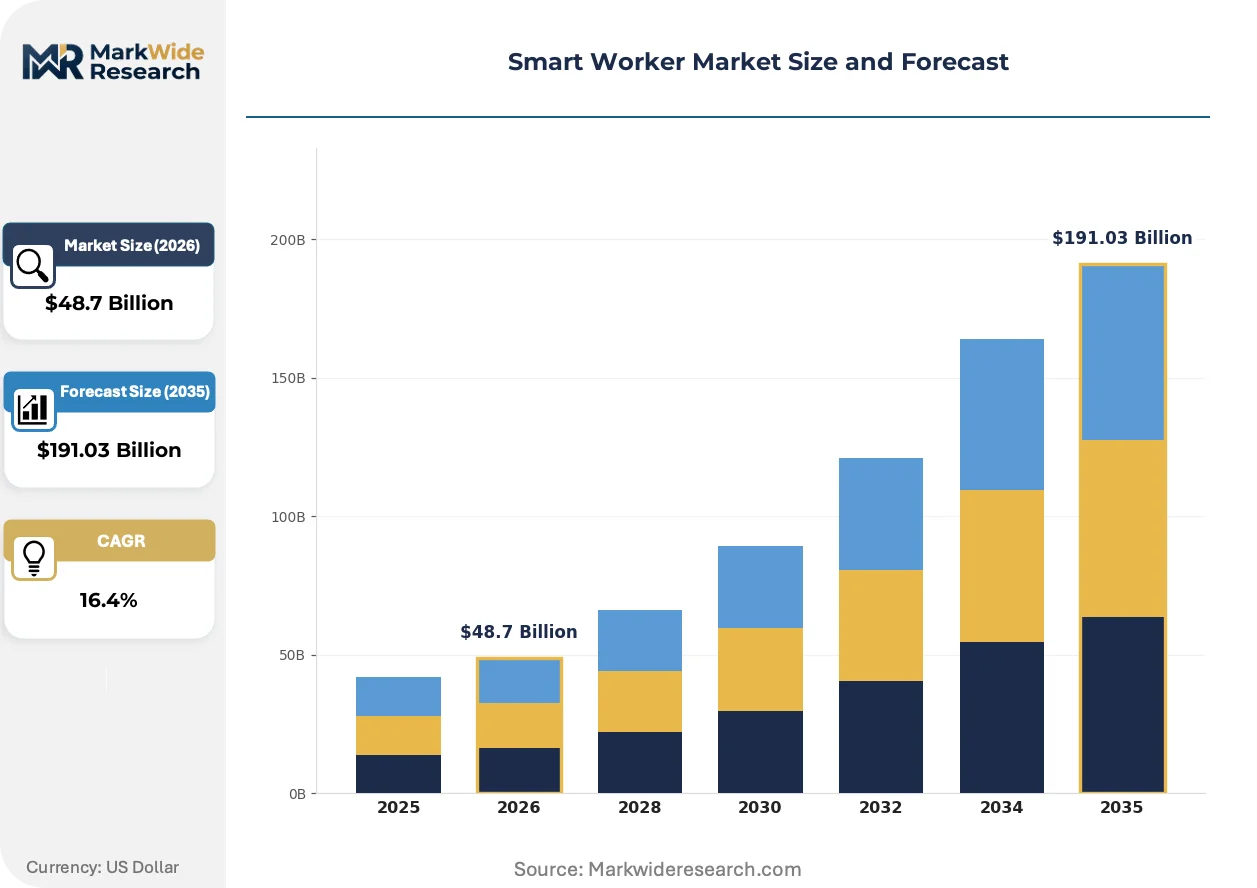
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Glasses, Smart Helmets, Sensor Systems Technology: IoT, AI, AR, Cloud Computing End User: Manufacturing, Logistics, Construction, Healthcare Application: Remote Monitoring, Workflow Automation, Safety Compliance, Workforce Training |
| Companies Covered | Schneider Electric, Zebra Technologies Corp., Honeywell International Inc, SymphonyAI, Hexagon AB, Microsoft, PTC, Innovapptive, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Worker Market Emerging Trajectories
Real-time worker augmentation systems are migrating from pilot programs to production-critical infrastructure, with latency requirements hardening and AI inference shifting toward the edge to survive network partition events.
Digital thread connectivity across CAD, PLM, and field service layers is rendering obsolete the siloed document repositories that previously isolated engineering design from operational feedback. Siemens and PTC are anchoring high-reliability deployments in automotive and aerospace assembly lines where configuration traceability is non-negotiable. This convergence compresses engineering change order cycles and enables predictive maintenance triggers based on actual worker interaction patterns with specific equipment instances.
The EU AI Act and Machinery Directive are extending conformity obligations for algorithmic safety systems sold into European manufacturing and logistics chains. Industrial software vendors must now document training data provenance and risk classification for AI models that trigger emergency shutdowns or redirect worker routing. German automotive OEMs and French nuclear maintenance providers are demanding third-party certification of explainability features before accepting vendor liability terms.
Buyer procurement patterns are hardening around outcome-based performance guarantees rather than perpetual license or SaaS subscription models. United States oil and gas operators and Gulf Coast chemical processors are negotiating contracts that tie vendor payments to measurable safety incident reduction and training time compression. This shift transfers implementation risk to platform providers and rewards vendors with demonstrated field reliability over those with superior feature checklists.
Smart Worker Market Segmentation
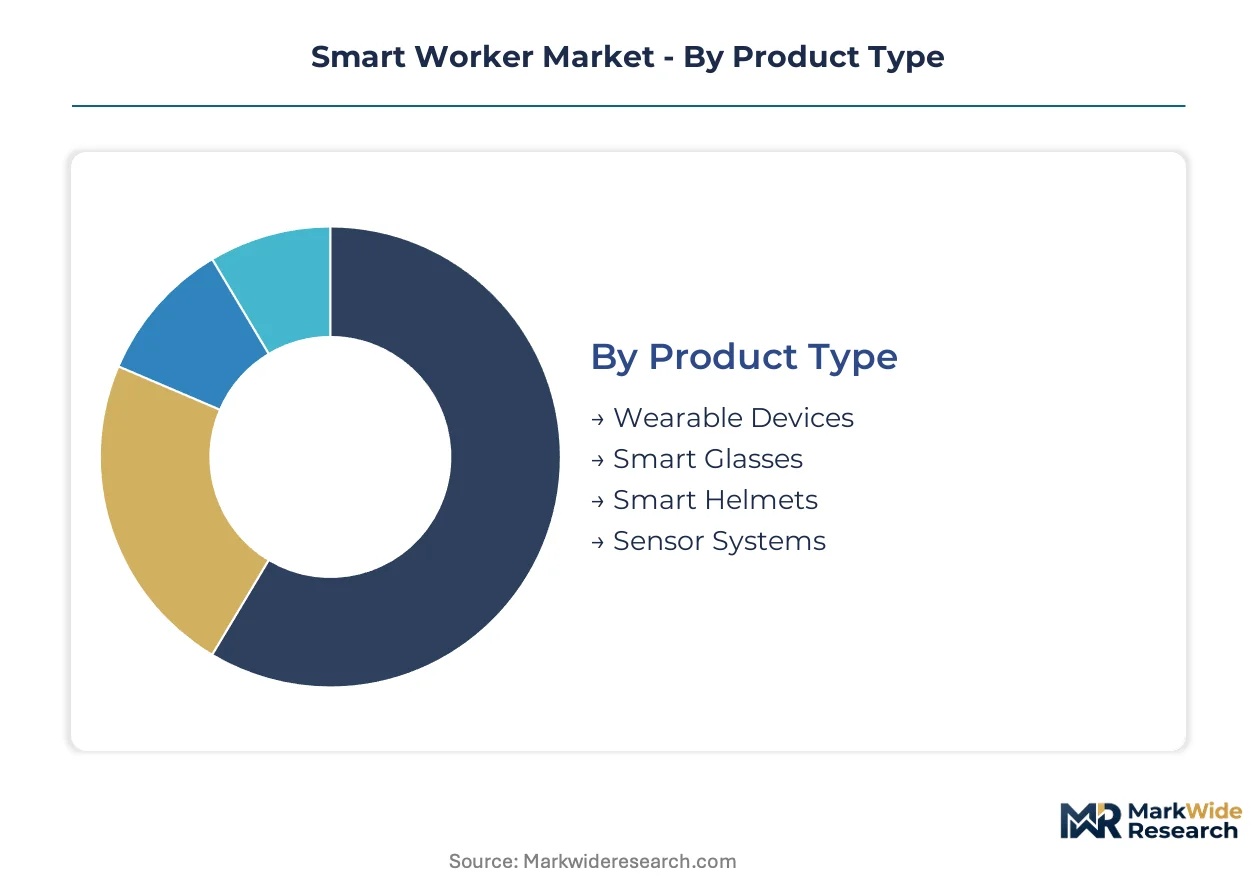
Smart worker deployments fragment across hardware form factors, software intelligence layers, and operational use cases. Procurement decisions hinge on latency requirements, legacy system compatibility, and regulator-mandated certification pathways. Understanding segment boundaries clarifies where vendor consolidation concentrates versus where niche specialists retain footholds.
Product Type:
Cost tier differentiation separates premium integrated systems from modular point solutions.
- Wearable Devices:Wrist-worn biometric monitors and location badges capture heart rate variability, fall detection, and proximity alerts through low-power BLE mesh networks. Logistics fulfillment centers in Germany and the United States are standardizing on these units for picker safety and throughput optimization. Battery life constraints and skin-contact sensor calibration remain primary procurement friction points.
- Smart Glasses:Optical see-through displays with waveguide optics overlay schematics and remote expert video feeds onto field-of-view. Manufacturing assembly lines in Japan deploy these for complex wiring harness installation guidance. Display brightness limitations in outdoor construction environments and software SDK fragmentation suppress fleet-scale adoption.
- Smart Helmets:Integrated hard hats with thermal cameras, gas sensors, and bone-conduction audio serve confined space entry and hot work permitting in oil and gas facilities.
- Sensor Systems:Environmental and equipment-mounted arrays detect toxic gas, noise exposure, and machine state without worker-worn hardware.
Wearable devices command the established base. The steepest expansion runs through smart helmets.
Technology:
Application maturity varies sharply across inference location and connectivity architecture.
- IoT:Edge sensor networks transmit telemetry through LoRaWAN, 5G private networks, or industrial Wi-Fi to centralized data lakes. United States utility operators leverage these for substation worker proximity monitoring and arc flash prevention. Network partition resilience and protocol translation complexity dominate implementation timelines.
- AI:Machine learning models running on edge accelerators classify video feeds, predict equipment failure, and trigger emergency shutdowns within sub-100ms latency budgets. French nuclear maintenance providers demand explainability certification under EU AI Act conformity requirements. Training data provenance documentation and model drift monitoring consume disproportionate engineering resources.
- AR:Spatial computing layers anchor digital content to physical environments for guided assembly and remote assistance.
- Cloud Computing:Centralized data processing and model training infrastructure supports fleet management and cross-site analytics.
IoT anchors current installed capacity. AI is climbing the fastest as inference migrates toward the edge.
End User:
Customer type determines certification burden, integration complexity, and procurement cycle length.
- Manufacturing:Automotive and electronics assembly plants deploy connected worker platforms for quality traceability and ergonomic hazard reduction. German OEMs require Machinery Directive conformity and digital thread integration with existing PLM systems. Brownfield facilities running decades-old SCADA layers face costly gateway procurement.
- Logistics:E-commerce fulfillment networks prioritize picker productivity and collision avoidance in high-density warehouse environments. OSHA incident reporting automation drives United States adoption.
- Construction:Project-based contracting models and fragmented subcontractor relationships complicate fleet standardization and data ownership.
- Healthcare:FDA-regulated deployments for surgical assistance and patient monitoring impose 18-24 month certification timelines.
Manufacturing retains the deepest installed base. Healthcare is expanding most quickly despite regulatory friction.
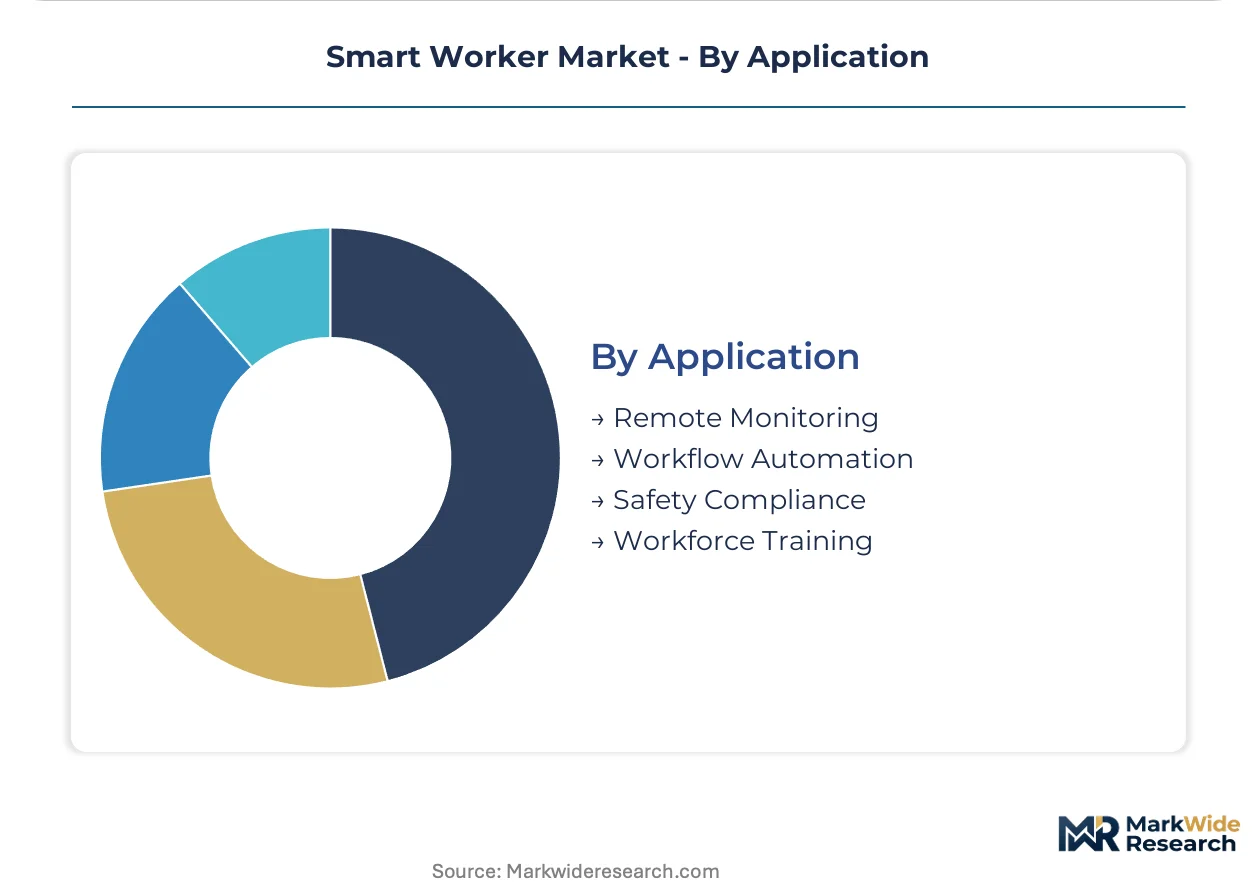
Application:
Volume concentration tracks safety mandate enforcement intensity and labor cost pressure.
- Remote Monitoring:Video and sensor feeds enable centralized oversight of distributed field crews without physical supervisor presence. United States oil and gas operators deploy these for offshore platform and pipeline inspection safety. Bandwidth constraints in remote locations and data privacy concerns limit coverage.
- Workflow Automation:Digital work instructions and pick-to-light systems guide task execution with real-time validation. Japanese electronics manufacturers use these to compress training time for seasonal workforce surges. Integration with existing MES and ERP systems determines deployment velocity.
- Safety Compliance:Automated near-miss capture and incident documentation streamlines OSHA and EU Machinery Directive reporting.
- Workforce Training:AR-enabled knowledge transfer preserves specialist expertise amid demographic turnover in German and Japanese industrial bases.
Remote monitoring holds the largest current footprint. Workforce training is gaining share fastest as retirement waves accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation vendors export edge-computing platforms to United States energy operators, while Japanese sensor manufacturers supply wearable systems to German automotive assembly plants. This cross-border equipment flow concentrates procurement decisions in jurisdictions with stringent safety certification regimes.
United States
Utility and oil and gas operators deploy smart helmet fleets for confined space entry and arc flash prevention. OSHA workplace safety mandates tighten incident reporting requirements, filtering procurement toward certified platform providers. Gulf Coast chemical processors in Texas and Louisiana negotiate outcome-based contracts tying vendor payments to measurable safety incident reduction.
Germany
Automotive OEMs demand Machinery Directive conformity and digital thread integration with existing PLM systems. The EU AI Act imposes algorithmic safety system certification requirements for AI models triggering emergency shutdowns. Bavarian automotive assembly plants anchor high-reliability deployments where configuration traceability is non-negotiable.
Japan
Electronics manufacturers deploy AR-enabled systems to compress training time for seasonal workforce surges amid specialist retirements. METI industrial standards guide wearable device interoperability specifications. Kansai region assembly plants standardize on guided wiring harness installation using optical see-through displays.
France
Nuclear maintenance providers demand third-party certification of explainability features before accepting vendor liability terms for AI-driven hazard detection. EU AI Act documentation requirements for training data provenance consume disproportionate engineering resources. Paris-region energy contractors pilot biometric-thermal convergence systems for hot work permitting.
China
Manufacturing enterprises scale adoption of connected worker platforms to close operational visibility gaps in electronics and automotive assembly. GB standards and MIIT cybersecurity frameworks shape device certification and data encryption requirements. Yangtze River Delta industrial clusters drive fleet-scale procurement of location badges and environmental sensor arrays.
Smart Worker Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around three dominant ecosystems. Honeywell, Siemens, and PTC anchor incompatible data architectures that raise switching costs for standardized manufacturing enterprises. Two strategic archetypes dominate: industrial conglomerates leveraging embedded controls heritage, and software-native vendors differentiating through digital thread connectivity. Competitive moves concentrate on strategic partnerships for protocol translation gateways and portfolio diversification into biometric-thermal convergence systems.
Within the industrial conglomerate tier, Honeywell International Inc and Siemens exemplify channel-controlling positions built on decades of operational technology deployment. Among software-native specialists, PTC occupies a position representing digital thread connectivity across CAD, PLM, and field service layers. These three anchors collectively shape procurement patterns as vendor consolidation accelerates and manufacturing enterprises weigh interoperability investments against proprietary platform lock-in risks.
| Leading Market Players |
|---|
| Schneider Electric |
| Zebra Technologies Corp. |
| Honeywell International Inc |
| SymphonyAI |
| Hexagon AB |
| Microsoft |
| PTC |
| Innovapptive |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion and transpacific container rates compress margins for East Asian waveguide display manufacturers, concentrating pricing power among integrated helmet producers while forcing modular sensor vendors toward volume-discount contracts with United States utility operators.
Pricing Analysis
Next-generation AI-enabled smart helmets command 40-60% premiums over first-generation IoT badge systems, while legacy SCADA-integrated wearables face commoditization pressure from cloud-native entrants. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aviation units from OSHA-compliant industrial badges and uncertified logistics trackers. Pricing pressure stems from optical hardware manufacturing concentration in Taiwan and South Korea, where display foundry capacity constraints inflate component costs. Logistics fulfillment centers exhibit highest price sensitivity due to thin operating margins, whereas nuclear maintenance providers accept premium pricing for EU AI Act conformity documentation.
Supply Chain Analysis
Extended 90-day payment terms from United States oil and gas operators strain working capital for Taiwanese MEMS sensor foundries, accelerating supply-chain finance facility adoption among tier-two environmental gas detector assemblers. Manufacturing concentrates in China, Germany, and Japan, with waveguide optics drawing from South Korean display panel producers and edge AI accelerators resting on TSMC's advanced node capacity. Single-source vulnerability pervades thermal imaging sensor supply, where FLIR and Seek Thermal anchor critical defense-industrial allocations. Distribution runs through Honeywell and Siemens direct sales forces for enterprise accounts, while Zebra Technologies channels modular hardware through industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI coding assistants threaten to commoditize AR application development layers, forcing incumbent platform vendors to defend integration depth and certification moats against software-native disruptors.
For Market Incumbents: Pre-empt generative AI commoditization by deepening digital thread connectivity across PLM-MES-ERP stacks, anchoring switching costs in configuration traceability workflows that AI-native entrants cannot replicate overnight. Accelerate biometric-thermal convergence R&D to capture confined space entry applications before specialist sensor vendors achieve certification scale. Defend against PTC's CAD-originated field service expansion by tightening embedded controls integration in oil and gas brownfield deployments.
For New Entrants and Emerging Players: Pursue white-space opportunity in Japanese electronics assembly AR training, where METI interoperability standards create entry pathways against fragmented incumbent SDK ecosystems. Target United States Gulf Coast chemical processors with outcome-based pilot contracts that transfer implementation risk from capital-constrained buyers. Attack logistics fulfillment center picker safety through BLE mesh wearables priced below Zebra's enterprise tier, leveraging cloud-native architecture to bypass legacy MES integration costs.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core connected worker divisions amid portfolio rationalization pressures. Long-term viability hinges on regulatory certification depth rather than feature velocity, favoring acquisition of EU AI Act-compliant algorithmic safety specialists over hardware-agnostic software layers. Watch FDA breakthrough device designation timelines for healthcare-adjacent deployments as inflection signal for valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Algorithmic safety certification opens German automotive and French nuclear maintenance procurement. |
| Biometric-Thermal Convergence Development | Wearable health monitors plus gas sensors capture confined space entry permits from Honeywell. |
| Outcome-Based Contract Structuring | Safety incident reduction guarantees align vendor payments with United States oil and gas operator KPIs. |
| Digital Thread Platform Integration | CAD-PLM-MES connectivity renders PTC's configuration traceability indispensable for aerospace assembly. |
| Edge AI Accelerator Partnership | Sub-100ms inference latency secures emergency shutdown trigger contracts against cloud-dependent rivals. |
Methodological Framework
Desk research of SEC 10-K filings, OSHA incident databases, EU Machinery Directive conformity registries, and industrial IoT patent landscapes preceded structured interviews with plant engineers, EHS directors, connected worker platform product managers, and utility procurement officers. Primary fieldwork validated secondary estimates against actual deployment timelines, latency requirements, and certification expenditure patterns. Bottom-up unit economics triangulated against top-down market sizing from vendor revenue disclosures and industrial automation trade association aggregates.
Assumptions held fixed include NIST cybersecurity framework compliance timelines, EU AI Act enforcement intensity, and United States utility sector capital expenditure trajectories. Variables stress-tested across the projection horizon encompass 5G private network deployment velocity, edge AI chip availability, and German automotive OEM PLM migration schedules. Segmentation modeling incorporated product type, technology layer, end-user industry, and application use case dimensions. CAGRs derived from logistic diffusion curves fitted to early-adopter penetration patterns in oil and gas and utility verticals.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, interest rate environments affecting utility infrastructure investment, or semiconductor foundry capacity allocation would shift the trajectory. Forecasts reflect documented assumptions; regulatory enforcement intensity variation, cybersecurity incident frequency, or generative AI capability advancement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Handheld Robotics Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Quadruped Robot Market
Robotics and Automation
Global Smart Robots Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
Underwater Jetpack Market