
 Asia Pacific Industrial Robots Market | 2026-2036
Asia Pacific Industrial Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Industrial Robots Market Insights
Mid-sized electronics contract manufacturers are redrawing procurement patterns for industrial robots, shifting volume away from traditional automotive integrators toward semiconductor and consumer electronics fabs. FANUC Corporation anchors Japan's premium servo-motor supply chain through captive production of precision reducers and controllers. Yaskawa Electric dominates arc-welding robot shipments to Vietnamese and Indonesian metalworking plants. ABB Ltd positions its collaborative robot line for cleanroom electronics assembly across Malaysia and Thailand.
Industrial robots encompass programmable multi-axis manipulators with payload capacities from 0.5 kg to over 2,000 kg, driven by servo motors, harmonic drives, and real-time kinematic controllers to execute repetitive or hazardous manufacturing tasks with sub-millimeter repeatability. Articulated robots lead unit shipments across heavy-payload automotive welding and press-tending operations, while collaborative robots capture the fastest expansion as electronics and pharmaceutical end users retrofit existing lines for human-robot coexistence without safety fencing. Sensor technology and vision systems now determine competitive differentiation, with AI integration migrating from pilot installations to standard factory acceptance test protocols.
China's MIIT enforces GB standards for robot functional safety and electromagnetic compatibility, while Japan's METI coordinates JIS certification for collaborative operation modes; both frameworks raise compliance costs for non-domestic suppliers but accelerate replacement cycles as older units fail new certification audits. South Korea's MFDS and KOSHA jointly regulate pharmaceutical cleanroom robot deployments, limiting market access to vendors with validated hygienic surface finishes. Stakeholders must track how India's BIS adoption of ISO 10218 safety standards reshapes tender requirements for automotive and electronics manufacturing investments.
Market Dynamics
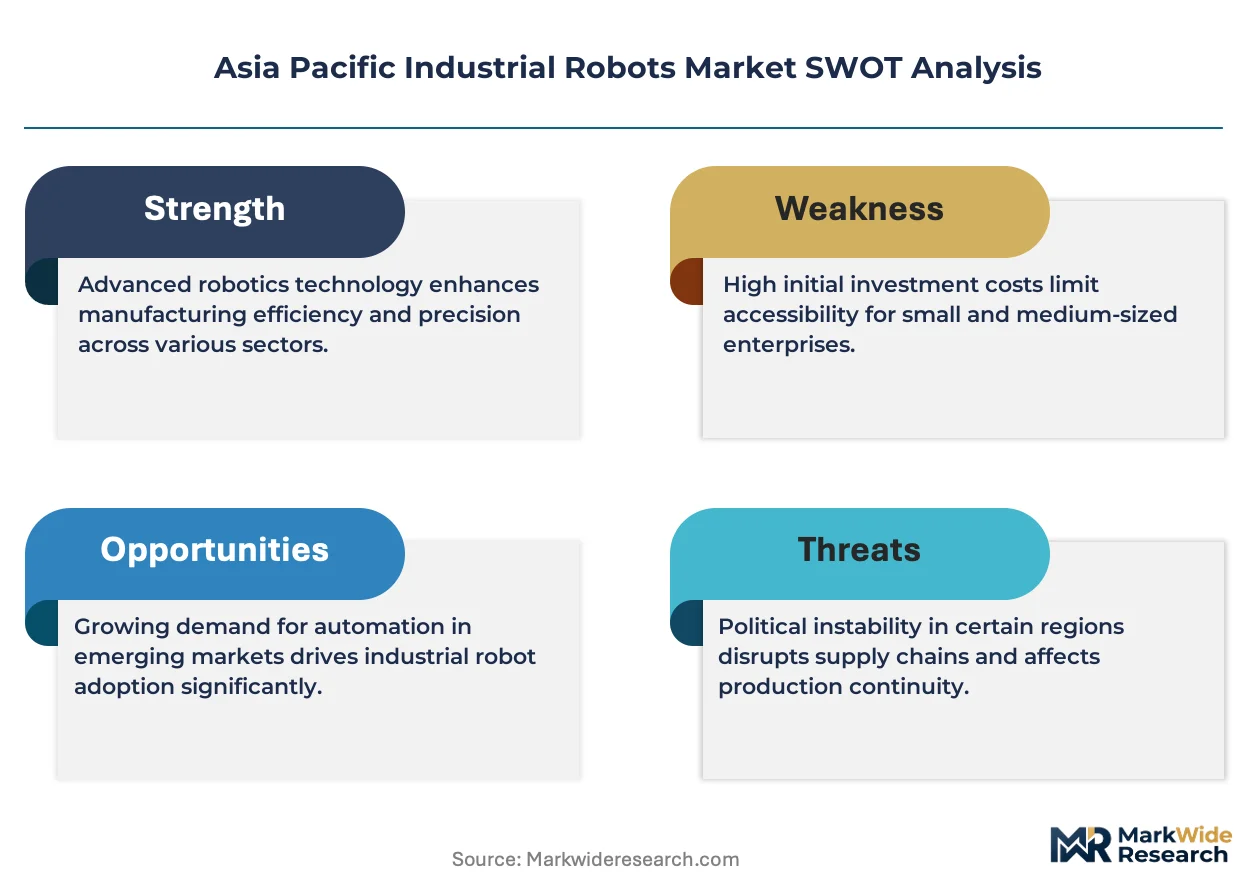
China's MIIT dual carbon mandates and Japan's METI automation subsidies are compressing replacement cycles for legacy hydraulic systems while redirecting procurement toward electric drive architectures with energy-efficient actuators.
Growth Catalysts
- MIIT Dual Carbon Goals:China's enforced GB standards for robot functional safety and electromagnetic compatibility accelerate factory upgrades as older units fail certification audits, forcing capital deployment toward compliant electric drive systems.
- Electronics Precision Assembly:Semiconductor fabs and consumer electronics contract manufacturers in South Korea's Gyeonggi-do belt expand collaborative robot deployment for sub-millimeter repeatability in cleanroom environments.
- India's BIS Adoption:The Bureau of Indian Standards' implementation of ISO 10218 safety protocols reshapes tender requirements for automotive and electronics manufacturing investments across Tamil Nadu's automotive corridor.
Market Restraints
- Harmonic Drive Supply Concentration:Precision reducer manufacturing concentrates among Japanese captive producers, creating input cost volatility for non-integrated robot assemblers throughout Southeast Asia.
- Certification Timeline Friction:South Korea's MFDS and KOSHA joint regulations for pharmaceutical cleanroom robots limit market access to vendors with validated hygienic surface finishes, extending validation periods.
- Legacy System Integration Costs:Retrofitting existing automotive press-tending lines for human-robot coexistence without safety fencing requires substantial controller and sensor architecture overhaul.
Strategic Opportunities
- Vietnamese Metalworking Expansion:Arc-welding robot deployment in Vietnamese and Indonesian fabrication plants remains underpenetrated relative to automotive intensity in Northeast Asia, offering volume white space.
- AI-Vision Convergence:Real-time kinematic controllers integrated with machine vision systems migrate from pilot installations to standard factory acceptance test protocols, enabling new service revenue models.
- Thailand Cleanroom Electronics:Collaborative robot lines for cleanroom assembly across Malaysia and Thailand benefit from unmet demand in medical device and semiconductor packaging applications.
Industry Challenges
- Mechatronics Skill Scarcity:Servo motor tuning and harmonic drive maintenance expertise concentrates in Japan and South Korea, constraining deployment velocity in emerging manufacturing clusters.
- Multi-Axis Programming Complexity:Electronics contract manufacturers face integration friction when retrofitting existing lines for programmable multi-axis manipulators with real-time kinematic controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Industrial Robots Market |
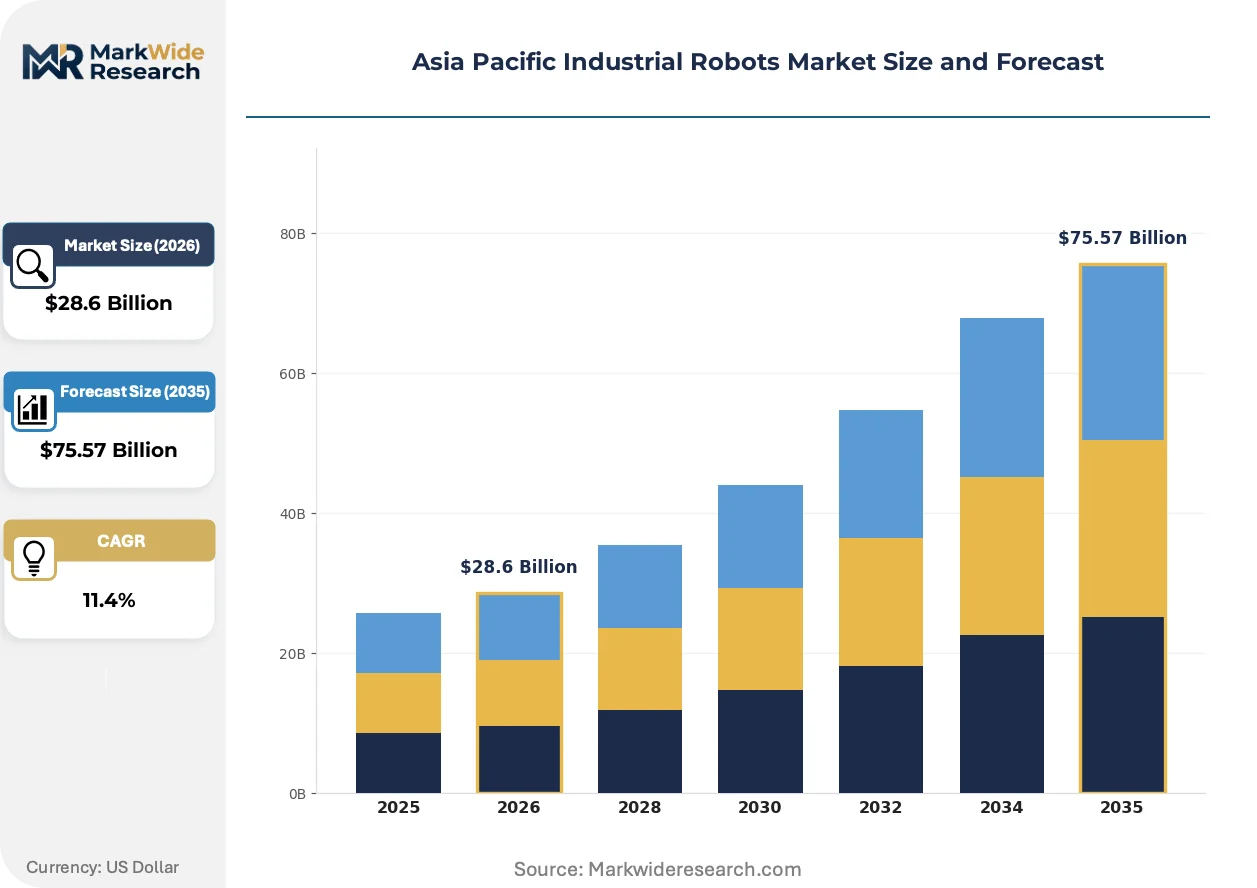
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Delta Robots, Collaborative Robots Application: Material Handling, Welding, Assembly, Painting End User: Aerospace, Electronics, Automotive, Pharmaceuticals Technology: AI Integration, Sensor Technology, Automation Software, Vision Systems |
| Companies Covered | FANUC Corporation, Yaskawa Electric Corporation, KUKA AG, ABB Ltd, Kawasaki Heavy Industries Ltd, Mitsubishi Electric Corp, Denso Corp, OMRON Corp, Nachi Fujikoshi Corp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Industrial Robots Market Trends and Innovations
Sensor technology and vision systems now determine competitive differentiation as AI integration migrates from pilot installations to standard protocols, while procurement patterns shift volume away from traditional automotive integrators.
Force-torque sensors combined with collaborative robot architectures are supplanting traditional safety-fenced articulated systems in electronics assembly. Semiconductor fabs and pharmaceutical cleanroom operators in South Korea and Malaysia adopt these configurations for human-robot coexistence. The structural consequence is compressing deployment timelines from eighteen-month integration cycles to six-week retrofits.
Japan's METI coordinates JIS certification for collaborative operation modes while China's MIIT enforces GB standards for electromagnetic compatibility. Both frameworks raise compliance costs for non-domestic suppliers but accelerate replacement cycles. Electronics and pharmaceutical end users in both countries respond by consolidating vendor relationships with certified regional suppliers.
Mid-sized electronics contract manufacturers now unbundle after-sales service from initial hardware procurement, favoring vendors with localized maintenance networks over integrated system providers. This pattern disrupts traditional automotive integrator channels across China's Yangtze River Delta. The shift is most visible in Tamil Nadu's automotive corridor, where tender structures increasingly separate hardware supply from multi-year service agreements.
Asia Pacific Industrial Robots Market Segmentation
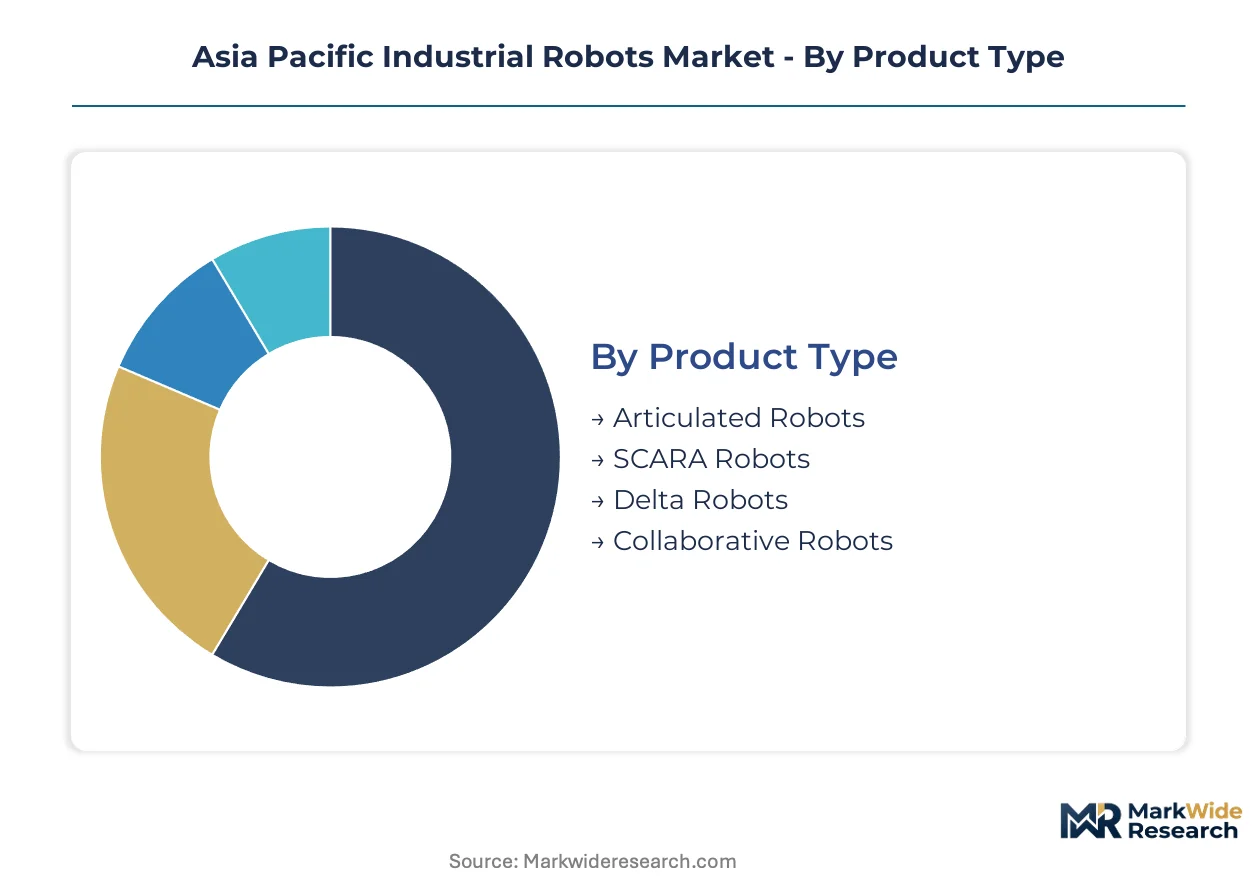
Industrial robot procurement in Asia Pacific splits across four distinct dimensions, each channeling through different sales architectures. Product type determines whether systems flow through automotive integrators or direct-to-fab semiconductor channels. Application and end-user segmentation reshape pricing power and service attachment rates. Technology tiering separates pilot-scale AI deployments from standardized automation software rollouts.
Product Type:
Channel mix varies sharply by kinematic architecture, with heavy-payload articulated systems dominating automotive integrator relationships while collaborative robots increasingly bypass traditional distribution through direct electronics fab sales.
- Articulated Robots:Six-axis or greater configurations with payload capacities exceeding 200 kg dominate automotive press-tending and body-in-white welding across China's Yangtze River Delta. Japanese captive producers of precision reducers control upstream supply, forcing non-integrated assemblers into volume commitments with extended payment terms.
- Collaborative Robots:Force-limited manipulators designed for human-robot coexistence without safety fencing capture the steepest expansion trajectory across South Korea's Gyeonggi-do semiconductor belt and Malaysia's medical device packaging plants. Deployment timelines compress from eighteen-month integration cycles to six-week retrofits as electronics contract manufacturers unbundle hardware from multi-year service agreements.
- SCARA Robots:Selective Compliance Assembly Robot Arms deliver sub-millimeter repeatability for planar pick-and-place operations in electronics assembly.
- Delta Robots:Parallel kinematic architectures optimized for high-speed lightweight manipulation in food and pharmaceutical packaging applications.
By volume, Articulated Robots lead. By growth pace, Collaborative Robots are climbing the fastest.
Application:
Cost tiering separates high-integration welding systems from standardized material handling modules, with welding commanding premium pricing through specialized arc-tracking sensor packages.
- Welding:Arc and spot welding configurations integrate real-time seam-tracking vision systems with through-the-arc sensing for adaptive parameter control. Vietnamese and Indonesian metalworking plants drive volume expansion as fabrication capacity migrates from Northeast Asia, though mechatronics skill scarcity constrains deployment velocity outside Japan and South Korea.
- Assembly:Precision joining operations for electronics and automotive components require force-torque feedback and sub-millimeter positioning repeatability. Semiconductor fabs in South Korea and cleanroom operators in Thailand consolidate vendor relationships with certified regional suppliers as China's MIIT and Japan's METI raise compliance costs for non-domestic hardware.
- Material Handling:Palletizing, machine tending, and logistics automation represent the largest installed base by unit volume.
- Painting:Explosion-proof manipulators with electrostatic spray integration serve automotive and aerospace finishing lines.
Welding commands the highest average system price. Assembly applications are expanding most quickly as electronics precision requirements intensify.
End User:
Customer type determines procurement structure, with automotive buyers demanding integrated turnkey solutions and electronics manufacturers unbundling hardware from service contracts.
- Electronics:Semiconductor fabs and consumer electronics contract manufacturers in South Korea's Gyeonggi-do belt and China's Yangtze River Delta drive collaborative robot adoption for cleanroom-compatible human-robot coexistence. Force-torque sensor integration and AI-vision convergence migrate from pilot installations to standard factory acceptance test protocols.
- Automotive:OEMs and Tier-1 suppliers across India's Tamil Nadu automotive corridor and Thailand's Eastern Economic Corridor deploy heavy-payload articulated systems for body-in-white welding and press-tending. India's BIS adoption of ISO 10218 safety standards reshapes tender requirements, separating hardware supply from multi-year maintenance agreements.
- Pharmaceuticals:Cleanroom-validated manipulators with hygienic surface finishes serve South Korean and Malaysian drug manufacturing under MFDS and KOSHA joint regulations.
- Aerospace:Large-work envelope systems with high-precision drilling and fastening capabilities support airframe assembly.
Automotive retains the largest cumulative installed base. Electronics end users are gaining share fastest through collaborative robot penetration.
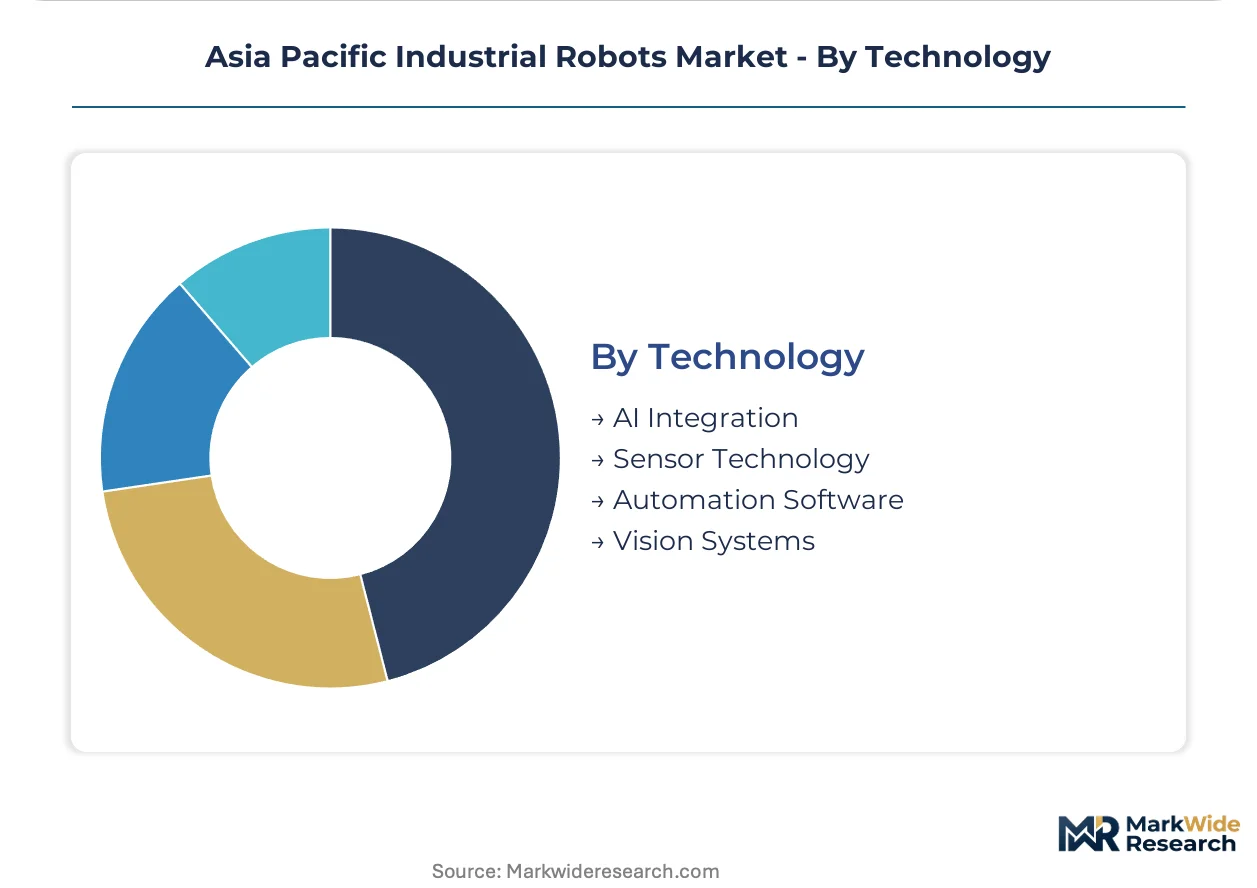
Technology:
Maturity gradients separate established automation software from emerging AI-vision convergence, with sensor technology occupying the commercialization midpoint.
- Vision Systems:Machine vision integration with real-time kinematic controllers enables adaptive path planning and quality inspection without fixed tooling. Electronics assembly across Malaysia and Thailand and pharmaceutical packaging in South Korea drive adoption as AI-vision convergence shifts from pilot validation to standard procurement specifications.
- Sensor Technology:Force-torque sensors, proximity arrays, and tactile feedback systems determine competitive differentiation in collaborative applications. The structural consequence is displacing traditional safety-fenced architectures across electronics and pharmaceutical cleanroom retrofits.
- AI Integration:Deep learning-based trajectory optimization and predictive maintenance algorithms remain concentrated in pilot installations at leading semiconductor fabs.
- Automation Software:Established PLC and robot controller programming environments constitute the baseline technology layer across all volume segments.
Automation Software reaches the broadest installed base. AI Integration holds the steepest future expansion trajectory as factory acceptance protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics contract manufacturers and automotive Tier-1 suppliers dominate procurement decisions across the Asia Pacific industrial robots market, with cluster concentration in China's eastern seaboard, Japan's industrial heartland, and South Korea's semiconductor belt driving volume allocation.
China
MIIT dual carbon mandates compress replacement cycles for legacy hydraulic systems across automotive press-tending lines. GB standards for robot functional safety and electromagnetic compatibility force capital deployment toward compliant electric drive architectures. Yangtze River Delta manufacturing clusters see mid-sized electronics contract manufacturers unbundling hardware procurement from multi-year service agreements.
Japan
METI automation subsidies redirect procurement toward energy-efficient actuator systems with real-time kinematic controllers. JIS certification for collaborative operation modes raises compliance costs for non-domestic suppliers while accelerating replacement cycles. Kanto and Chubu industrial corridors anchor captive production of precision reducers and servo-motor supply chains.
South Korea
MFDS and KOSHA joint regulations limit pharmaceutical cleanroom robot deployments to vendors with validated hygienic surface finishes. Gyeonggi-do semiconductor belt drives collaborative robot adoption for sub-millimeter repeatability in cleanroom environments. Electronics fabs consolidate vendor relationships with certified regional suppliers as validation periods extend.
India
BIS adoption of ISO 10218 safety standards reshapes tender requirements for automotive and electronics manufacturing investments. Tamil Nadu automotive corridor sees OEMs separating hardware supply from multi-year maintenance agreements in procurement structures. Mechatronics skill scarcity constrains deployment velocity relative to Northeast Asian benchmarks.
Vietnam
Arc-welding robot deployment in metalworking fabrication plants remains underpenetrated relative to automotive intensity in Northeast Asia. Vietnamese fabricators drive volume expansion as welding capacity migrates from higher-cost neighboring markets. Indonesian metalworking clusters present adjacent white space for similar equipment configurations.
Asia Pacific Industrial Robots Market Competitive Landscape
Player mix skews toward integrated Japanese industrial conglomerates with captive precision component supply chains, creating a tiered structure where non-integrated assemblers face input cost volatility. Strategic archetypes include: vertically integrated servo-motor and reducer producers; collaborative robot specialists targeting electronics cleanroom retrofits; and European system integrators positioning AI-vision convergence for factory acceptance protocols. Dominant competitive moves center on backward integration into precision reducer manufacturing and geographic expansion through localized maintenance network buildout.
Among Japan-based integrated producers, FANUC Corporation and Yaskawa Electric Corporation occupy positions as archetypes of captive supply chain control, while ABB Ltd represents the European system integrator model targeting collaborative applications across Southeast Asian electronics assembly. These three companies exemplify the strategic divergence between component-integrated and solution-focused competitive positioning.
| Leading Market Players |
|---|
| FANUC Corporation |
| Yaskawa Electric Corporation |
| KUKA AG |
| ABB Ltd |
| Kawasaki Heavy Industries Ltd |
| Mitsubishi Electric Corp |
| Denso Corp |
| OMRON Corp |
| Nachi Fujikoshi Corp |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Japanese precision reducer foundries anchors cost floors across Asia Pacific robot assembly, concentrating pricing power among captive producers while forcing non-integrated vendors into volume-commitment contracts with extended payment terms. China's Yangtze River Delta electronics fabs and South Korea's Gyeonggi-do semiconductor belt drive procurement scale, yet harmonic drive supply scarcity transmits directly into system-level price premiums for collaborative robot configurations.
Pricing Analysis
Cost-plus contracts with rare-earth magnet and copper winding indexation dominate procurement between Japanese servo-motor suppliers and downstream robot assemblers. Price differentiation hinges on JIS certification tier for collaborative operation modes and after-sales service bundling, with certified systems commanding premiums over non-compliant hardware. Cost compression in mid-payload articulated segments is intensifying because Vietnamese and Indonesian metalworking buyers prioritize unit economics over precision specifications. Electronics contract manufacturers in Malaysia and Thailand exhibit lowest price sensitivity due to cleanroom validation requirements, while Indian automotive Tier-1 suppliers in Tamil Nadu drive hardest bargain on hardware-only procurement.
Supply Chain Analysis
Nagoya Port throughput and Yokohama container terminal capacity constraints throttle precision component dispatch to Southeast Asian assembly plants. Captive production of harmonic drives and servo motors concentrates in Japan and South Korea, with controller firmware development anchored in Taiwan and select Chinese design houses. Raw material dependencies span neodymium rare-earth magnets from Chinese separation facilities, high-grade steel alloys from South Korean integrated mills, and ceramic bearings from Japanese specialty manufacturers. Single-source vulnerability runs through precision reducer supply, where two Japanese conglomerates control global capacity. Distribution runs through automotive integrator channels for heavy-payload systems and direct fab sales for collaborative robot lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics skill scarcity constrains deployment velocity across emerging manufacturing clusters, creating asymmetric returns for stakeholders who secure localized maintenance networks and certified technician pipelines before competitors. The gap between Japan-Korea servo tuning expertise and Vietnam-India field capability represents the critical binding constraint on market expansion.
For Market Incumbents: Shield precision reducer supply advantages by locking in multi-year rare-earth offtake agreements and expanding captive foundry capacity in Nagoya and Chubu corridors. Accelerate JIS certification audits for collaborative operation modes to raise compliance barriers against European system integrators targeting Thailand cleanroom electronics. Channel control through localized service depots in Tamil Nadu and Vietnam's northern industrial provinces defends against emerging Chinese electric-drive specialists.
For New Entrants and Emerging Players: BIS fast-track certification for ISO 10218 safety protocols offers entry pathway into India's automotive corridor tender structures. Vietnamese arc-welding robot deployment remains underpenetrated relative to Northeast Asia intensity, presenting volume white space for mid-payload articulated systems with simplified controller architectures. Go-to-market angle should unbundle hardware from service contracts, mirroring procurement pattern shifts visible across Yangtze River Delta electronics contract manufacturers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among collaborative robot specialists with multi-year service agreements attached to cleanroom electronics deployments. Long-term viability over the projection horizon favors vendors with backward integration into precision reducer manufacturing and established technician training pipelines. Acquisition target archetype: mid-cap Japanese or South Korean firms with validated hygienic surface finishes and MFDS-KOSHA joint regulatory clearance. Signal to watch is certification timeline compression for AI-vision convergence protocols migrating from pilot to standard factory acceptance specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Reducers | Captive harmonic drive production insulates margin structure against Japanese supply concentration and input cost volatility. |
| Localized Maintenance Network Buildout | Vietnam and India service depots address mechatronics skill scarcity constraining deployment velocity in emerging clusters. |
| JIS Certification Investment | Collaborative operation mode compliance raises barriers against European entrants targeting Thailand cleanroom electronics. |
| AI-Vision Convergence Development | Real-time kinematic controller integration with machine vision shifts from pilot validation to standard procurement specifications. |
| Rare-Earth Magnet Offtake Agreements | Long-term neodymium supply contracts secure cost-plus pricing stability with Chinese separation facility operators. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at automotive Tier-1 suppliers, procurement leads at electronics contract manufacturers, aftermarket service heads at Japanese robot OEMs, and maintenance directors across Vietnam and Indian manufacturing clusters, then refined through secondary validation. Trade flow data from Japan Customs and Korea Customs Service, MIIT equipment registration filings, BIS tender documentation, and SEC 10-K disclosures from listed automation suppliers provided demand-side calibration. Bottom-up unit shipment estimates by product type and application were cross-referenced against top-down capital expenditure tracking across Yangtze River Delta, Gyeonggi-do, and Tamil Nadu manufacturing corridors.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling spanning kinematic architecture, payload tier, end-use industry, and technology maturity gradient. CAGRs were derived from regression analysis of historical replacement cycle data against regulatory compliance deadline schedules and subsidy program phase-outs. Industry-specific forecast inputs include MIIT dual carbon mandate enforcement timelines, METI automation subsidy renewal probabilities, and BIS ISO 10218 adoption trajectory across Indian state industrial development corporations.
Decision-makers should treat outputs as directional under assumptions of sustained electronics capital expenditure in Northeast Asia and gradual automotive electrification transition in India; material deviation would warrant model refresh. Forecasts embed assumptions around harmonic drive supply elasticity, rare-earth magnet price stability, and certification timeline consistency across MFDS-KOSHA joint regulatory frameworks. Revision becomes warranted when AI-vision convergence adoption crosses threshold from pilot installations to majority share of new factory acceptance test protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Inspection Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Cognitive Robotics Market