
 Europe Service Robotics Market | 2026-2036
Europe Service Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Service Robotics Market Insights
The EU AI Act is decoupling compliance costs from hardware scale, forcing smaller vendors to absorb certification overhead that incumbents amortize across larger fleets. KUKA AG leverages its industrial automation heritage to anchor service robot production in Germany. ABB Ltd. competes through its navigation software stack for mobile platforms in logistics corridors. PAL Robotics specializes in humanoid architectures for research and retail interaction, sustaining R&D intensity through European grant programs.
Europe service robotics encompasses autonomous electromechanical systems designed for non-manufacturing tasks, typically integrating lidar arrays, force-torque sensors, and real-time path-planning algorithms operating at sub-50-millisecond loop cycles. These platforms perform material transport, patient assistance, crop monitoring, and customer engagement without fixed protective enclosures. The medical segment leads current revenue generation as hospitals deploy surgical assistance and rehabilitation exoskeletons. The logistic segment represents the fastest expansion corridor, driven by warehouse-to-last-yard automation demand. Artificial Intelligence as a technology layer commands the deepest margin pools, since sensor fusion and adaptive behavior engines differentiate vendor offerings beyond commoditized mechanical platforms.
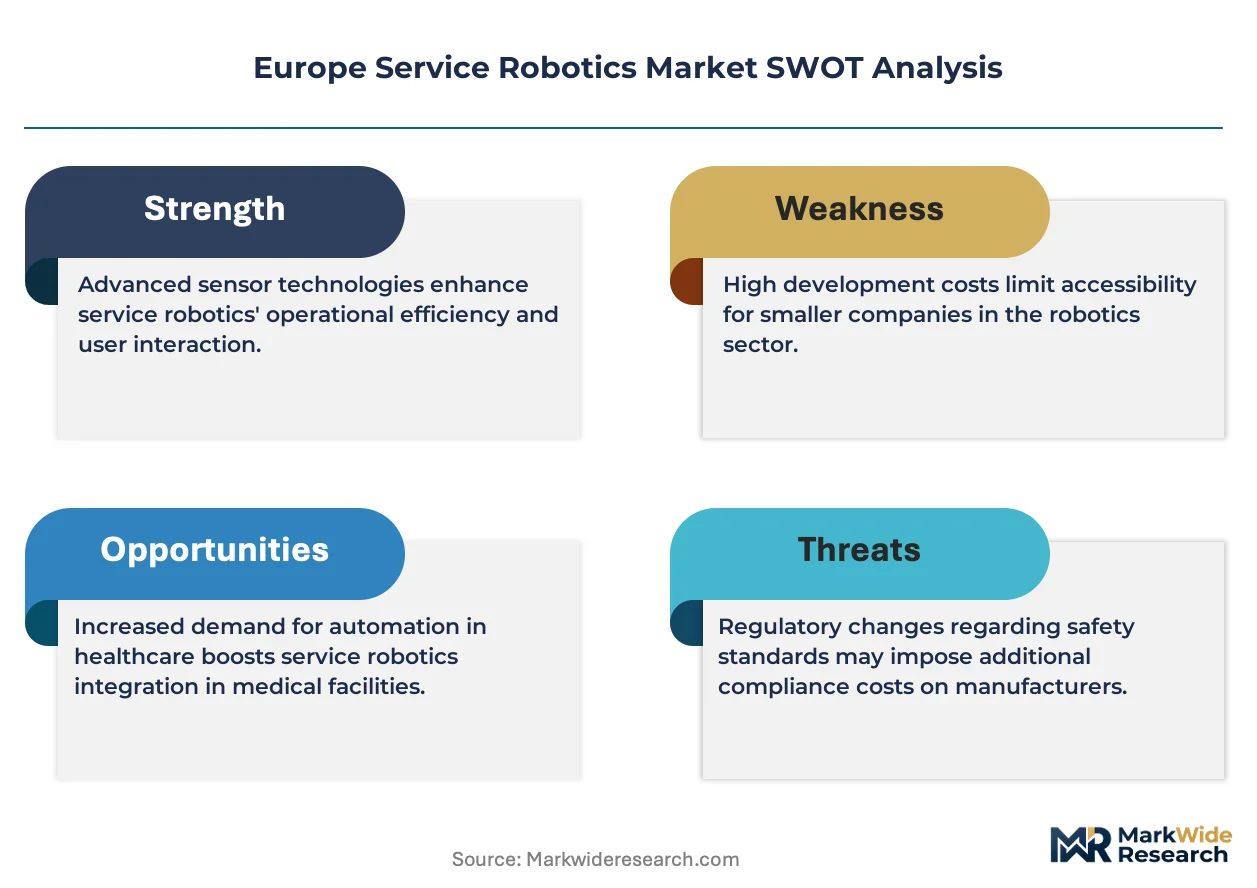
EMA guidelines on clinical evidence for medical robots, CE marking under the Machinery Directive, and the EU AI Act's risk-classification framework collectively shape product development timelines and market access conditions across member states. ECHA REACH compliance for battery chemistries and sensor coatings adds material-selection constraints that favor established supply chains. Stakeholders must monitor how the EU Green Deal's circular-economy requirements will alter end-of-life obligations for deployed fleets.
Market Dynamics
The EU AI Act is forcing service robot vendors to restructure compliance workflows around risk-classification tiers, decoupling certification costs from production scale and compressing margin structures for mid-tier hardware producers.
Growth Catalysts
- EMA clinical-evidence pathways:Medical robot developers in Germany and France accelerate hospital adoption through streamlined conformity routes for surgical assistance platforms.
- France hospitality automation:Hotel chains deploy reception and room-service units to address persistent labor gaps in Paris and Lyon metropolitan corridors.
- Force-torque sensor integration:Real-time haptic feedback loops enable safer human-robot collaboration in rehabilitation and patient-handling scenarios.
Market Restraints
- Lithium-ion supply concentration:Battery cell sourcing depends on East Asian cathode material flows, exposing European assemblers to input volatility and ECHA REACH compliance costs for alternative chemistries.
- EU AI Act conformity overhead:High-risk system classification triggers third-party audit requirements that extend product launch timelines by twelve to eighteen months for machine-learning-driven navigation stacks.
- Fixed-base industrial arms:Traditional articulated robots in manufacturing guard applications compete on total-cost-of-ownership metrics against mobile service platforms in logistics corridor retrofits.
Strategic Opportunities
- Spain agricultural monitoring:Olive and vineyard operators under EU Green Deal carbon-accounting mandates seek autonomous crop-scouting units to reduce diesel tractor hours.
- CE marking plus MDR dual certification:Vendors mastering concurrent Machinery Directive and Medical Device Regulation pathways capture hospital procurement contracts that competitors forfeit.
- Edge-AI and 5G convergence:Sub-10-millisecond latency networks in German industrial zones enable cloud-offloaded path planning for warehouse fleets without onboard GPU premium.
Industry Challenges
- Embedded systems firmware gaps:Real-time operating system expertise concentrates in automotive and aerospace clusters, forcing robotics firms to compete for scarce talent in Munich and Toulouse engineering markets.
- Sensor fusion integration:Lidar, IMU, and camera array calibration demands specialized test facilities that smaller vendors must access through shared European research infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Service Robotics Market |
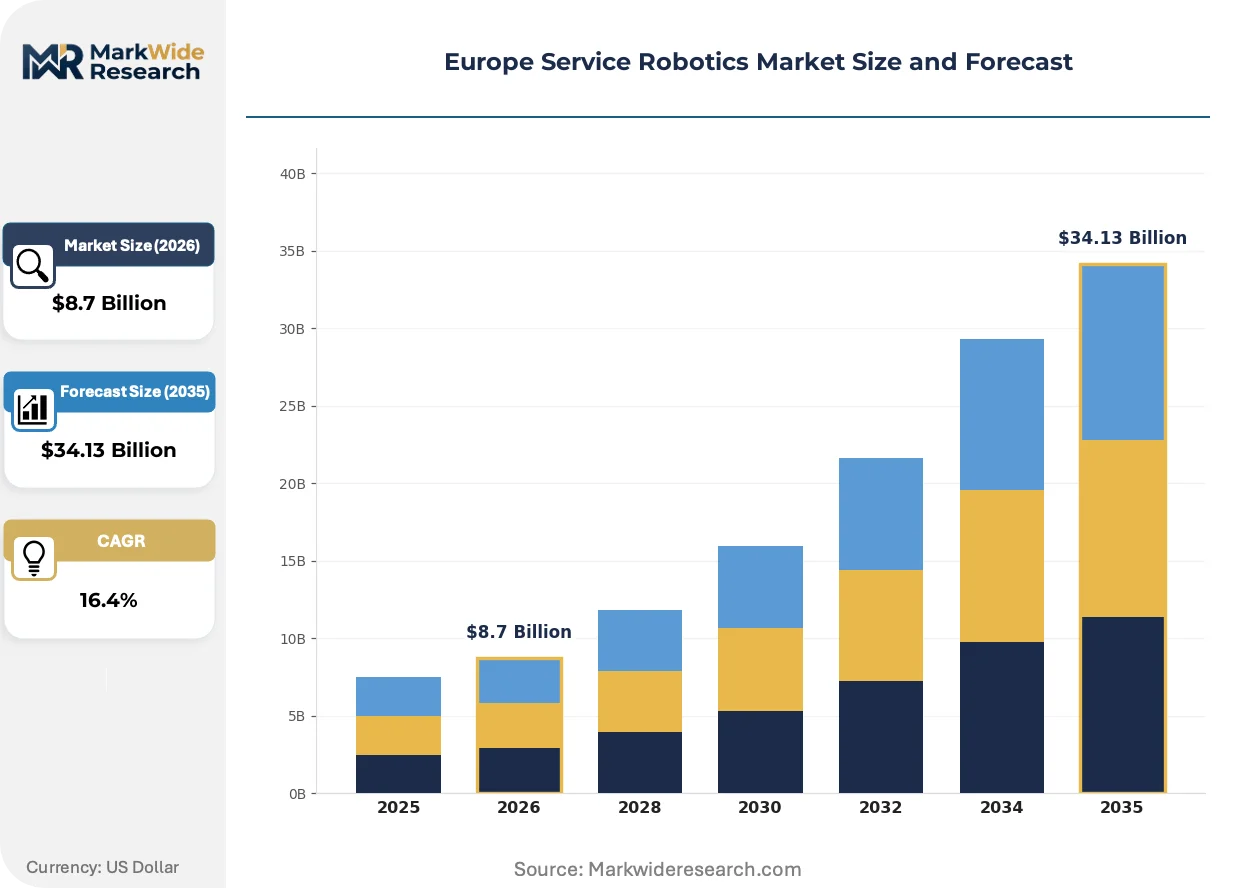
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Household, Medical, Logistic, Educational Technology: Artificial Intelligence, Machine Learning, Navigation, Sensors Application: Healthcare, Hospitality, Retail, Agriculture End User: Hospitals, Restaurants, Retail Stores, Farms |
| Companies Covered | KUKA AG, ABB Ltd., iRobot Corporation, SoftBank Robotics Group, FANUC Corporation, Boston Dynamics, Yaskawa Electric Corporation, PAL Robotics, Starship Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Service Robotics Market Trends and Innovations
Solid-state lidar arrays are absorbing cost compression pressure from silicon-photonics manufacturing scale, while regulatory frameworks harden around algorithmic transparency and end-of-life material recovery.
Solid-state lidar is absorbing the cost trajectory of CMOS fabrication economies, shifting unit economics from mechanical spinning assemblies to chip-scale packages. German logistics operators now specify solid-state units for warehouse navigation at price points fifty percent below legacy mechanical alternatives. This absorption of semiconductor scaling laws is compressing sensor supplier margins while expanding addressable fleet sizes for mid-market automation buyers.
EU AI Act risk-classification tiers are mandating conformity assessment body involvement for systems deploying adaptive behavior engines in public spaces. Manufacturers must document training data provenance and algorithmic decision boundaries to satisfy notified body scrutiny. Medical and hospitality segments face the steepest compliance ramps, with French hospital procurement teams now requiring AI Act technical documentation alongside traditional CE marking.
Hospital capital committees are unbundling robot hardware from service contracts, separating upfront platform acquisition from per-procedure software licensing. This procurement fragmentation pressures vendors to defend recurring revenue through adaptive feature releases rather than bundled maintenance. The shift is most visible in German university hospital networks, where procurement offices negotiate lidar hardware and navigation software through distinct tender processes.
Europe Service Robotics Market Segmentation
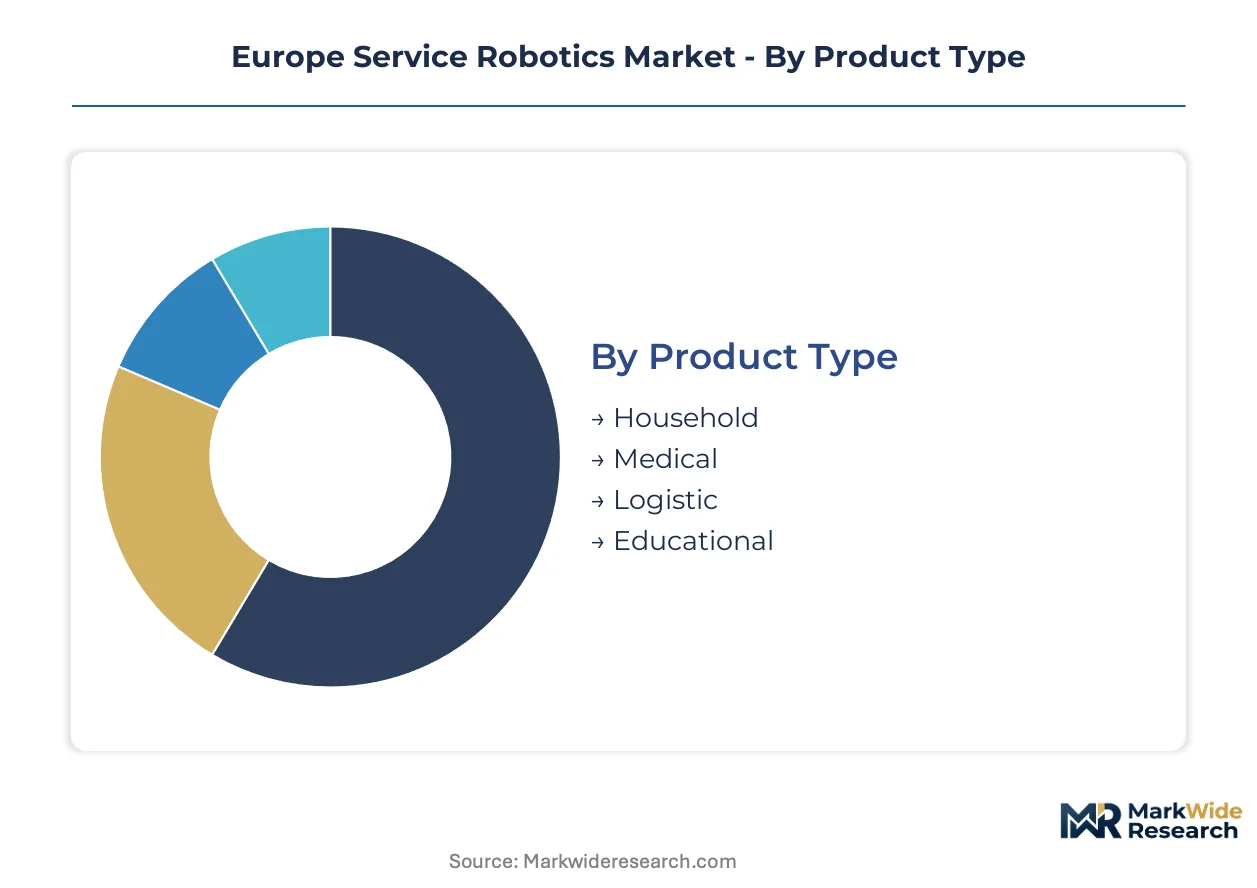
Service robotics segmentation in Europe reflects divergent integration architectures. Some segments deploy as standalone platforms with full autonomy stacks; others embed as subsystems within larger equipment networks. Understanding these integration patterns clarifies where vendors capture margin through software licensing versus hardware sales.
Product Type:
Household units operate as consumer-grade standalone appliances with minimal external connectivity, while medical and logistic platforms embed deeply into institutional IT infrastructure and building management systems.
- Medical:Surgical assistance platforms and rehabilitation exoskeletons integrate force-torque sensors with real-time haptic feedback at sub-50-millisecond loop cycles. German university hospital networks in Munich and Berlin drive procurement concentration as capital committees unbundle hardware from per-procedure software licensing.
- Logistic:Autonomous mobile robots for warehouse-to-last-yard transport incorporate lidar arrays and adaptive path-planning algorithms operating in 5G-enabled German industrial zones with sub-10-millisecond latency. Fleet operators specify solid-state lidar at price points fifty percent below legacy mechanical alternatives.
- Household:Vacuum and maintenance robots function as standalone consumer appliances with onboard navigation without external infrastructure dependency.
- Educational:Research and teaching platforms emphasize programmable architectures for university robotics labs and vocational training centers.
Medical leads volumes today; Logistic is gaining share fastest.
Technology:
Technology segments stratify by margin capture depth, with software layers commanding premium pricing over commoditized sensor hardware.
- Artificial Intelligence:Adaptive behavior engines and sensor fusion algorithms differentiate vendor offerings beyond mechanical platforms, attracting the deepest margin pools. EU AI Act risk-classification tiers mandate conformity assessment body involvement for public-space deployments, extending launch timelines twelve to eighteen months.
- Navigation:Real-time path-planning software stacks from industrial automation heritage vendors anchor mobile platform competitiveness in logistics corridors. ABB Ltd. competes specifically through this layer for warehouse fleet management.
- Machine Learning:Training data provenance documentation and algorithmic decision boundary transparency requirements under EU AI Act scrutiny concentrate development resources.
- Sensors:Lidar, IMU, and camera array hardware faces cost compression from silicon-photonics manufacturing scale, compressing supplier margins while expanding addressable fleet sizes.
Navigation leads volumes today; Artificial Intelligence climbs the fastest.
Application:
Application segments map to distinct regulatory exposure profiles, with healthcare and hospitality facing the steepest EU AI Act compliance ramps.
- Healthcare:Surgical assistance and patient-handling robots require concurrent CE marking under the Machinery Directive and Medical Device Regulation pathways. EMA clinical-evidence guidelines accelerate hospital adoption for platforms meeting dual certification standards.
- Hospitality:Reception and room-service automation addresses persistent labor gaps in Paris and Lyon metropolitan corridors. French hotel chains now require AI Act technical documentation alongside traditional conformity marking.
- Retail:Customer engagement and inventory management platforms deploy in humanoid architectures for research and interaction scenarios.
- Agriculture:Autonomous crop-scouting units reduce diesel tractor hours for olive and vineyard operators under EU Green Deal carbon-accounting mandates.
Healthcare leads volumes today; Hospitality is expanding most quickly.
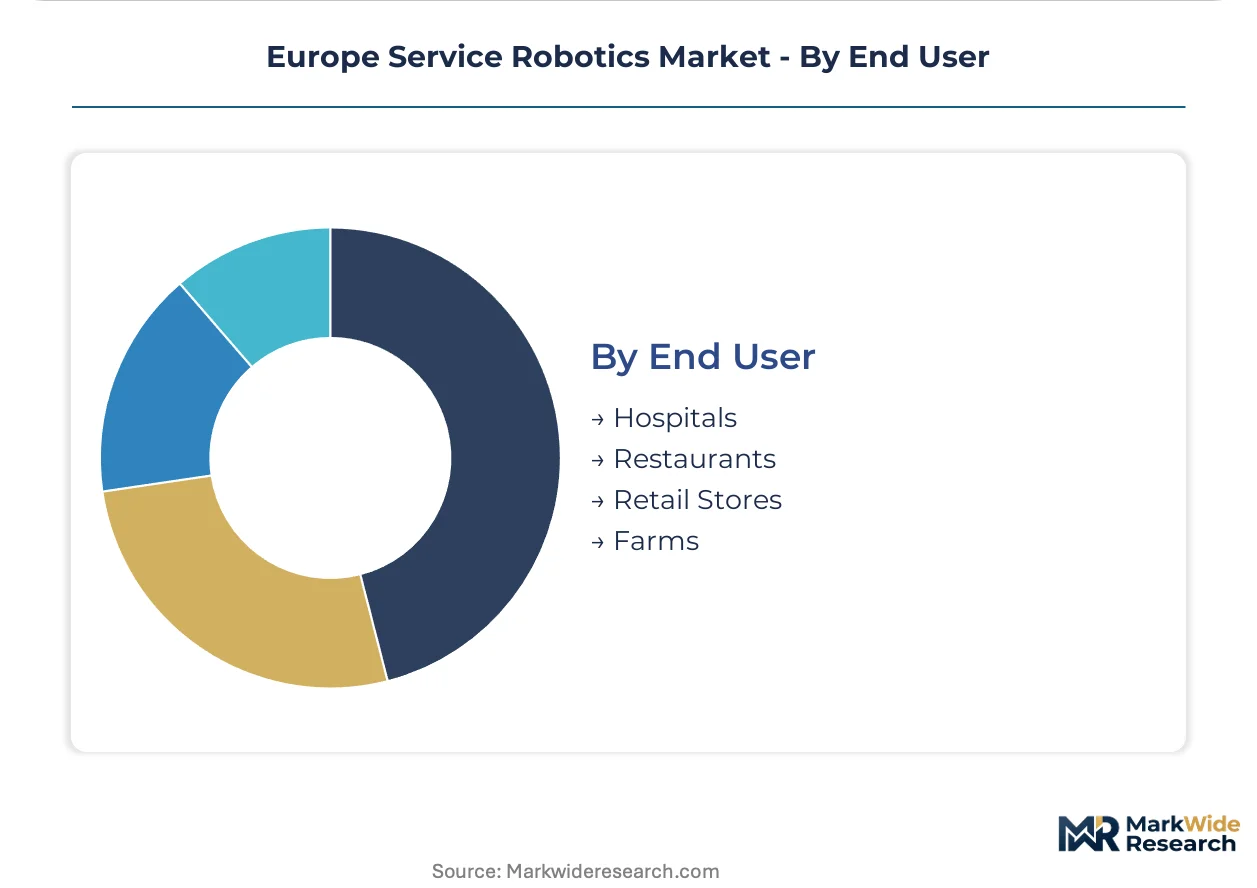
End User:
End user categories diverge sharply in procurement sophistication, with hospitals negotiating unbundled tenders while farms and restaurants seek turnkey solutions.
- Hospitals:German capital committees separate lidar hardware and navigation software into distinct tender processes, pressuring vendors to defend recurring revenue through adaptive feature releases rather than bundled maintenance.
- Restaurants:Food service automation in France concentrates on room-service delivery and reception functions with simpler integration requirements than clinical environments.
- Retail Stores:Inventory and customer-facing platforms prioritize ease of deployment over customization depth.
- Farms:Spanish olive and vineyard operators under EU Green Deal mandates seek autonomous units with minimal IT infrastructure dependency.
Hospitals lead volumes today; Farms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Munich, Stuttgart, and Paris anchor European service robotics development. These metropolitan concentrations host embedded systems expertise, sensor calibration facilities, and university-industry research partnerships that feed vendor pipelines.
Germany
Autonomous disinfection units and surgical assistance platforms drive hospital procurement in Berlin and Munich. The EU AI Act's risk-classification framework triggers third-party audit requirements that extend product launches twelve to eighteen months. Bavaria's industrial automation heritage centers on KUKA AG's production facilities near Augsburg.
France
Hotel chains in Paris and Lyon deploy reception and room-service automation to address persistent hospitality labor gaps. EMA clinical-evidence guidelines accelerate medical robot adoption when platforms meet dual CE marking and Medical Device Regulation standards. The Île-de-France cluster concentrates PAL Robotics' humanoid development for retail interaction scenarios.
United Kingdom
Logistics corridor automation in the Midlands and Southeast absorbs mobile platforms for warehouse-to-last-yard transport. GDPR compliance requirements shape data governance for cloud-offloaded path planning systems. London's financial-technology crossover supplies venture funding for early-stage navigation software vendors.
Spain
Olive and vineyard operators in Andalusia and Catalonia seek autonomous crop-scouting units under EU Green Deal carbon-accounting mandates. ECHA REACH compliance for battery chemistries constrains material selection for agricultural platforms. The Basque Country hosts shared research infrastructure for sensor fusion calibration that smaller vendors access.
Italy
Lombardy's manufacturing base integrates service robots into logistics networks alongside traditional industrial arms. The Machinery Directive's CE marking requirements govern mobile platform deployment in Milan-Turin industrial corridors. Emilia-Romagna's automotive supply chain feeds force-torque sensor component sourcing for rehabilitation exoskeletons.
Europe Service Robotics Market Competitive Landscape
The competitive structure tilts toward industrial-automation heritage players with established certification workflows. Mid-tier hardware producers face margin compression as EU AI Act compliance costs decouple from production scale. Two strategic archetypes dominate: diversified industrial conglomerates leveraging navigation software stacks, and specialized humanoid developers sustained by European grant programs. Competitive moves concentrate on M&A for sensor technology access and strategic partnerships for 5G-enabled fleet management.
Among Germany-based industrial conglomerates, KUKA AG anchors the automation-heritage tier, while ABB Ltd. represents the Swiss-German navigation software specialization. PAL Robotics exemplifies the grant-funded humanoid development archetype with its Barcelona-based research orientation. These three occupy distinct competitive positions: production scale, software differentiation, and architectural specialization respectively.
| Leading Market Players |
|---|
| KUKA AG |
| ABB Ltd. |
| iRobot Corporation |
| SoftBank Robotics Group |
| FANUC Corporation |
| Boston Dynamics |
| Yaskawa Electric Corporation |
| PAL Robotics |
| Starship Technologies |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between CE-marked medical platforms and uncertified hospitality units splits pricing power across vendor tiers, with German hospital procurement offices commanding unbundled hardware-software tenders while French hotel chains absorb bundled service premiums. This bifurcation concentrates margin capture in firms mastering dual Machinery Directive and Medical Device Regulation pathways, while squeezing mid-tier producers unable to amortize EU AI Act compliance overhead across fleet scale.
Pricing Analysis
Bundled-versus-unbundled service splits dominate pricing architecture, with German university hospitals separating lidar hardware acquisition from per-procedure navigation software licensing. Price differentiation rests on certification tier—dual CE marking plus MDR compliance commands premium positioning against single-conformity alternatives. Cost compression in solid-state lidar sensor tiers intensifies pricing pressure from silicon-photonics manufacturing scale. Small-to-mid hospitality operators exhibit highest price sensitivity, while hospital capital committees prioritize compliance assurance over unit economics.
Supply Chain Analysis
Freight cost volatility from East Asian battery component flows shapes European assembler sourcing strategies, with lithium-ion cathode materials drawing primarily from China, South Korea, and Japan. Solid-state lidar arrays rest on Taiwan and USA semiconductor fabrication, while force-torque sensor components feed from Germany and Japan automotive supply chains. Single-source vulnerability concentrates in rare-earth magnet sourcing for drive motors. Distribution runs through direct OEM relationships for hospital procurement and channel partners for agricultural and hospitality deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Spain's agricultural automation demand and Germany's compliance-heavy hospital procurement creates divergent margin profiles, with EU Green Deal carbon-accounting mandates in Andalusia offering lighter regulatory entry than Bavaria's dual certification requirements.
For Market Incumbents: Anchor defensive positioning through backward integration into force-torque sensor production and captive supply of solid-state lidar components, countering margin erosion from EU AI Act audit overhead. Prioritize certification investment in concurrent Machinery Directive and Medical Device Regulation pathways to capture hospital contracts that competitors forfeit. Channel control through direct procurement relationships with German university hospital networks reinforces pricing power against software-unbundling trends. For New Entrants and Emerging Players: EU AI Act risk-classification tiers in France open a window for adaptive behavior engine specialists targeting hospitality reception automation with lighter conformity burdens than medical-grade platforms. White-space concentration lies in Spanish olive and vineyard crop-scouting units under Green Deal carbon mandates, with minimal IT infrastructure requirements lowering integration barriers. Go-to-market leverage rests on 5G-enabled fleet management partnerships with German logistics operators seeking cloud-offloaded path planning. For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act compliance costs decouple from production scale, favoring acquisition of mid-tier hardware producers with established CE marking workflows but strained margin structures. Long-term viability frames around sensor fusion software differentiation and grant-funded humanoid architecture pipelines. Watch for inflection in hospital procurement fragmentation—unbundled tender prevalence signals shift toward recurring-revenue software valuations over hardware multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Mastery | Captures German hospital procurement contracts requiring concurrent CE marking and MDR compliance. |
| Sensor Technology Acquisition | Absorbs solid-state lidar specialists to compress unit costs for logistics fleet expansion. |
| 5G Fleet Management Partnership | Enables cloud-offloaded path planning in Bavarian industrial zones without onboard GPU premiums. |
| Agricultural Automation Launch | Targets Spanish olive operators under EU Green Deal diesel reduction mandates. |
| Grant-Funded R&D Expansion | Sustains humanoid architecture development through European research infrastructure access. |
Research Methodology
Coverage spans Western Europe with primary inputs from each major national market, combining structured interviews with hospital procurement managers, robotics platform engineers, agricultural cooperative technical directors, and hospitality operations executives with secondary validation. Regulatory filings from EMA and notified body documentation, EU AI Act implementation guidance, hospital procurement database records, and industrial automation trade flows support triangulation. Bottom-up unit deployment estimates and top-down market sizing reconcile across the analysis.
Rate-of-change decomposition separates hardware volume trajectories from software value expansion across product type, technology layer, application segment, and end-user procurement sophistication dimensions. CAGRs derive from segment-specific growth drivers—medical adoption curves, logistics automation penetration, and agricultural diesel displacement mandates—weighted against regulatory timeline constraints. Forecast inputs incorporate EU AI Act risk-classification implementation schedules and 5G network deployment cadence in German industrial corridors.
Revisions become necessary when EMA clinical-evidence guidelines shift, EU AI Act conformity assessment body capacity constraints extend audit timelines, or lithium-ion supply concentration disrupts European assembler input flows. Forecasts reflect documented assumptions about regulatory implementation pace and technology cost curves. Stakeholders should weight assumptions against their own operating context and certification readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Robot Operating System Market