
 Europe Logistics Robotics Market | 2026-2036
Europe Logistics Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Logistics Robotics Market Insights
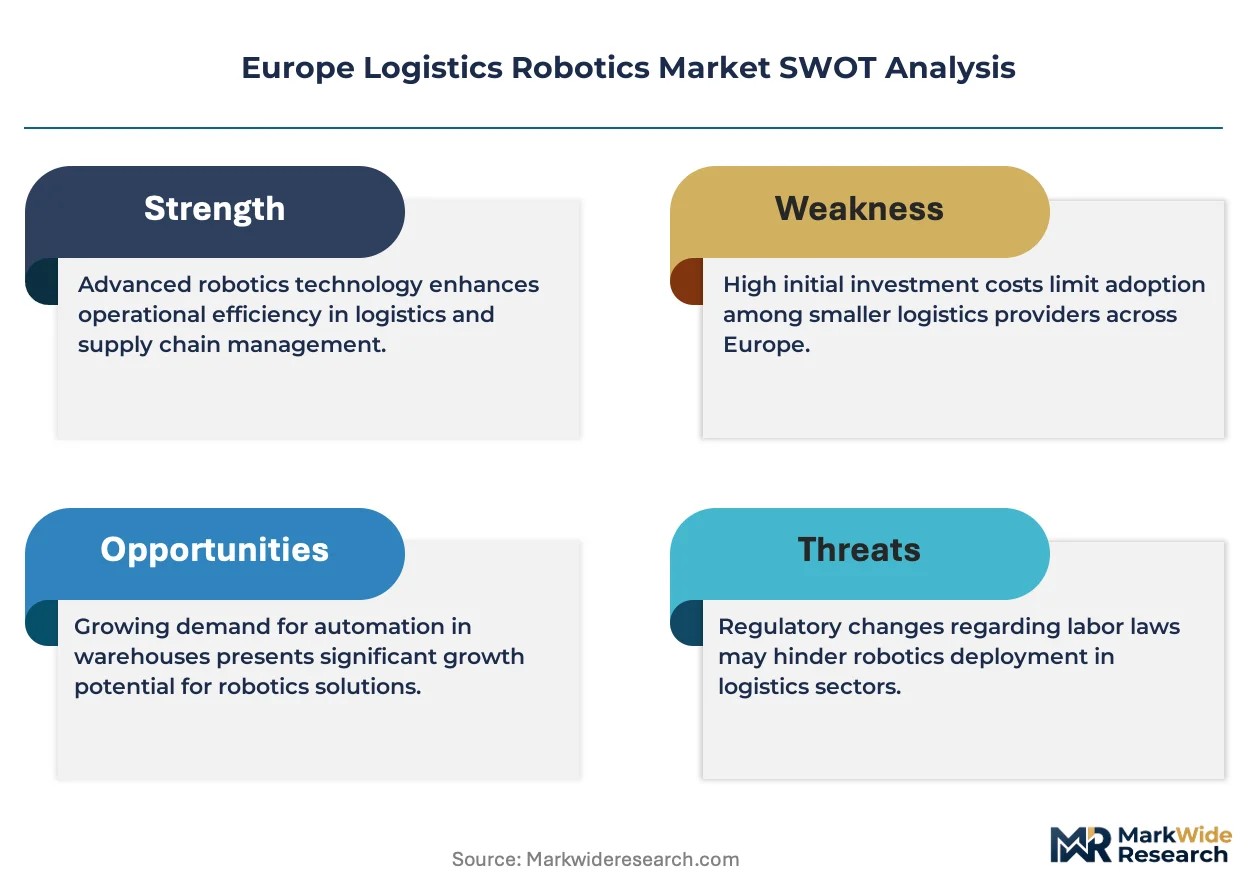
Modular robot-as-a-service bundling is rebalancing procurement economics for mid-size 3PL operators across Europe. KION Group AG leverages its industrial truck installed base to anchor automation retrofit contracts in Central European distribution centers. Swisslog Holding AG competes through deep specialization in pharmaceutical cold-chain robotic systems, a segment where regulatory compliance creates sticky customer relationships. Mobile Industrial Robots extends its footprint via open fleet-management architecture that reduces integration friction for multi-vendor warehouses.
Europe logistics robotics encompasses autonomous and semi-autonomous systems engineered for material transport, sortation, and handling within supply chain nodes, typically operating at payload capacities from 50 kg to 1,500 kg with navigation precision within ±10 mm. These systems execute repetitive logistics tasks under programmable logic controllers or AI-driven decision frameworks, primarily to compress order cycle times and mitigate labor volatility in fulfillment networks. Autonomous Mobile Robots now command the fastest expansion trajectory among product types, driven by flexibility advantages over fixed conveyor infrastructure in seasonal-demand environments. Warehouse Management applications sustain the largest revenue pool, though Packaging Solutions is narrowing the gap as e-commerce shippers automate final-mile preparation. AI-Driven Automation technology captures disproportionate R&D investment as integrators embed predictive maintenance algorithms to reduce unplanned downtime.
The EU Machinery Directive and CE marking framework mandate functional safety validation for collaborative robot deployments, elevating compliance costs but also screening out low-specification imports. ECHA REACH restrictions on battery chemistries are reshaping supplier qualification criteria for mobile robot power systems. Germany's KBA and France's ANSM both influence sector standards through national workplace safety enforcement, creating a layered regulatory landscape. Stakeholders must monitor how the EU AI Act's risk-classification rules will recalibrate liability structures for fully autonomous sorting and picking systems.
Market Dynamics
The EU AI Act's risk-classification framework is recalibrating liability structures for fully autonomous sorting and picking systems, forcing integrators to redesign decision architectures before the enforcement window closes.
Growth Catalysts
- Rhine-Ruhr logistics corridor concentration:Germany's dense warehousing cluster generates network effects where AMR deployments achieve faster payback through shared maintenance infrastructure and technician pools.
- EU Machinery Directive harmonization:CE marking mutual recognition accelerates cross-border fleet deployments for 3PL operators serving pan-European e-commerce networks.
- Pharmaceutical cold-chain automation:EMA temperature-compliance mandates drive robotic handling investments in vaccine distribution centers across Benelux and Alpine regions.
Market Restraints
- Lithium-ion chemistry constraints:ECHA REACH restrictions on nickel-cobalt battery formulations limit supplier qualification for mobile robot power systems, compressing vendor options.
- Safety certification bottlenecks:KBA and ANSM divergent enforcement timelines create multi-month delays for collaborative robot deployments in Franco-German cross-border facilities.
- Fixed infrastructure substitution:Retrofit-ready conveyor systems from industrial truck incumbents compete for capital allocation against greenfield AMR installations in brownfield warehouses.
Strategic Opportunities
- Polish warehouse automation gap:Central European distribution hubs near Warsaw and Łódź remain underpenetrated for robotic sortation relative to throughput growth in apparel and electronics fulfillment.
- CSRD carbon reporting integration:The EU Corporate Sustainability Reporting Directive creates demand for AMR fleet energy-monitoring modules that quantify Scope 3 logistics emissions reductions.
- 5G-AMR convergence:Private network deployments in Rotterdam and Hamburg port zones enable sub-10ms latency for coordinated multi-robot swarms in high-density container handling.
Industry Challenges
- Functional safety engineering scarcity:Certified robot safety assessors under ISO 10218 remain concentrated in Southern Germany, extending commissioning timelines for Nordic and Iberian deployments.
- Warehouse Management System fragmentation:Proprietary fleet-management protocols from established automation vendors create integration friction for multi-brand robot deployments in consolidated 3PL networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Logistics Robotics Market |
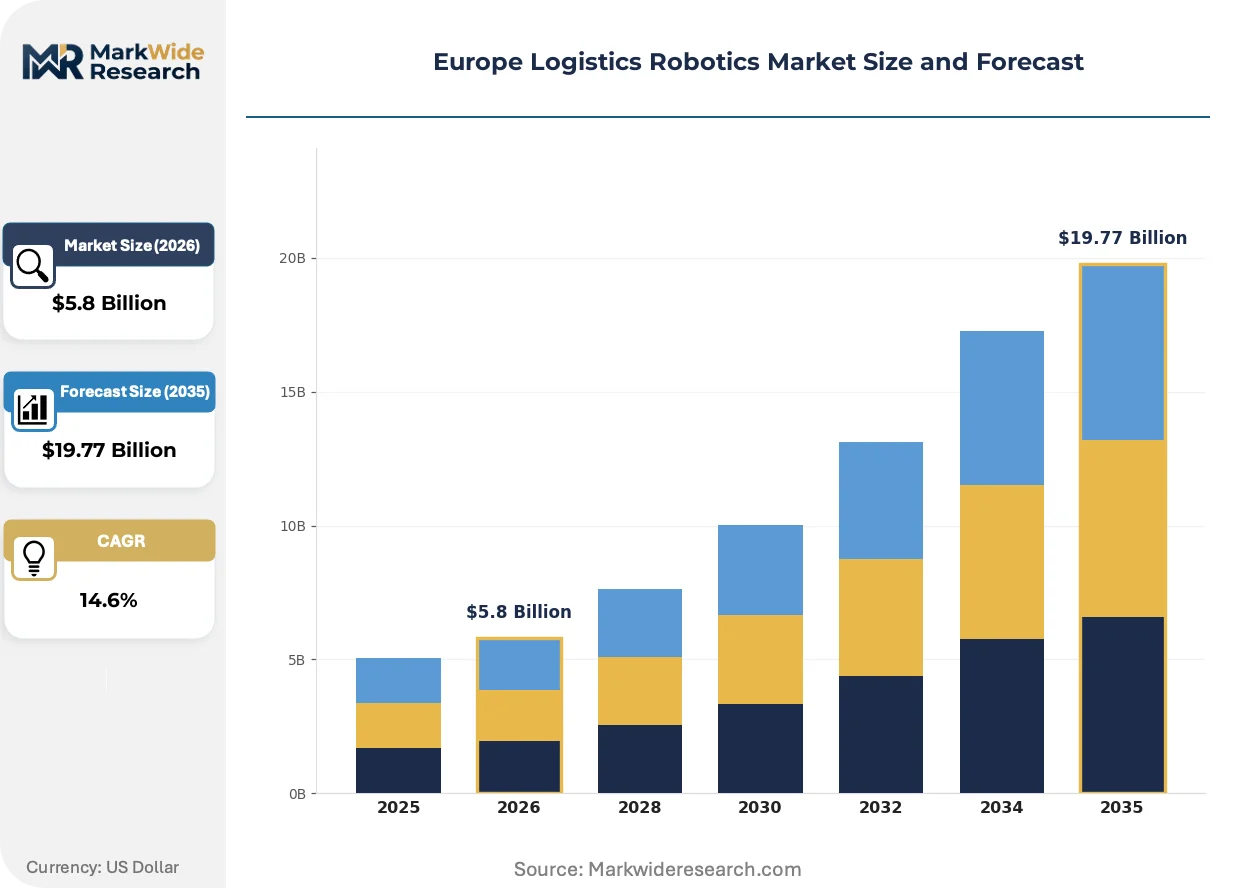
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotic Arms, Autonomous Mobile Robots, Sorting Systems Application: Warehouse Management, Order Fulfillment, Inventory Management, Packaging Solutions End User: E-commerce, Retail, Manufacturing, Third-Party Logistics Technology: AI-Driven Automation, Machine Learning, Computer Vision, Sensor Technology |
| Companies Covered | ABB Ltd., KUKA AG, SSI Schaefer AG, KION Group AG, KNAPP AG, Mobile Industrial Robots, Swisslog Holding AG, Dematic, EK Robotics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Logistics Robotics Market Trends and Innovations
Open fleet-management architectures are dismantling single-vendor lock-in across European distribution centers, enabling modular procurement that matches robot capabilities to specific warehouse zones rather than enterprise-wide standardization.
Edge-based AI inference is decentralizing robot decision-making from centralized warehouse servers to onboard compute units in AMRs. Pharmaceutical 3PLs in Switzerland and Northern Italy are deploying these systems for real-time contamination detection in cleanroom environments. The shift compresses response latency for obstacle avoidance while reducing network infrastructure costs in retrofit facilities.
The EU AI Act's high-risk system classification is mandating conformity assessments for autonomous picking robots before market placement. German automotive suppliers are front-loading documentation costs to secure CE-plus-AI dual certification ahead of the 2026 enforcement cliff. This regulatory sequencing favors established integrators with existing notified body relationships over new market entrants.
Mid-size 3PLs are unbundling automation procurement from long-term service contracts, preferring robot-as-a-service arrangements with usage-based pricing. Dutch and Belgian fulfillment operators pioneered this shift during peak-season volatility in 2024. The model now spreads to French grocery e-commerce networks seeking to align automation costs with transaction volumes rather than fixed asset depreciation schedules.
Europe Logistics Robotics Market Segmentation
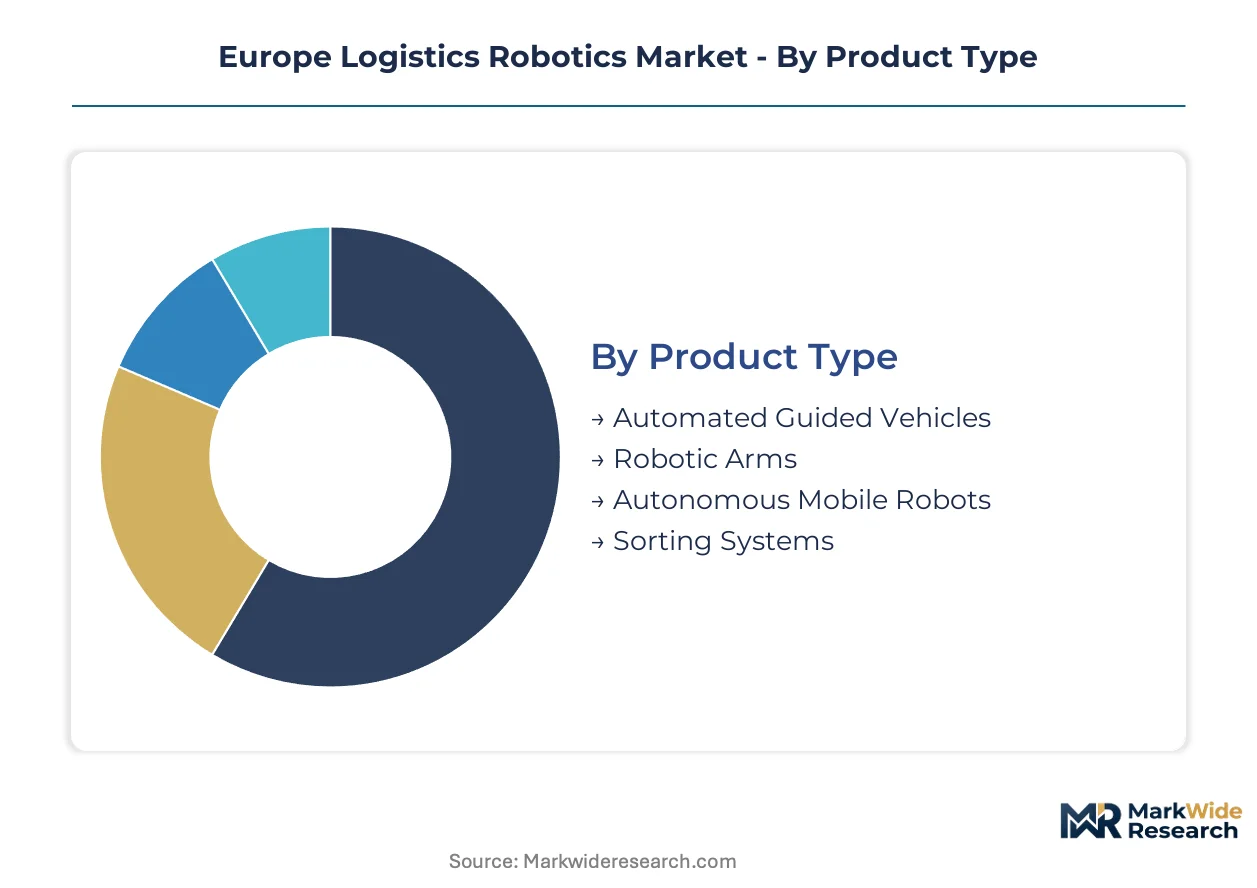
Segmentation in Europe logistics robotics reveals how procurement patterns split between standardized platforms for rapid deployment and engineered-to-order systems for specialized compliance environments. Understanding these fault lines clarifies where integrators can capture margin through customization versus where scale economies dominate.
Product Type:
Standardized navigation platforms compete with bespoke mechanical configurations across this category, with procurement decisions hinging on payload specificity and facility retrofit constraints.
- Autonomous Mobile Robots:These systems operate on lidar or vision-based simultaneous localization and mapping with payload ranges from 50 kg to 1,500 kg. Demand concentrates in Germany's Rhine-Ruhr corridor where shared technician pools and maintenance infrastructure accelerate payback calculations for 3PL fleet operators. Flexibility advantages over fixed conveyor systems drive replacement cycles in seasonal-demand fulfillment networks.
- Sorting Systems:High-throughput parcel sortation employs cross-belt or tilt-tray mechanisms handling 6,000 to 15,000 items hourly. Belgian and Dutch e-commerce hubs deploy these for final-mile preparation where throughput density justifies capital intensity. Regulatory pressure from the EU AI Act's risk classification is forcing integrators to front-load conformity documentation for autonomous sortation modules.
- Automated Guided Vehicles:Magnetic tape or inductive wire guidance systems serve predictable routes in automotive assembly plants with lower navigation complexity.
- Robotic Arms:Articulated manipulators with six or seven degrees of freedom handle pick-and-place operations in pharmaceutical cold-chain facilities requiring ISO 14644 cleanroom compliance.
Leading the category by volume: Autonomous Mobile Robots. Growing fastest: Sorting Systems.
Application:
Volume concentration versus margin capture varies sharply across this category, with operational criticality determining pricing power for integrators.
- Warehouse Management:Fleet coordination software and physical automation for put-away, replenishment, and cycle counting functions. German distribution centers sustain the largest revenue pool here, though saturation in mature markets is compressing expansion rates relative to emerging applications.
- Packaging Solutions:Automated carton erection, void fill insertion, and label application for e-commerce shipment preparation. French grocery networks are expanding these installations to align automation costs with transaction volatility through robot-as-a-service contracting structures.
- Order Fulfillment:Piece-picking and consolidation systems for direct-to-consumer shipment assembly.
- Inventory Management:Cycle counting drones and RFID-enabled robotic auditors for stock accuracy verification.
Dominant by revenue: Warehouse Management. Steepest expansion trajectory: Packaging Solutions.
End User:
Customer sophistication and in-house engineering capability create distinct service requirements across this category.
- Third-Party Logistics:Contract operators serving multiple brand clients require rapid reconfiguration capabilities and multi-tenant WMS integration. Polish fulfillment hubs near Warsaw and Łódź remain underpenetrated for robotic sortation relative to throughput growth in apparel and electronics verticals.
- E-commerce:Pure-play digital retailers prioritize peak-season elasticity and same-day fulfillment velocity. The sector's transaction-volume volatility has pioneered usage-based robot-as-a-service contracting across Benelux operations.
- Retail:Omnichannel grocers and general merchandise chains blending store fulfillment with distribution center automation.
- Manufacturing:Automotive and pharmaceutical producers with captive logistics operations and stringent traceability requirements.
Largest installed base: Third-Party Logistics. Gaining share fastest: E-commerce.
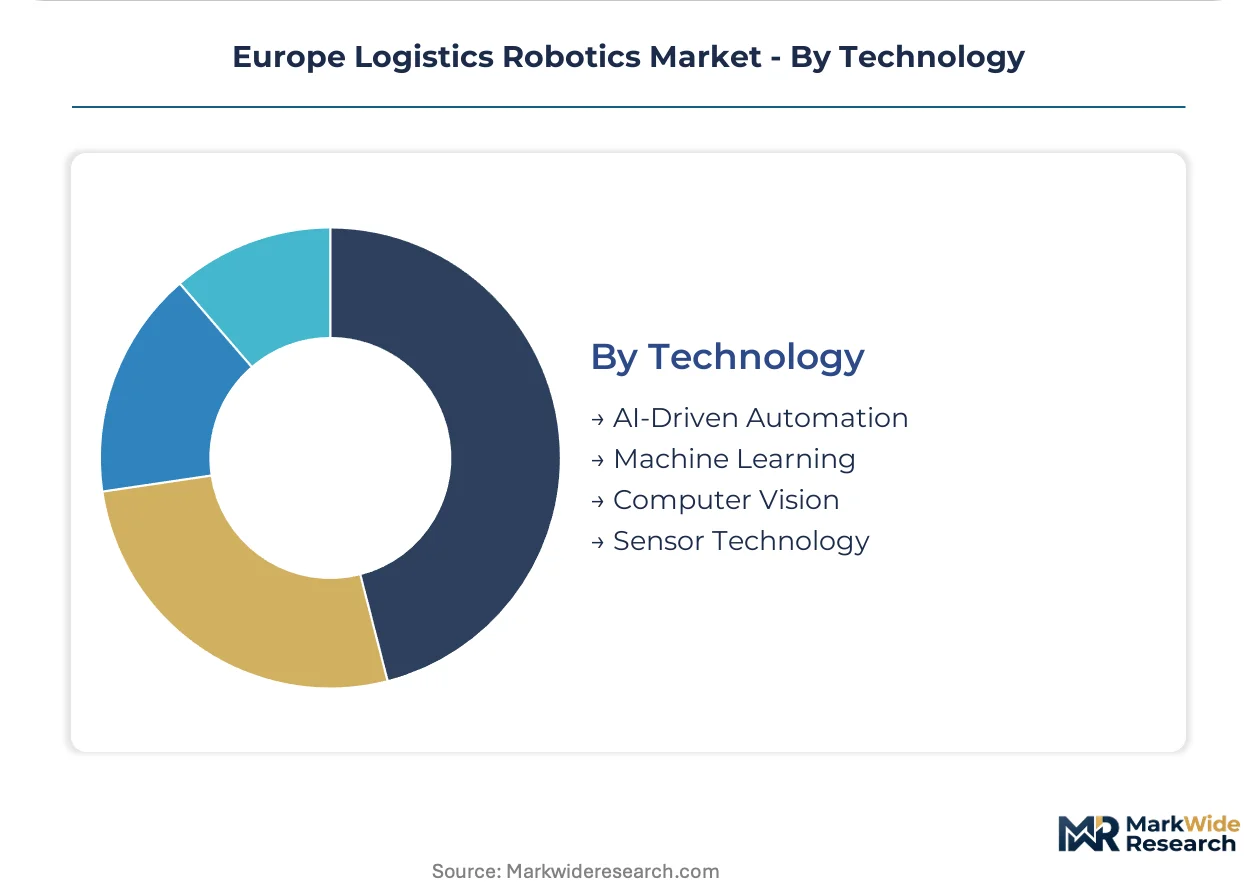
Technology:
Proprietary versus open-architecture approaches divide competitive positioning in this category, with interoperability emerging as a procurement priority.
- AI-Driven Automation:Predictive maintenance algorithms and dynamic path optimization embedded in fleet management platforms. German automotive suppliers are securing CE-plus-AI dual certification ahead of enforcement windows to capture first-mover positioning in high-risk system classifications.
- Computer Vision:Depth cameras and convolutional neural networks for object recognition, damage detection, and quality verification. Swiss pharmaceutical 3PLs deploy these for real-time contamination detection in cleanroom robotic handling.
- Machine Learning:Reinforcement learning for pick-point optimization and demand forecasting integration.
- Sensor Technology:Ultrasonic, infrared, and tactile arrays for proximity detection and collision avoidance in collaborative robot deployments.
Commanding disproportionate R&D investment: AI-Driven Automation. Expanding most quickly: Computer Vision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of logistics robotics hardware concentrates in Germany's industrial belt, while consumption spreads across distribution corridors in France, the Netherlands, and Poland. German manufacturers export AMR platforms to fulfillment operators throughout the continent. Southern European markets remain import-dependent for sophisticated sortation systems.
Germany
Automotive assembly plants in Baden-Württemberg and Bavaria are expanding autonomous mobile robot fleets for just-in-sequence material delivery. KBA enforcement of the EU Machinery Directive accelerates certification timelines for collaborative robot deployments. The Rhine-Ruhr logistics corridor generates network effects where shared technician pools and maintenance infrastructure compress AMR payback periods for 3PL operators.
France
Grocery e-commerce networks in Île-de-France are adopting robot-as-a-service structures to align automation costs with transaction volatility. ANSM divergent enforcement timelines with German counterparts create multi-month delays for collaborative robot deployments in Franco-German cross-border facilities. The Paris metropolitan warehousing cluster is expanding automated packaging solutions for final-mile preparation.
Netherlands
Rotterdam port zone operators are deploying private 5G networks to enable sub-10ms latency for coordinated multi-robot swarms in high-density container handling. ECHA REACH restrictions on battery chemistries are reshaping supplier qualification criteria for mobile robot power systems across Dutch distribution centers. Benelux fulfillment operators pioneered usage-based robot contracting during peak-season volatility.
Poland
Central European distribution hubs near Warsaw and Łódź remain underpenetrated for robotic sortation relative to throughput growth in apparel and electronics fulfillment. EU Cohesion Fund infrastructure investments are upgrading warehouse connectivity in preparation for automation retrofits. The country's logistics real estate expansion is attracting AMR fleet operators seeking lower labor cost baselines than Western European alternatives.
Switzerland
Pharmaceutical 3PLs in the Basel-Zurich corridor are deploying edge-based AI inference systems for real-time contamination detection in cleanroom robotic handling. Swissmedic standards for temperature-compliance mandates drive robotic handling investments in vaccine distribution centers. Alpine region logistics facilities are specializing in high-value cold-chain automation where regulatory compliance creates sticky customer relationships.
Europe Logistics Robotics Market Competitive Landscape
The competitive structure tilts toward industrial conglomerates with captive distribution channels. KION Group AG leverages its industrial truck installed base to anchor retrofit contracts, while SSI Schaefer AG and KNAPP AG compete through deep warehouse system integration capabilities. Three archetypes dominate: diversified industrial technology groups, pure-play automation specialists, and forklift incumbents extending into robotics. Consolidation activity concentrates on software stack acquisitions and regional system integrator roll-ups.
Among Germany-based industrial groups, KUKA AG and KION Group AG exemplify the conglomerate archetype with cross-selling advantages into automotive and logistics end-markets. Swisslog Holding AG occupies a specialist position anchored in pharmaceutical cold-chain compliance requirements. Mobile Industrial Robots represents the open-architecture challenger, competing through fleet-management interoperability that reduces integration friction for multi-vendor warehouses.
| Leading Market Players |
|---|
| ABB Ltd. |
| KUKA AG |
| SSI Schaefer AG |
| KION Group AG |
| KNAPP AG |
| Mobile Industrial Robots |
| Swisslog Holding AG |
| Dematic |
| EK Robotics |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up automation specialists in Germany's industrial belt are consolidating component sourcing and service networks, compressing procurement costs for mid-size 3PL buyers while elevating pricing discipline among integrated incumbents serving pharmaceutical cold-chain compliance segments.
Pricing Analysis
Cost-down pressure on mid-tier AMR fleets accelerates because ECHA REACH battery chemistry restrictions are disqualifying low-cost Asian suppliers from CE marking pathways. Three-tier pricing structure across premium certified, standard compliant, and economy retrofit levels separates KION Group's integrated service bundles from Swisslog's specialized pharmaceutical configurations and Mobile Industrial Robots' open-architecture hardware. Price differentiation hinges on ISO 10218 safety certification grade and after-sales technician density. E-commerce operators in Benelux demonstrate highest price sensitivity through usage-based RaaS contracting, while Swiss pharmaceutical 3PLs absorb premium pricing for cleanroom-validated systems.
Supply Chain Analysis
Freight cost volatility from Asia-to-Europe container lanes is forcing AMR manufacturers toward regional component stocking in Rotterdam and Hamburg port zones. Hardware assembly concentrates in Germany, Czech Republic, and Poland, with lidar sensors and servo motors drawing from German automotive supplier networks. Lithium-ion cell supply rests on South Korean and Chinese producers subject to ECHA REACH nickel-cobalt restrictions. Single-source vulnerability in safety-certified controller boards creates qualification bottlenecks. Distribution runs through KION Group's captive industrial truck service infrastructure and independent system integrator channels serving fragmented 3PL networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 10218 safety assessor scarcity in Southern Germany is constraining commissioning capacity, propping pricing power for certified integrators while extending delivery timelines for Nordic and Iberian deployments.
For Market Incumbents: Extend CE-plus-AI dual certification coverage ahead of EU AI Act enforcement windows to preempt regulatory displacement of uncertified competitors. Consolidate backward integration into safety controller board production to reduce single-source exposure from Asian semiconductor suppliers. Anchor retrofit contracts through KION Group's industrial truck installed base density in Rhine-Ruhr distribution centers. For New Entrants and Emerging Players: The price-point gap between Swisslog's premium pharmaceutical systems and economy AMR platforms in Polish fulfillment hubs offers white-space entry through modular cold-chain attachments. Target Warsaw and Łódź distribution corridors where throughput growth outpaces robotic sortation penetration. Lead with open fleet-management protocols that reduce WMS integration friction for multi-tenant 3PL operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap system integrators with existing notified body relationships in Germany's industrial belt. Five-to-ten-year viability hinges on software stack differentiation rather than hardware commoditization. Monitor ECHA battery chemistry rulings as inflection signal for supplier qualification shakeouts.| Strategic Initiative | Industry Significance |
|---|---|
| CE-Plus-AI Dual Certification | EU AI Act risk-classification rules recalibrate liability for autonomous sorting systems in German automotive plants. |
| Backward Integration into Safety Controllers | In-house production of ISO 10218-certified boards reduces qualification bottlenecks from Asian semiconductor suppliers. |
| Robot-as-a-Service Platform Launch | Usage-based pricing aligns automation costs with Benelux e-commerce transaction volatility. |
| 5G-AMR Private Network Deployment | Sub-10ms latency enables coordinated swarms in Rotterdam and Hamburg port container handling. |
| Polish Distribution Hub Expansion | Warsaw and Łódź corridors remain underpenetrated for robotic sortation relative to apparel and electronics throughput growth. |
Research Methodology
Document review covered EU regulatory filings, ECHA REACH substance restrictions, and CE marking databases, complemented by interviews with warehouse operations directors at 3PL providers, automation procurement leads at German automotive OEMs, fleet management software engineers, and notified body certification assessors. Secondary validation drew from KBA enforcement guidelines, ANSM workplace safety directives, EU AI Act implementation drafts, and customs trade data for robotics component flows. Bottom-up unit economics for AMR deployments were triangulated against top-down market sizing from industrial automation trade associations.
Segmentation outputs across product type, application, end user, and technology dimensions were modeled over the projection horizon, with AI-Driven Automation and Computer Vision tracked as distinct R&D investment categories. CAGRs were derived from installed base replacement cycles and greenfield automation penetration rates in brownfield warehouses. Forecast inputs incorporated EMA temperature-compliance mandates for pharmaceutical distribution and EU Cohesion Fund infrastructure investments in Polish logistics real estate.
Inputs from KBA and ANSM enforcement timelines were available through the study window; gaps in EU AI Act conformity assessment precedents introduce uncertainty bands around liability cost projections for fully autonomous systems. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Mobile Robot Charging Station Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Healthcare Mobile Robots Market