
 Asia-Pacific Logistics Robotics Market | 2026-2036
Asia-Pacific Logistics Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Logistics Robotics Market Insights
Japan's METI carbon-neutrality roadmap for industrial sectors is consolidating procurement criteria around energy-efficient automation. KUKA AG leverages its Chinese manufacturing base to anchor regional supply of heavy-payload robotic arms for automotive logistics. Geek+ specializes in vision-guided mobile robots for e-commerce sortation, competing directly with Daifuku Co., Ltd., which dominates airport baggage and parcel hub installations across East Asia.
Asia-Pacific logistics robotics encompasses autonomous mobile platforms, articulated manipulators, and aerial delivery systems engineered for payload capacities from kilograms to multiple tons, operating via lidar, camera arrays, and sensor fusion for navigation in dynamic warehouse environments. Automated Guided Vehicles and Sorting Robots occupy the largest installed base, reflecting mature demand from retail distribution centers, while Delivery Drones represent the fastest-expanding category as regulatory frameworks in Australia, Japan, and Singapore gradually open beyond-visual-line-of-sight corridors. AI-Driven Automation and SLAM technology concentrate margin pools, since software-defined routing and real-time mapping command premium pricing over hardware-only deployments.
China's SAMR enforces GB standards for industrial robot safety and electromagnetic compatibility, while Japan's METI coordinates JIS certification for collaborative robot deployments; Australia's TGA and WorkSafe jurisdictions add layers for drone operations in populated areas, collectively shaping product design requirements and market access timelines. India's PLI scheme for advanced manufacturing is drawing component suppliers to Gujarat and Tamil Nadu, altering regional cost structures. Stakeholders must monitor divergence between China's GB standards and Japan's JIS frameworks, as misalignment threatens interoperability across multinational warehouse networks.
Market Dynamics
China's dual carbon goals from MEE are forcing warehouse operators across the Yangtze River Delta to electrify their automation fleets, compressing diesel-powered equipment replacement cycles and reshaping procurement criteria for mobile robotics platforms.
Growth Catalysts
- E-commerce fulfillment expansion:Mega-facilities near Shanghai, Shenzhen, and Hangzhou are deploying autonomous mobile robots to manage parcel volume surges. Sortation throughput requirements now exceed manual labor capacity.
- Japan's METI carbon-neutrality roadmap:Industrial sector procurement criteria now prioritize energy-efficient automation systems. This regulatory pressure accelerates replacement of legacy material handling equipment.
- SLAM technology maturation:Real-time mapping and navigation software enables deployment in dynamic warehouse environments without fixed infrastructure. This reduces installation timelines and facility modification costs.
Market Restraints
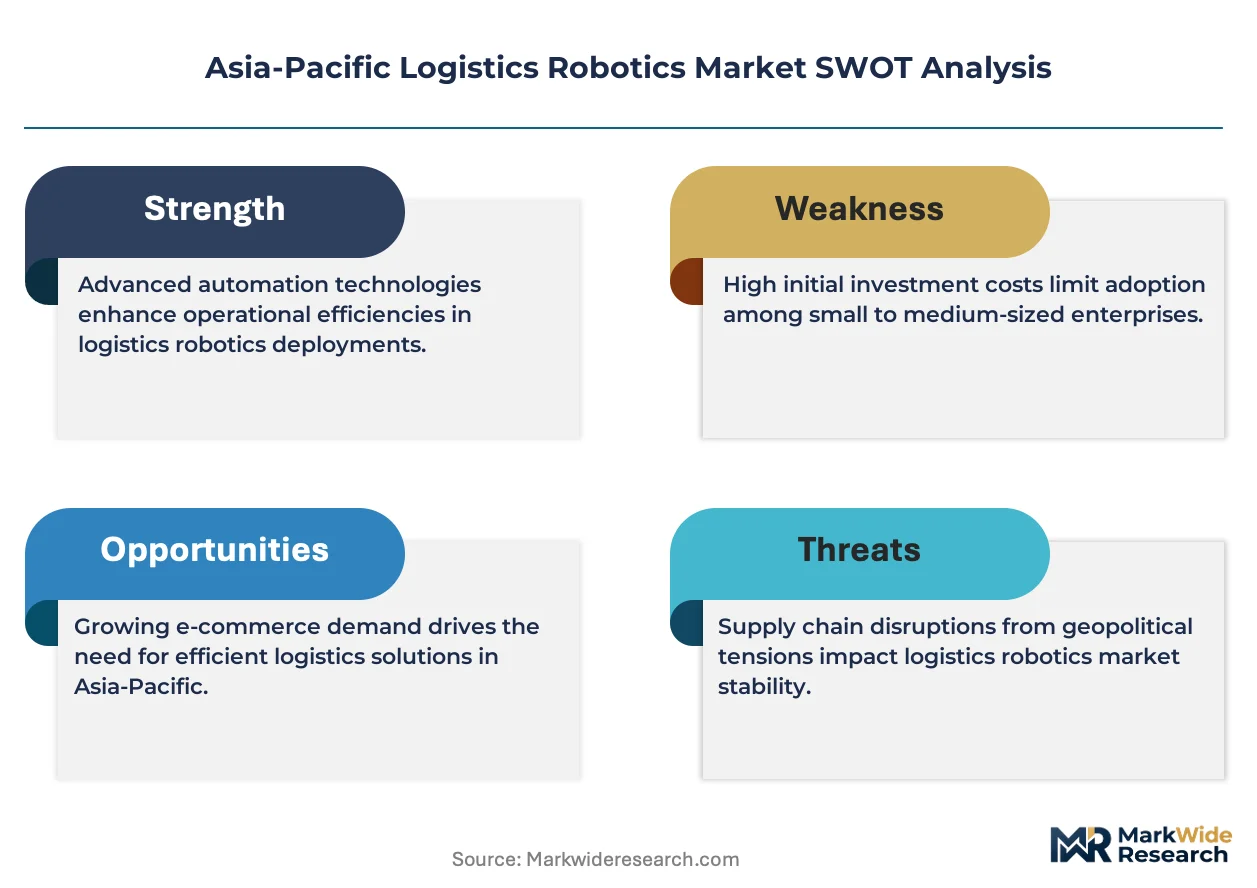
- Heavy-payload actuator supply concentration:Precision servo motor production clusters in specific Chinese manufacturing zones. Geographic concentration creates vulnerability to regional logistics disruptions.
- GB-JIS standard divergence:China's SAMR safety standards and Japan's METI certification frameworks lack mutual recognition. Multinational warehouse networks face duplicate compliance costs.
- Lithium battery input volatility:Electrified autonomous systems depend on battery cell supply subject to raw material price swings. Energy density requirements limit substitute chemistry options.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Component suppliers are relocating to Gujarat and Tamil Nadu. This alters regional cost structures and creates captive supply opportunities for system integrators.
- Beyond-visual-line-of-sight drone corridors:Australia's TGA and Japan's aviation regulators are opening airspace frameworks. Delivery drones represent underpenetrated application space with regulatory tailwinds.
- Vision-guided manipulation convergence:Integration of depth cameras with collaborative arms enables piece-picking in unstructured environments. E-commerce returns processing is the immediate application target.
Industry Challenges
- Sensor fusion engineering talent scarcity:Lidar-camera integration and real-time path optimization require specialized robotics software expertise. Universities in the region produce insufficient graduates with these compound skills.
- Legacy WMS integration complexity:Existing warehouse management systems use proprietary data protocols. Retrofitting APIs for robot fleet management extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Logistics Robotics Market |
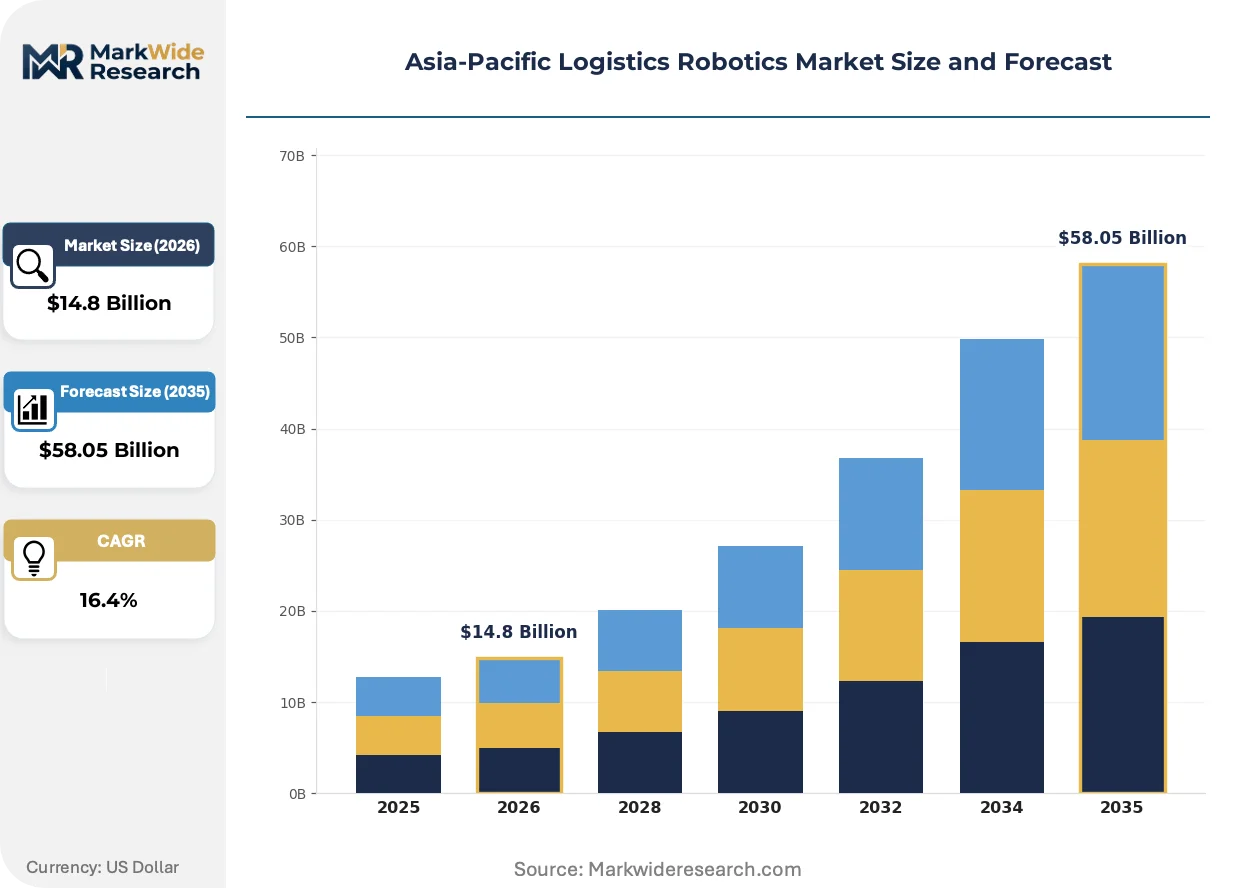
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $58.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Sorting Robots, Robotic Arms, Delivery Drones Technology: Vision-Based Navigation, SLAM, RFID, AI-Driven Automation Application: Warehouse Automation, Last-Mile Delivery, Inventory Management, Order Fulfillment End User: E-Commerce, Retail, Manufacturing, Food & Beverage |
| Companies Covered | KUKA AG, Honeywell International Inc, Fanuc Corporation, Daifuku Co., Ltd., Geek+, Yaskawa Electric Corporation, ABB Limited, Swisslog Holding AG, Kawasaki Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Logistics Robotics Market Trends and Innovations
Software-defined routing is displacing fixed-path automation across Asia-Pacific distribution networks. Real-time fleet optimization now commands premium pricing over hardware-only deployments.
Sensor fusion architectures combining lidar, camera arrays, and inertial measurement units are automating navigation in previously unstructured warehouse zones. Third-party logistics providers in China's Yangtze River Delta are deploying these systems at scale for dynamic slotting operations. The technology is automating labor previously reserved for human judgment in congested aisle environments.
Japan's METI is coordinating JIS certification requirements for collaborative robot deployments in shared human-machine workspaces. This framework mandates force-limiting controls and emergency stop protocols. Automotive logistics facilities in Toyota City and surrounding industrial corridors are the primary compliance testing grounds.
Buyer procurement patterns are compressing from capital purchase toward robotics-as-a-service models. E-commerce operators in Singapore and Australia now prefer per-pick pricing over equipment ownership. This shift transfers fleet utilization risk to vendors and accelerates vendor consolidation among balance-sheet-capable suppliers.
Asia-Pacific Logistics Robotics Market Segmentation
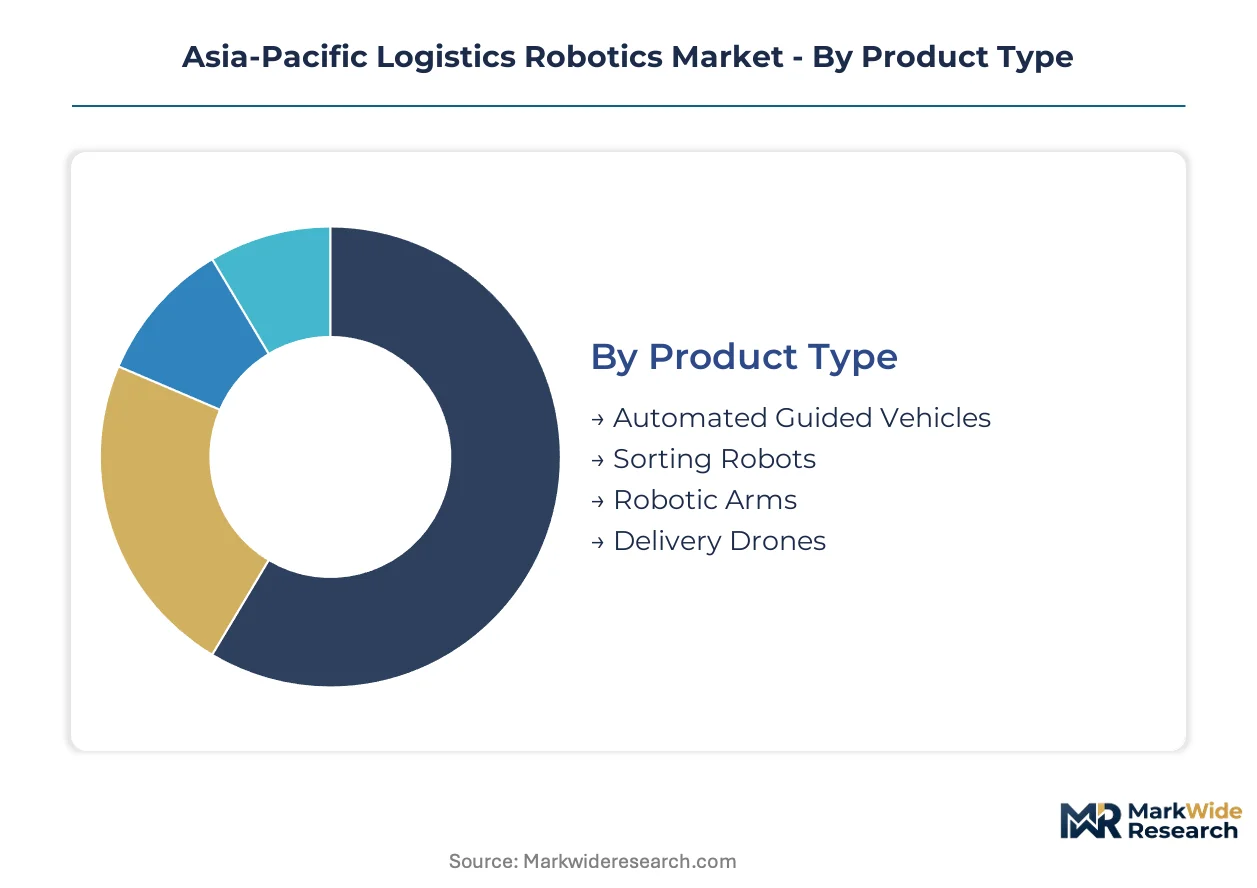
Equipment replacement cycles across Asia-Pacific logistics networks are accelerating as electrification mandates and e-commerce throughput demands converge. Procurement committees now evaluate segments through dual lenses of carbon compliance and parcel volume elasticity.
Product Type:
Upgrade trajectories favor platforms that eliminate fixed infrastructure while accommodating payload scaling from kilograms to multiple tons.
- Automated Guided Vehicles:Electrified autonomous platforms navigate warehouse floors via magnetic tape, lidar, or vision fusion. Demand clusters in Yangtze River Delta mega-facilities where Shanghai-based operators replace diesel forklifts under MEE dual carbon enforcement.
- Sorting Robots:Vision-guided articulated systems handle parcel singulation and destination routing at throughput rates exceeding manual capacity. Shenzhen and Hangzhou e-commerce hubs deploy these for seasonal volume surges that strain permanent workforce availability.
- Robotic Arms:Heavy-payload manipulators perform palletizing and depalletizing operations in automotive logistics corridors.
- Delivery Drones:Aerial systems for beyond-visual-line-of-sight parcel transport are gaining regulatory traction in Australia and Japan.
Volume placements concentrate in Automated Guided Vehicles; the faster expansion belongs to Delivery Drones.
Technology:
Margin capture increasingly depends on software layers that reduce facility modification costs and accelerate deployment timelines.
- AI-Driven Automation:Machine learning models optimize fleet routing, predict maintenance intervals, and enable dynamic task allocation across heterogeneous robot populations. Australia's TGA-registered drone operators and Japan's METI-certified collaborative deployments both require algorithmic transparency documentation.
- SLAM:Simultaneous Localization and Mapping enables navigation without pre-installed beacons or floor markings. Real-time environmental mapping commands premium pricing over hardware-only deployments in third-party logistics facilities throughout China's Yangtze River Delta.
- Vision-Based Navigation:Depth camera arrays and neural network processing guide mobile platforms through unstructured aisle environments.
- RFID:Radio-frequency identification supports inventory tracking and robot-to-goods verification workflows.
Commercial traction clusters around AI-Driven Automation; SLAM is climbing the fastest as retrofit-friendly deployment economics improve.
Application:
Customer willingness-to-pay varies sharply by labor substitution economics and facility downtime tolerance.
- Warehouse Automation:Comprehensive systems integrating mobile robots, sortation equipment, and warehouse management software orchestration. India's Gujarat and Tamil Nadu manufacturing zones are emerging as testbeds for PLI scheme-supported automation retrofits.
- Order Fulfillment:Piece-picking and packing operations in e-commerce distribution centers. Singapore and Australian operators increasingly prefer robotics-as-a-service pricing models that transfer utilization risk to vendors.
- Last-Mile Delivery:Drone and autonomous ground vehicle deployment for final customer handoff.
- Inventory Management:Cycle counting and stock location verification via autonomous mobile platforms.
Deployment scale favors Warehouse Automation; Order Fulfillment is gaining share fastest as per-pick commercial models reduce capital barriers.
End User:
Procurement sophistication and contract structuring sophistication diverge substantially across buyer categories.
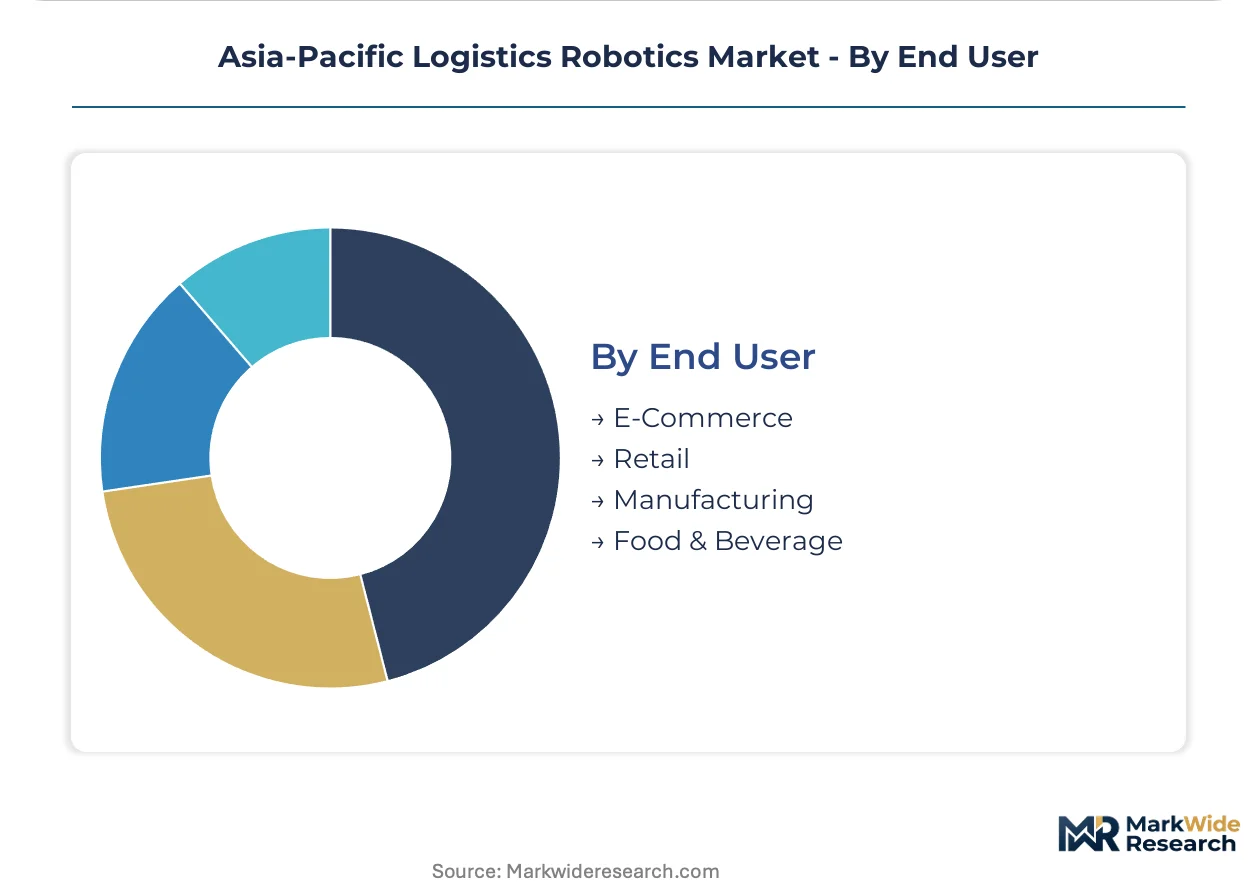
- E-Commerce:Volume-sensitive operators with extreme seasonality and returns processing complexity. Alibaba-affiliated and JD.com logistics networks in China drive specifications for vision-guided manipulation in unstructured environments.
- Retail:Omnichannel distribution requirements combining store replenishment and direct-to-consumer fulfillment. Japanese METI energy-efficiency procurement criteria reshape automation fleet specifications for retail distribution centers.
- Manufacturing:Automotive and electronics production logistics with heavy-payload and precision handling requirements.
- Food & Beverage:Cold-chain compliant automation with hygiene certification and temperature-controlled operation specifications.
Contract value concentrates in E-Commerce; Food & Beverage shows steepest expansion trajectory as cold-chain robotics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of logistics robotics hardware while Japan and Australia concentrate demand for high-specification automation systems. South Korea and India are emerging as dual markets for both component sourcing and system deployment.
China
E-commerce fulfillment centers in Shanghai, Shenzhen, and Hangzhou drive mobile robot procurement at volumes unmatched elsewhere. MEE dual carbon enforcement compels warehouse operators to electrify automation fleets and retire diesel-powered material handling equipment. The Yangtze River Delta mega-facility cluster anchors regional production capacity for articulated manipulators and autonomous guided platforms.
Japan
Automotive logistics corridors in Toyota City and surrounding industrial zones demand heavy-payload precision handling systems. METI coordinates JIS certification requirements for collaborative robot deployments in shared human-machine workspaces. Kansai and Chubu manufacturing belts serve as primary testing grounds for force-limiting controls and emergency stop protocols.
India
PLI scheme incentives for advanced manufacturing draw component suppliers to Gujarat and Tamil Nadu, altering regional cost structures for servo motor and sensor production. BIS safety standards for industrial automation are converging with international frameworks to accelerate import substitution. Mumbai-Pune and Chennai-Bengaluru industrial corridors host pilot deployments for warehouse automation retrofits.
Australia
TGA and WorkSafe jurisdictions are opening beyond-visual-line-of-sight corridors for delivery drone operations in populated areas. Mining logistics automation in Western Australia demands heavy-payload autonomous haulage adapted for warehouse environments. Sydney and Melbourne distribution centers are early adopters of robotics-as-a-service pricing models that transfer fleet utilization risk to vendors.
South Korea
Seoul Capital Area electronics logistics networks require high-throughput sortation systems for semiconductor and display component handling. MFDS pharmaceutical logistics regulations are extending to warehouse automation hygiene standards for medical device distribution. Busan-Ulsan port automation projects are generating demand for container-handling robotic systems with vision-guided precision.
Asia-Pacific Logistics Robotics Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive automation divisions. European and Japanese heavy-machinery groups anchor the premium tier through established automotive sector relationships. Chinese pure-play mobile robot specialists are compressing margins in mid-market e-commerce applications. Consolidation pressure is intensifying as balance-sheet-capable vendors acquire software-defined routing capabilities and regional system integrators.
Among Asia-Pacific headquartered specialists, Daifuku Co., Ltd. exemplifies the airport baggage and parcel hub installation archetype, while Geek+ occupies the vision-guided mobile robot position for e-commerce sortation. KUKA AG represents the European industrial conglomerate model leveraging Chinese manufacturing bases for regional heavy-payload supply.
| Leading Market Players |
|---|
| KUKA AG |
| Honeywell International Inc |
| Fanuc Corporation |
| Daifuku Co., Ltd. |
| Geek+ |
| Yaskawa Electric Corporation |
| ABB Limited |
| Swisslog Holding AG |
| Kawasaki Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot prices in Chinese commodity markets cascade through battery pack costs into three distinct pricing tiers for electrified autonomous mobile robots. Warehouse operators in the Yangtze River Delta face compressed procurement cycles as MEE dual carbon enforcement accelerates diesel-to-electric fleet conversions, amplifying buyer sensitivity to energy storage input volatility.
Pricing Analysis
Per-pick robotics-as-a-service contracts now anchor value-based pricing in Singapore and Australian distribution centers, transferring utilization risk from e-commerce operators to vendors. Price differentiation rests on SLAM navigation maturity and JIS certification tier for collaborative deployments in Japan's automotive logistics corridors. Cost compression in mid-market AGV segments intensifies as Geek+ and domestic Chinese suppliers compete on hardware margins. E-commerce fulfillment operators exhibit highest price sensitivity due to seasonal volume volatility, while pharmaceutical logistics under MFDS jurisdiction in South Korea accept premium tiers for hygiene-validated automation.
Supply Chain Analysis
Workforce availability constraints in China's Guangdong and Jiangsu provinces are pushing precision servo motor production toward India's Gujarat and Tamil Nadu zones under PLI scheme incentives. The supply chain draws from lithium cell manufacturing in China, South Korea, and Japan, with magnetic encoder and depth camera components concentrated in Taiwanese and South Korean electronics corridors. Single-source vulnerability persists in heavy-payload harmonic drive gear production. Distribution runs through system integrators with captive service networks in Shanghai, Tokyo, and Sydney metro areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where METI JIS certification and SAMR GB standard divergence erect regulatory moats favoring balance-sheet-capable incumbents with dedicated compliance engineering teams.
For Market Incumbents: Extend software-defined routing capabilities through acquisition of SLAM-specialist firms to defend against margin erosion from hardware-commoditizing Chinese pure-plays. Deepen backward integration into lithium battery pack assembly in Yangtze River Delta manufacturing zones to secure supply continuity against raw material volatility. Prioritize dual-certification engineering investment spanning JIS and GB frameworks to capture multinational warehouse network contracts. For New Entrants and Emerging Players: Vision-guided piece-picking for e-commerce returns processing offers the most penetrable white-space target, as unstructured environment manipulation remains undersupplied relative to mobile platform saturation. Australia's beyond-visual-line-of-sight drone corridors present regulatory-favorable geography with limited incumbent presence. A software-first go-to-market emphasizing rapid WMS API integration addresses legacy system retrofit friction that extends deployment timelines for established vendors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap system integrators with established METI certification relationships in Japan's Chubu manufacturing belt. Long-term viability across the analysis window hinges on software-margin capture rather than hardware shipment volume. Watch for convergence signals between China's SAMR and Japan's METI on collaborative robot safety protocols as inflection indicator for cross-border M&A rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| SLAM Technology Acquisition | Software-defined routing commands premium pricing over fixed-path automation in Yangtze River Delta facilities. |
| Dual-Certification Engineering Investment | JIS-GB alignment reduces duplicate compliance costs for multinational warehouse network deployments. |
| Battery Pack Assembly Integration | Captive lithium cell sourcing insulates against commodity price swings in electrified fleet conversions. |
| Robotics-as-a-Service Platform Launch | Per-pick pricing transfers utilization risk to vendors and accelerates consolidation among balance-sheet-capable suppliers. |
| Beyond-Visual-Line-of-Sight Regulatory Engagement | TGA and Japanese aviation framework openings create first-mover positioning in Australian last-mile drone corridors. |
Research Methodology
Independent corroboration across warehouse operator procurement directors, robotics system integrators, and SAMR certification engineers underwrites the qualitative findings in this study. Primary interviews with e-commerce fulfillment executives, automotive logistics managers in Toyota City corridors, and PLI scheme administrators in Gujarat supplemented secondary validation through customs trade data, METI technology roadmaps, and SAMR GB standard filings. Bottom-up installed base estimates triangulate against top-down e-commerce parcel volume projections.
Rate-of-change decomposition separates hardware shipment growth from software and services margin expansion across the projection horizon. Segmentation dimensions modeled include product type, navigation technology tier, application workflow, and end-user procurement sophistication. CAGRs derive from logistic curve adoption modeling calibrated to electrification mandate enforcement timelines and e-commerce fulfillment center build-out schedules in Shanghai, Shenzhen, and Hangzhou clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption scenarios or accelerated GB-JIS standard harmonization. Material deviation in MEE dual carbon enforcement intensity or TGA drone corridor authorization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market