
 Global Delivery Robots Market | 2026-2036
Global Delivery Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Delivery Robots Market Analysis
The EU Green Deal's emissions-reduction mandates for urban freight is decoupling last-mile logistics from diesel van dependency across European capitals. Nuro, Inc. anchors its position through purpose-built electric vehicle platforms designed for neighborhood-speed operation. Starship Technologies dominates university and corporate campus deployments with a controlled-environment strategy that limits regulatory friction. JD.com, Inc. leverages its parent ecosystem to sustain high-utilization robot fleets integrated with existing warehouse infrastructure.
Delivery robots are autonomous or semi-autonomous mobile systems equipped with lidar, cameras, and ultrasonic sensors, typically operating at speeds below 25 km/h to transport goods without human drivers. Ground robots currently occupy the largest deployment base due to lower energy requirements and simpler airspace compliance compared to aerial alternatives. Food delivery applications are attracting the fastest fleet expansion as restaurants seek labor-cost containment during peak hours. SLAM technology leads the navigation stack for indoor and constrained outdoor environments, while computer vision is displacing simpler sensor fusion in complex pedestrian zones.
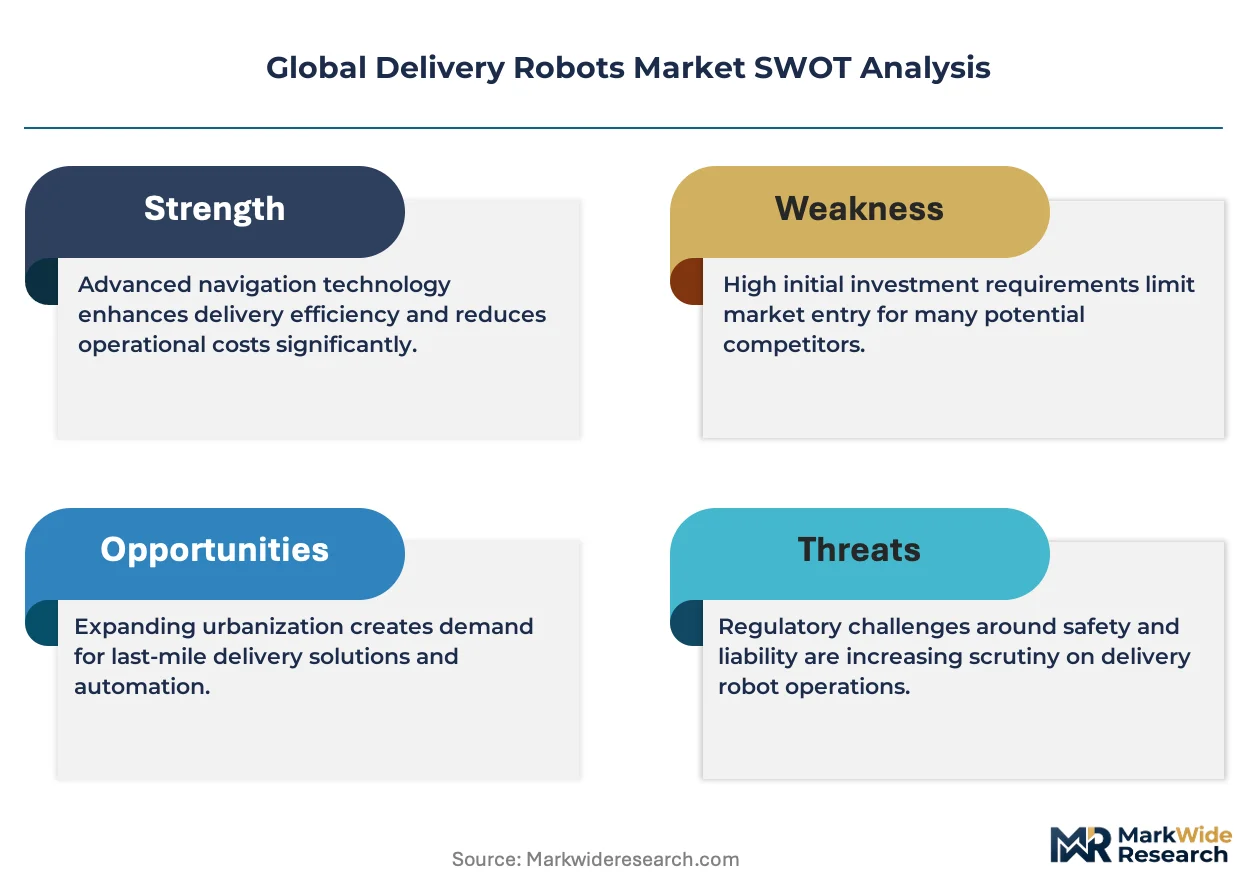
The FAA in the United States restricts aerial drone operations beyond visual line of sight without specific waivers, constraining aerial delivery scaling. China's MIIT and SAMR jointly govern robot road-testing permissions, creating a permitting bottleneck that favors established technology conglomerates. Japan's METI has issued safety guidelines for sidewalk robots that shape product design for any vendor targeting Tokyo or Osaka. Stakeholders must monitor how municipal liability frameworks evolve before committing capital to multi-city fleet rollouts.
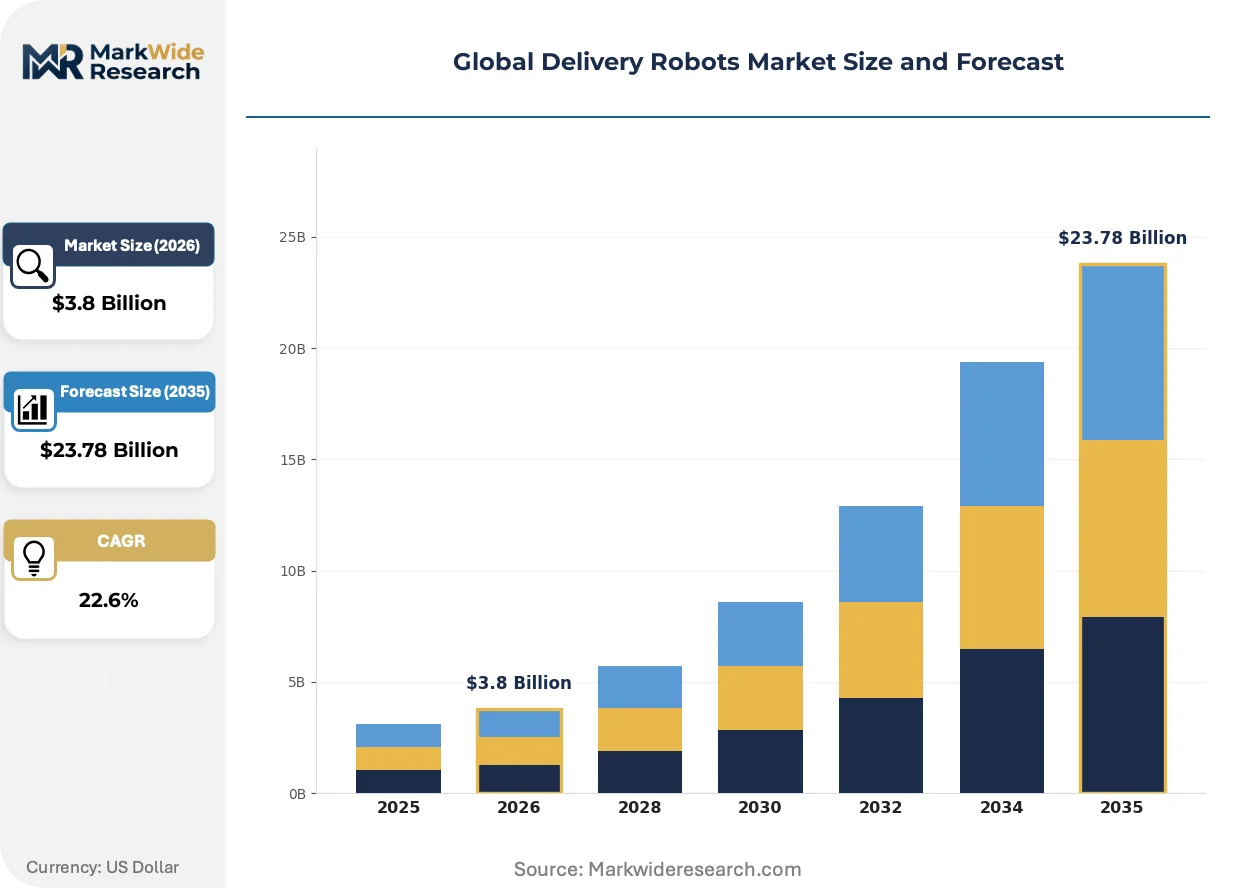
Market Dynamics
Autonomous navigation stack maturation is compressing time-to-certification timelines while municipal liability fragmentation forces deployers to maintain jurisdiction-specific legal reserves. The EU AI Act's risk-classification framework for autonomous systems is accelerating certification investments among European deployers.
Growth Catalysts
- Urban Emissions Mandates:The EU Green Deal's emissions-reduction mandates for urban freight is decoupling last-mile logistics from diesel van dependency across European capitals. Municipal procurement offices now specify zero-emission delivery in RFPs.
- SLAM Technology Maturation:Simultaneous Localization and Mapping technology leads the navigation stack for indoor and constrained outdoor environments, reducing sensor suite costs by consolidating lidar and camera inputs into unified perception layers.
- China's Permitting Velocity:China's MIIT and SAMR jointly govern robot road-testing permissions, creating streamlined corridors in Shenzhen, Beijing, and Shanghai that sustain high-utilization fleet economics.
Market Restraints
- FAA Airspace Friction:The FAA in the United States restricts aerial drone operations beyond visual line of sight without specific waivers, constraining aerial delivery scaling and forcing capital toward ground-based alternatives.
- Lithium-Ion Supply Concentration:Battery cell supply concentrates among East Asian producers, exposing fleet operators to input cost volatility and currency-hedging complexity in procurement contracts.
- Pedestrian Right-of-Way Conflicts:Sidewalk robot operations face technical limitations in dense pedestrian zones where unstructured human movement exceeds current predictive model accuracy.
Strategic Opportunities
- Japanese Safety Guidelines:Japan's METI has issued safety guidelines for sidewalk robots that shape product design for any vendor targeting Tokyo or Osaka, creating first-mover certification advantages for compliant hardware.
- Campus-to-Urban Expansion:Controlled-environment deployments at universities and corporate parks offer replicable operational templates for denser urban rollouts with pre-mapped terrain and predictable demand patterns.
- Computer Vision Convergence:Computer vision is displacing simpler sensor fusion in complex pedestrian zones, enabling lighter hardware configurations that reduce per-unit manufacturing cost.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Stakeholders must monitor how municipal liability frameworks evolve before committing capital to multi-city fleet rollouts, requiring dedicated regulatory affairs staffing in each operating geography.
- Legacy Warehouse Integration:Fleet integration with existing warehouse management systems demands custom API development and real-time inventory synchronization that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Delivery Robots Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.78 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Ground Robots, Aerial Drones, Hybrid Robots, Autonomous Vehicles Application: Last-Mile Delivery, Food Delivery, Parcel Delivery, Logistics Support End User: Retailers, E-Commerce, Restaurants, Logistics Providers Technology: SLAM, GPS Navigation, Computer Vision, IoT Integration |
| Companies Covered | Nuro, Inc., Relay Robotics, Inc., Starship Technologies, Kiwibot, Alibaba Group Holding Limited, JD.com, Inc., Boston Dynamics, Serve Robotics, Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Delivery Robots Market Emerging Trajectories
Hardware-software co-design is compressing development cycles while regulatory sandbox programs accelerate real-world validation. Three forces are actively reshaping competitive positioning in autonomous last-mile systems.
Computer vision-based navigation is electrifying the shift from multi-sensor fusion stacks to camera-primary perception architectures. Food delivery chains are adopting these lighter configurations fastest, prioritizing unit economics over maximum environmental robustness. This transition is electrifying margin expansion for deployers operating in weather-moderated geographies.
The EU AI Act's risk-classification framework for autonomous systems is mandating conformity assessment procedures for high-risk AI applications. European deployers are restructuring engineering teams to embed compliance documentation into development sprints rather than post-hoc certification. Neighborhood-speed ground robots face the most intensive documentation requirements, driving consolidation among vendors with dedicated regulatory capacity.
Restaurant procurement of delivery capacity is fragmenting from exclusive platform contracts toward multi-robot fleet access. Chains now negotiate slot-based utilization agreements across competing robot providers rather than single-source dependencies. This pattern is most visible in Chinese megacities where Meituan and JD.com operate overlapping service territories.
Global Delivery Robots Market Segmentation
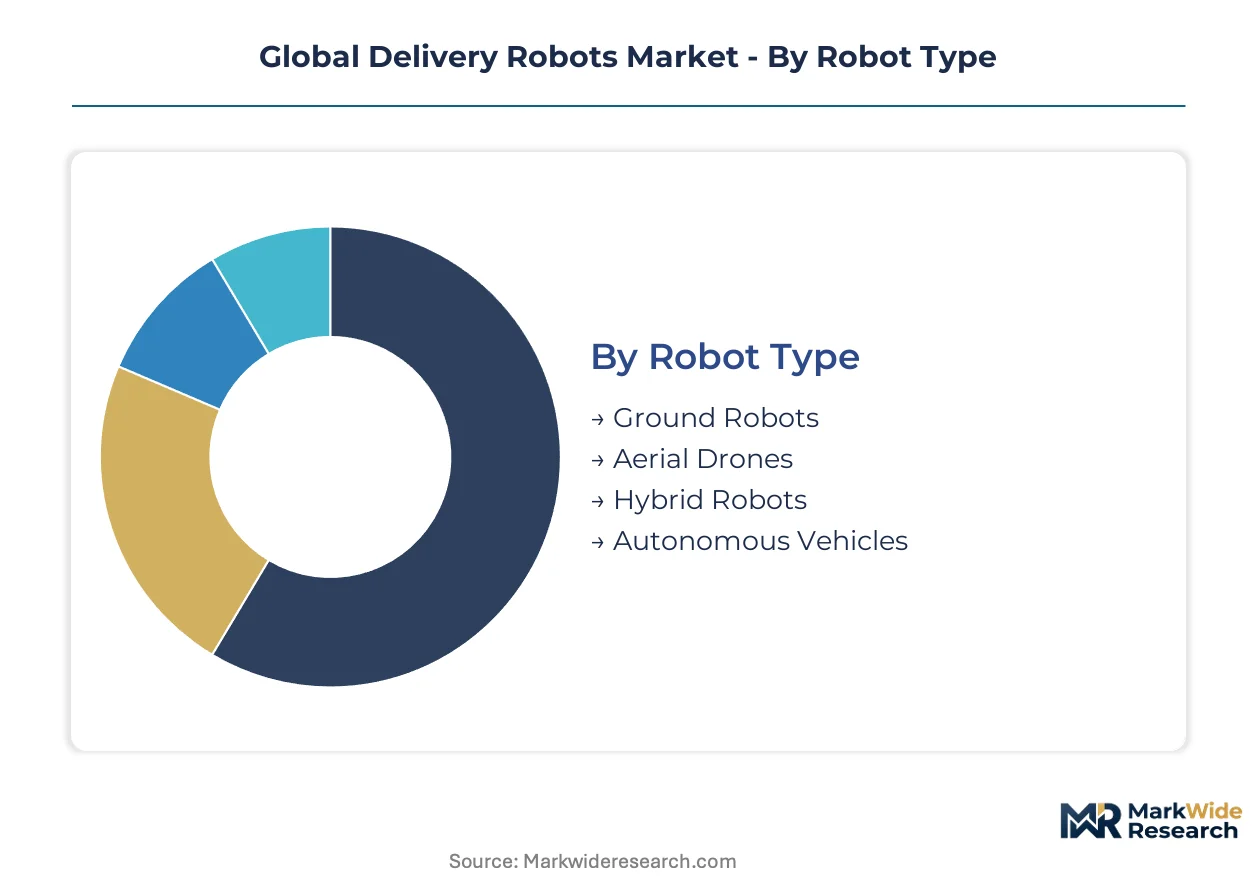
Delivery robot segmentation reveals how hardware configuration, navigation technology, and customer workflow integration determine deployable scale. Each category carries distinct regulatory footprints and capital intensity thresholds that shape vendor specialization strategies.
Robot Type:
Standardization dominates sidewalk-rated ground platforms while aerial systems require extensive customization for payload-range tradeoffs.
- Ground Robots:Electric-powered units with lidar-camera sensor suites operate below 25 km/h on sidewalks and bike lanes. Demand clusters in Chinese megacities where MIIT permits thousands of units in Shenzhen, Beijing, and Shanghai, though pedestrian right-of-way conflicts constrain dense urban throughput.
- Aerial Drones:Multi-rotor and fixed-wing configurations face FAA beyond-visual-line-of-sight restrictions in the United States, forcing capital toward ground alternatives despite faster point-to-point transit potential.
- Hybrid Robots:Dual-mode systems switch between ground transit and limited aerial hop capabilities for obstacle clearance.
- Autonomous Vehicles:Neighborhood-speed electric platforms from Nuro operate on public roads with NHTSA exemptions.
Most installed capacity flows through Ground Robots. Expansion is steepest in Aerial Drones where regulatory sandboxes in select jurisdictions enable pilot scaling.
Application:
Volume tiers separate predictable campus environments from complex municipal street networks with variable traffic patterns.
- Last-Mile Delivery:Final-segment logistics from micro-fulfillment centers to residential addresses. The EU Green Deal's urban freight emissions mandates accelerate zero-emission procurement specifications across Paris, Berlin, and Amsterdam municipal RFPs.
- Food Delivery:Temperature-controlled compartments transport prepared meals within 30-minute windows. Domino's and Pizza Hut robot trials concentrate on college campuses where demand patterns repeat predictably.
- Parcel Delivery:E-commerce fulfillment for small-package distribution.
- Logistics Support:Intra-facility material movement and warehouse-to-warehouse shuttles.
Food Delivery captures the steepest fleet expansion trajectory. Parcel Delivery holds the largest addressable volume base pending sidewalk liability clarity.
End User:
Procurement sophistication varies from standardized fleet leases to custom warehouse integration projects.
- Retailers:Grocery and convenience chains deploy for click-and-collect fulfillment.
- E-Commerce:JD.com leverages parent ecosystem integration to sustain high-utilization robot fleets synchronized with existing warehouse infrastructure.
- Restaurants:Chains negotiate slot-based utilization agreements across competing robot providers rather than single-source dependencies, fragmenting procurement from exclusive platform contracts.
- Logistics Providers:Third-party carriers seek modular fleet access without capital ownership.
E-Commerce channels the most units currently deployed. Restaurants are gaining share fastest as labor-cost containment during peak hours drives adoption.
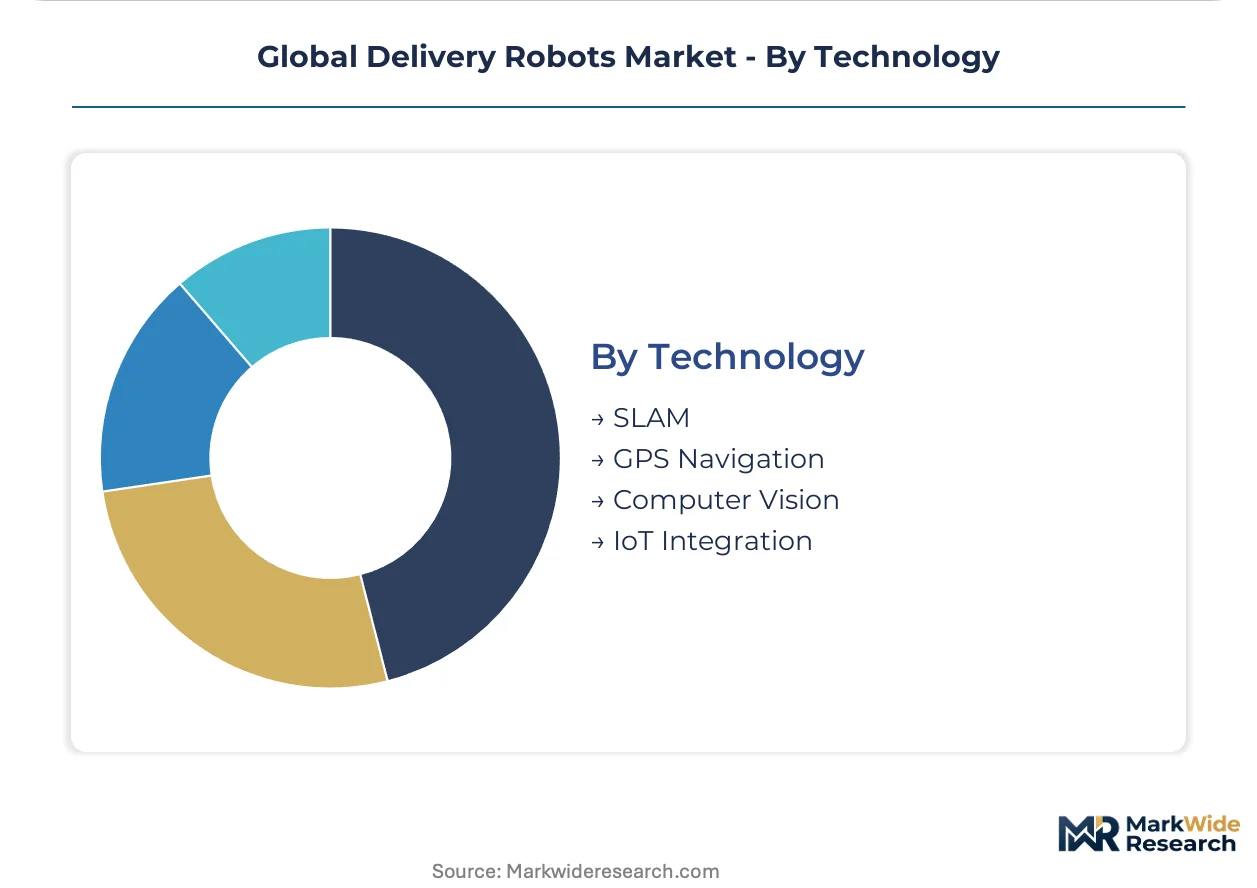
Technology:
Navigation stack costs stratify from camera-primary architectures to multi-sensor fusion systems with redundant perception layers.
- SLAM:Simultaneous Localization and Mapping consolidates lidar and camera inputs into unified perception layers, reducing sensor suite costs for indoor and constrained outdoor environments.
- GPS Navigation:Satellite-dependent positioning supplements dead-reckoning in open outdoor corridors.
- Computer Vision:Camera-primary perception displaces simpler sensor fusion in complex pedestrian zones, enabling lighter hardware configurations that reduce per-unit manufacturing cost for food delivery chains in weather-moderated geographies.
- IoT Integration:Real-time connectivity with warehouse management systems and customer notification platforms.
SLAM anchors the largest installed navigation base. Computer Vision is climbing the fastest as hardware-software co-design compresses development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delivery robotics originated in controlled campus environments across the United States before scaling into Chinese megacities where permissive testing corridors enabled rapid fleet deployment. The technology has since diffused through European capitals under emissions-mandate procurement and into Japanese urban centers with strict sidewalk safety protocols.
United States
FAA beyond-visual-line-of-sight restrictions constrain aerial scaling while NHTSA exemptions enable neighborhood-speed ground platforms. The FAA's Part 107 waiver process creates regulatory friction that favors capital-rich deployers capable of sustained compliance investment. Pittsburgh and San Francisco host dense testing clusters where university-corporate partnerships validate navigation stacks before municipal expansion.
China
MIIT and SAMR joint permitting sustains high-utilization economics across Shenzhen, Beijing, and Shanghai corridors. The MIIT's streamlined road-testing permissions favor established technology conglomerates with existing regulatory relationships. JD.com and Meituan operate overlapping service territories in Shenzhen where thousands of units execute last-mile fulfillment synchronized with warehouse infrastructure.
Germany
EU Green Deal urban freight mandates accelerate zero-emission procurement specifications across Berlin and Amsterdam municipal RFPs. The EU AI Act's risk-classification framework forces conformity assessment restructuring into development sprints. Berlin anchors European certification investment as deployers embed compliance documentation ahead of neighborhood-speed deployment.
Japan
METI sidewalk safety guidelines shape product design requirements for Tokyo and Osaka targeting. METI's technical specifications for pedestrian interaction protocols create first-mover certification advantages for compliant hardware vendors. Tokyo's Shibuya and Shinjuku districts concentrate pilot deployments where unstructured pedestrian movement tests predictive model accuracy.
United Kingdom
Department for Transport pilot programs enable supervised autonomous trials in Cambridge and Milton Keynes. The UK's Code of Practice for automated vehicle trialling mandates insurance coverage thresholds that filter smaller operators. Milton Keynes operates Europe's largest suburban robot deployment where pre-mapped residential grids support predictable demand patterns.
Global Delivery Robots Market Vendor Landscape
Capital-heavy hardware producers compete with asset-light navigation stack designers for procurement contracts across restaurant and logistics verticals. The vendor base stratifies between integrated platform operators and component specialists licensing perception software. Three archetypes dominate: ecosystem-integrated technology conglomerates, pure-play robot-as-a-service providers, and automotive-tier suppliers repurposing autonomous vehicle stacks. Consolidation pressure intensifies through strategic partnerships bridging hardware manufacturing with last-mile platform access, while geographic expansion demands jurisdiction-specific regulatory capacity.
Within the ecosystem-integrated tier, JD.com, Inc. and Alibaba Group Holding Limited represent Asian technology conglomerates leveraging parent infrastructure for fleet synchronization. Nuro, Inc. anchors the purpose-built vehicle segment with neighborhood-speed platforms designed for public road operation. Starship Technologies exemplifies the controlled-environment specialist archetype dominating university and corporate campus deployments where liability exposure remains bounded.
| Leading Market Players |
|---|
| Nuro, Inc. |
| Relay Robotics, Inc. |
| Starship Technologies |
| Kiwibot |
| Alibaba Group Holding Limited |
| JD.com, Inc. |
| Boston Dynamics |
| Serve Robotics |
| Panasonic Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU AI Act-compliant platforms and baseline sensor-fusion units splits procurement budgets across European deployers and cost-optimized Asian operators, compressing margins for mid-tier vendors caught between premium documentation investments and commodity hardware competition.
Pricing Analysis
Robot-as-a-service subscription tiers with per-delivery fees dominate fleet procurement, separating NHTSA-exempt neighborhood-speed platforms from campus-confined sidewalk units. Price differentiation rests on lidar density and MIIT permitting status, with Chinese conglomerates extracting volume discounts unavailable to Western deployers. Pricing pressure stems from lithium-ion cell volatility, forcing operators toward shorter contract terms. Restaurant chains exhibit highest price sensitivity, while e-commerce platforms prioritize integration reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from JD.com and Meituan, bypassing distributor markups for fleet-scale orders. Component manufacturing concentrates in China, South Korea, and Taiwan for battery cells, camera modules, and lidar sensors. Raw material dependencies span lithium carbonate, rare-earth magnets, and precision-machined aluminum chassis. Single-source vulnerability concentrates in solid-state lidar emitters. Distribution runs through integrated logistics platforms rather than independent dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between China's streamlined MIIT permitting corridors and Europe's EU AI Act compliance costs, rewarding operators who stage certification investments in Shenzhen or Beijing before European market entry.
For Market Incumbents: Hedge against pedestrian-liability fragmentation by maintaining jurisdiction-specific legal reserves in each operating geography. Deepen backward integration into custom lidar-camera fusion stacks to reduce sensor suite costs. Prioritize METI guideline compliance for Tokyo-Osaka corridor access before competitors secure first-mover certification advantages.
For New Entrants and Emerging Players: Enter via controlled-environment deployments at university campuses where Starship Technologies has validated operational templates but not saturated demand. Target Milton Keynes-style suburban grids with pre-mapped residential terrain and predictable delivery windows. Pursue slot-based utilization agreements with restaurant chains seeking multi-robot fleet access rather than exclusive platform dependencies.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory affairs staffing costs exceed $2 million annually per operating geography, favoring acquisition of vendors with embedded compliance documentation. Long-term viability hinges on computer vision navigation maturation displacing multi-sensor fusion. Monitor FAA beyond-visual-line-of-sight waiver velocity as aerial delivery inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Integration | Restructures engineering sprints around conformity assessment documentation for neighborhood-speed deployment. |
| Campus-to-Urban Expansion | Replicates Starship Technologies' controlled-environment templates across denser municipal street networks. |
| Computer Vision Navigation Migration | Displaces lidar-heavy stacks for food delivery chains in weather-moderated geographies. |
| Lithium-Ion Supply Diversification | Reduces exposure to East Asian cell concentration through dual-sourcing contracts with South Korean producers. |
| Multi-Robot Fleet Access Agreements | Fragments restaurant procurement from exclusive platform contracts toward slot-based utilization models. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster combining interviews with fleet operations directors, regulatory affairs leads at autonomous vehicle deployers, municipal procurement officers, and warehouse integration specialists. Secondary validation draws from FAA Part 107 waiver databases, MIIT road-testing permit disclosures, EU AI Act implementation guidance, and NHTSA exemption filings. Bottom-up unit deployment estimates triangulate against top-down market value reconstructions.
Granularity-level modeling segments by robot type, navigation technology stack, application workflow, and end-user procurement sophistication across the projection horizon. CAGRs derive from logistic diffusion curves fitted to observed fleet scaling patterns in Shenzhen, Pittsburgh, and Milton Keynes. Industry-specific inputs include sidewalk robot density limits per municipal jurisdiction and warehouse management system API integration timelines.
Inputs from MIIT permit registries and FAA waiver databases were available through the study window; gaps in real-time fleet utilization metrics from JD.com and Meituan introduce uncertainty bands around Chinese deployment estimates. Forecasts assume continued lithium-ion cost trajectories and stable municipal liability frameworks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Servo Gripper Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
Robot Market