
 Shared Mobility Market | 2026-2036
Shared Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Shared Mobility Market Intelligence
The transition from internal combustion engines to battery-electric powertrains is recalibrating the unit economics and operational models for fleet operators. This shift requires substantial capital investment in charging infrastructure and vehicle procurement. Uber Technologies Inc. leverages its global scale to partner with automakers for EV access, while Didi Chuxing Technology Co. dominates the vast Chinese market with integrated mobility solutions. Grab Holdings Inc. differentiates through its super-app strategy in Southeast Asia.
Shared mobility encompasses services that provide short-term access to transportation modes on an as-needed basis, managed through digital platforms. These systems rely on GPS for vehicle tracking and algorithmic dispatch for efficient fleet utilization. Ride hailing remains the largest service type by revenue, commanding significant market share. Meanwhile, scooter sharing and bike sharing represent the fastest-growing segments, driven by demand for micro-mobility solutions in congested city centers.
Regulatory frameworks create a complex operational environment. The EU's GDPR imposes strict data handling requirements on mobile applications, while various US municipal transport authorities set local licensing and operational rules. In China, the MIIT influences standards for vehicle connectivity and data security. Deciding how to allocate capital between platform technology and compliance with divergent local mandates is a central strategic challenge for operators.
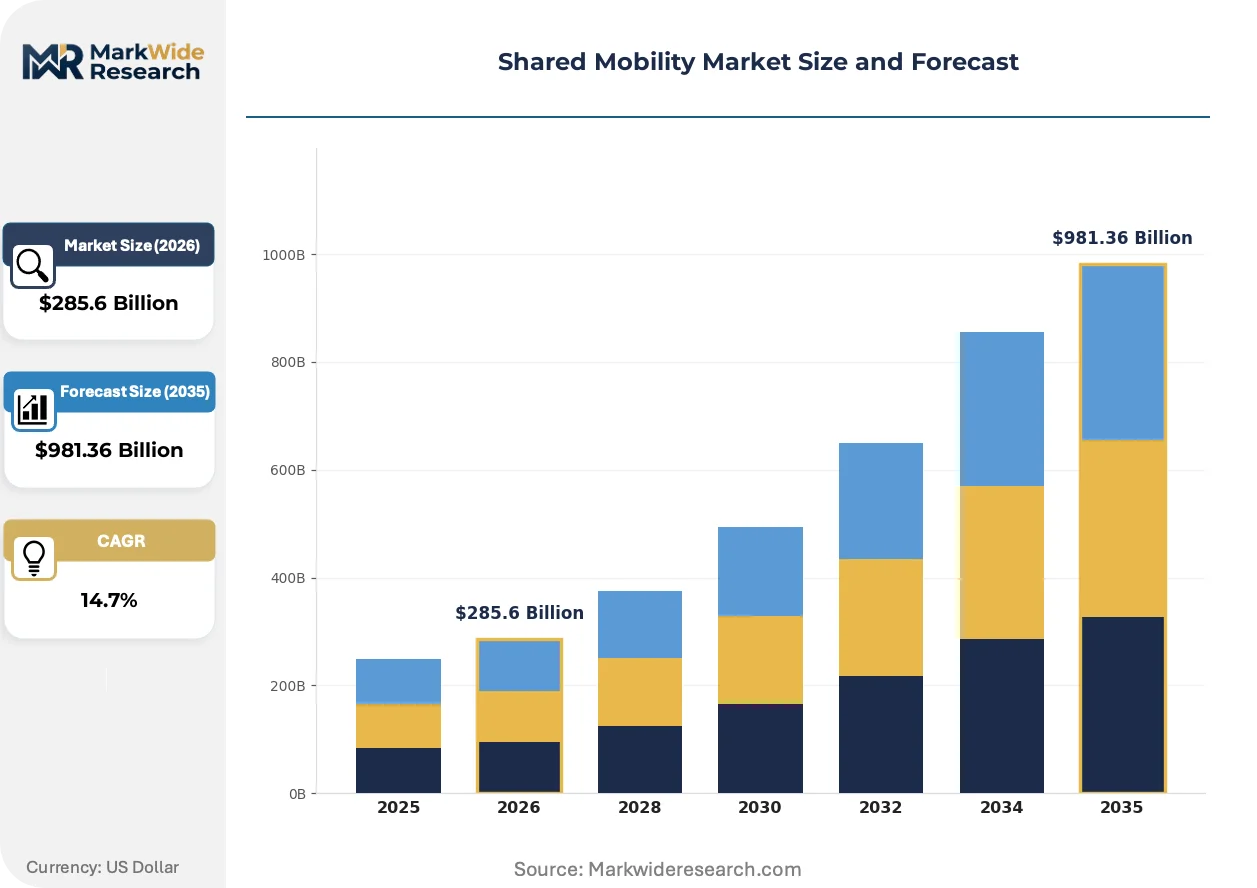
Market Dynamics
The collision of urban density with new regulatory mandates for decarbonization provides the central force driving shared mobility models. This creates a push away from private vehicle ownership in city centers, favoring on-demand, fleet-based transportation solutions.
Growth Catalysts
- Corporate Adoption:Businesses are increasingly integrating shared mobility services into their corporate travel policies as a cost-effective and flexible alternative to car rentals and reimbursements for employee travel.
- Urban Policy Frameworks:The EU Green Deal and similar municipal initiatives incentivize the use of shared services by implementing low-emission zones and congestion pricing, making private car use more expensive and less convenient.
- Emerging Market Demand:In densely populated cities across India and Southeast Asia, app-based shared services fill critical gaps in public transportation infrastructure, providing essential first-and-last-mile connectivity.
Market Restraints
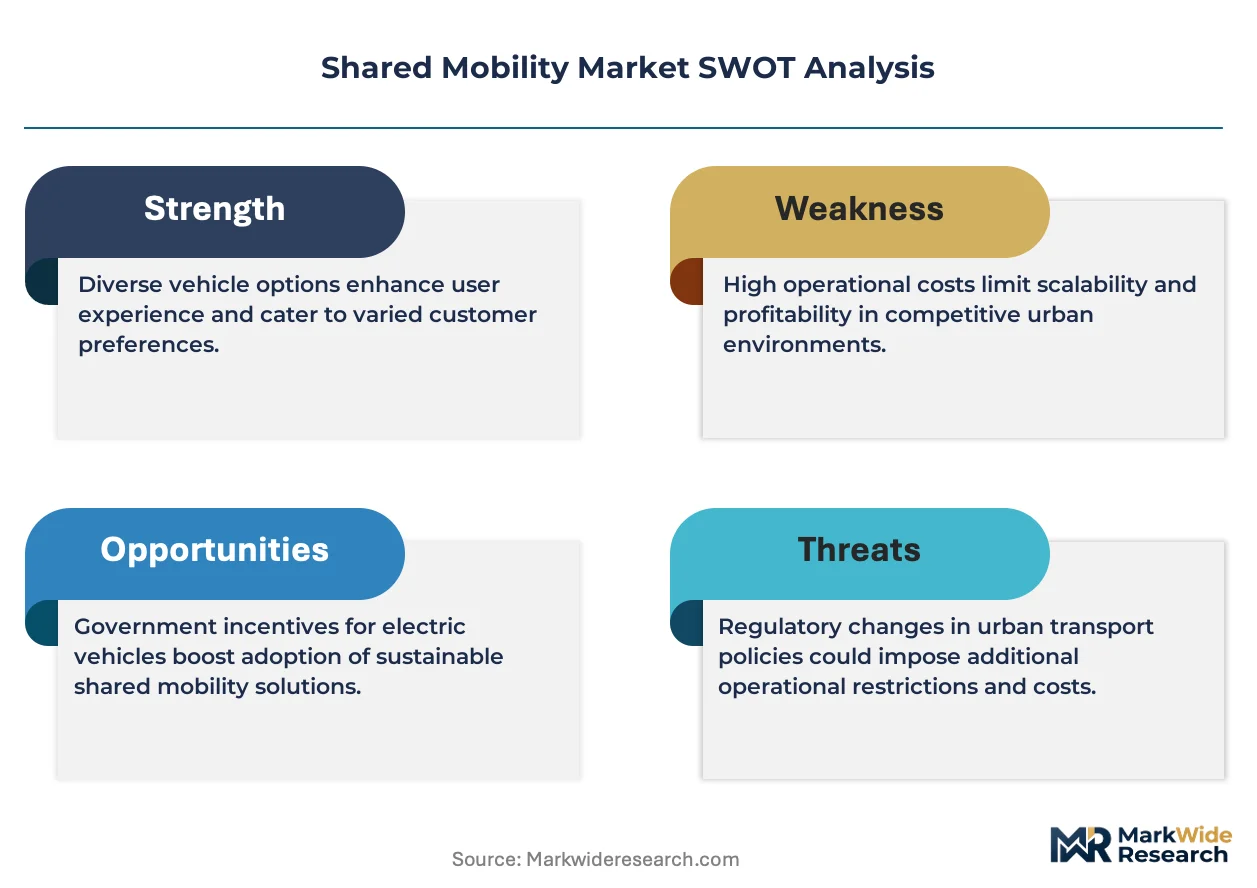
- High Capital Intensity:The transition to electric vehicle fleets requires substantial upfront investment in both vehicle procurement and the development of proprietary or partnered charging infrastructure, straining operator finances.
- Regulatory Fragmentation:A patchwork of local, state, and national regulations, particularly across the United States, creates significant compliance overhead and complicates market entry and expansion strategies for operators.
- Short Vehicle Lifespan:Vehicles used in high-frequency sharing services, especially micromobility assets like scooters and e-bikes, experience accelerated wear and tear, leading to shorter replacement cycles and higher operational costs.
Strategic Opportunities
- Integration with Public Transit:Partnering with municipal transit agencies to offer bundled services provides a new revenue channel and positions shared mobility as an essential component of the public transportation ecosystem.
- Specialized Vehicle Segments:There is an opportunity to develop and deploy services for specific use cases, such as wheelchair-accessible vehicles, cargo e-bikes for logistics, or premium vehicles for corporate clients.
- Insurance and Fintech Products:Developing usage-based insurance products or integrated payment solutions for mobility services offers a path to diversify revenue streams beyond per-trip fees and subscriptions.
Industry Challenges
- Infrastructure Lag:The pace of EV adoption in shared fleets is often faster than the public build-out of charging stations, creating operational bottlenecks and "charging deserts" in certain urban areas.
- Data Security Compliance:Operators must navigate a complex web of data privacy laws, such as GDPR in Europe and specific data localization rules from China's MIIT, increasing technology and legal costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shared Mobility Market |
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $981.36 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Car Sharing, Bike Sharing, Ride Hailing, Scooter Sharing, Shuttle Services Vehicle Type: Sedan, Electric Bike, Electric Scooter, Mini Van, Compact Car End User: Commuters, Tourists, University Students, Corporate Employees, Delivery Operators Distribution Channel: Mobile Applications, Web Platforms, Call Centers, Kiosks, Partner Networks |
| Companies Covered | Uber Technologies Inc., Lyft Inc., Didi Chuxing Technology Co., Grab Holdings Inc., ANI Technologies Pvt. Ltd. (Ola Cabs), Zipcar Inc., SHARE NOW GmbH, BlaBlaCar, Bolt Technology OU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shared Mobility Market Strategic Shifts & Innovations
The market's evolution reflects a shift from pure disruption to industrial-scale optimization and integration. Operators are now focused on refining unit economics and embedding services within broader urban and corporate transportation ecosystems, moving beyond simple ride-hailing.
Vehicle-to-Everything (V2X) communication technology enables real-time data exchange between vehicles, infrastructure, and network platforms. Fleet operators are deploying V2X to improve safety and optimize traffic flow. This integration of telematics and connectivity is consolidating disparate operational functions like dispatch, maintenance, and energy management into unified command centers.
The EU's General Data Protection Regulation (GDPR) continues to set a global benchmark for data handling, influencing platform design far beyond Europe. This regulation forces operators to engineer privacy-by-design principles into their mobile applications and back-end systems. Global platforms are most affected, often adopting GDPR's strict consent and data minimization standards across all their markets to ensure a consistent and compliant user experience.
A transition toward Mobility-as-a-Service (MaaS) subscriptions is altering consumer purchasing habits. This model disrupts the pay-per-ride transaction, replacing it with bundled monthly access to multiple modes like bikes, scooters, and ride-hailing. The shift is most prominent in European cities with strong public transit networks and integrated multi-modal apps.
Shared Mobility Market Segmentation
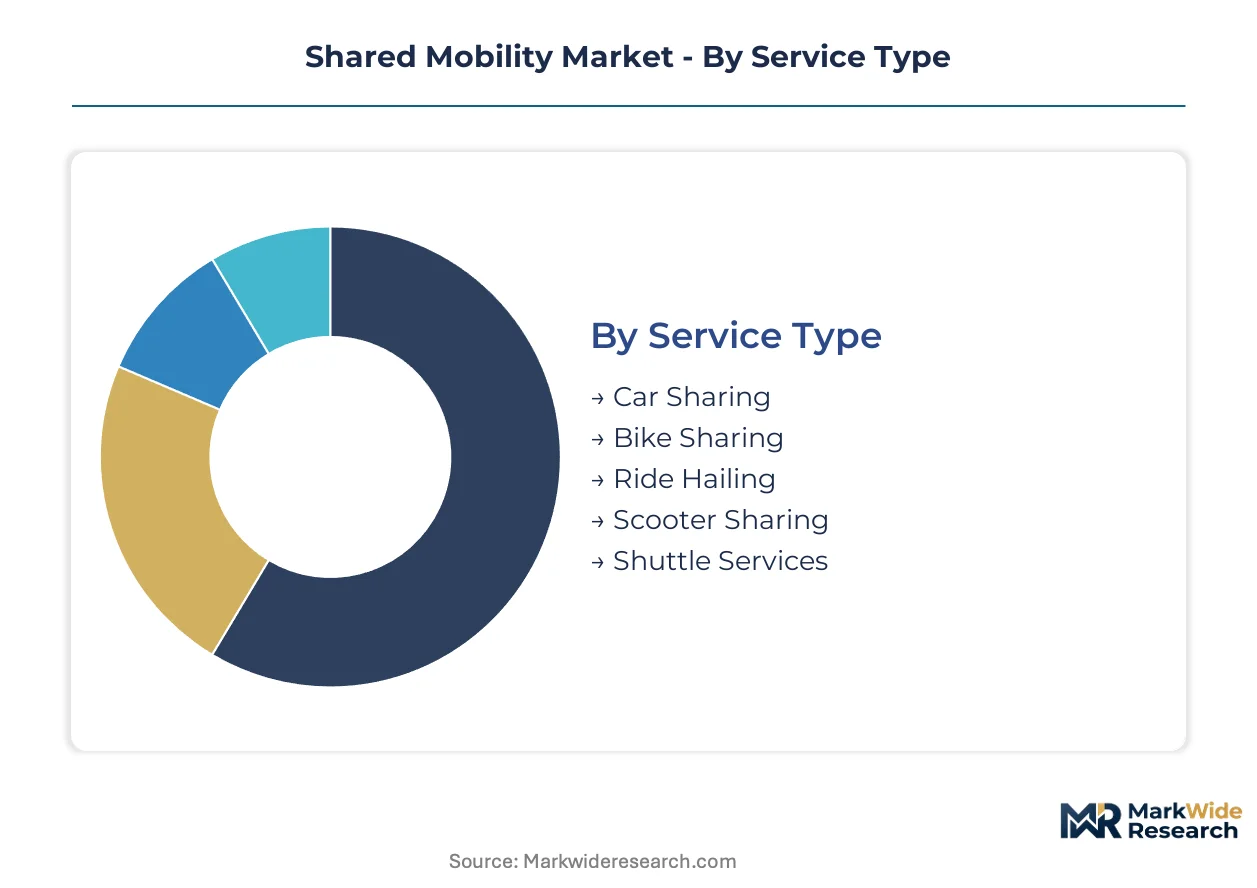
The shared mobility market's diverse service offerings and operational models necessitate a granular segmentation to understand demand patterns and strategic focus areas. This classification helps identify where technological investments yield the highest returns and how regulatory compliance shapes localized service deployment. Analyzing these segments provides clarity on market maturity and growth trajectories for various transportation solutions.
Service Type:
This category distinguishes segments by their level of integration into broader urban transport systems and their typical use cases, from standalone trips to first-and-last-mile solutions.
- Ride Hailing:This service involves on-demand personal transportation facilitated by digital platforms connecting passengers with drivers. Demand concentrates in dense urban centers globally, driven by convenience and the avoidance of private vehicle ownership in cities like Mumbai and Jakarta.
- Scooter Sharing:These services provide short-term access to electric scooters for individual use, managed via mobile applications. Demand is rapidly expanding in European cities such as Paris and Rome, addressing short-distance travel and urban congestion challenges.
- Car Sharing:This model offers short-term rental of vehicles, typically by the hour or day, often for self-driven trips.
- Bike Sharing:This service provides bicycles for short-term use, accessible through docking stations or dockless systems.
- Shuttle Services:These are pre-booked or on-demand shared rides, often operating on fixed routes or within specific zones.
Volume placements concentrate in Ride Hailing; the faster expansion belongs to Scooter Sharing.
Vehicle Type:
This category reflects the core assets deployed by operators, highlighting the shift towards electric and compact solutions for urban environments.
- Electric Bike:These pedal-assist bicycles are deployed for micro-mobility solutions, particularly effective in navigating urban congestion and providing an eco-friendly alternative. Their application is prominent in cities with dedicated bike lanes, such as Copenhagen and Amsterdam.
- Electric Scooter:Lightweight and agile, these vehicles cater to short-distance, last-mile connectivity, reducing reliance on private cars for quick errands. Their deployment is widespread across US metropolitan areas, including San Francisco and Austin.
- Sedan:Traditional four-door passenger cars form the backbone of many ride-hailing fleets, offering comfort and capacity.
- Mini Van:These larger vehicles provide increased passenger capacity, suitable for group travel or airport transfers.
- Compact Car:Smaller, fuel-efficient cars are utilized for car-sharing services, ideal for urban driving and parking.
The operational costs for Electric Scooter are generally lower, while Sedan commands higher per-trip revenue.
End User:
This category delineates the primary consumer demographics and their distinct motivations for utilizing shared mobility services.
- Corporate Employees:Businesses integrate shared mobility into travel policies for cost-effective and flexible transportation during business trips or daily commutes. This segment drives consistent demand in major business hubs like New York and London.
- Commuters:Daily travelers use shared services for routine journeys to work or school, often supplementing public transportation for first-and-last-mile solutions. This user group is critical in densely populated cities across India, including Bangalore and Delhi.
- Tourists:Visitors to new cities use shared mobility for convenient exploration and sightseeing without needing to rent a private car.
- University Students:This demographic frequently uses shared bikes and scooters for campus travel and short trips around college towns.
- Delivery Operators:Logistics companies utilize shared fleets, particularly cargo bikes and scooters, for efficient last-mile parcel delivery.
Demand from Commuters drives consistent daily usage, whereas Corporate Employees represent a growing segment for specialized services.
Distribution Channel:
This category examines the primary interfaces through which users access and manage shared mobility services, emphasizing digital platforms.
- Mobile Applications:Digital platforms on smartphones serve as the primary interface for booking, tracking, and managing shared mobility services. These applications leverage GPS and algorithmic dispatch for efficient fleet utilization across global markets.
- Partner Networks:Integration with public transit agencies or corporate travel platforms allows for bundled services and expanded reach. This channel is gaining traction in European cities aiming for comprehensive Mobility-as-a-Service ecosystems.
- Web Platforms:Online portals provide an alternative booking and management channel, often used for pre-planned trips or corporate accounts.
- Call Centers:Traditional phone-based support offers assistance for bookings, inquiries, and issue resolution, particularly for less tech-savvy users.
- Kiosks:Physical stations or terminals facilitate access to shared vehicles, especially common for bike-sharing systems in public spaces.
The reach of Mobile Applications is extensive, while Partner Networks offer localized support and specialized access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and similar policy frameworks drive significant shared mobility concentration in urban centers. These regulatory initiatives incentivize a shift from private car ownership to shared, on-demand transportation services. This creates distinct regional demand patterns and operational challenges for market participants.
India
Demand for shared mobility services in India is driven by vast transportation gaps and increasing urbanization. The Indian government's focus on smart city development encourages multimodal transport solutions. Densely populated cities like Mumbai and Bangalore show high utilization rates for app-based ride-hailing services.
China
China's shared mobility market experiences strong demand from its massive urban populations seeking efficient travel options. The MIIT heavily influences standards for vehicle connectivity and data security within this sector. Didi Chuxing Technology Co. dominates the Chinese market, integrating various mobility solutions across major cities.
France
French urban dwellers increasingly adopt shared mobility for short-distance travel and environmental benefits. Local municipal policies, aligned with the EU Green Deal, promote micromobility solutions and low-emission zones. Paris and other major French cities see rapid expansion in scooter sharing, addressing urban congestion.
United States
United States demand for shared mobility is concentrated in metropolitan areas, driven by convenience and reducing parking stress. Various US municipal transport authorities set local licensing and operational rules for shared services. San Francisco and Austin represent key markets for electric scooter deployment and innovation.
Singapore
Singapore's smart city initiatives and high urban density propel demand for integrated shared mobility solutions. The Land Transport Authority (LTA) actively regulates and supports the development of sustainable transport options. Grab Holdings Inc. utilizes its super-app strategy to offer diverse services across the city-state.
Shared Mobility Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the shared mobility market structure. This market shows elements of both consolidation among global ride-hailing platforms and fragmentation within micromobility services. Strategic archetypes include global platform operators, regional super-app providers, and specialized micro-mobility fleet managers. Dominant competitive moves involve strategic partnerships with automakers for EV access and continuous investment in proprietary platform technology.
At the scale-driven end, Uber Technologies Inc. represents a global platform operator leveraging its extensive network for ride-hailing and other services. Didi Chuxing Technology Co. occupies a dominant position within the vast Chinese market, exemplifying a regionally focused, integrated mobility provider with a strong local presence. Grab Holdings Inc. showcases the super-app archetype, offering diversified services across Southeast Asia through its mobile platform and expanding into fintech solutions.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Lyft Inc. |
| Didi Chuxing Technology Co. |
| Grab Holdings Inc. |
| ANI Technologies Pvt. Ltd. (Ola Cabs) |
| Zipcar Inc. |
| SHARE NOW GmbH |
| BlaBlaCar |
| Bolt Technology OU |
Cost & Logistics Intelligence
The extensive driver pool across India and Southeast Asia significantly impacts shared mobility pricing, creating wider spreads between economy and premium service tiers due to labor-cost differentials.
Pricing Analysis
Volume-driven ride-hailing services operate on thin margins, contrasting with higher-margin specialized offerings. The dominant pricing structure is per-trip transactional, with MaaS subscriptions gaining traction. Price differentiation stems from vehicle type and service level. Intense competition and regulatory fare caps exert downward pricing pressure, making commuters highly price-sensitive compared to corporate employees who prioritize convenience.
Supply Chain Analysis
Vehicle certification and local operational licensing requirements gate the shared mobility supply chain. Geographic supply concentrates in China for EV manufacturing and India for driver sourcing, drawing from global lithium-ion battery and electric motor producers. Single-source vulnerability for specialized EV components represents a structural risk. Distribution runs through mobile applications, directly connecting users to available vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shared mobility market is undergoing a fundamental technology-transition phase, as electric powertrains rapidly displace internal combustion engines across fleet operations.
For Market Incumbents:Deploy charging infrastructure rapidly to mitigate operational bottlenecks from infrastructure lag. Incumbents like Uber Technologies Inc. must forge strategic partnerships with automakers for preferential EV access. Continuous investment in proprietary platform technology reinforces competitive positioning against emerging specialized entrants. Advanced telematics integration optimizes fleet utilization and reduces maintenance costs.
For New Entrants and Emerging Players:Municipal transit agencies represent a critical channel for new entrants to integrate services. Focus on specialized vehicle segments like wheelchair-accessible transport or cargo e-bikes for logistics. Micro-mobility in congested city centers offers a penetrable segment, particularly through partnerships with local businesses. Bundled service offerings with public transit provide a compelling go-to-market angle.
For Investors and Strategic Acquirers:Re-rating potential sits with super-app providers given their diversified revenue streams beyond core mobility services. This market offers long-term viability as an essential component of future urban transportation ecosystems. Acquisition targets include specialized fleet operators demonstrating robust local regulatory compliance and efficient EV fleet management. Accelerated MaaS subscription uptake serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Fleet Transition | Accelerates decarbonization goals for urban transport. |
| MaaS Platform Integration | Bundles diverse mobility options for consumer convenience. |
| Charging Infrastructure Partnerships | Mitigates operational bottlenecks for electric fleets. |
| Data Privacy Compliance | Builds user trust and navigates complex regulatory environments like GDPR. |
| Micro-mobility Expansion | Addresses last-mile connectivity in congested urban areas. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with fleet operators, urban planners, and corporate travel managers provided critical insights. This approach combined bottom-up data collection with top-down validation through SEC filings and government transport statistics. Such triangulation ensured robust market sizing and trend identification.
Data-stream reconciliation across multiple sources informed the analytical framework over the projection horizon. Segmentation dimensions included service type, vehicle type, end user, distribution channel, and regional regulatory environment. Compound annual growth rates were derived from historical patterns and projected future demand. Urban density growth and EV charging infrastructure build-out served as key forecast inputs.
Caveats apply where rapid policy shifts or unforeseen technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions documented at the time of analysis. A model refresh is warranted upon material change in regulatory frameworks or consumer behavior.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
Vehicle Parking Meter Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Connected Parking Solutions Market