
 Smart Roads Market | 2026-2036
Smart Roads Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Roads Market Outlook
The EU Green Deal is recalibrating procurement criteria for roadway infrastructure across member states. Siemens AG anchors European smart intersection deployments through its Yunex Traffic subsidiary. Cisco Systems Inc. competes in edge-networking layers for connected corridors. Huawei Technologies Co. Ltd. dominates V2X communication hardware in Asian markets.
Smart roads integrate sensor networks, edge computing nodes, and V2X communication protocols to enable real-time traffic optimization and autonomous vehicle coordination. These systems typically operate on sub-100-millisecond latency thresholds to support safety-critical applications. Traffic Management Systems command the largest installed base, while Sensor Networks represent the fastest-expanding segment as pavement-embedded IoT density rises. Cloud-Based deployment models capture growing share among municipalities seeking reduced capital overhead.
The European Commission's F-Gas Regulation and the U.S. Department of Transportation's ITS deployment guidelines shape equipment standards and interoperability mandates. China's MIIT issues GB standards for connected vehicle infrastructure, creating distinct certification requirements. Stakeholders must monitor diverging regional technical specifications when configuring multi-country product platforms.
Market Dynamics
EU Green Deal compliance timelines are compressing procurement cycles for connected corridor infrastructure as municipal authorities accelerate V2X deployment schedules to meet 2030 carbon reduction benchmarks.
Growth Catalysts
- F-Gas Regulation:The European Commission's phasedown mandates are forcing replacement of conventional traffic signal cooling systems with low-global-warming-potential alternatives, creating hardware refresh cycles across Germany, France, and Italy.
- Edge computing density:Pavement-embedded sensor networks capable of sub-100-millisecond latency are enabling real-time autonomous vehicle coordination, pulling demand from traffic management authorities in the United States and China.
- Cloud migration:Municipal budget constraints are accelerating shift from on-premise traffic control centers to subscription-based cloud deployments, reducing capital overhead for mid-sized cities.
Market Restraints
- Semiconductor supply concentration:V2X communication chip fabrication concentrates in Taiwan and South Korea, exposing deployment timelines to foundry capacity constraints and geopolitical friction.
- Interoperability fragmentation:China's MIIT-issued GB standards for connected vehicle infrastructure diverge from IEEE 1609 protocols used in North America, forcing redundant certification investments for multi-country platforms.
- Copper and rare earth volatility:Sensor network cabling and magnet components face input cost swings tied to extraction quotas in the Democratic Republic of Congo and Chinese processing dominance.
Strategic Opportunities
- India corridor modernization:National highway expansion under the Bharatmala program creates greenfield deployment potential for V2X-enabled tolling and incident detection systems.
- Digital twin convergence:Integration of real-time traffic data with 3D infrastructure modeling is opening predictive maintenance contracts for aging bridge and tunnel assets.
- Utility partnerships:Smart road deployments are embedding inductive charging coils and photovoltaic pavement trials, creating new revenue-sharing structures with electricity distributors.
Industry Challenges
- Embedded systems engineering shortage:Firmware development for sub-100-millisecond safety-critical applications requires specialized talent pools concentrated in Germany, Japan, and California.
- Legacy signal controller integration:1980s-era electromechanical traffic cabinets in older US municipalities resist retrofit with IP-based communication protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Roads Market |
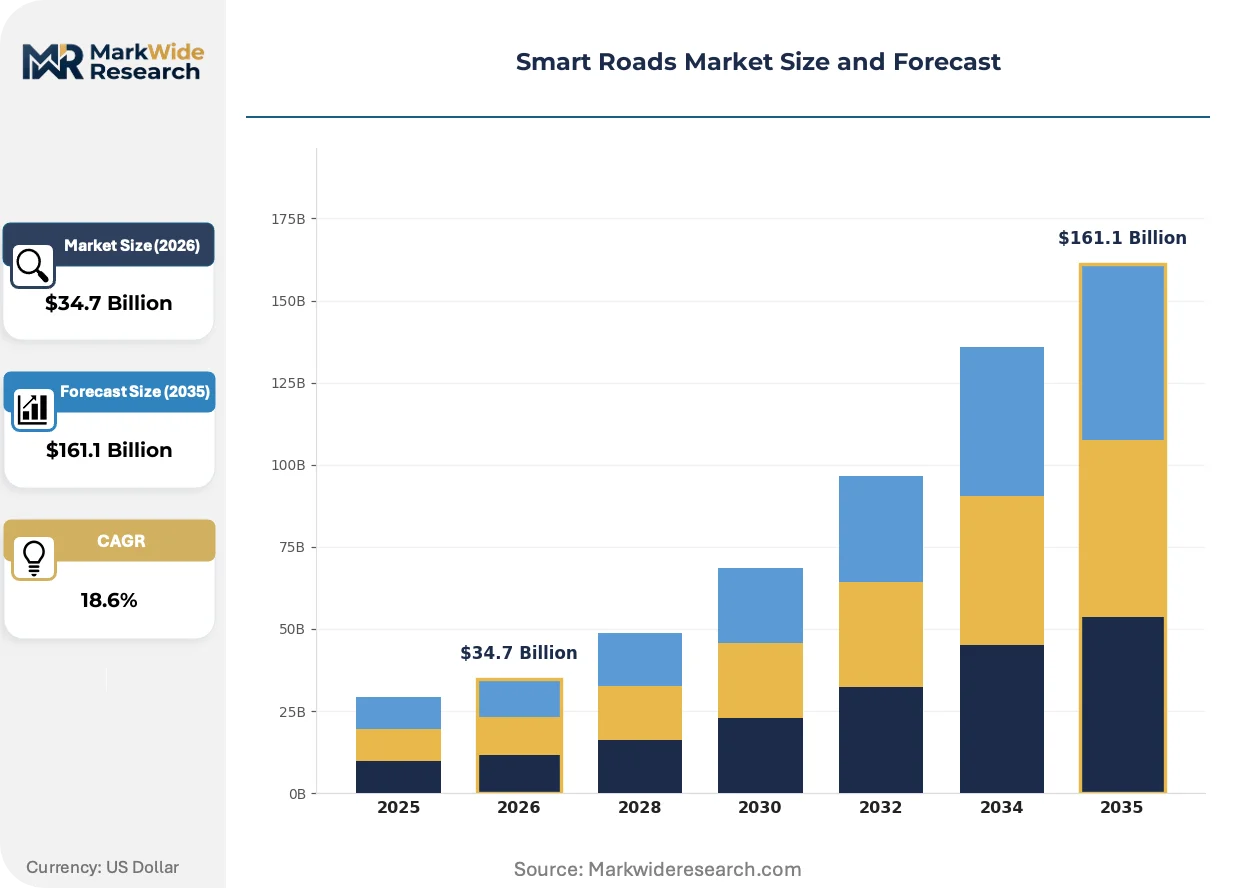
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $161.1 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: V2X Communication, Traffic Management Systems, Smart Signage, Sensor Networks Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Traffic Monitoring, Incident Management, Autonomous Driving, Infrastructure Management End User: Government Agencies, Transportation Authorities, Municipalities, Private Sector |
| Companies Covered | ABB Ltd, Siemens AG, Huawei Technologies Co. Ltd., Yunex Traffic, Kapsch TrafficCom, International Business Machines Corporation, Honeywell International Inc., Indra, Cisco Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Roads Market Strategic Shifts
Real-time data fusion architectures are compressing the boundary between roadside sensors and centralized traffic management platforms, enabling predictive rather than reactive congestion mitigation.
Cellular V2X (C-V2X) is overtaking dedicated short-range communication as the dominant connectivity protocol for vehicle-to-infrastructure messaging. Traffic authorities in Germany and China are prioritizing 5G-based roadside units over 802.11p hardware in new procurements. This protocol shift is collapsing the installed base of DSRC-only equipment and forcing dual-mode compatibility investments from legacy suppliers.
The EU AI Act's risk classification framework is imposing documentation and transparency requirements on automated traffic signal optimization algorithms. System vendors must now maintain model training logs and human oversight interfaces for safety-critical decision paths. European deployments are absorbing compliance costs through extended engineering timelines, while US and Chinese competitors face uncertainty on algorithm exportability.
Performance-based service contracts are displacing capital equipment purchases for mid-sized municipal buyers. French and Italian transportation authorities now specify uptime guarantees and congestion reduction metrics rather than hardware unit counts in tender documents. Channel partners with field service capabilities are capturing margin previously retained by original equipment manufacturers.
Smart Roads Market Segmentation
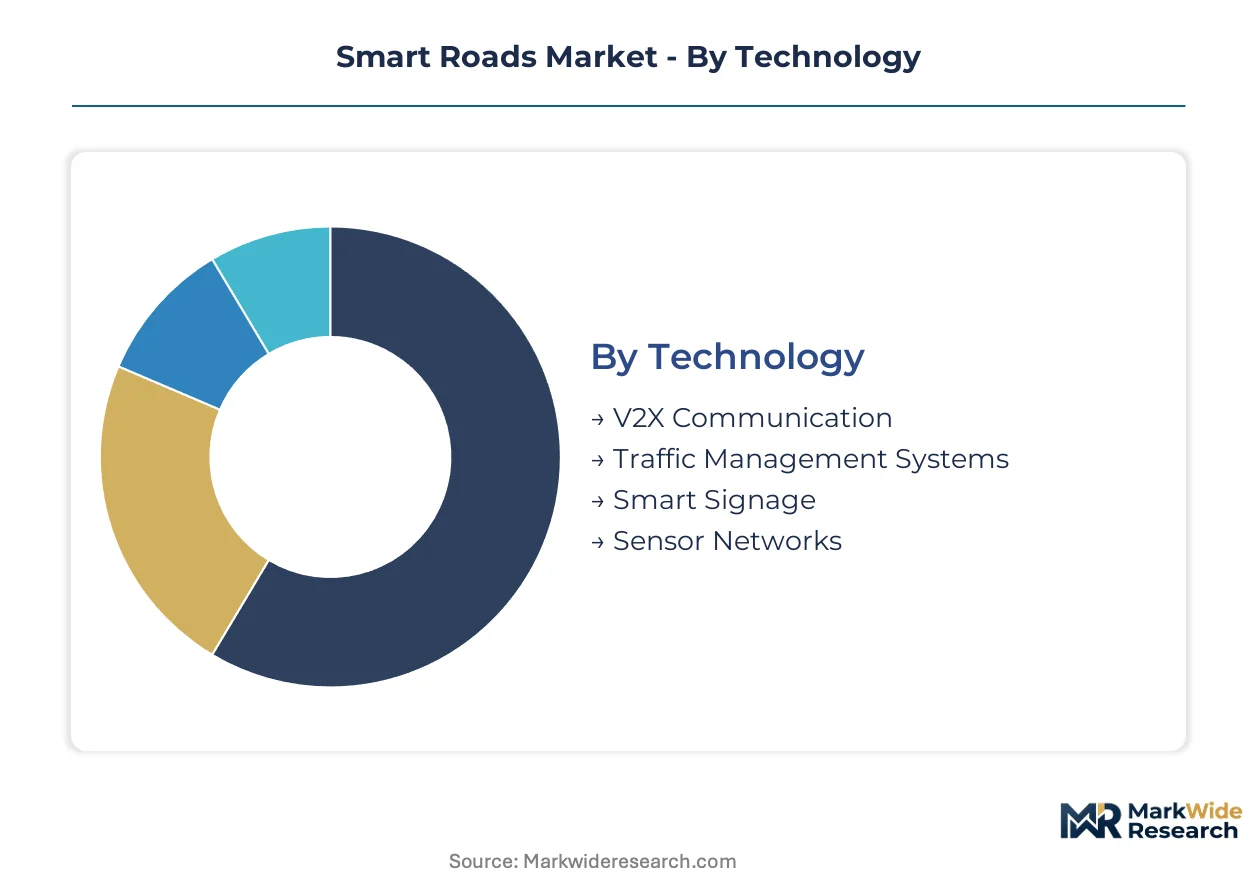
Smart roads require layered technology stacks with divergent capital profiles. Procurement patterns vary sharply between legacy infrastructure retrofits and greenfield autonomous corridors. Understanding segment-level investment thresholds enables vendors to align product roadmaps with buyer budget cycles.
Technology:
Capital intensity peaks in embedded hardware requiring civil works, while software layers deploy faster with lower upfront commitment.
- V2X Communication:Dedicated roadside units and onboard modules exchange safety-critical messages over PC5 or Uu interfaces. German and Chinese transportation authorities prioritize 5G-based C-V2X procurements, collapsing demand for legacy DSRC hardware. Deployment concentrates in connected corridors along the Rhine-Alpine and Beijing-Shanghai freight axes.
- Traffic Management Systems:Centralized platforms integrate signal control, variable message signs, and detection loops through proprietary or open-architecture protocols. Municipal authorities in the United States and France dominate installed base, driven by congestion reduction mandates and F-Gas Regulation compliance timelines forcing controller refresh cycles.
- Smart Signage:LED and e-paper displays deliver dynamic speed limits and lane guidance.
- Sensor Networks:Pavement-embedded accelerometers, magnetometers, and environmental monitors feed edge nodes.
Most installed capacity flows through Traffic Management Systems. Expansion is steepest in Sensor Networks.
Deployment Model:
Operational expenditure versus capital expenditure trade-offs reshape municipal procurement preferences across budget cycle lengths.
- On-Premises:Dedicated traffic control centers with localized servers and fiber backhaul demand substantial civil infrastructure and IT staffing. Large German municipalities retain preference for sovereign data architectures under GDPR and national cybersecurity frameworks, sustaining demand despite higher lifecycle costs.
- Cloud-Based:Subscription-hosted platforms eliminate server procurement and reduce facility requirements. Mid-sized French and Italian cities accelerate migration under performance-based service contracts specifying uptime guarantees rather than hardware ownership, compressing deployment timelines from years to months.
- Hybrid:Critical safety functions run locally while analytics shift to hosted environments.
- Edge Computing:Roadside nodes process sensor fusion with sub-100-millisecond latency for autonomous coordination.
Hybrid architectures dominate new procurements in privacy-sensitive jurisdictions. Cloud-Based deployments are gaining share fastest among municipalities under fiscal pressure.
Application:
Use case maturity determines whether buyers seek proven solutions or pilot-stage technologies with higher risk tolerance.
- Traffic Monitoring:Loop detectors, video analytics, and radar systems measure flow, occupancy, and queue lengths. Chinese provincial transport departments deploy at scale under MIIT-connected vehicle infrastructure guidelines, integrating real-time data with provincial command centers for corridor-level optimization.
- Incident Management:Automated detection and response workflows reduce secondary collision risk. United States state DOTs concentrate investment along Interstate corridors with high commercial vehicle density, driven by FHWA Highway Safety Improvement Program incentives and liability exposure reduction.
- Autonomous Driving:High-definition map updates and cooperative perception enable SAE Level 4 operation.
- Infrastructure Management:Structural health monitoring of bridges, tunnels, and pavement condition.
Traffic Monitoring carries the largest installed base. Autonomous Driving applications are climbing the fastest as pilot zones expand.
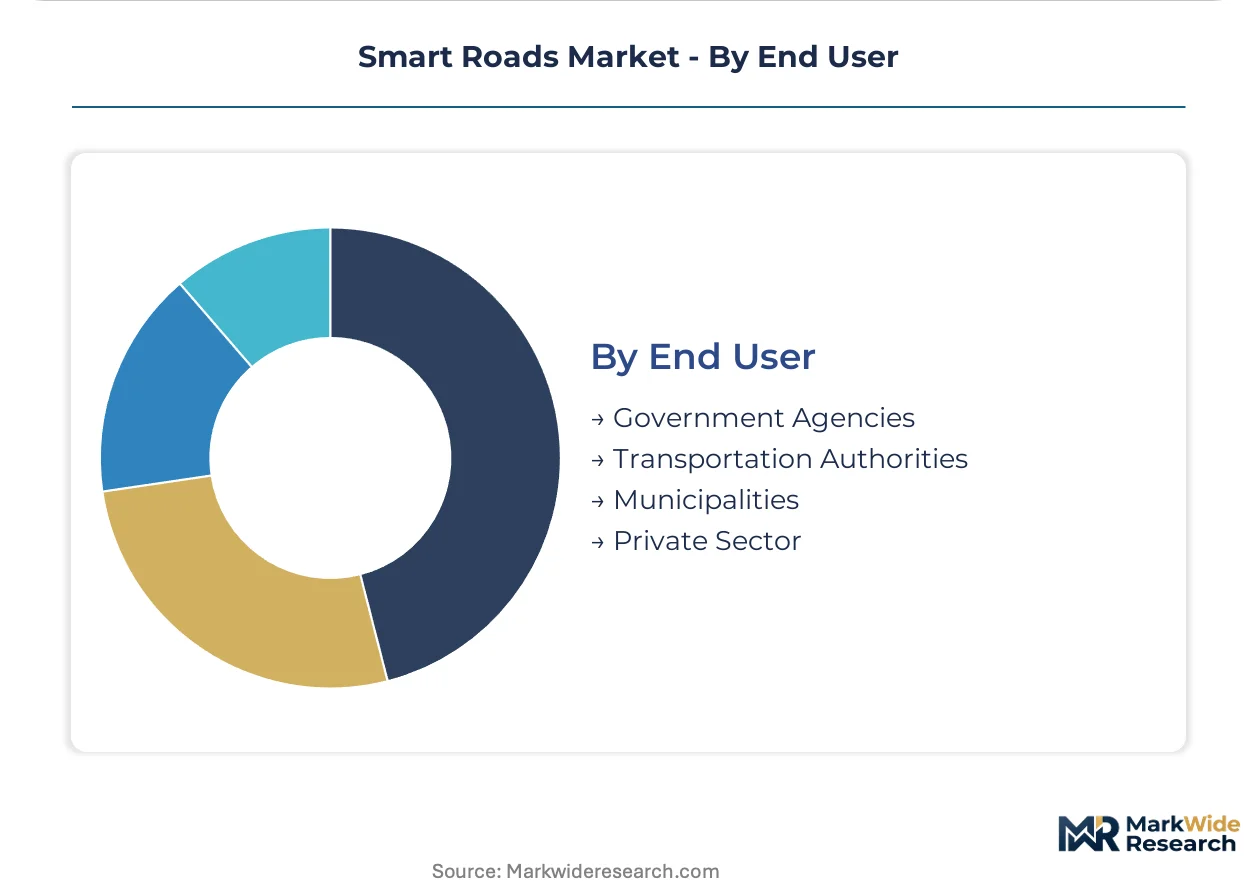
End User:
Procurement sophistication and contract scale diverge between centralized national programs and fragmented local authorities.
- Government Agencies:National ministries and federal departments specify multi-year programs with standardized technical requirements. India's Ministry of Road Transport and Highways channels Bharatmala corridor investments through centralized tenders, creating volume opportunities for integrated system vendors.
- Transportation Authorities:Regional bodies manage arterial networks and transit corridors with operational autonomy. German state-level Straßenbauverwaltungen balance EU Green Deal compliance with legacy asset replacement, generating sustained demand for interoperable V2X infrastructure.
- Municipalities:City governments control urban signal networks and local street deployment.
- Private Sector:Logistics operators and autonomous vehicle developers fund pilot deployments.
Government Agencies command the largest contract values. Private Sector involvement is expanding most quickly as OEMs seek testbed access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers concentrated in Germany, Japan, and California anchor smart road development capacity. Their expertise in sub-100-millisecond firmware development determines deployment feasibility for safety-critical V2X applications. Geographic clustering of this talent shapes regional competitive advantages.
United States
State DOTs along Interstate corridors with high commercial vehicle density drive incident management investment. The FHWA Highway Safety Improvement Program incentivizes automated detection and response workflows. Greater Boston and Silicon Valley clusters concentrate edge-computing node development for autonomous coordination.
Germany
Straßenbauverwaltungen at state level balance EU Green Deal compliance with legacy asset replacement. The F-Gas Regulation forces replacement of conventional traffic signal cooling systems with low-global-warming-potential alternatives. Rhine-Alpine freight corridors concentrate connected corridor procurement under compressed 2030 carbon reduction timelines.
China
Provincial transport departments deploy traffic monitoring at scale under MIIT-connected vehicle infrastructure guidelines. GB standards for connected vehicle infrastructure create distinct certification requirements diverging from IEEE 1609 protocols. Beijing-Shanghai freight axes concentrate C-V2X roadside unit deployment as authorities prioritize 5G-based hardware.
India
The Ministry of Road Transport and Highways channels Bharatmala corridor investments through centralized tenders for V2X-enabled tolling. National highway expansion creates greenfield deployment potential without legacy electromechanical constraints. Gujarat and Maharashtra industrial corridors attract pilot deployments for incident detection systems.
France
Transportation authorities specify performance-based service contracts with uptime guarantees rather than hardware ownership. Subscription-hosted platforms accelerate migration among mid-sized cities under fiscal pressure. Île-de-France and Auvergne-Rhône-Alpes regions compress deployment timelines from years to months through cloud migration.
Smart Roads Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the smart road technology stack. The vendor base separates between integrated infrastructure conglomerates owning civil-electrical capabilities and specialized software firms licensing traffic optimization algorithms. Three archetypes dominate: traffic management platform vendors, V2X communication hardware fabricators, and edge-computing node specialists. Strategic moves center on dual-mode compatibility investments for C-V2X transitions and performance-based service contract capture.
Among European infrastructure conglomerates, Siemens AG and ABB Ltd exemplify integrated players with civil-electrical capabilities spanning signal control to power distribution. Huawei Technologies Co. Ltd. occupies a distinct position in V2X communication hardware fabrication. Cisco Systems Inc. represents the edge-networking specialist archetype competing in connected corridor data layers.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Huawei Technologies Co. Ltd. |
| Yunex Traffic |
| Kapsch TrafficCom |
| International Business Machines Corporation |
| Honeywell International Inc. |
| Indra |
| Cisco Systems Inc. |
| Others |
Value Chain & Pricing Dynamics
C-V2X protocol transitions are compressing hardware refresh cycles while concentrating procurement power among transportation authorities in Germany, China, and the United States. This technology shift simultaneously elevates R&D amortization costs for dual-mode compatibility and consolidates supplier margins around 5G-enabled roadside unit fabricators with proven sub-100-millisecond latency credentials.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs smart road deployments. Premium tiers command certification-grade positioning under EU AI Act documentation requirements and F-Gas Regulation compliance, while economy tiers serve Indian and Southeast Asian greenfield corridors with stripped-down sensor density. Cost compression in standard-tier traffic management systems is intensifying because municipal budget constraints are accelerating cloud migration. Mid-sized French and Italian cities exhibit highest price sensitivity due to performance-based contract structures, whereas German state Straßenbauverwaltungen absorb premium pricing for sovereign data architectures.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for V2X roadside units and edge-computing nodes. Semiconductor fabrication concentrates in Taiwan and South Korea, while rare earth processing for sensor magnet components centers on Chinese facilities. Copper cabling and pavement-embedded IoT enclosures draw from German and Japanese precision manufacturers. Single-source vulnerability around TSMC foundry capacity for automotive-grade chips poses the dominant structural risk. Distribution runs through systems integrators with civil-electrical capabilities rather than direct OEM-to-municipality channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart roads market functions as a regulatory compounder where EU Green Deal 2030 carbon reduction benchmarks and F-Gas Regulation phasedown mandates are compressing procurement timelines and forcing hardware refresh investments across European transportation authorities.
For Market Incumbents: Extend dual-mode C-V2X/DSRC compatibility roadmaps to capture legacy equipment replacement cycles in the United States and Germany. Deepen backward integration into edge-computing firmware development to offset embedded systems engineering talent scarcity concentrated in California and Japan. Lock in performance-based service contract templates with French and Italian municipalities before channel partners capture OEM margin. For New Entrants and Emerging Players: Municipal engineering consultants with civil works expertise represent the most accessible channel partner type for bypassing entrenched systems integrators. Target India's Bharatmala corridor modernization under centralized Ministry of Road Transport and Highways tenders, where greenfield deployment lacks legacy electromechanical constraints. Pursue predictive maintenance contracts for aging bridge and tunnel assets as the most penetrable application segment with lower certification barriers than safety-critical V2X messaging. For Investors and Strategic Acquirers: Valuations sit cheapest among edge-computing node specialists with proven sub-100-millisecond latency credentials but limited geographic footprint. Long-term viability over the next decade hinges on C-V2X protocol dominance and 5G roadside unit deployment velocity. Watch for MIIT GB standard harmonization signals with IEEE 1609 protocols as the critical inflection indicator for multi-country platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode C-V2X/DSRC Compatibility Investment | Captures legacy equipment replacement cycles in Germany and United States procurement windows. |
| Performance-Based Service Contract Capture | Shifts revenue from hardware sales to uptime guarantees under French and Italian tender structures. |
| Backward Integration into Firmware Development | Offsets embedded systems engineering scarcity concentrated in Germany, Japan, and California talent pools. |
| Cloud Migration Partnership Structuring | Accelerates deployment timelines for mid-sized municipalities under fiscal pressure in France and Italy. |
| Digital Twin Convergence Development | Opens predictive maintenance contracts for aging bridge and tunnel assets in United States and European markets. |
Study Parameters
Coverage spans Germany, China, the United States, India, and France, with primary inputs from each regional cluster. The analysis combines structured interviews with transportation authority procurement officers, traffic management system engineers, V2X hardware product managers, and municipal IT directors with secondary validation from SEC filings, EU tender databases, MIIT GB standard documentation, and FHWA Highway Safety Improvement Program disbursement records. Bottom-up deployment tracking and top-down infrastructure investment forecasts were triangulated to establish segment-level sizing.
Rate-of-change decomposition anchored the analytical framework across the analysis window. Segmentation dimensions modeled include technology layer, deployment model, application use case, and end-user procurement sophistication. CAGRs were derived from infrastructure investment pipeline analysis and regulatory milestone timing. Forecast inputs incorporated EU Green Deal compliance timeline acceleration, F-Gas Regulation hardware refresh cycle compression, and C-V2X protocol transition velocity across German and Chinese transportation authorities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity constraints, geopolitical friction affecting Taiwan and South Korean fabrication, and divergence between China's MIIT GB standards and IEEE 1609 protocols. Outputs reflect documented assumptions around municipal budget elasticity and autonomous vehicle pilot zone expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Smart Bus Shelters Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
E-Bike Rental Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Smart Chassis Market