
 Netherlands Solar E-Bike Market | 2026-2036
Netherlands Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Solar E-Bike Market Insights
Single-source battery procurement is decoupling from traditional supplier relationships as Dutch assemblers diversify photovoltaic component sourcing. Accell Group leverages integrated European supply lines for frame and motor assembly. Royal Dutch Gazelle sustains domestic manufacturing presence in Dieren while navigating Asian solar panel partnerships. VanMoof controls direct-to-consumer distribution channels across Dutch urban centers.
Solar e-bikes integrate photovoltaic cells into frame surfaces or detachable panels to supplement lithium-ion battery systems, converting sunlight into auxiliary electrical energy for pedal-assist propulsion. Cargo e-bikes dominate commercial fleet deployments due to last-mile delivery electrification mandates. Commuters represent the fastest-growing end user segment as employers expand cycle-to-work benefit schemes. Solar-powered charging technology captures margin concentration through reduced grid dependency and lower lifetime operating costs.
Rijkswaterstaat infrastructure standards and Nederlandse Organisatie voor toegepast-natuurwetenschappelijk onderzoek (TNO) testing protocols shape vehicle safety and solar conversion efficiency benchmarks. The SDE++ subsidy framework and municipal low-emission zone expansions directly condition purchase incentives and fleet conversion timelines. Stakeholders must monitor provincial grid interconnection rules and building code amendments for rooftop solar charging integration.
Market Dynamics
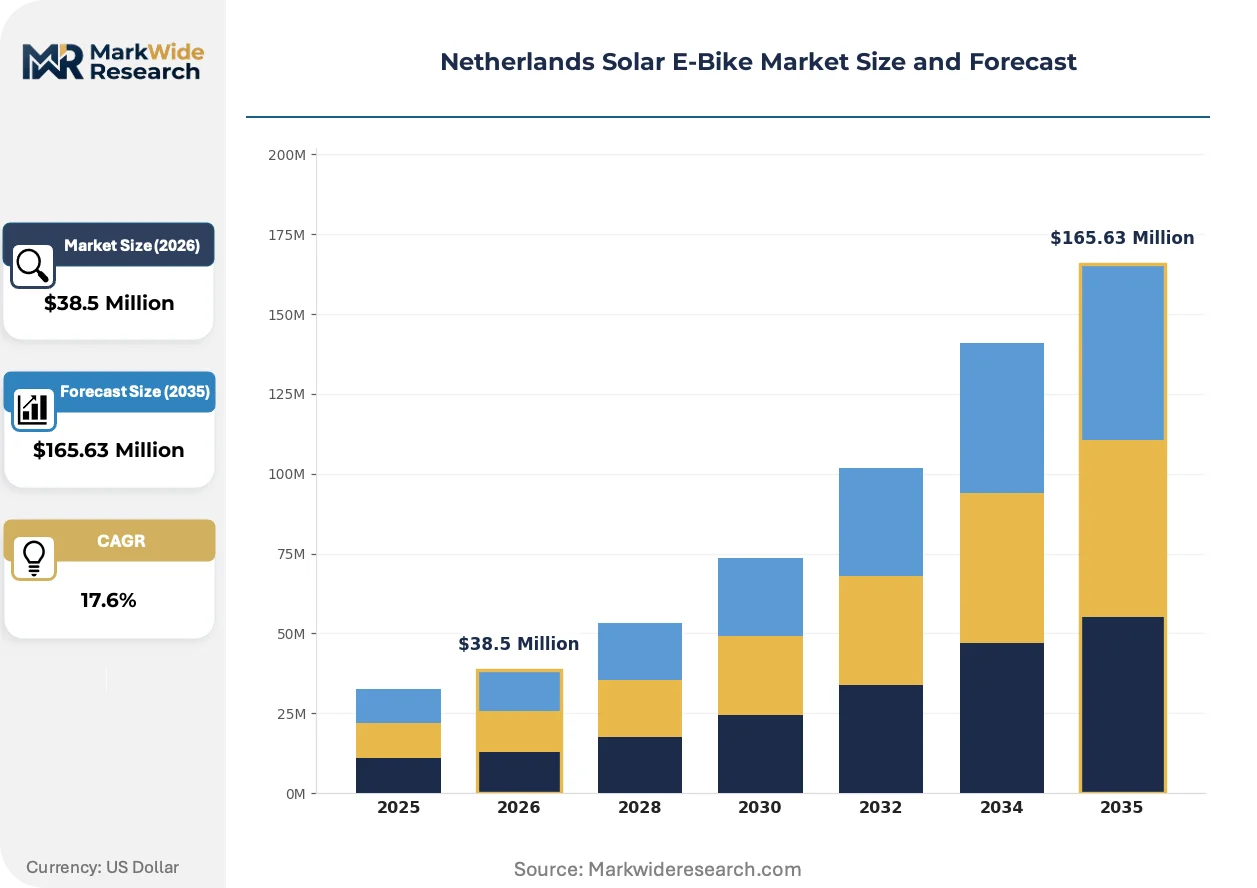
Single-source battery procurement is decoupling from traditional supplier relationships as Dutch assemblers diversify photovoltaic component sourcing. The SDE++ subsidy framework and municipal low-emission zone expansions directly condition purchase incentives and fleet conversion timelines.
Growth Catalysts
- SDE++ Subsidy Scheme:The Stimulering Duurzame Energieproductie program expands charging station networks across Randstad metropolitan corridors, reducing infrastructure cost barriers for commercial fleet operators.
- Last-Mile Delivery Mandates:Urban logistics electrification requirements in Amsterdam and Rotterdam accelerate cargo e-bike deployments for parcel and food service distribution.
- Cycle-to-Work Benefit Expansion:Employer-sponsored mobility schemes extend tax-advantaged lease structures to solar-assisted models, broadening commuter access beyond traditional pedal-assist categories.
Market Restraints
- Lithium-Ion Cell Concentration:Battery pack dependency on Asian cathode material suppliers exposes assemblers to freight cost volatility and geopolitical supply disruptions.
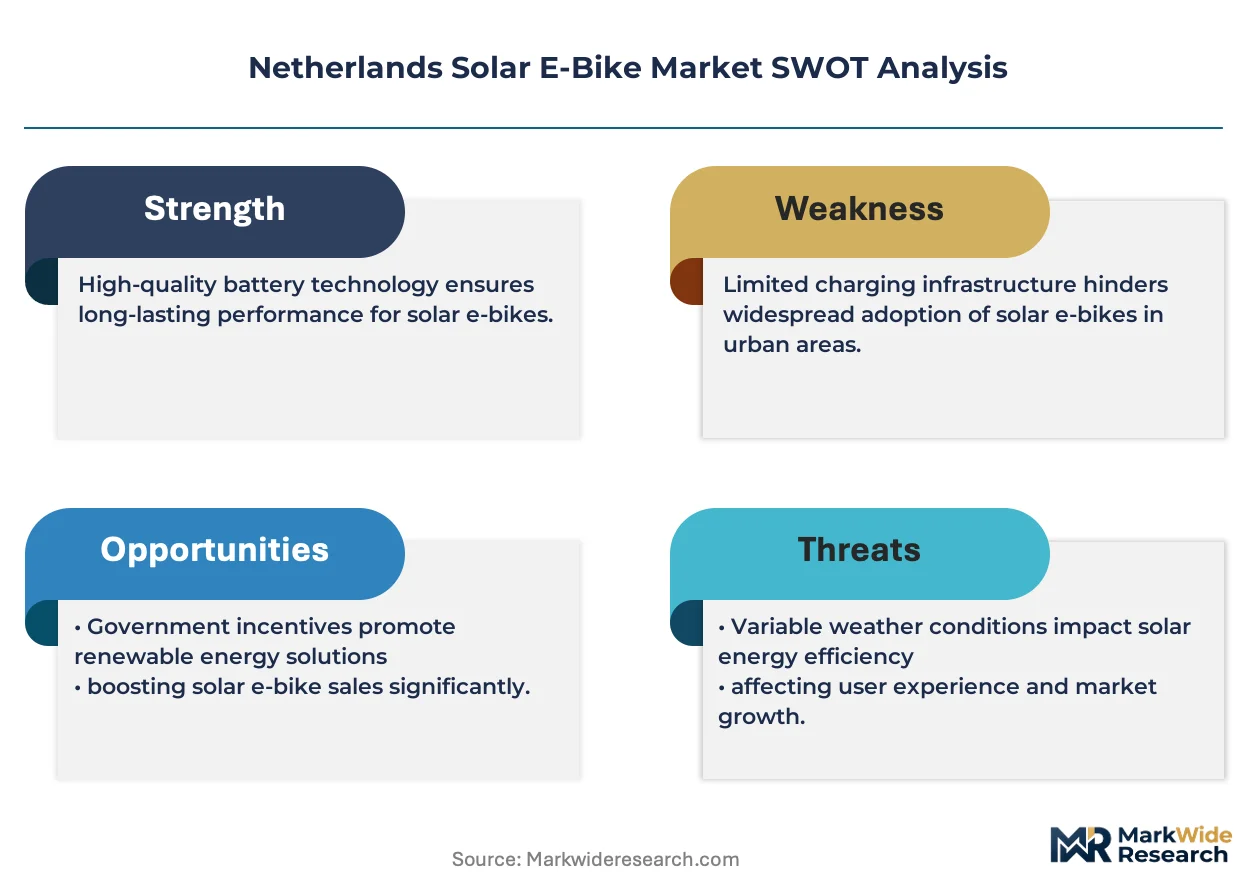
- Photovoltaic Conversion Limits:Frame-integrated solar cells deliver auxiliary rather than primary charging, constraining range extension claims and consumer value perception.
- Grid Interconnection Friction:Provincial building code variations for rooftop solar charging integration create permitting delays for residential and workplace installations.
Strategic Opportunities
- Workplace Charging Infrastructure:Untapped commercial real estate in Utrecht and Eindhoven offers fleet aggregation points for employer-sponsored solar charging hubs.
- Photovoltaic-Motor Convergence:Integration of thin-film solar surfaces with mid-drive motor thermal management systems enables direct energy transfer without intermediate battery storage.
- Subscription Mobility Models:Direct-to-consumer platforms bypass traditional bicycle retail channels, capturing recurring revenue through bundled maintenance and energy services.
Industry Challenges
- TNO Certification Timelines:Extended testing protocols for solar conversion efficiency and vehicle safety delay product launch cycles and tie up R&D capital.
- Multi-Supplier Integration Complexity:Coordinating photovoltaic cell, motor controller, and frame manufacturers across European and Asian supply lines strains quality assurance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Solar E-Bike Market |
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $165.63 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solo E-Bikes, Tandem E-Bikes, Cargo E-Bikes, Folding E-Bikes End User: Commuters, Recreational Users, Delivery Services, Tourists Battery Type: Lithium-Ion, Lead-Acid, Solid-State, Nickel-Metal Hydride Charging Technology: Solar-Powered, Standard Charging, Regenerative Braking, Fast Charging |
| Companies Covered | Accell Group, Pon Holdings, Royal Dutch Gazelle, VanMoof, Koga, Batavus, CUBE Bikes, Giant Manufacturing, Trek Bicycle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Solar E-Bike Market Trends and Innovations
Photovoltaic integration is migrating from bolt-on accessories to structural frame elements, compressing assembly steps and altering competitive differentiation. Three developments are reshaping how Dutch manufacturers configure product architectures and capture value.
Perovskite-silicon tandem cells are consolidating auxiliary charging performance for urban commuter segments. Frame-embedded photovoltaic layers now supplement lithium-ion reserves during daylight operation, extending effective range by fifteen to twenty kilometers. Royal Dutch Gazelle and Accell Group procurement teams are qualifying these cells for 2025 model year integration, compressing supplier qualification cycles from eighteen to twelve months.
Rijkswaterstaat infrastructure standards now mandate unified connector protocols for public charging points across all twelve provinces. The harmonization eliminates proprietary cable incompatibilities that previously fragmented fleet deployment decisions. Municipal procurement offices in The Hague and Rotterdam are accelerating tender specifications that reference these standards, forcing smaller assemblers to redesign electrical architectures.
Employer lease schemes are displacing direct consumer purchase as the dominant acquisition channel for premium solar e-bike categories. Human resources departments negotiate fleet contracts with integrated maintenance and energy monitoring services, unbundling traditional retail margins. This channel rotation concentrates volume with assemblers possessing direct-to-business sales infrastructure, particularly visible among technology sector employers in Amsterdam's Zuidas district.
Netherlands Solar E-Bike Market Segmentation
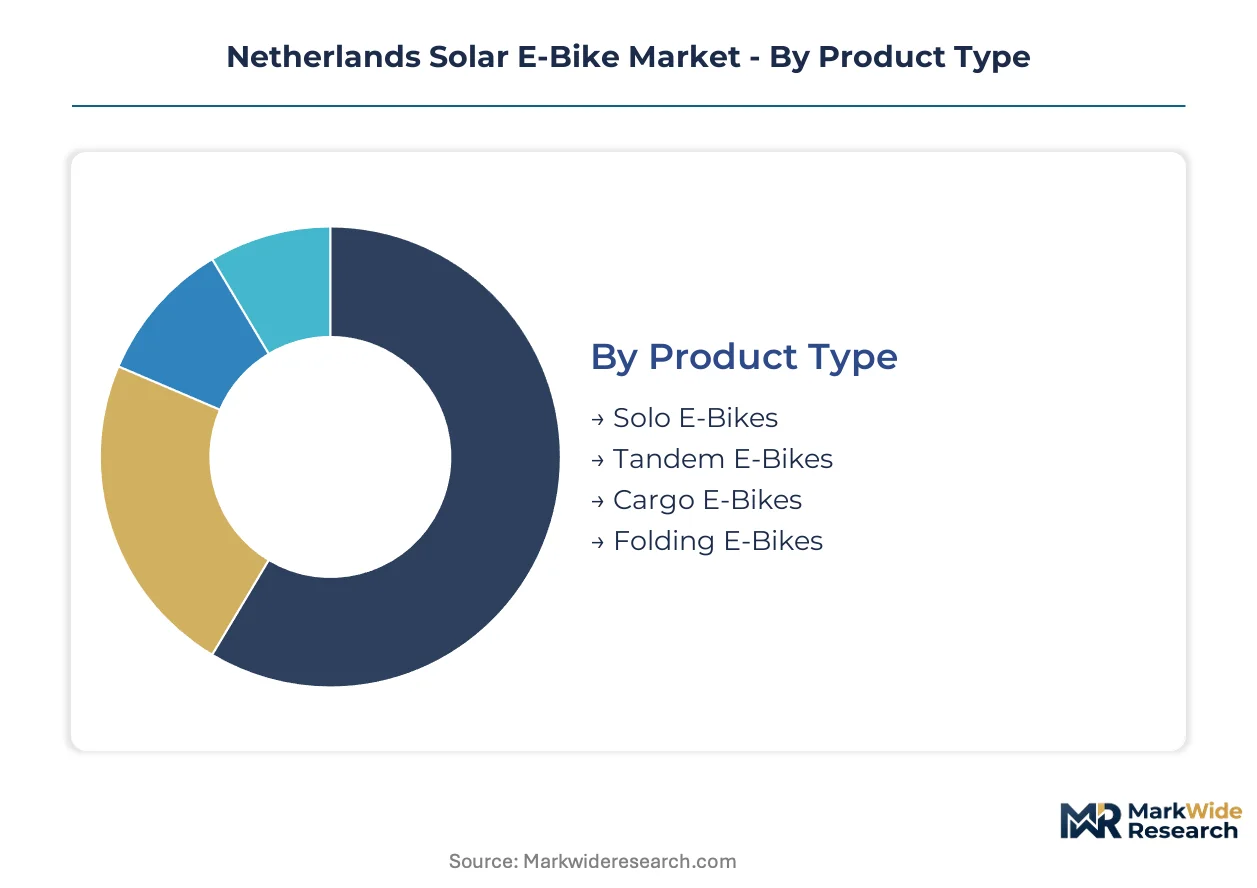
Segmentation in the Dutch solar e-bike market reveals how photovoltaic integration, battery chemistry, and charging infrastructure align with distinct mobility use cases across Randstad urban corridors and provincial networks. Understanding these divisions exposes where subsidy efficiency, fleet economics, and consumer willingness-to-pay converge.
Product Type:
Frame architecture and load capacity specifications determine solar panel surface area, battery placement, and motor torque requirements across Dutch manufacturing lines.
- Cargo E-Bikes:Extended wheelbases accommodate integrated photovoltaic roof panels and dual battery systems for commercial payload capacity. Amsterdam and Rotterdam last-mile delivery fleets prioritize these configurations under municipal electrification mandates, with SDE++ subsidies offsetting higher capital costs for logistics operators.
- Solo E-Bikes:Standard frame geometries embed thin-film solar cells into top tubes and seat posts for auxiliary charging during daylight commuting. Urban professionals in Utrecht and The Hague dominate procurement through employer lease schemes, valuing reduced grid dependency for daily Randstad corridor travel.
- Tandem E-Bikes:Dual-rider configurations require reinforced frame structures with distributed solar cell arrays across elongated top tubes.
- Folding E-Bikes:Compact hinge mechanisms limit photovoltaic surface area to detachable handlebar-mounted panels.
Cargo e-bikes lead on scale through fleet aggregation; solo e-bikes lead on momentum through commuter benefit expansion.
End User:
Acquisition channel economics and usage intensity vary sharply between commercial fleet operators and individual mobility subscribers.
- Delivery Services:Parcel and food distribution networks in Amsterdam, Rotterdam, and Eindhoven deploy solar-assisted cargo fleets to comply with low-emission zone requirements. These operators negotiate direct maintenance contracts with assemblers, bypassing retail markup and capturing energy monitoring services as bundled offerings.
- Commuters:Employer-sponsored cycle-to-work schemes in the Zuidas district and Utrecht Science Park extend tax-advantaged leases to solar-assisted categories. Human resources departments aggregate demand across technology and professional services firms, concentrating volume with direct-to-business sales infrastructure.
- Recreational Users:Weekend cyclists in Gelderland and Limburg provinces prioritize range extension for rural route exploration.
- Tourists:Rental operators at Schiphol and central station hubs offer short-term solar e-bike access for intercity exploration.
Delivery services lead on scale through mandate-driven fleet conversion; commuters lead on momentum through benefit scheme expansion.
Battery Type:
Chemistry selection determines energy density, cycle life, and compatibility with photovoltaic auxiliary charging systems.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate chemistries dominate Dutch assembly lines for their charge acceptance rates and thermal stability during solar trickle charging. Accell Group and Royal Dutch Gazelle procurement teams qualify cells from multiple Asian suppliers to mitigate freight cost volatility.
- Solid-State:Emerging ceramic electrolyte architectures promise higher energy density for frame-integrated battery compartments without thermal runaway risks. TNO testing protocols currently extend certification timelines for these configurations, delaying commercial deployment.
- Lead-Acid:Heavy, low-cycle-life chemistry persists only in price-sensitive rental fleet subsegments.
- Nickel-Metal Hydride:Moderate energy density chemistry occupies niche applications in university research fleets.
Lithium-ion leads on scale through supply chain maturity; solid-state leads on momentum through safety and density advantages.
Charging Technology:
Energy input methods determine infrastructure dependency, operating cost structure, and grid interconnection requirements.
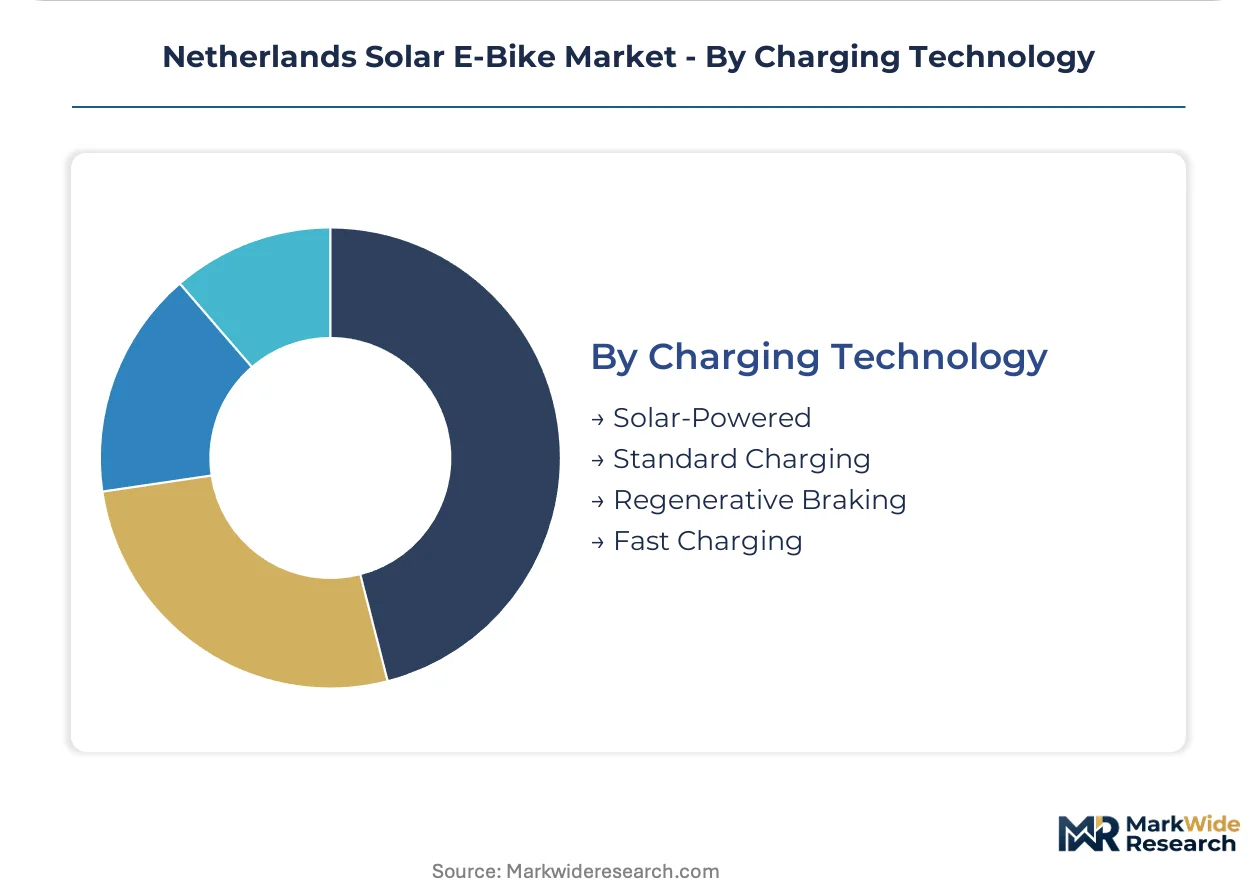
- Solar-Powered:Frame-integrated and rooftop-mounted photovoltaic systems reduce lifetime operating costs for commercial fleets and residential users with workplace or home solar installations. Provincial building code variations for rooftop charging integration create permitting friction in North Brabant versus South Holland.
- Regenerative Braking:Kinetic energy recovery through mid-drive motor controllers supplements range in stop-start urban environments. Rotterdam and The Hague municipal procurement specifications increasingly mandate this capability for fleet tenders.
- Standard Charging:Grid-connected Level 1 and Level 2 systems remain baseline for residential overnight charging.
- Fast Charging:High-amperage public infrastructure concentrates along Randstad corridor charging networks.
Solar-powered charging leads on scale through subsidy-supported infrastructure expansion; regenerative braking leads on momentum through municipal procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Randstad metropolitan corridors concentrate Dutch solar e-bike demand through employer lease schemes and municipal electrification mandates. Provincial infrastructure standards and subsidy eligibility create distinct adoption velocities across sub-regional markets.
Randstad Conurbation
Amsterdam, Rotterdam, The Hague, and Utrecht generate the highest commuter lease volumes through technology sector employers in Zuidas and Utrecht Science Park. The SDE++ subsidy scheme prioritizes charging infrastructure deployment along A4 and A12 motorway corridors. Municipal low-emission zones in Amsterdam and Rotterdam accelerate cargo fleet conversions for last-mile logistics operators.
North Brabant
Eindhoven's high-tech manufacturing ecosystem sustains workplace charging hub development for Philips and ASML employee mobility programs. Provincial building codes for rooftop solar integration lag South Holland standards, creating permitting friction for residential installations. The Brainport Eindhoven cluster aggregates employer demand through collective procurement negotiations with assemblers.
Utrecht Province
Utrecht Science Park and De Uithof research campus anchor cycle-to-work scheme expansion among academic and medical employers. Rijkswaterstaat corridor planning prioritizes A27 and A28 motorway charging networks connecting Randstad to eastern provinces. Regional transport authority U-OV integrates solar e-bike parking at intermodal transit nodes.
South Holland
Rotterdam port logistics and The Hague government districts drive divergent demand profiles across commercial and commuter segments. Municipal procurement mandates for regenerative braking capability shape fleet tender specifications. Delft University research partnerships accelerate TNO testing protocol development for frame-integrated photovoltaic systems.
Northern Netherlands
Groningen and Leeuwarden university cities sustain smaller-scale adoption through student and faculty mobility programs. Grid interconnection rules for rural rooftop solar charging remain less standardized than Randstad counterparts. Provincial economic development boards leverage SDE++ subsidies to attract assembler distribution facilities.
Netherlands Solar E-Bike Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer distribution and integrated energy service models. The vendor base clusters around three strategic archetypes: domestic heritage manufacturers with European supply integration, Asian-scale fabricators with cost-optimized assembly, and digital-native brands controlling subscription mobility platforms. Competitive differentiation concentrates on photovoltaic-motor convergence and employer-facing sales infrastructure rather than retail channel expansion.
Among Netherlands-based manufacturers, Accell Group, Royal Dutch Gazelle, and VanMoof exemplify distinct positioning archetypes. Accell Group represents diversified European supply chain integration across multiple brand portfolios. Royal Dutch Gazelle occupies the heritage domestic manufacturing position with sustained Dieren production presence. VanMoof anchors direct-to-consumer platform development through urban-centric distribution infrastructure. These three entities collectively illustrate how Dutch assemblers navigate photovoltaic component sourcing diversification and employer lease channel concentration.
| Leading Market Players |
|---|
| Accell Group |
| Pon Holdings |
| Royal Dutch Gazelle |
| VanMoof |
| Koga |
| Batavus |
| CUBE Bikes |
| Giant Manufacturing |
| Trek Bicycle Corporation |
| Others |
Pricing and Supply Chain Analysis
Photovoltaic cell procurement costs cascade through Dutch assembly lines from Asian wafer suppliers to Randstad fleet operators, compressing margins at mid-tier price points while premium configurations capture employer lease premiums.
Pricing Analysis
Input-cost pass-through from lithium-ion cathode materials and frame-integrated solar cells stratifies pricing across premium, standard, and economy tiers. Price differentiation hinges on TNO certification status and employer lease bundling intensity. Pricing pressure stems from freight volatility on Asian battery supply routes. Delivery services exhibit highest price sensitivity due to mandate-driven volume procurement; technology sector commuters show lowest sensitivity through tax-advantaged benefit structures.
Supply Chain Analysis
Dutch domestic-content preferences under SDE++ qualification rules are reshaping sourcing patterns for frame assembly and motor integration. Photovoltaic cells draw from China, South Korea, and Taiwan; lithium-ion cathodes rest on Chinese and Indonesian nickel processing. Single-source vulnerability concentrates in mid-drive motor controllers from German and Japanese suppliers. Distribution runs through direct-to-business channels for fleet operators and employer lease aggregators, bypassing traditional retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Employer-sponsored lease expansion and photovoltaic efficiency gains create margin-expansion headroom as grid-dependency costs recede for commercial adopters.
For Market Incumbents: Extend direct-to-business sales infrastructure into Utrecht and Eindhoven workplace charging hubs before Asian-scale fabricants establish employer lease relationships. Backward integration into European photovoltaic cell qualification compresses supplier cycles from eighteen to twelve months. Channel control through bundled energy monitoring services defends against digital-native subscription entrants. For New Entrants and Emerging Players: The premium-to-economy price gap in recreational rural segments offers white-space entry below Accell Group and Royal Dutch Gazelle positioning. Gelderland and Limburg weekend cyclists represent the most penetrable end-user category with minimal fleet mandate competition. A direct-to-consumer platform with detachable solar panel accessories bypasses incumbent retail entrenchment. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-supplier integration complexity strains quality assurance systems among mid-scale assemblers. Long-term viability centers on employer lease channel concentration and photovoltaic-motor convergence capabilities. The signal to watch is municipal procurement specification shifts toward regenerative braking mandates in Rotterdam and The Hague tender documents.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic-Motor Integration | Direct energy transfer without intermediate battery storage reduces component count for Accell Group and Gazelle assembly lines. |
| Workplace Charging Hub Development | Untapped commercial real estate in Utrecht and Eindhoven aggregates employer demand through centralized solar infrastructure. |
| Perovskite-Silicon Cell Qualification | TNO testing protocol alignment accelerates supplier approval cycles and extends auxiliary range claims for commuter segments. |
| Direct-to-Business Channel Expansion | Human resources department negotiations capture recurring revenue through bundled maintenance and energy monitoring services. |
| Regenerative Braking Mandate Alignment | Rotterdam and The Hague municipal procurement specifications favor assemblers with integrated kinetic recovery systems. |
Research Methodology
Direct dialogue with Dutch e-bike procurement managers, Rijkswaterstaat infrastructure planners, TNO testing protocol engineers, and employer benefit scheme administrators grounded qualitative findings in operational constraints. Secondary validation drew from SDE++ subsidy disbursement records, municipal low-emission zone enforcement data, Rijkswaterstaat corridor planning documents, and Netherlands Enterprise Agency renewable mobility filings. Bottom-up assembly volume estimates triangulated against top-down Randstad commuter flow projections.
Segment-level outputs across the projection horizon reflect product type, battery chemistry, charging technology, and end-user category dimensions. CAGRs derived from logistic diffusion curves fitted to employer lease penetration rates and fleet conversion timelines under municipal mandate schedules. Photovoltaic conversion efficiency assumptions and lithium-ion cell cost trajectories anchored the analytical framework.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization or perovskite cell degradation rates would alter the outlook. Forecasts reflect documented assumptions on subsidy continuity and provincial building code harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market