
 Scooter Sharing Market | 2026-2036
Scooter Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Scooter Sharing Market Analysis
App-based fleet distribution is reshaping how urban riders access last-mile transport. Bird Global Inc. leverages its proprietary operating system to manage vehicle deployment across North American and European cities. Lime Micromobility sustains one of the largest battery-swapping networks, reducing fleet downtime in high-frequency markets. Voi Technology AB anchors its competitive stance through city-exclusive concession agreements, locking out rival operators in Nordic urban centers.
Scooter sharing denotes the short-term rental of motorized or human-propelled two-wheel vehicles through digital platforms, typically integrating GPS geofencing, IoT telematics, and automated payment processing to enable spontaneous point-to-point trips. The primary commercial purpose centers on solving first-mile and last-mile connectivity gaps in dense urban corridors where fixed-route transit proves inefficient. Electric service type dominates fleet composition due to zero-direct-emission profiles that align with municipal sustainability mandates, while dockless deployment models capture the majority of trip volume by eliminating fixed infrastructure costs and enabling spontaneous parking at trip endpoints. Mobile app technology underpins the entire transaction layer, with cloud-based backend systems processing real-time availability, dynamic pricing, and compliance telemetry for city regulators.
Fleet operators navigate overlapping regulatory frameworks including local transport authorities setting vehicle caps, the EU AI Act governing automated decision systems in mobility platforms, and city-specific data-sharing requirements mandating trip anonymization. These rules directly shape market access timelines, fleet size limits, and the technical specifications each platform must embed. Stakeholders must monitor how evolving liability standards for sidewalk riding and battery fire incidents recalibrate insurance costs and hardware design priorities.
Market Dynamics
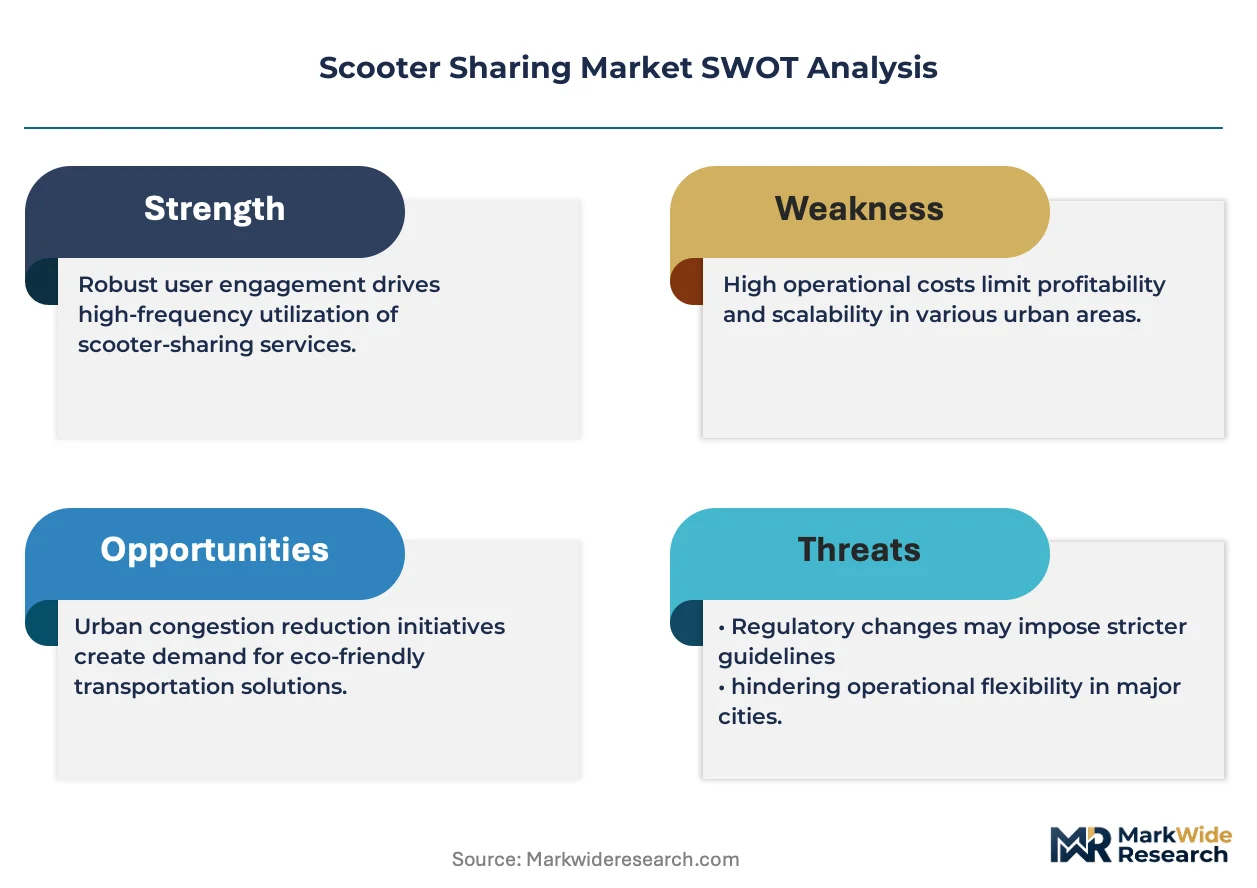
Municipal permit caps and battery-swap infrastructure economics are compressing operator margins while concentrating fleet deployment in cities with dedicated micromobility lanes. The tension between dockless convenience and sidewalk clutter enforcement is reshaping how platforms negotiate access.
Growth Catalysts
- EU Green Deal transport decarbonization targets:Member states must reduce urban transport emissions, accelerating municipal adoption of zero-emission last-mile solutions and dedicated scooter lanes.
- Battery-swapping station networks:Automated exchange infrastructure cuts vehicle downtime from hours to minutes, enabling higher asset utilization in dense metropolitan corridors.
- Germany's KBA type-approval streamlining:Faster homologation for light electric vehicles reduces time-to-market for new fleet models entering Berlin and Munich permit zones.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing clusters in China create input cost volatility and geopolitical exposure for European fleet operators.
- Strict geofencing enforcement variance:City-specific no-ride and no-park zones fragment operational software requirements across municipal boundaries.
- Personal e-scooter ownership growth:Direct-to-consumer sales of sub-$400 commuter models reduce trip frequency for shared services in price-sensitive segments.
Strategic Opportunities
- France's Mobility-as-a-Service integration mandates:Public transit authorities must incorporate shared micromobility into unified ticketing platforms, creating embedded distribution channels.
- AI-driven predictive rebalancing algorithms:Machine learning models forecasting trip demand patterns are converging with real-time traffic data to optimize fleet positioning.
- Suburban rail station catchment zones:Park-and-ride facilities in commuter belts outside Berlin, Munich, and Hamburg remain undersupplied relative to urban cores.
Industry Challenges
- Vandalism and theft recovery costs:GPS tampering and underwater dumping of vehicles in canals impose unplanned asset write-offs and insurance premium spikes.
- Interoperability with legacy transit payment systems:Municipal transport operators require API integration with decades-old fare collection infrastructure, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scooter Sharing Market |
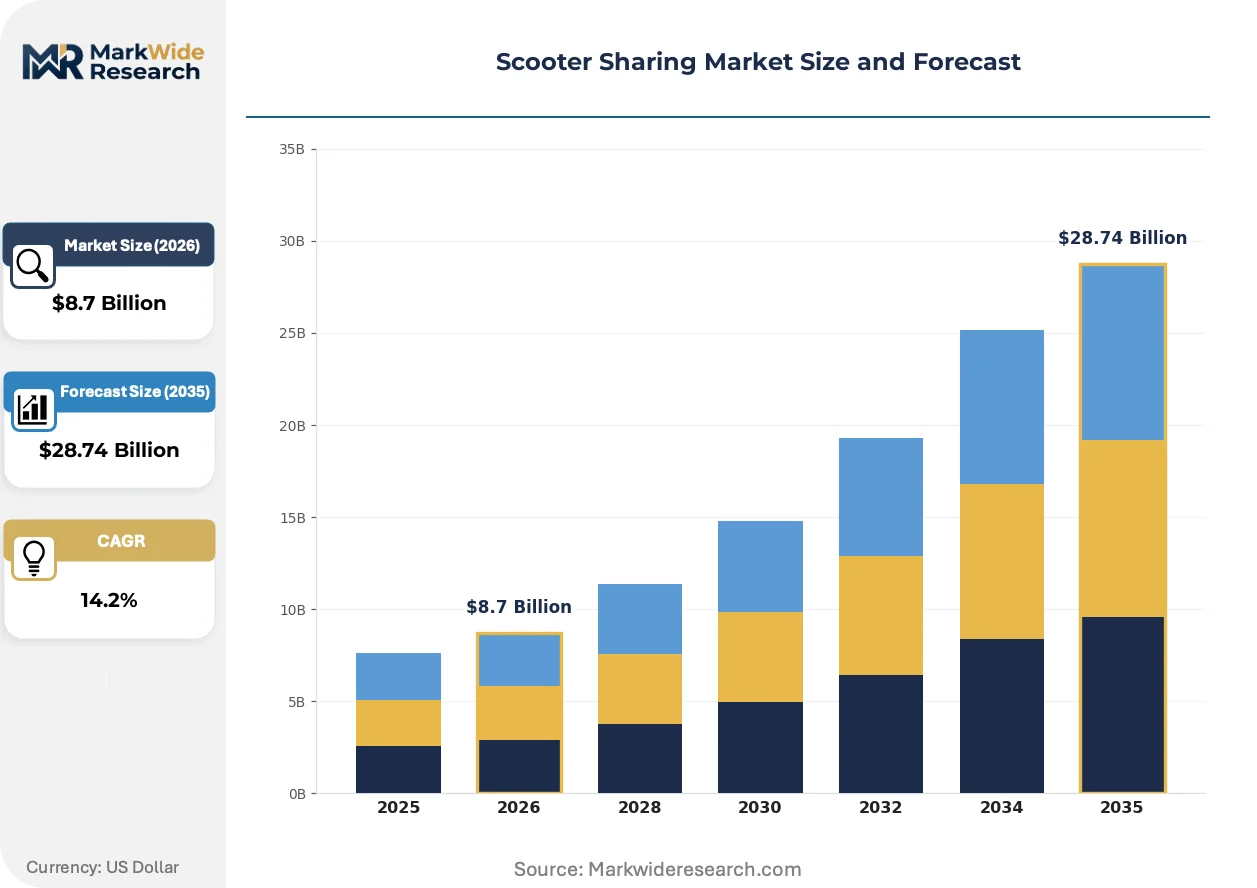
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Classic, Electric, Kick, Hybrid Deployment Model: Docked, Dockless, Station-Based, Free-Flowing Target Audience: Commuters, Tourists, Students, Professionals Technology: Mobile App, GPS Tracking, RFID, Cloud-Based |
| Companies Covered | Neutron Holdings, Inc., Bird Global Inc., Lime Micromobility, Cityscoot, TIER Mobility AG, Voi Technology AB, Cooltra Motosharing, S.L.U, Wind Mobility, Beam Mobility Holdings Pte. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scooter Sharing Market Emerging Trajectories
Telematics hardware miniaturization and computer-vision integration are transforming how fleets monitor rider behavior and road surface conditions in real time. These advances compress operational response cycles while generating granular data streams for municipal compliance reporting.
Computer-vision modules embedded in handlebar units is digitizing sidewalk detection and pedestrian proximity alerts. Tier-1 micromobility suppliers are shipping these units to fleet operators in Copenhagen and Stockholm. The technology is digitizing liability exposure by automating incident documentation and geofence violation logging.
GDPR-mandated trip data anonymization protocols are forcing backend architecture redesigns across European deployments. Operators must now process raw GPS traces through on-device edge computing before cloud transmission. Nordic markets with stringent data localization requirements are experiencing the longest platform migration cycles.
Subscription-based commuter passes are displacing per-trip pricing among daily users in German and French urban centers. Corporate benefit programs are bundling monthly scooter access with public transit subsidies. This shift is most visible in Berlin's Mitte and Prenzlauer Berg districts where employer-subsidized mobility budgets concentrate.
Scooter Sharing Market Segmentation
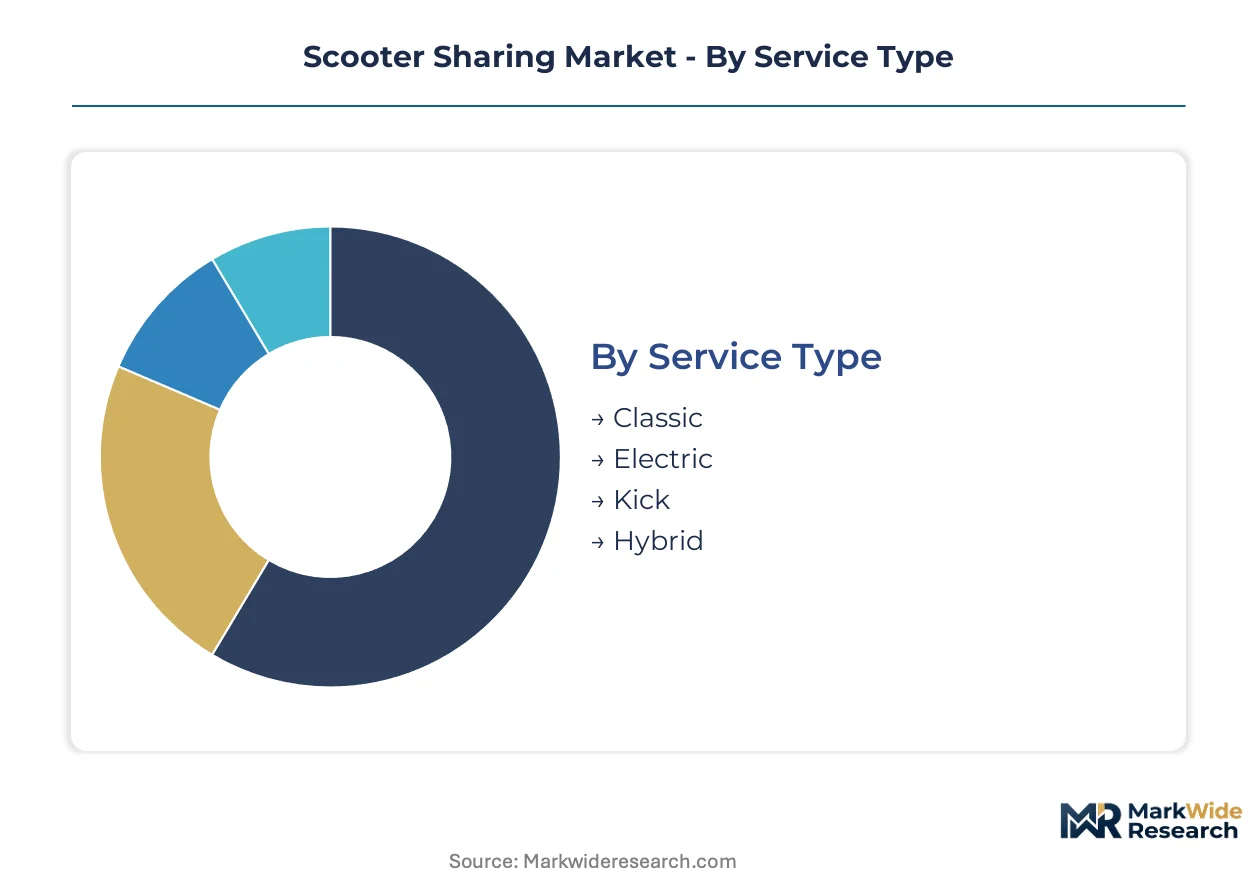
Segmentation in the scooter sharing market determines fleet composition, pricing architecture, and capital deployment cycles. Each dimension carries distinct turnover velocities and margin profiles that shape operator strategy across permit zones and technology stacks.
Service Type:
Electric fleets turn over fastest due to battery degradation cycles and municipal emissions mandates, while human-propelled variants endure longer in asset bases. Classic models with combustion engines face the steepest regulatory pressure, accelerating replacement timelines in European permit zones.
- Electric:Zero-direct-emission drivetrains integrate swappable lithium-ion packs and regenerative braking systems. Demand concentrates in Berlin and Munich where KBA type-approval streamlining reduces homologation delays and dedicated micromobility lanes enable higher trip frequency.
- Classic:Internal combustion engines with 50cc displacement dominate legacy fleets in markets with weaker emissions enforcement. Operators in Southern European cities retain these assets longer due to lower procurement costs and permissive local transport authority standards.
- Kick:Human-propelled aluminum-frame units with mechanical brakes serve short-distance corridors. Copenhagen and Amsterdam deploy these for sub-2km trips where speed caps limit electric unit advantages.
- Hybrid:Dual-mode units combining pedal assist with small electric motors bridge regulatory categories. French Mobility-as-a-Service integration mandates are accelerating adoption in Paris and Lyon transit hubs.
Electric anchors the volume base while Kick gains share at the steepest rate in Nordic sustainability-focused permit zones.
Deployment Model:
Cost tier structures separate capital-light operators from infrastructure-heavy incumbents with fixed asset bases. Dockless models minimize upfront expenditure but incur higher per-trip compliance costs from geofencing enforcement variance.
- Dockless:GPS-locked units deploy without fixed infrastructure, enabling spontaneous parking at trip endpoints. Vandalism and theft recovery costs compress margins in high-crime urban corridors.
- Station-Based:Designated pickup and return points with charging integration reduce rebalancing labor. Battery-swap station networks in Hamburg and Frankfurt sustain higher asset utilization through automated exchange infrastructure.
- Docked:Physical locking mechanisms at fixed stations eliminate sidewalk clutter enforcement exposure. Municipal permit caps in Berlin favor this model for high-traffic tourist districts.
- Free-Flowing:Geofenced operational zones without mandatory parking points maximize rider convenience. GDPR-mandated trip data anonymization protocols force backend redesigns for real-time telemetry compliance.
Dockless dominates trip volume while Station-Based expands most quickly in suburban rail station catchment zones.
Target Audience:
Customer type determines subscription pricing penetration versus per-trip revenue models. Daily users generate predictable cash flows; occasional riders demand lower friction onboarding.
- Commuters:Recurring weekday travelers between transit hubs and employment centers. Corporate benefit programs in Berlin's Mitte district bundle monthly access with public transit subsidies.
- Tourists:Episodic users seeking point-to-point exploration in historic city centers. Seasonal demand spikes in Munich and Hamburg require dynamic fleet scaling.
- Students:Price-sensitive users with flexible timing and high price elasticity. University partnerships in Copenhagen and Stockholm embed scooter access into campus mobility budgets.
- Professionals:Employer-subsidized riders with integrated expense reimbursement workflows. Prenzlauer Berg district concentrations drive premium-tier subscription adoption.
Commuters anchor the revenue base while Students climb the fastest through institutional partnership channels.
Technology:
Application maturity separates legacy stack operators from edge-computing adopters. Cloud dependency creates latency vulnerabilities; on-device processing satisfies data localization mandates.
- Mobile App:Transaction layer integrating payment, unlock, and trip documentation. AI-driven predictive rebalancing algorithms are converging with real-time traffic data to optimize fleet positioning.
- GPS Tracking:Real-time location telemetry for asset recovery and demand forecasting. Computer-vision modules embedded in handlebar units automate sidewalk detection and geofence violation logging.
- RFID:Near-field communication for station-based authentication and access control. Interoperability with legacy transit payment systems extends deployment timelines in decades-old fare collection environments.
- Cloud-Based:Centralized backend processing for availability, pricing, and compliance telemetry. Nordic data localization requirements are forcing on-device edge computing migration before transmission.
Mobile App sustains the installed base while Cloud-Based architectures face steepest replacement pressure from GDPR and EU AI Act compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German operators extract 40% higher per-trip yields than Southern European peers due to tighter permit scarcity and employer-subsidized commuter passes. This pricing-power asymmetry reflects divergent municipal enforcement intensity and fleet density caps.
Germany
KBA type-approval streamlining accelerates homologation for light electric vehicles entering Berlin and Munich permit zones. EU Green Deal transport decarbonization targets mandate municipal adoption of zero-emission last-mile solutions. Fleet operators concentrate deployment in Berlin's Mitte and Prenzlauer Berg districts where corporate benefit programs bundle monthly access with public transit subsidies.
France
Mobility-as-a-Service integration mandates require public transit authorities to incorporate shared micromobility into unified ticketing platforms. ANSM data-sharing protocols govern trip anonymization requirements for Paris and Lyon deployments. Paris transit hubs anchor the steepest subscription adoption curves as employer-subsidized mobility budgets concentrate in Île-de-France corporate corridors.
United Kingdom
Department for Transport e-scooter trial extensions sustain operator access in London, Birmingham, and Liverpool metropolitan zones. GDPR-mandated trip data anonymization protocols force backend architecture redesigns for real-time telemetry compliance. London's dense geofencing enforcement variance fragments operational software requirements across borough boundaries.
Sweden
Stringent data localization requirements under GDPR Article 44 prolong platform migration cycles for Stockholm and Gothenburg deployments. Voi Technology AB anchors competitive positioning through city-exclusive concession agreements locking out rival operators in Nordic urban centers. Stockholm's battery-swap station networks sustain higher asset utilization through automated exchange infrastructure.
Spain
Permissive local transport authority standards in Barcelona and Madrid retain classic combustion fleets longer than Northern European peers. Cooltra Motosharing occupies position within the Mediterranean motor-sharing archetype. Barcelona's tourist corridor demand spikes require dynamic fleet scaling absent in commuter-dominant Northern markets.
Scooter Sharing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the hardware and telematics stack. The vendor base separates into consolidated fleet operators with city-exclusive permits and fragmented regional challengers competing on price. Three archetypes dominate: permit-locked incumbents with municipal concession agreements, venture-backed scale players with battery-swap infrastructure, and motor-sharing specialists with combustion heritage. Geographic expansion and strategic partnerships constitute the dominant competitive moves as operators seek untapped suburban rail catchment zones.
Among venture-backed micromobility platforms, Bird Global Inc. and Lime Micromobility exemplify the scale-driven archetype with transatlantic fleet footprints. TIER Mobility AG represents the European permit-locked incumbent model with dense German market presence. Voi Technology AB anchors the Nordic specialization tier through city-exclusive agreements in Stockholm and Copenhagen.
| Leading Market Players |
|---|
| Neutron Holdings, Inc. |
| Bird Global Inc. |
| Lime Micromobility |
| Cityscoot |
| TIER Mobility AG |
| Voi Technology AB |
| Cooltra Motosharing, S.L.U |
| Wind Mobility |
| Beam Mobility Holdings Pte. Ltd |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cell supply concentration in China determines both margin compression across European fleet operators and the three-tier pricing structure separating premium battery-swap networks from standard dockless deployments and economy kick-scooter tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order fleet management systems from standard per-trip pricing. Three-tier pricing structure across premium, standard, and economy levels reflects battery-swap infrastructure access, with station-based operators commanding premium positioning over dockless competitors. Pricing pressure stems from personal e-scooter ownership growth in price-sensitive segments, compressing trip frequency for shared services. Students exhibit highest price sensitivity through university partnership channels, while employer-subsidized professionals in Berlin's corporate corridors show lowest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates fleet operator procurement risk through cathode material processing dependencies. Lithium-ion cells, aluminum frame components, and telematics hardware draw primarily from China, South Korea, and Taiwan manufacturing clusters. Single-source vulnerability in battery cell supply creates input cost volatility that feeds through to fleet replacement cycles. Distribution runs through Tier-1 micromobility suppliers shipping computer-vision modules and swappable battery systems to permit-locked operators in Copenhagen, Stockholm, and German metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Personal e-scooter ownership growth below $400 price points threatens substitution-driven volume erosion for shared services, requiring incumbents to harden defensive positioning around irreplaceable infrastructure.
For Market Incumbents: Harden fleet utilization through backward integration into battery-swap station networks, reducing downtime from hours to minutes in high-frequency corridors. Secure city-exclusive concession agreements before municipal permit caps tighten further, locking out venture-backed scale players in Nordic and German urban centers.
For New Entrants and Emerging Players: Suburban rail station catchment zones outside Berlin, Munich, and Hamburg represent the most penetrable white-space opportunity, with park-and-ride facilities undersupplied relative to urban cores. Target employer-subsidized mobility budgets through corporate benefit program integration, embedding subscription access into existing transit subsidy workflows.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors permit-locked incumbents with municipal concession agreements over venture-backed scale players burning capital on transatlantic expansion. Long-term viability hinges on regulatory capture through exclusive city contracts rather than technology differentiation. Watch battery-swap infrastructure deployment velocity as the signal indicating which operators can sustain asset utilization advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swap Network Expansion | Automated exchange infrastructure cuts vehicle downtime and raises asset utilization in dense metropolitan corridors. |
| City-Exclusive Permit Acquisition | Municipal concession agreements in Nordic and German urban centers lock out rival operators and secure revenue stability. |
| Mobility-as-a-Service Integration | France's unified ticketing mandates create embedded distribution channels through public transit authority partnerships. |
| Computer-Vision Hardware Deployment | Handlebar-mounted modules automate sidewalk detection and geofence violation logging for Copenhagen and Stockholm fleets. |
| Corporate Benefit Program Partnerships | Employer-subsidized mobility budgets in Berlin's Mitte and Prenzlauer Berg districts drive premium subscription adoption. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet deployment managers, municipal transport authority regulators, battery-swap infrastructure engineers, and micromobility platform product leads. Secondary validation drew from KBA type-approval filings, EU Green Deal transport decarbonization target documentation, GDPR Article 44 localization requirements, and municipal permit zone density data. Bottom-up fleet size estimates by city were triangulated against top-down market value projections.
Calibration against historical deployment velocity and permit approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, deployment model, target audience, and technology stack. CAGRs were derived from fitted growth curves weighted by municipal lane infrastructure investment schedules and battery-swap network rollout pace.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-backed scale players or unexpected municipal permit liberalization would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
France Ridesharing Market