
 Global Automated Fare Collection Market | 2026-2036
Global Automated Fare Collection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Fare Collection Market Foresight
ISO 24014 certification for interoperable public transport ticketing is bifurcating the competitive landscape between certified integrators and regional vendors. Cubic Corporation leverages its North American transit agency relationships to sustain long-term service contracts. Thales Group anchors European rail modernization programs through embedded cybersecurity modules. Masabi Ltd specializes in cloud-native mobile ticketing, competing against hardware-heavy incumbents with lower capital deployment models.
Automated fare collection encompasses the integrated hardware and software systems that validate, process, and record passenger payments across transit networks, typically incorporating validators with sub-300 millisecond transaction latency and centralized clearinghouse architectures. The primary commercial purpose is to reduce fare evasion while enabling dynamic pricing and real-time ridership analytics. Contactless smart cards still occupy the largest installed base, though mobile ticketing is displacing legacy magnetic stripe systems fastest in emerging deployments. Cloud-based platforms concentrate margin pools through recurring software-as-a-service revenues rather than one-time equipment sales.
The European Union's F-Gas Regulation and CE marking requirements shape hardware import standards, while the U.S. Federal Transit Administration's Buy America provisions govern domestic content ratios for federally funded installations. India's BIS certification and China's GB standards create additional compliance layers for multinational suppliers seeking local procurement channels. Stakeholders must monitor which regulatory jurisdictions will mandate open-payment interoperability first, as this determination will reshape vendor qualification criteria and contract award mechanisms across subsequent procurement cycles.
Market Dynamics
The migration from proprietary closed-loop systems to open-payment architectures is fragmenting vendor lock-in advantages and forcing incumbents to restructure revenue models around software subscriptions rather than hardware margins.
Growth Catalysts
- ISO 24014 Certification Mandates:Transit authorities in France, Germany, and the Netherlands now require interoperable ticketing standards, compelling system upgrades across legacy networks.
- Contactless EMV Migration:Bank card networks are pushing tap-to-pay directly at transit gates, eliminating the need for agency-issued media and reducing card distribution costs.
- China's Tier-One Consolidation:Municipal governments in Beijing, Shanghai, and Guangzhou are merging disparate rail operators under unified clearinghouse platforms.
Market Restraints
- Semiconductor Supply Concentration:Validator manufacturing depends on specialized secure-element chips from a concentrated East Asian supplier base, creating procurement bottlenecks.
- F-Gas Hardware Compliance:The European Union's fluorinated gas regulations impose retrofit costs on legacy gate equipment containing restricted cooling agents.
- Magnetic Stripe Stranded Assets:Agencies with recent investments in card-based systems face accelerated obsolescence as mobile-first architectures become default specifications.
Strategic Opportunities
- India's BIS Certification Channel:Domestic manufacturing incentives under the PLI scheme are opening procurement pathways for locally assembled validators.
- Account-Based Ticketing Convergence:Integration of transit wallets with retail payment apps creates cross-subsidy models and data monetization potential.
- Saudi Arabia Giga-Project Transit:NEOM and Red Sea Project developments are specifying greenfield AFC systems without legacy integration burdens.
Industry Challenges
- Cybersecurity Certification Timelines:Common Criteria EAL4+ evaluations for payment security modules extend product launch schedules by 12-18 months.
- Legacy Mainframe Integration:Back-office reconciliation with 1980s-era transit agency IT systems requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Fare Collection Market |
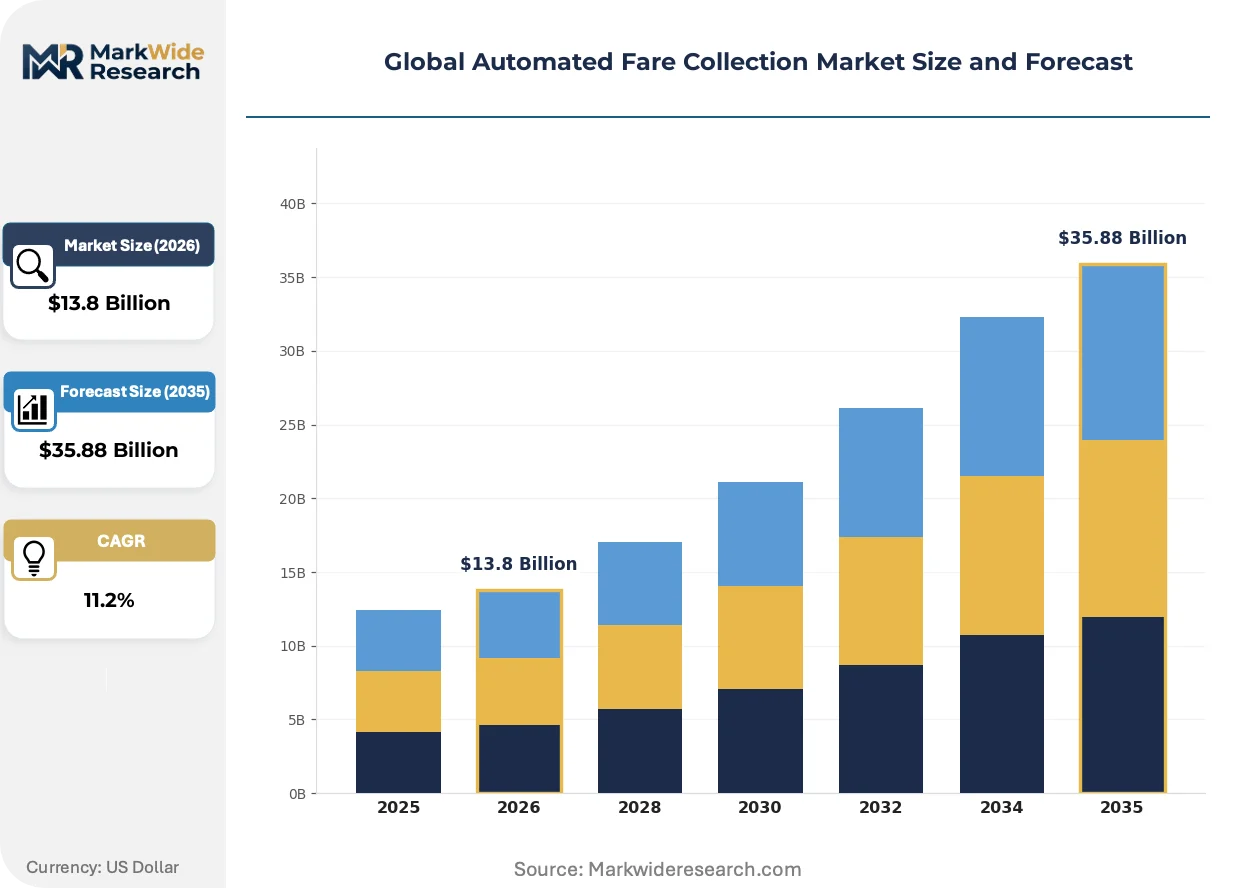
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $35.88 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Contactless Smart Cards, Mobile Ticketing, Barcode Scanners, Magnetic Stripe Cards, Biometric Authentication Technology: Radio Frequency Identification, Near Field Communication, Bluetooth Low Energy, QR Code, Cloud-Based Platforms Application: Public Transit, Toll Collection, Parking Management, Event Ticketing, Campus Transportation End User: Transit Agencies, Toll Operators, Parking Authorities, Event Organizers, Educational Institutions |
| Companies Covered | Indra Sistemas, Scheidt & Bachmann GmbH, Cubic Corporation, Vix Technology, GMV Innovating Solutions, Thales Group, OMRON Corporation, Masabi Ltd, Atos SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Fare Collection Market Shifts & Advancements
Cloud-native architectures are collapsing the traditional distinction between hardware vendors and software providers, enabling new entrants to compete without manufacturing capacity.
Biometric facial recognition payment systems are bifurcating the authentication layer from physical media entirely. Metro operators in South Korea and China are piloting gateless corridor flow systems that deduct fares via facial matching without tapping or scanning. This compression of transaction friction is bifurcating competitive advantage toward computer vision specialists and away from card-reader manufacturers.
The European Union's F-Gas Regulation is accelerating hardware replacement cycles across rolling stock and station infrastructure. Transit agencies must retire or retrofit validators containing prohibited refrigerants before mandated phase-out deadlines. German and French rail operators are responding by bundling climate-compliant equipment upgrades into broader digitalization tenders.
Agency procurement departments are unbundling long-term service contracts from initial system deployment. North American transit authorities now separate hardware purchase from software maintenance and clearinghouse operations, enabling multi-vendor environments. This fragmentation is most advanced in California, where regional rail consortia negotiate software subscriptions independently from gate hardware specifications.
Global Automated Fare Collection Market Segmentation
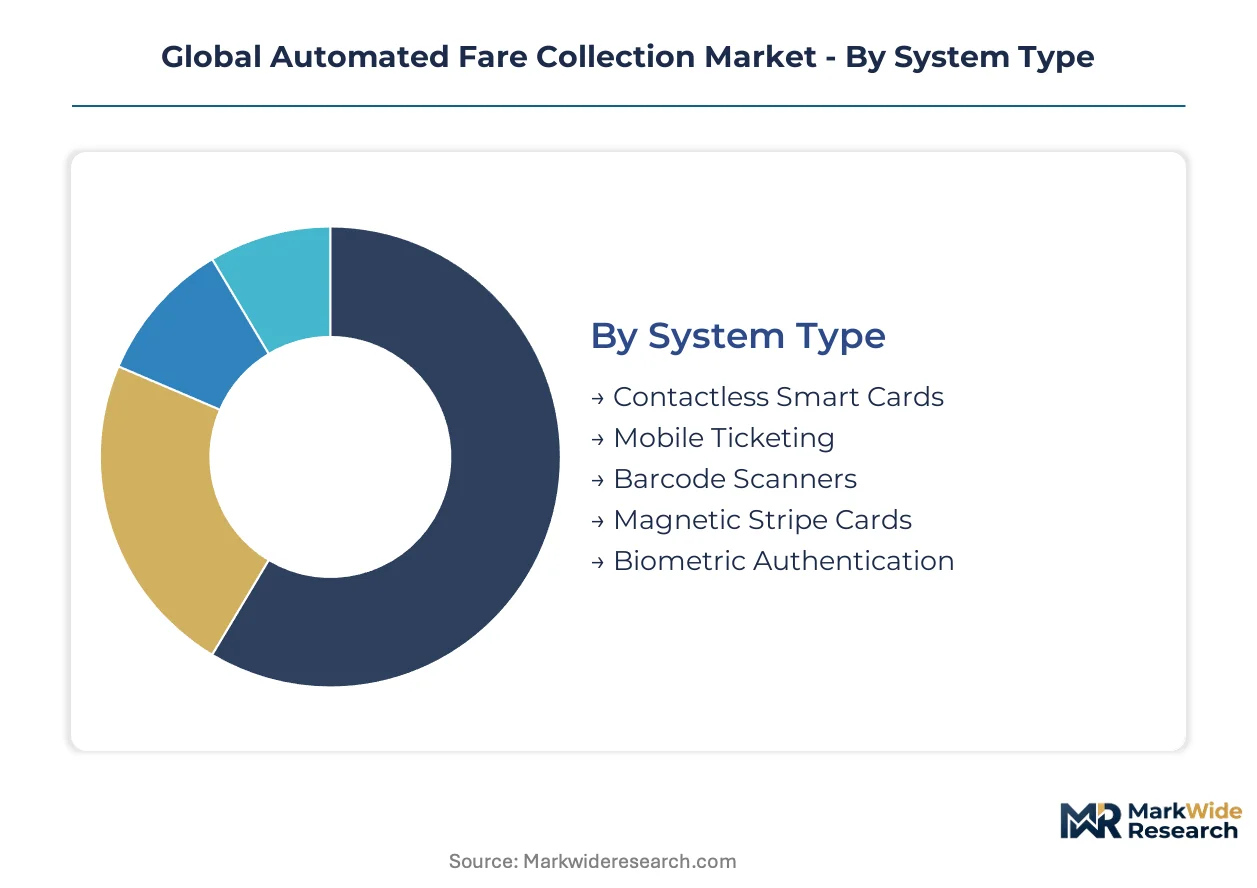
Automated fare collection markets fragment across payment modalities, authentication layers, and infrastructure deployment models. Margin pools concentrate where recurring software revenues displace one-time hardware sales, and where open-payment architectures reduce vendor lock-in.
System Type:
Recurring revenue intensity varies sharply across authentication media, with cloud-connected platforms capturing disproportionate lifetime value versus card-issued systems.
- Contactless Smart Cards:Polymer-based stored-value cards with embedded secure elements dominate legacy installed bases across European and Asian metro networks. Paris RATP and London TfL maintain multi-million card circulations despite mobile displacement pressures, as unbanked populations and tourist segments sustain physical media demand.
- Mobile Ticketing:Smartphone-based digital wallets with tokenized payment credentials are climbing the fastest in greenfield deployments. São Paulo Metro and Jakarta MRT specified app-first architectures that eliminate card distribution infrastructure entirely, reducing capital deployment timelines.
- Barcode Scanners:Optical validation of printed or displayed QR codes serves low-frequency transit modes and paratransit services.
- Magnetic Stripe Cards:Legacy paper ticket encoding persists in maintenance-deferred systems across older North American commuter rail networks.
- Biometric Authentication:Facial recognition and palm-vein matching systems are piloting gateless corridor flow in Seoul Metro and Shenzhen Rail Transit.
Contactless smart cards hold installed capacity. Mobile ticketing is rotating up the share rankings.
Technology:
Authentication protocol selection determines hardware supplier qualification requirements and cybersecurity certification burdens.
- Radio Frequency Identification:Passive 13.56 MHz transponders embedded in cards and wearables enable sub-300 millisecond gate transaction speeds. The technology anchors ISO 14443-compliant systems across German Bahn regional networks and Spanish Cercanías commuter services.
- Near Field Communication:Bidirectional short-range communication enables device-to-reader authentication without dedicated transit media. Tokyo Metro and Singapore LTA have enabled NFC bank card tapping directly at fare gates, collapsing clearinghouse complexity.
- Bluetooth Low Energy:Longer-range proximity detection supports beacon-based station entry without physical gate interaction.
- QR Code:Two-dimensional barcode encoding allows camera-based validation on low-cost hardware.
- Cloud-Based Platforms:Centralized account-based ticketing architectures decouple fare calculation from physical media, enabling real-time price elasticity experiments.
Radio frequency identification dominates hardware shipment volumes. Near field communication is gaining share fastest as open-payment mandates proliferate.
Application:
Deployment complexity scales with passenger volume volatility and fare structure intricacy.
- Public Transit:Multi-modal urban rail and bus networks with peak-load pricing and transfer discounts constitute the core revenue base. New York MTA and Chicago CTA are consolidating disparate bus and rail payment systems under unified account-based architectures.
- Toll Collection:Highway and bridge revenue recovery with variable congestion pricing demands vehicle-mounted transponders and license-plate recognition backup. India's FASTag program and Brazil's Sem Parar network demonstrate national-scale RFID deployment at speed.
- Parking Management:Off-street garage and on-street meter payment integration with municipal enforcement systems.
- Event Ticketing:Temporary high-volume access control for stadiums and exhibition centers.
- Campus Transportation:University shuttle and bike-share systems with semester-pass bundling.
Public transit commands the deepest installed base. Toll collection is expanding most quickly as highway privatization accelerates.
End User:
Procurement sophistication and contract duration vary with institutional scale and public accountability requirements.
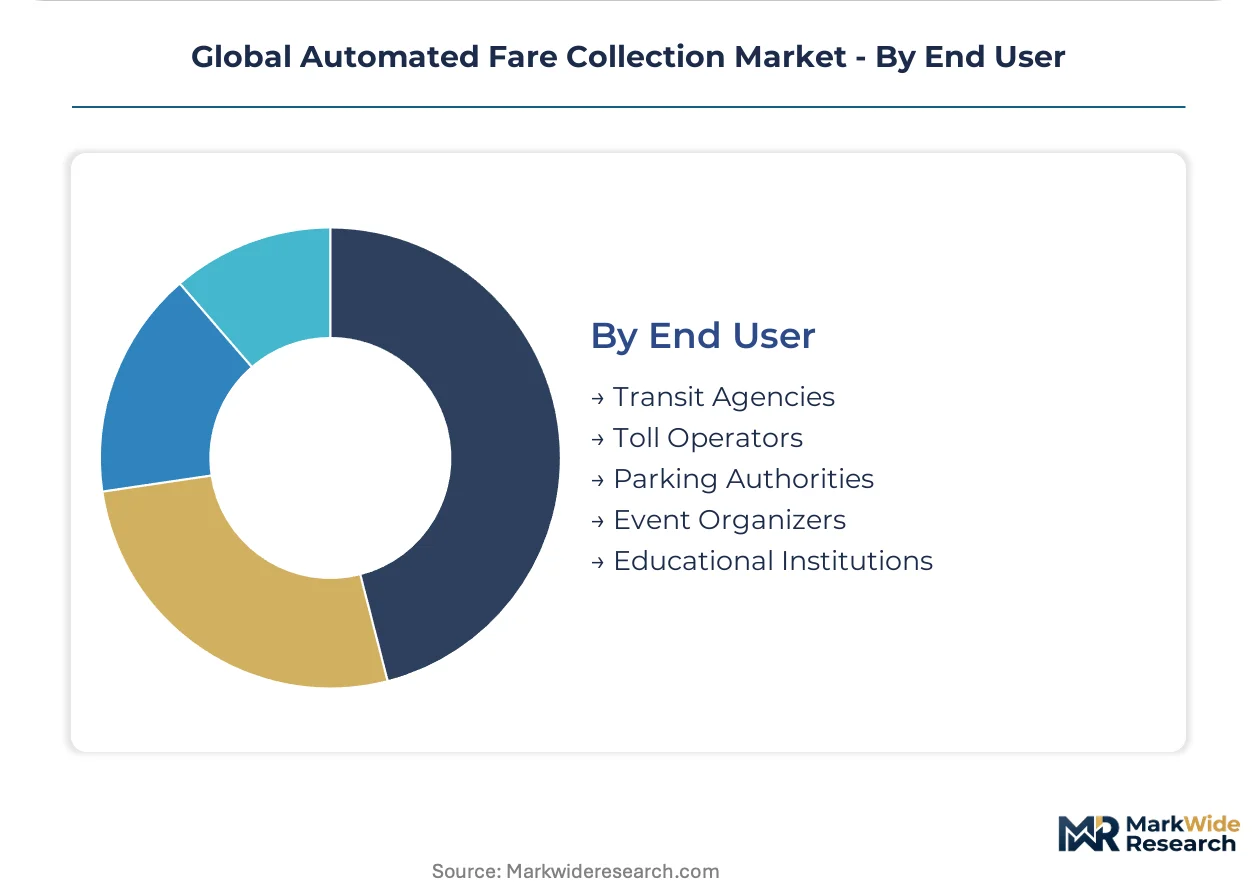
- Transit Agencies:Municipal and regional public transport authorities with 10-15 year system lifecycles and federal funding compliance obligations. Los Angeles Metro and Washington WMATA structure multi-vendor environments separating hardware from software procurement.
- Toll Operators:Public-private partnership concessions and state highway authorities with revenue-risk contracts. France's Vinci Autoroutes and Spain's Abertis operate trans-European tolling interoperability through EETS framework compliance.
- Parking Authorities:Municipal departments and private operators managing curb space allocation.
- Event Organizers:Temporary deployment customers with seasonal demand spikes and rental-based equipment models.
- Educational Institutions:University systems with integrated ID card and transportation payment bundling.
Transit agencies anchor long-term service contract values. Toll operators are climbing the fastest as concession renewals specify next-generation architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's F-Gas Regulation and ISO 24014 certification mandates are accelerating system replacements across legacy networks. China's municipal consolidation programs and India's PLI scheme for domestic manufacturing are redirecting procurement flows toward local assembly requirements.
United States
The Federal Transit Administration's Buy America provisions govern domestic content ratios for federally funded installations. Los Angeles Metro and Chicago CTA are consolidating disparate bus and rail payment systems under unified account-based architectures. California's regional rail consortia negotiate software subscriptions independently from gate hardware specifications.
Germany
Deutsche Bahn regional networks anchor ISO 14443-compliant RFID system deployments across commuter services. The F-Gas Regulation imposes retrofit costs on legacy gate equipment containing restricted cooling agents. Berlin and Munich transit authorities are bundling climate-compliant equipment upgrades into broader digitalization tenders.
China
Municipal governments in Beijing, Shanghai, and Guangzhou are merging disparate rail operators under unified clearinghouse platforms. GB standards and MIIT directives shape hardware import compliance for multinational suppliers. Shenzhen Rail Transit pilots gateless corridor flow systems using biometric facial recognition payment authentication.
India
The PLI scheme and BIS certification requirements are opening procurement pathways for locally assembled validators. Mumbai Metro and Delhi Metro Rail Corporation are expanding contactless payment infrastructure across urban networks. Domestic manufacturing incentives redirect contract awards toward Indian-assembled equipment meeting central government content mandates.
Saudi Arabia
NEOM and Red Sea Project developments specify greenfield AFC systems without legacy integration burdens. The Public Investment Fund's giga-project portfolio demands next-generation architectures from initial deployment. Riyadh Metro's six-line network incorporates account-based ticketing with retail payment app convergence.
Global Automated Fare Collection Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with embedded transit divisions. The vendor base concentrates around three strategic archetypes: hardware-integrated system integrators, cloud-native software specialists, and industrial automation conglomerates. Competitive positioning hardens through long-term service contract capture and cybersecurity certification accumulation rather than equipment pricing alone.
Within the hardware-integrated tier, Cubic Corporation and Thales Group exemplify the dual-capability model combining gate manufacturing with clearinghouse operations. Scheidt & Bachmann GmbH occupies a position among European rail specialists leveraging embedded cybersecurity modules for ISO 24014-compliant tenders. Masabi Ltd represents the cloud-native archetype competing through software-as-a-service models against capital-intensive incumbents. These three anchors illustrate the market's bifurcation between equipment-heavy and subscription-based revenue structures.
| Leading Market Players |
|---|
| Indra Sistemas |
| Scheidt & Bachmann GmbH |
| Cubic Corporation |
| Vix Technology |
| GMV Innovating Solutions |
| Thales Group |
| OMRON Corporation |
| Masabi Ltd |
| Atos SE |
| Others |
Supply & Pricing Matrix
Ninety-day secure-element chip lead times from East Asian foundries concentrate procurement leverage among hardware-integrated incumbents while compressing margins for system integrators lacking captive semiconductor supply. This inventory pressure cascades into pricing power asymmetries across validator manufacturing tiers.
Pricing Analysis
Certification level creates the primary spread between ISO 24014-compliant integrators and regional vendors lacking Common Criteria EAL4+ accreditation. Three-tier pricing structure across certified-premium, standard-compliant, and non-certified economy levels reflects cybersecurity module costs and evaluation timelines. Pricing pressure stems from cloud-native software specialists undercutting hardware-heavy incumbents with subscription-based deployment models. Municipal transit agencies with federal funding obligations demonstrate highest price sensitivity, while Saudi giga-project developers prioritize performance over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate validator assembly, though European rail operators are stockpiling F-Gas-compliant cooling modules ahead of regulatory deadlines. Secure-element chip fabrication concentrates in Taiwan, South Korea, and Japan, while gate mechanical assembly localizes in Germany, China, and India under BIS and GB standards. Supply chain risk centers on single-source vulnerability for payment security modules subject to Common Criteria certification bottlenecks. Distribution runs through transit agency procurement consortia in North America and direct national tender processes in Europe and Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery driven by post-pandemic ridership normalization and deferred infrastructure replacement backlogs across legacy metro networks.
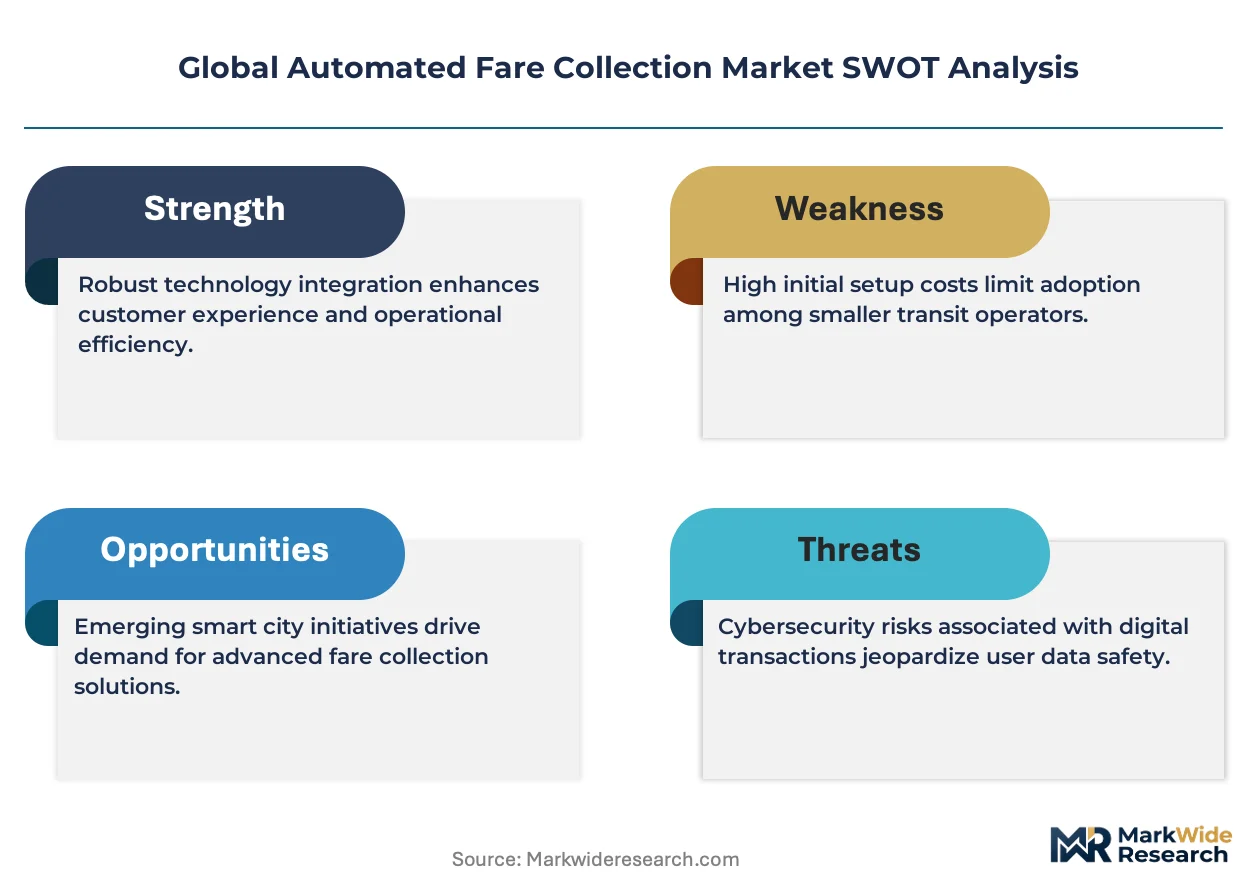
For Market Incumbents: Secure long-term service contract renewals before open-payment interoperability mandates fragment vendor relationships. Defend against cloud-native entrants by embedding subscription software layers into existing hardware deployments. Prioritize backward integration into secure-element chip sourcing to mitigate procurement bottlenecks from East Asian suppliers. For New Entrants and Emerging Players: Anchor in India's PLI scheme domestic manufacturing incentives to bypass BIS certification barriers for multinational competitors. Target Saudi Arabia's greenfield giga-projects where legacy integration burdens are absent. Lead with account-based ticketing platforms that collapse hardware deployment timelines versus card-issued system incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because transit agencies are unbundling hardware purchase from software maintenance and clearinghouse operations. Acquisition targets should demonstrate ISO 24014 certification accumulation and multi-vendor environment integration capabilities. Watch for open-payment interoperability mandate announcements as the inflection signal that rewrites vendor qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables SaaS revenue capture against hardware-dependent incumbents in transit agency procurement. |
| ISO 24014 Certification Investment | Qualifies vendors for French, German, and Dutch interoperable ticketing tenders under regulatory mandate. |
| Secure-Element Chip Backward Integration | Reduces procurement vulnerability to Taiwan and South Korea foundry concentration. |
| Biometric Authentication Development | Positions vendors for Seoul Metro and Shenzhen Rail Transit gateless corridor flow pilots. |
| India PLI Scheme Manufacturing Localization | Opens Delhi Metro and Mumbai Metro procurement channels under BIS domestic content rules. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of transit agency procurement databases, F-Gas Regulation compliance filings, and ISO certification registries. Interviews with transit authority procurement directors, system integrator project managers, and semiconductor supply specialists informed demand-side and supply-side validation. Secondary sources include Federal Transit Administration Buy America guidance, European Commission digital interoperability directives, and China MIIT equipment standards. Bottom-up unit deployment estimates triangulate against top-down market value reconstruction.
Segmentation dimensions modeled span payment modality, authentication technology, application vertical, and end-user procurement archetype across the analysis window. CAGRs derive from ridership recovery trajectories, infrastructure replacement cycles, and regulatory mandate implementation schedules. Industry-specific inputs include validator shipment volumes by secure-element chip generation and transit agency software subscription renewal rates.
Material uncertainties — semiconductor supply disruption, cybersecurity certification timeline extensions, and open-payment interoperability mandate delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding ridership normalization and federal funding continuity. Revision becomes warranted when F-Gas Regulation phase-out deadlines or ISO 24014 certification adoption rates cross thresholds that reshape procurement specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Car E-Hailing Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Automated People Mover Market