
 Platform Screen Doors Market | 2026-2036
Platform Screen Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Platform Screen Doors Market Outlook
Buyer concentration among state-owned metro operators is realigning procurement toward integrated system packages rather than component sourcing. Shanghai Electric leverages its domestic installation footprint to dominate retrofitting contracts across Chinese provincial capitals. Panasonic Corporation sustains technology leadership in sensor-based door control systems for high-frequency Asian metro lines. Siemens AG competes on European safety certification depth, anchoring its position in German and French railway modernization programs.
Platform screen doors are sealed barrier systems installed at transit platform edges, typically constructed from tempered glass panels with aluminum framing and electromechanical drive units that synchronize with train door positions to prevent passenger falls and control platform climate. Their primary purpose is eliminating accidental or intentional track incursions while reducing ventilation energy loads in underground stations. Automatic product types command the largest installed base due to universal integration with train control signaling, though sensor-based technology segments are expanding fastest as operators replace legacy pneumatic systems with precision obstacle detection. Metro systems represent the deepest end-user margin pool given scale and standardization, while airport retrofits present fragmented but higher-margin opportunities.
China's NMPA and GB standards mandate fire resistance ratings and electromagnetic compatibility testing that filter out uncertified suppliers. The EU's CE marking and MDR frameworks for safety-critical transit components create parallel compliance thresholds for European deployments. Stakeholders must monitor how India's BIS railway equipment certifications and the country's PLI scheme for urban infrastructure reshape supplier qualification requirements in Asia's fastest-expanding transit markets.
Market Dynamics
Metro operators in China and India are consolidating procurement around integrated electromechanical packages, compressing component-level supplier margins while elevating system integrators with full-stack certification capabilities. This buyer concentration is restructuring competitive positioning across Asian urban rail networks.
Growth Catalysts
- China's GB 50157 fire safety standards:Mandated platform edge protection in new underground stations is accelerating electromechanical door installations across tier-one cities.
- Sensor-based obstacle detection:Precision infrared and LiDAR arrays are replacing pneumatic systems in high-frequency metro corridors, reducing track intrusion incidents.
- India's PLI scheme for urban infrastructure:Production-linked incentives for railway equipment localization are attracting foreign system integrators to establish domestic manufacturing.
Market Restraints
- Aluminum and tempered glass input volatility:Price swings in industrial metals and specialty glass are squeezing fabrication margins for door panel assemblies.
- Supplier concentration in electromechanical drives:German and Japanese motor-control specialists dominate precision drive unit supply, creating single-source vulnerability for tier-two integrators.
- Legacy pneumatic system lock-in:Existing compressed-air infrastructure in older metro networks delays capital conversion to electromechanical platforms.
Strategic Opportunities
- India's expanding urban rail networks:Cities including Bengaluru, Hyderabad, and Pune are tendering for first-generation platform screen door systems with full lifecycle service contracts.
- Airport automated people mover retrofits:Climate-controlled terminal environments are driving demand for sealed barrier systems with precision climate integration.
- EU MDR safety-critical component certification:European medical device regulation frameworks are being adapted for transit safety systems, creating compliance advisory services demand.
Industry Challenges
- Electromechanical systems integration expertise:Shortage of engineers proficient in both railway signaling protocols and precision door control algorithms is delaying commissioning timelines.
- Multi-jurisdiction certification sequencing:Concurrent NMPA, CE marking, and BIS approval processes for cross-border projects are extending product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platform Screen Doors Market |
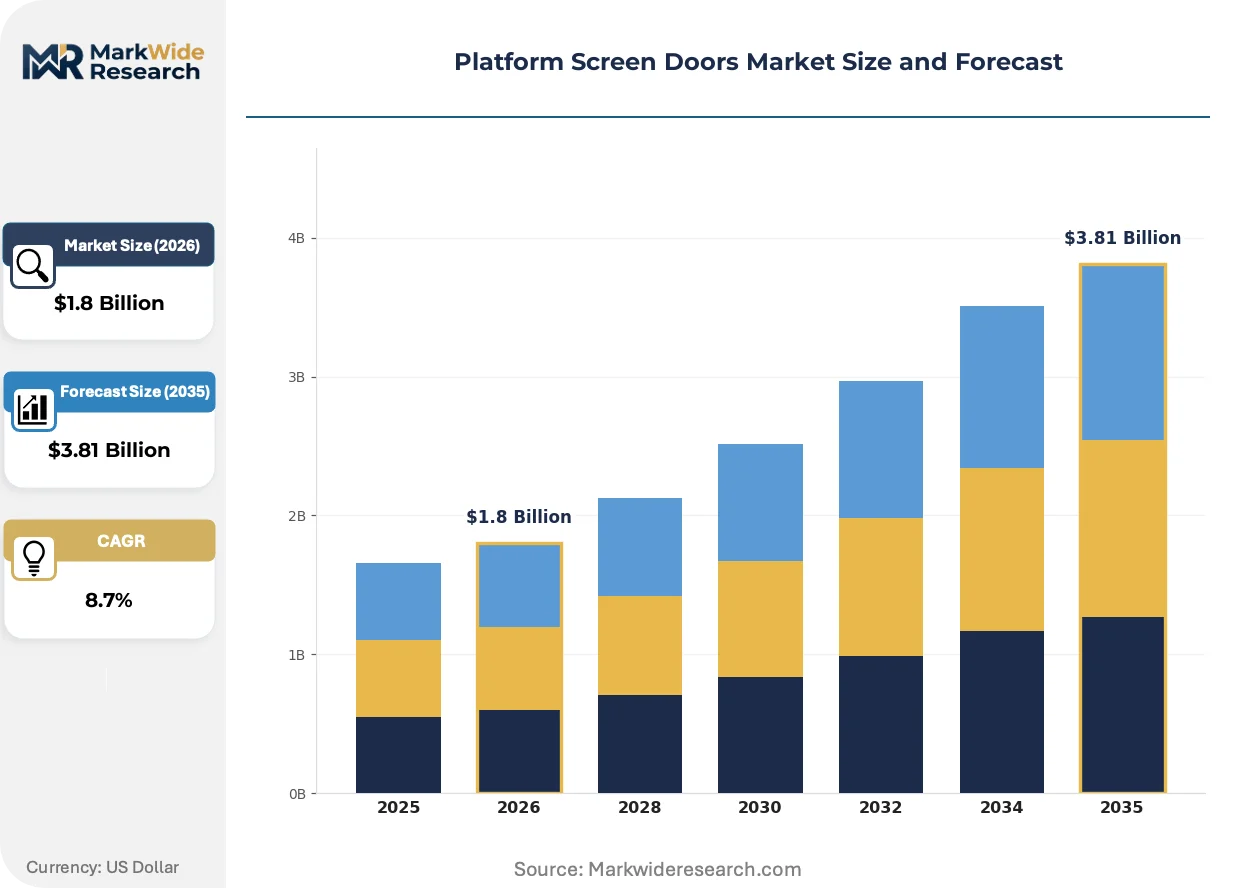
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Semi-Automatic, Pneumatic Technology: Electromechanical, Hydraulic, Magnetic, Sensor-Based End User: Metro Systems, Airports, Railway Stations, Bus Terminals Installation Type: New Construction, Retrofitting, Modular, Custom |
| Companies Covered | Shanghai Electric, Panasonic Corporation, Fangda Group, Nanjing Kangni Mechanical & Electrical, Faiveley Transport, Nabtesco Corporation, Siemens AG, Horton Automatics, KTK Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platform Screen Doors Market Strategic Shifts
Platform screen door technology is converging with train control signaling and building management systems, creating integrated transit environments where barrier operation, climate control, and passenger flow optimization operate from unified command architectures.
Machine vision-based passenger detection is automating gap management between train and platform edges. Shanghai Metro and Tokyo Metro are deploying stereo camera arrays that calculate real-time crowd density and adjust door timing algorithms. This sensor fusion is automating the elimination of manual platform observer roles while compressing station dwell times during peak hours.
China's NMPA and MIIT are tightening electromagnetic compatibility testing for railway safety equipment, filtering out uncertified electromechanical suppliers. The new GB/T standards mandate conducted emissions testing that legacy pneumatic systems cannot satisfy. European manufacturers serving Chinese joint ventures are establishing dedicated compliance laboratories in Suzhou and Chengdu to accelerate certification cycles.
Buyer consolidation among state-owned metro operators is compressing supplier negotiation cycles and unbundling after-sales service contracts from initial installation. Chinese provincial rail groups now separate 10-year maintenance agreements from capital procurement, creating standalone service revenue pools. This unbundling is most visible in Jiangsu and Zhejiang province tenders, where lifecycle cost evaluation criteria outweigh upfront capital bids.
Platform Screen Doors Market Segmentation
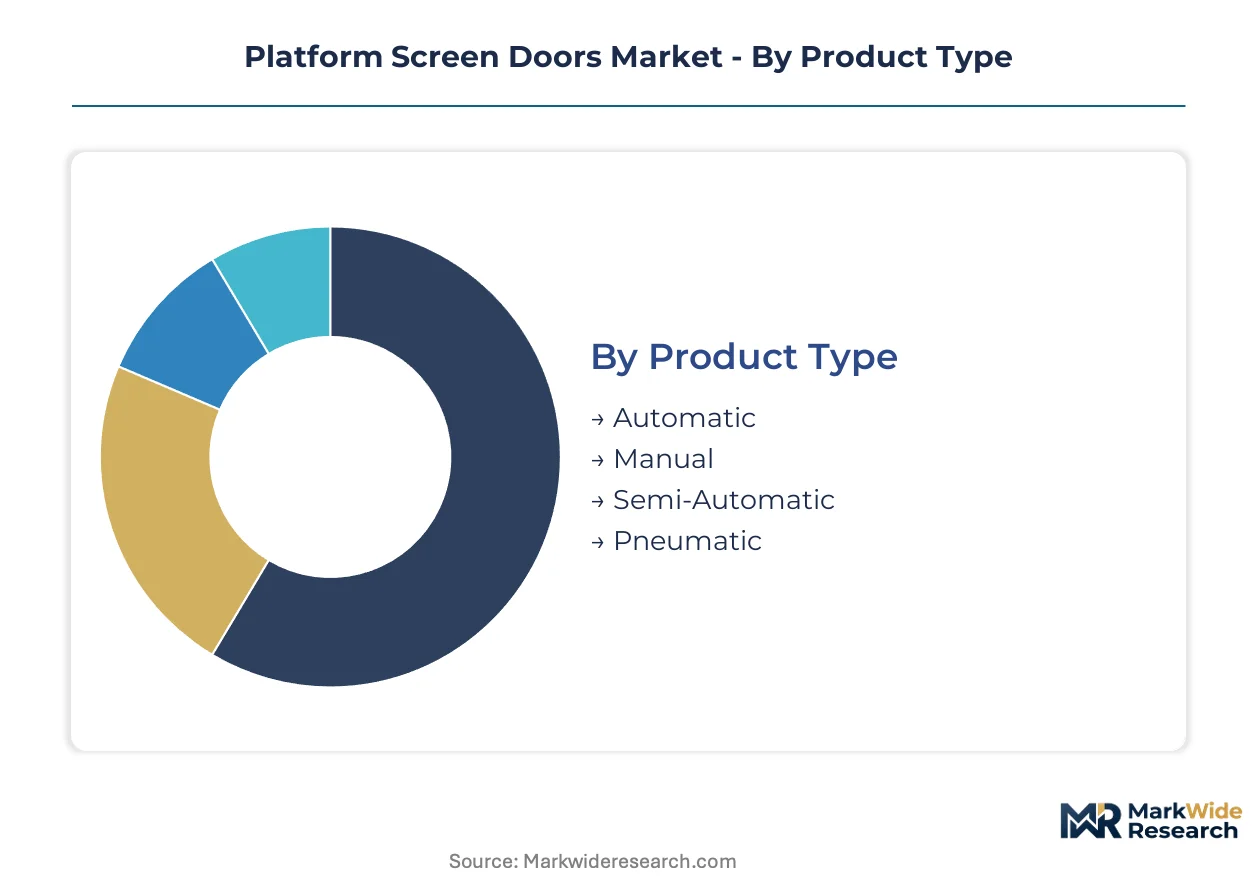
Platform screen door procurement patterns diverge sharply across product architectures and installation contexts. Electromechanical system integrators command premium positioning in high-frequency metro corridors, while pneumatic legacy networks create retrofit-driven demand fragmentation.
Product Type:
Supply concentration in drive unit manufacturing favors integrators with captive electromechanical production.
- Automatic:Full synchronization with train control signaling enables sub-second door response times. Shanghai Metro and Tokyo Metro deployments concentrate demand here, driven by GB 50157 fire safety mandates for underground stations.
- Sensor-Based:Infrared and LiDAR obstacle detection arrays are displacing pneumatic systems in high-frequency Asian corridors. Delhi Metro and Bengaluru Metro tenders specify these for new underground lines.
- Manual:Staff-operated barrier systems persist in low-frequency airport shuttle contexts.
- Semi-Automatic:Hybrid control architectures bridge legacy pneumatic infrastructure with modern signaling.
- Pneumatic:Compressed-air systems dominate legacy networks in older European metros awaiting capital conversion.
Automatic systems absorb the bulk of installed capacity; sensor-based configurations are expanding most quickly.
Technology:
Cost tier differentiation separates precision drive specialists from commodity actuator suppliers.
- Electromechanical:Brushless DC motor arrays with encoder feedback deliver millimeter-position accuracy. German and Japanese motor-control specialists concentrate supply, creating qualification barriers for tier-two integrators.
- Sensor-Based:Machine vision and proximity sensing enable predictive maintenance algorithms. Chinese NMPA electromagnetic compatibility testing filters uncertified suppliers from metro procurement.
- Hydraulic:Fluid power actuation persists in heavy-duty freight rail crossings.
- Magnetic:Linear induction drives enable contactless operation in climate-sensitive airport environments.
Electromechanical platforms anchor current revenue; sensor-based technology gains share fastest.
End User:
Application context dictates specification stringency and lifecycle service bundling.
- Metro Systems:High-frequency underground corridors demand fire-rated glass and synchronized train-to-platform control. China's tier-one cities and India's expanding urban rail networks concentrate procurement volume.
- Airports:Climate-controlled terminal environments require sealed barrier integration with HVAC systems. Automated people mover retrofits present fragmented but higher-margin opportunities.
- Railway Stations:Intercity platforms balance passenger throughput with heritage infrastructure constraints.
- Bus Terminals:Lower-speed applications tolerate simpler barrier specifications.
Metro systems command the deepest margin pool; airport retrofits exhibit the steepest expansion trajectory.
Installation Type:
Customer type fragmentation separates capital-project integrators from lifecycle service providers.
- New Construction:Greenfield metro lines specify integrated electromechanical packages from foundation phase. China's provincial rail groups unbundle 10-year maintenance agreements from capital procurement.
- Retrofitting:Legacy pneumatic conversion demands structural adaptation of platform edges. Jiangsu and Zhejiang province tenders evaluate lifecycle cost criteria above upfront capital bids.
- Modular:Prefabricated panel systems accelerate commissioning in constrained construction windows.
- Custom:Heritage station geometries require bespoke aluminum framing and glass cutting.
New construction absorbs dominant capital flow; retrofitting is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum and tempered glass fabrication clusters in China's Yangtze River Delta and Pearl River Delta anchor regional supply capacity for electromechanical door assemblies. Metro expansion in India and certification tightening across East Asian markets are redistributing procurement volumes.
China
GB 50157 fire safety mandates for underground stations are accelerating electromechanical installations across tier-one cities. NMPA electromagnetic compatibility testing filters uncertified suppliers from metro procurement. Shanghai and Beijing municipal rail operators dominate retrofitting contracts for legacy pneumatic conversions.
India
Bengaluru Metro and Hyderabad Metro are tendering first-generation platform screen door systems with 10-year lifecycle service contracts. The PLI scheme for urban infrastructure attracts foreign system integrators to establish domestic manufacturing. Delhi-NCR and Maharashtra state rail projects concentrate new construction demand.
Japan
Tokyo Metro deploys stereo camera arrays for real-time crowd density management and automated gap detection. METI industrial standards for railway safety equipment enforce precision electromechanical specifications. Osaka and Nagoya urban rail networks sustain replacement cycles for high-frequency corridor systems.
Germany
Siemens AG anchors European safety certification depth through CE marking and adapted MDR frameworks for transit safety systems. KBA vehicle safety standards influence railway equipment qualification protocols. Berlin and Munich S-Bahn modernization programs drive retrofitting demand for sealed barrier integration.
South Korea
Seoul Metropolitan Subway expands sensor-based obstacle detection across high-frequency underground corridors. MFDS medical device regulation frameworks are being adapted for safety-critical transit component certification. Busan and Daegu metro operators unbundle maintenance agreements from capital procurement.
Platform Screen Doors Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sensor-based automation and integrated lifecycle service contracts. The market exhibits moderate concentration around electromechanical system integrators with captive drive unit production. Three archetypes dominate: domestic installation specialists leveraging regional certification proximity, precision motor-control technology leaders, and full-stack safety certification aggregators. Competitive moves center on geographic licensing partnerships and backward integration into aluminum framing fabrication.
Within the domestic installation tier, Shanghai Electric exemplifies regional footprint leverage for retrofitting contracts. Panasonic Corporation and Siemens AG occupy positions on opposite certification vectors—Asian sensor-based precision versus European safety standard depth. Nabtesco Corporation represents the precision drive unit specialization archetype. Fangda Group and Nanjing Kangni Mechanical & Electrical sit within the Chinese provincial system integrator cluster.
| Leading Market Players |
|---|
| Shanghai Electric |
| Panasonic Corporation |
| Fangda Group |
| Nanjing Kangni Mechanical & Electrical |
| Faiveley Transport |
| Nabtesco Corporation |
| Siemens AG |
| Horton Automatics |
| KTK Group |
| Others |
Value Chain & Pricing Dynamics
Chinese provincial rail groups unbundling 10-year maintenance agreements from capital procurement is forcing suppliers to restructure cost allocation across electromechanical packages and standalone service contracts. This buyer-driven separation compresses upfront capital bids while elevating lifecycle cost evaluation criteria in Jiangsu and Zhejiang tenders.
Pricing Analysis
Warranty and service-bundling variations now dominate pricing architecture, with Chinese metro operators separating 10-year maintenance pacts from initial installation while Indian PLI-scheme tenders favor full-lifecycle packages. Three-tier pricing structure across premium electromechanical systems, standard retrofit configurations, and economy pneumatic conversions reflects certification depth and fire-resistance ratings. Cost compression in standard-tier panel assemblies is intensifying because aluminum and tempered glass input volatility squeezes fabrication margins. State-owned metro operators in China exhibit lowest price sensitivity due to procurement consolidation, while tier-two Indian urban rail projects show highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Workforce availability for precision electromechanical assembly in China's Yangtze River Delta, Japan's Kansai industrial corridor, and Germany's Baden-Württemberg region anchors supply capacity for drive unit manufacturing. Raw material dependencies center on aluminum extrusion from Chinese smelters, tempered glass from specialty float-glass producers, and brushless DC motors from Japanese and German motor-control specialists. Single-source vulnerability in precision drive unit supply creates qualification barriers for tier-two integrators seeking NMPA electromagnetic compatibility certification. Distribution runs through state-owned metro procurement consortia in Asia and specialized railway equipment distributors in European modernization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where China's NMPA electromagnetic compatibility testing and GB 50157 fire safety mandates erect certification moats that filter out uncertified suppliers and consolidate procurement around full-stack system integrators.
For Market Incumbents: Lock in retrofitting contracts across Chinese provincial capitals by leveraging captive electromechanical production and established NMPA certification laboratories in Suzhou and Chengdu. Defend against emerging sensor-based automation specialists by deepening backward integration into aluminum framing fabrication and securing exclusive service agreements for unbundled maintenance contracts in Jiangsu and Zhejiang province tenders.
For New Entrants and Emerging Players: Launch via direct engagement with India's PLI-scheme urban infrastructure tenders, targeting first-generation platform screen door installations in Bengaluru, Hyderabad, and Pune with full lifecycle service contracts as the go-to-market anchor. Bypass saturated Chinese tier-one city procurement by specializing in modular prefabricated panel systems that accelerate commissioning in constrained construction windows for airport automated people mover retrofits.
For Investors and Strategic Acquirers: The window for entry favors electromechanical system integrators with captive drive unit production and multi-jurisdiction certification capabilities spanning NMPA, CE marking, and BIS approval processes. Long-term viability hinges on consolidation plays that aggregate regional installation footprints and compliance advisory services. Monitor India's BIS railway equipment certification sequencing and PLI localization thresholds as the inflection signal for supplier qualification reshaping in Asia's fastest-expanding transit markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Framing | Captive supply of fire-rated panel assemblies reduces input volatility exposure for Chinese metro retrofits. |
| Multi-Jurisdiction Certification Investment | Concurrent NMPA, CE marking, and BIS capabilities compress product launch cycles by 12-18 months for cross-border projects. |
| Lifecycle Service Contract Unbundling | Standalone 10-year maintenance agreements in Jiangsu and Zhejiang create recurring revenue pools separate from capital procurement. |
| Sensor-Based Obstacle Detection Development | Precision infrared and LiDAR arrays displace pneumatic systems in Delhi Metro and Bengaluru Metro underground lines. |
| Domestic Manufacturing Establishment under PLI | Foreign system integrators localize production to qualify for India's production-linked incentives in urban railway equipment. |
Study Parameters
Independent corroboration across metro operator procurement officers, electromechanical system engineering directors, and railway safety certification consultants underwrites the qualitative findings in this study. Primary interviews with platform screen door commissioning specialists, aluminum fabrication plant managers, and German motor-control supplier account executives combined with secondary validation from NMPA electromagnetic compatibility filings, BIS railway equipment certification registers, and EU CE marking databases for transit safety components. Bottom-up project pipeline aggregation and top-down transit infrastructure investment flow analysis complete the triangulation.
Rate-of-change decomposition across the projection horizon separates volume expansion from value-per-unit evolution through product type, technology architecture, end-user application, and installation context dimensions. CAGRs derive from fitted growth curves calibrated to metro line commissioning schedules, airport retrofit tender pipelines, and regulatory mandate implementation timelines. Industry-specific forecast inputs include China's GB 50157 fire safety standard adoption curves and India's PLI scheme localization thresholds for railway equipment manufacturing.
The model assumes a particular technology adoption path; alternative pathways for sensor-based electromechanical systems displacing legacy pneumatic infrastructure would alter the outlook. Forecasts reflect assumptions regarding NMPA certification cycle durations, aluminum input price stabilization, and Indian state-level urban rail project approval velocities. Material deviation in China's dual carbon goals implementation or India's BIS certification sequencing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Air Taxi Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
E-Bike Rental Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market