
 North America Passenger Information System Market | 2026-2036
North America Passenger Information System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Passenger Information System Market Analytics
Software-defined fleet management is consolidating around subscription-based service models that replace upfront capital expenditure with recurring platform fees. Thales Group leverages its signaling heritage to anchor integrated PIS-rail control bundles across Amtrak corridors. Cubic Corporation sustains competitive density through its fare-collection-to-information convergence in urban transit. Alstom SA differentiates via manufacturing scale in North American rolling stock, embedding passenger information as a factory-standard feature rather than aftermarket retrofit.
A passenger information system integrates real-time data processing, audiovisual display hardware, and communication networks to deliver schedule, route, and emergency content to travelers across transport modes. Core specifications include IP65-rated displays for vehicle environments, IEEE 802.11 wireless backbone protocols, and latency thresholds under three seconds for critical safety announcements. Display systems and software categories capture concentrated margin pools where hardware refresh cycles overlap with cloud migration. Interactive touchscreen adoption accelerates fastest among airport and premium rail deployments. LED technology segments face commoditization pressure as procurement shifts toward full-service platform contracts bundling content management with physical infrastructure.
The Federal Railroad Administration enforces positive train control interoperability standards that mandate integrated passenger communication during service disruptions. The Federal Transit Administration's accessibility directives under ADA Title II compel audio-visual parity in all public transit information systems. Transport Canada and the Canadian Transportation Agency coordinate cross-border harmonization for VIA Rail and Amtrak joint operations. Stakeholders must weigh capital ownership against operational flexibility as regulatory compliance deadlines compress procurement timelines and favor vendors with certified, upgradeable platforms.
Market Dynamics
Software-defined fleet management is consolidating around subscription-based service models that replace upfront capital expenditure with recurring platform fees across North American transit authorities.
Growth Catalysts
- Federal Railroad Administration mandates:Positive train control interoperability standards require integrated passenger communication during service disruptions, forcing hardware refresh cycles.
- Cloud migration:Transit authorities in the Northeast Corridor rail network connecting Boston, New York, Philadelphia, and Washington DC accelerate real-time data processing deployments.
- ADA Title II directives:The Federal Transit Administration's accessibility requirements compel audio-visual parity in all public transit information systems.
Market Restraints
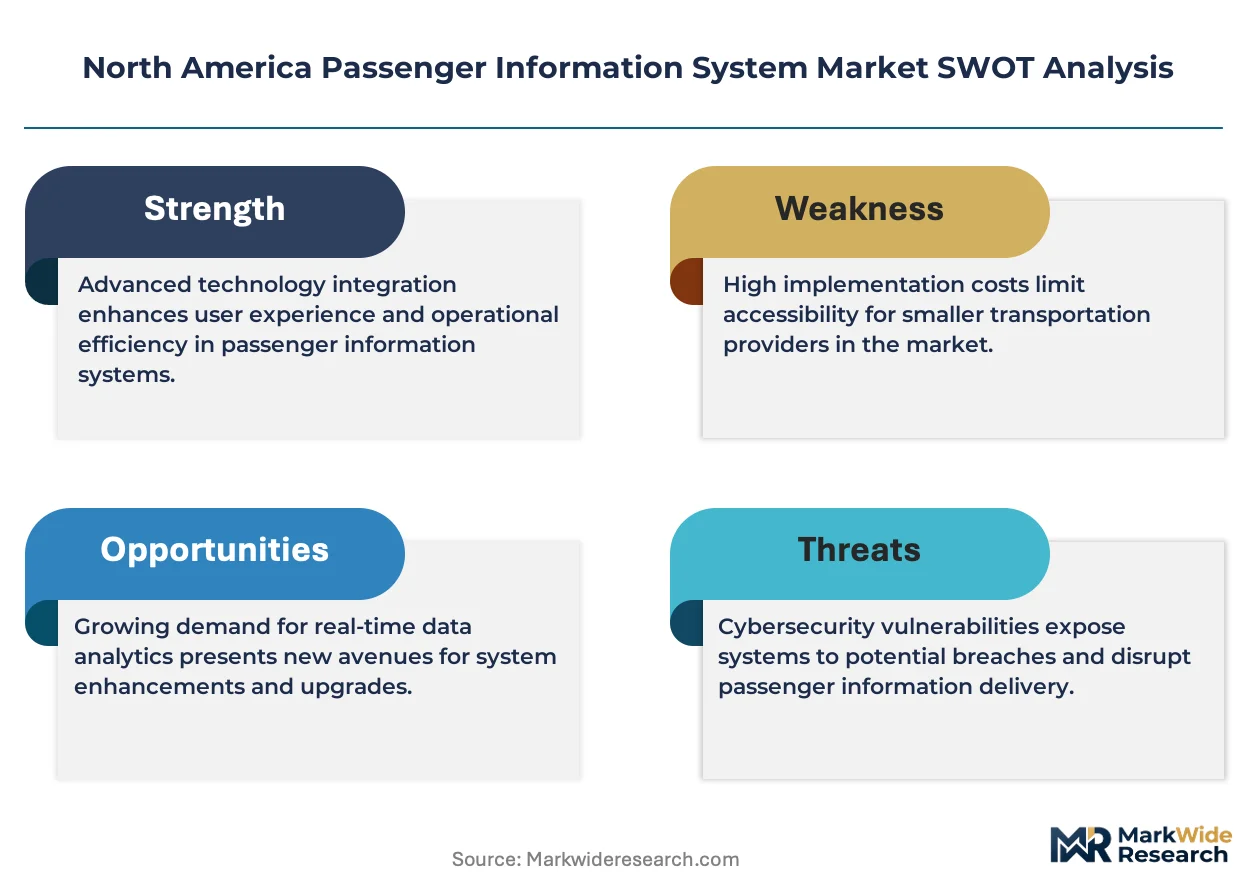
- Capital intensity:IP65-rated displays and IEEE 802.11 wireless backbone protocols require substantial upfront investment before operational savings materialize.
- Supply concentration:LED technology segments face commoditization pressure as procurement shifts toward full-service platform contracts bundling content management with physical infrastructure.
- Technical latency thresholds:Critical safety announcements must deliver under three seconds, constraining hardware and network architecture choices.
Strategic Opportunities
- Cross-border harmonization:Transport Canada and the Canadian Transportation Agency coordinate standards for VIA Rail and Amtrak joint operations.
- Interactive touchscreen adoption:Airport and premium rail deployments show fastest uptake for passenger-facing interface upgrades.
- Factory-standard embedding:Rolling stock manufacturers integrate passenger information as original equipment rather than aftermarket retrofit.
Industry Challenges
- Certified platform scarcity:Regulatory compliance deadlines compress procurement timelines and favor vendors with upgradeable, pre-certified systems.
- Legacy system integration:Transit authorities must bridge decades-old infrastructure with modern IP-based communication networks.
- Operational flexibility trade-offs:Stakeholders weigh capital ownership against recurring platform fees under constrained upgrade windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Passenger Information System Market |
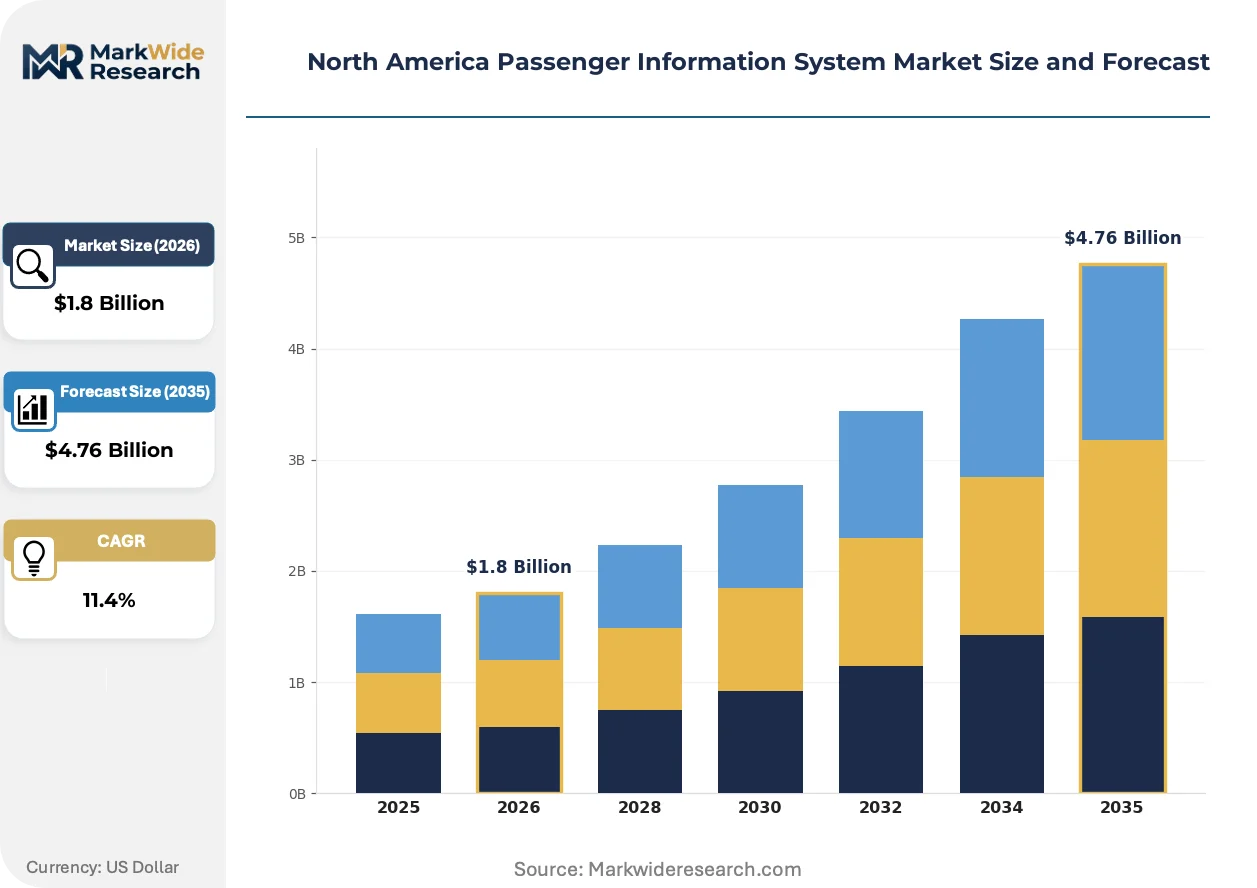
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display System, Announcement System, Software, Network Infrastructure End User: Airlines, Rail Operators, Bus Services, Transit Authorities Technology: LCD, LED, Interactive Touchscreens, Cloud-based Solutions Application: Real-time Updates, Ticketing Information, Schedule Notifications, Emergency Announcements |
| Companies Covered | Thales Group, Cubic Corporation, Alstom SA, ST Engineering, Luminator Technology Group, Indra Sistemas, Hitachi Ltd, Siemens Mobility, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Passenger Information System Market Evolving Landscape
Real-time passenger communication deployments are accelerating as transit authorities modernize aging infrastructure and federal mandates compress procurement timelines.
Edge computing architectures are electrifying onboard data processing capabilities across rail and bus fleets. Transit operators in the Northeast Corridor deploy localized processing nodes to reduce dependency on continuous cellular connectivity. This distributed topology is electrifying competitive positioning among system integrators who can deliver sub-three-second latency for emergency broadcasts.
The Federal Railroad Administration enforces interoperability standards that mandate integrated passenger communication during service disruptions. These rules compress vendor qualification timelines and elevate certified platform providers. Amtrak corridors and commuter rail operators face the steepest compliance burdens as positive train control integration deadlines approach.
Service contract structures are displacing capital purchase models across municipal transit agencies. Three-to-five-year platform subscriptions with bundled maintenance replace discrete hardware procurement. This shift concentrates most visibly among mid-sized urban transit authorities seeking to preserve budget flexibility while meeting ADA compliance deadlines.
North America Passenger Information System Market Segmentation
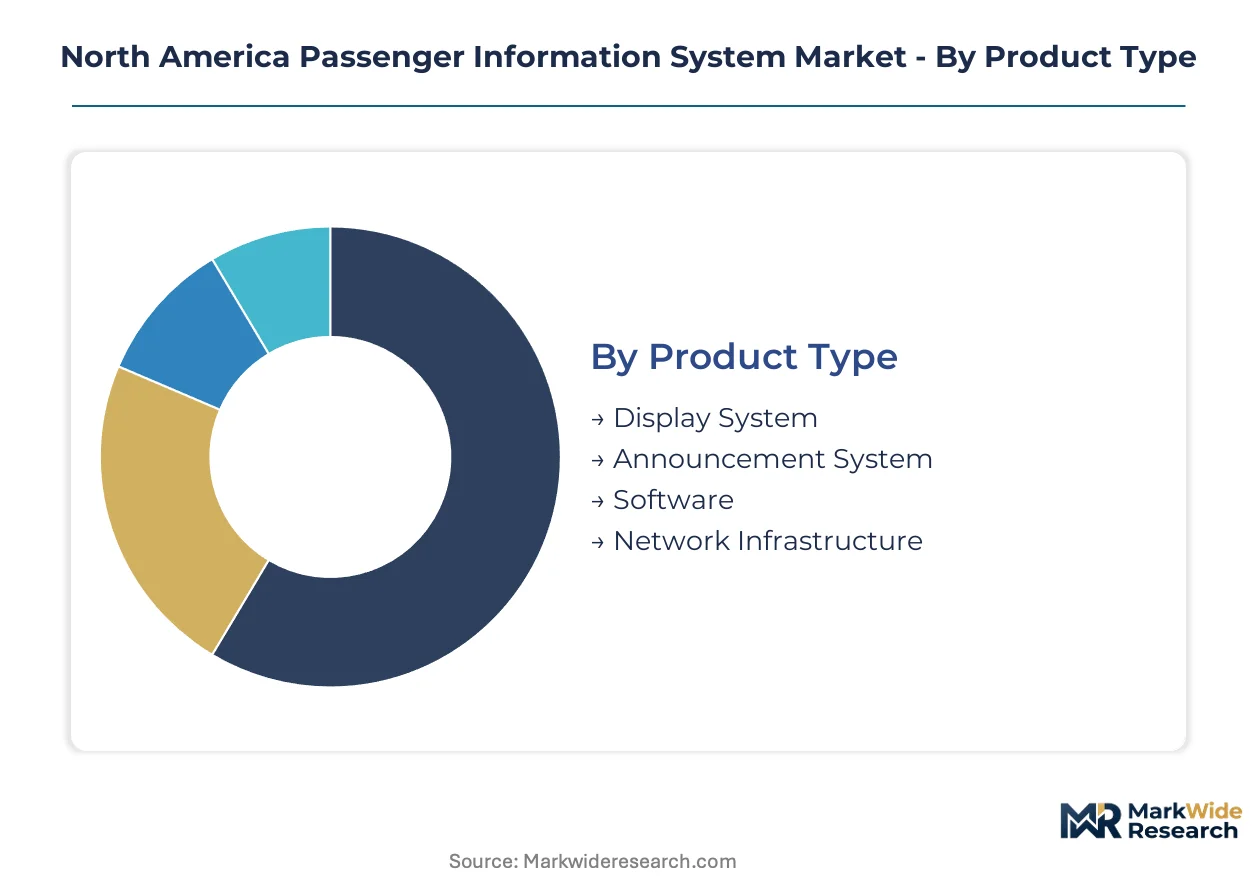
Passenger information system procurement across North America follows distinct technology refresh cycles and regulatory compliance deadlines. Understanding how display hardware, software platforms, and service delivery models fragment reveals where margin concentrates and where commoditization pressures build.
Product Type:
Volume deployments concentrate in hardware categories with standardized specifications, while premium capture sits with software and integrated service bundles that command recurring revenue streams.
- Display System:IP65-rated panels engineered for vibration, temperature extremes, and humidity exposure in vehicle environments. Northeast Corridor rail operators and major metropolitan transit authorities drive replacement demand as ADA compliance deadlines force audio-visual parity upgrades.
- Software:Cloud-native platforms processing real-time data feeds from signaling, scheduling, and emergency management systems. Transit authorities in Boston, New York, Philadelphia, and Washington DC accelerate subscription-based procurement to replace capital-intensive legacy architectures.
- Announcement System:Synchronized audio distribution networks meeting Federal Railroad Administration latency thresholds under three seconds for safety-critical broadcasts.
- Network Infrastructure:IEEE 802.11 wireless backbone protocols enabling seamless vehicle-to-ground communication across tunnels and rural corridors.
Mature deployment sits with Display System hardware. Newer deployment is concentrated in Software platforms.
End User:
Customer type determines procurement authority structure and budget cycle timing, with federal operators following distinct acquisition rules versus municipal agencies.
- Rail Operators:Amtrak and commuter rail systems spanning the Northeast Corridor face compressed vendor qualification timelines under Federal Railroad Administration interoperability mandates. Positive train control integration requirements elevate demand for certified, upgradeable platforms.
- Transit Authorities:Municipal bus and subway operators in Chicago, Los Angeles, and Toronto balance ADA Title II compliance deadlines against constrained capital budgets through service contract structures.
- Airlines:Hub airports in Atlanta, Dallas, and Denver deploy interactive wayfinding and gate management systems with premium passenger experience specifications.
- Bus Services:Intercity and regional operators prioritize cost-effective LED displays with minimal maintenance requirements across dispersed route networks.
Procurement centralization is strongest among Rail Operators. Fragmented purchasing characterizes Bus Services.
Technology:
Manufacturing scale and supply concentration vary sharply across display technologies, with implications for vendor margin sustainability and customer switching costs.
- Cloud-based Solutions:Edge computing architectures processing data locally onboard vehicles while synchronizing with central management platforms. Transit operators deploy these distributed topologies to reduce cellular dependency across coverage gaps.
- Interactive Touchscreens:Passenger-facing interfaces with gesture recognition and multilingual content delivery. Premium airport terminals and Amtrak Acela corridors show steepest uptake for wayfinding and service disruption communication.
- LED:High-brightness panels with extended operational lifespans for outdoor station platforms and bus shelters facing direct sunlight exposure.
- LCD:Cost-optimized indoor displays for climate-controlled transit facilities with standardized mounting configurations.
Technology refresh cycles are shortest for Cloud-based Solutions. Replacement intervals extend longest for LCD installations.
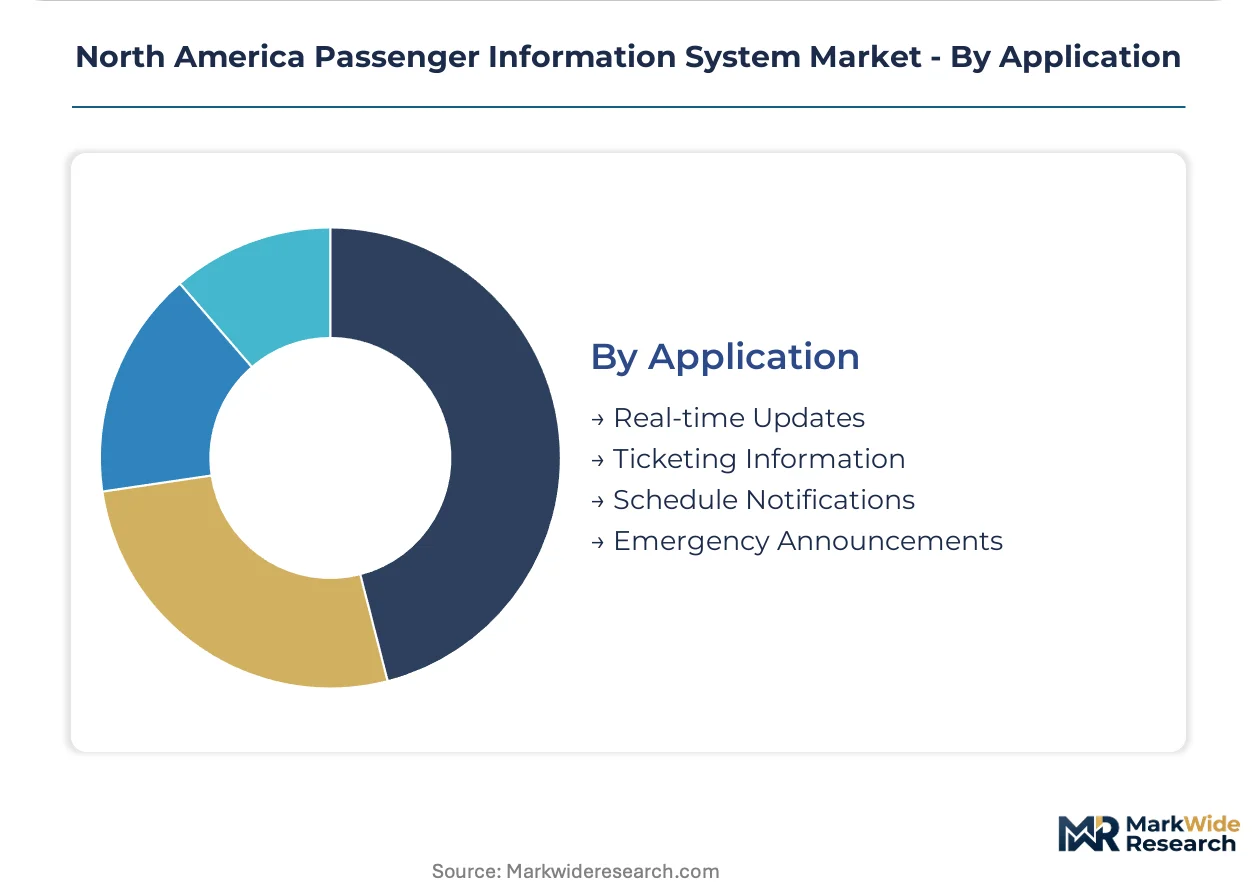
Application:
Use case prioritization reflects regulatory mandates versus operational efficiency investments, with safety-critical functions commanding procurement precedence.
- Emergency Announcements:Federally mandated communication pathways integrating positive train control disruption alerts with passenger notification systems. Federal Railroad Administration enforcement elevates platform certification requirements.
- Real-time Updates:Dynamic arrival and departure information synthesized from GPS, signaling, and traffic management feeds. Northeast Corridor deployments lead in accuracy and refresh frequency specifications.
- Schedule Notifications:Planned service information with predictive delay modeling based on historical performance patterns.
- Ticketing Information:Fare purchase prompts and transfer guidance converging with mobile payment system integration.
Regulatory pressure concentrates on Emergency Announcements. Operational investment prioritizes Real-time Updates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast Corridor rail network connecting Boston, New York, Philadelphia, and Washington DC anchors North American passenger information system deployment density. Federal mandates and ADA compliance deadlines compress procurement timelines across this corridor. Transit authorities prioritize certified, upgradeable platforms that satisfy cross-border operational requirements.
United States
The Federal Railroad Administration enforces positive train control interoperability standards that mandate integrated passenger communication during service disruptions. Amtrak corridors and commuter rail operators face compressed vendor qualification timelines as compliance deadlines approach. Transit authorities in Chicago, Los Angeles, and Atlanta balance capital budgets against recurring platform subscription models.
Canada
Transport Canada and the Canadian Transportation Agency coordinate cross-border harmonization standards for VIA Rail operations. Municipal transit operators in Toronto and Vancouver accelerate real-time data processing deployments to match US corridor specifications. Canadian procurement favors service contract structures that preserve operational flexibility under constrained upgrade windows.
Mexico
Ferromex and KCSM rail operators modernize passenger communication infrastructure along cross-border freight corridors. Mexico's Secretariat of Infrastructure, Communications and Transportation aligns emerging standards with US Federal Railroad Administration frameworks. Monterrey and Mexico City transit authorities pilot interactive touchscreen installations in premium corridor segments.
North America Passenger Information System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent value capture models in the passenger information system market. Integrated rolling stock manufacturers embed hardware as factory-standard features, while specialized software vendors pursue subscription-based platform revenues. Three archetypes dominate: signaling heritage conglomerates anchoring rail control bundles, fare-collection convergers exploiting urban transit density, and display technology specialists facing commoditization pressure. Competitive moves concentrate on M&A for certified platform portfolios and strategic partnerships for cloud-native service delivery.
Within the signaling heritage tier, Thales Group and Alstom SA exemplify integrated system bundling across Amtrak corridors. Cubic Corporation occupies a position at the fare-collection converger node, exploiting municipal transit procurement patterns. Siemens Mobility and Hitachi Ltd represent diversified industrial conglomerates leveraging manufacturing scale for factory-standard embedding strategies. These named entities anchor competitive positioning without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Thales Group |
| Cubic Corporation |
| Alstom SA |
| ST Engineering |
| Luminator Technology Group |
| Indra Sistemas |
| Hitachi Ltd |
| Siemens Mobility |
| Mitsubishi Electric Corporation |
| Others |
Value Network & Pricing Analysis
Semiconductor price indices for industrial-grade processors cascade through passenger information system manufacturing, compressing margins on display controllers and edge computing nodes while amplifying spreads between subscription-based platform tiers and commoditized hardware-only contracts.
Pricing Analysis
Uptime guarantees anchor value-based pricing across North American transit authorities, with three-tier pricing structure across premium, standard, and economy levels tied to system availability commitments. Price differentiation stems from ADA certification grade and after-sales service bundling. Cost compression in LED display modules intensifies because procurement shifts toward full-service platform contracts. Municipal transit authorities exhibit highest price sensitivity; premium rail operators and hub airports show lowest sensitivity due to federal compliance deadlines.
Supply Chain Analysis
Workforce availability constraints in Mexican electronics assembly hubs and Vietnamese component manufacturing centers ripple through display panel lead times. Supply concentrates in China for LED driver circuits, South Korea for OLED subassemblies, and Taiwan for industrial computing chipsets. Raw material dependencies span rare earth phosphors, copper interconnects, and aluminum heat dissipation housings. Single-source vulnerability in IEEE 802.11 wireless chipset supply poses structural risk. Distribution runs through certified systems integrators with Federal Railroad Administration qualification status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American passenger information system competition has become a vertical-integration race, with signaling heritage conglomerates and rolling stock manufacturers capturing margin through captive supply of cloud-native platforms and factory-embedded hardware.
For Market Incumbents: Anchor competitive position through backward integration into edge computing hardware production and exclusive certification pipelines with the Federal Railroad Administration. Consolidate around subscription-based service models that replace discrete hardware procurement. Counter emerging software-native entrants by bundling positive train control interoperability into integrated rail control offerings. For New Entrants and Emerging Players: Cloud-native middleware for legacy system bridging offers a technology-first wedge into municipal transit authorities facing compressed ADA compliance deadlines. Target mid-sized bus operators in the US Southeast and Canadian Prairie provinces where procurement remains fragmented. Pursue channel partnerships with established fare collection system vendors to bypass direct certification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-defined platform specialists with Transport Canada pre-certification in Ontario and Quebec. Long-term viability hinges on recurring revenue share exceeding sixty percent of total contract value. Monitor Federal Transit Administration grant disbursement velocity as inflection indicator for municipal procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Thales Group and Alstom SA bundle PIS with signaling to lock out point-solution competitors across Amtrak corridors. |
| Backward Integration | Cubic Corporation captures margin through in-house production of IP65-rated display enclosures for harsh vehicle environments. |
| Certification Investment | Federal Railroad Administration qualification status compresses vendor pools and elevates pricing power for pre-approved platforms. |
| Geographic Expansion | Cross-border harmonization between Transport Canada and US regulators opens unified procurement for VIA Rail and Amtrak joint operations. |
| Strategic Partnership | Cloud infrastructure alliances with hyperscalers reduce latency below three seconds for emergency broadcast compliance. |
Research Methodology
Multi-period observation of Federal Railroad Administration enforcement actions, ADA litigation filings, and transit authority capital budget disclosures anchored the trend analysis, supplemented by interviews with rail operations directors, municipal procurement officers, systems integration engineers, and cloud platform architects. Secondary validation drew from Federal Transit Administration grant databases, Transport Canada regulatory notices, Amtrak capital investment reports, and SEC filings of listed rolling stock manufacturers. Bottom-up project pipeline tracking triangulated against top-down addressable market sizing.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical deployment data and regulatory deadline clustering. Forecast inputs incorporated Northeast Corridor infrastructure age profiles and positive train control integration completion schedules.
Several conditions sit outside the modeled scope, including Mexico regulatory harmonization velocity and hyperscaler cloud pricing volatility. Forecasts reflect assumptions about federal grant continuity and cross-border operational standardization timelines. Material deviation in Federal Railroad Administration enforcement intensity or ADA litigation volume warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Mexico Ride Hailing Market