
 Intermodal Corridor Performance Monitoring Dashboards Market | 2026-2036
Intermodal Corridor Performance Monitoring Dashboards Market Size, Share, and Industry Trends Forecast 2026-2036
Intermodal Corridor Performance Monitoring Dashboards Market Insights
The performance monitoring dashboard landscape is shifting between premium platforms with embedded predictive engines and commodity offerings limited to basic visualization. Wabtec leverages its rail heritage to dominate hardware-integrated deployments across North American corridors. Siemens Mobility anchors European market presence through its signaling-to-analytics stack. SAP competes by extending ERP data pipelines directly into corridor operations.
Intermodal corridor performance monitoring dashboards are software platforms that aggregate telemetry from rail, truck, vessel, and terminal assets to calculate dwell times, velocity consistency, and handoff reliability across freight corridors. These systems typically process IoT sensor streams, GPS signals, and EDI messages through edge gateways before surfacing operational KPIs to dispatchers and planners. Cloud-based deployment leads solution type adoption due to elastic compute requirements during peak freight seasons, while predictive analytics commands the fastest expansion as operators seek to preempt congestion before it cascades through hub networks. Real-time analytics remains the mature revenue base, though margin pools concentrate in visualization platforms customized for multimodal control towers.
The Federal Railroad Administration enforces safety and interoperability standards that shape data collection protocols across US corridors. The EU Green Deal and F-Gas Regulation mandate emissions transparency, forcing dashboard vendors to integrate carbon accounting modules for European market access. Stakeholders must weigh whether to build captive analytics capabilities or absorb platform consolidation as predictive functionality becomes table stakes.
Market Dynamics
The EU Green Deal's emissions tracking mandates are compressing procurement timelines as freight operators race to deploy carbon-accounting dashboards before enforcement deadlines.
Growth Catalysts
- Rail-to-truck handoff optimization:Terminal operators in Germany's Rhine-Alpine corridor are mandating real-time dwell tracking to minimize container idle time during modal transfers.
- F-Gas Regulation:The EU's phasedown of fluorinated gases is forcing refrigerated intermodal operators to monitor reefer unit performance through integrated dashboard telemetry.
- Predictive congestion algorithms:Machine learning models processing GPS and EDI streams now flag bottleneck risks 4-6 hours before cascade failures disrupt hub operations.
Market Restraints
- Sensor hardware concentration:Industrial IoT gateways for rail telemetry rely heavily on semiconductor fabs in Taiwan, exposing deployment schedules to geopolitical supply shocks.
- Edge compute costs:Processing telemetry streams locally in remote corridor segments requires ruggedized servers that cost 3-4x equivalent cloud capacity.
- Cross-border data friction:GDPR's data residency requirements block seamless dashboard aggregation when freight crosses from Germany into non-EU Balkan corridors.
Strategic Opportunities
- India's Dedicated Freight Corridors:The Eastern and Western DFCs lack mature monitoring infrastructure, creating first-mover openings for cloud-native dashboard vendors.
- Digital twin convergence:Combining physics-based corridor simulations with live telemetry is enabling scenario planning for infrastructure expansion projects.
- CSRD-aligned carbon reporting:The EU's Corporate Sustainability Reporting Directive mandates granular emissions disclosure, positioning dashboard vendors as compliance infrastructure providers.
Industry Challenges
- OT-IT integration complexity:Rail signaling systems using legacy protocols require protocol gateways that introduce latency and failure points into real-time pipelines.
- Multimodal data standardization:EDI, API, and proprietary terminal formats lack unified schemas, forcing expensive normalization layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intermodal Corridor Performance Monitoring Dashboards Market |
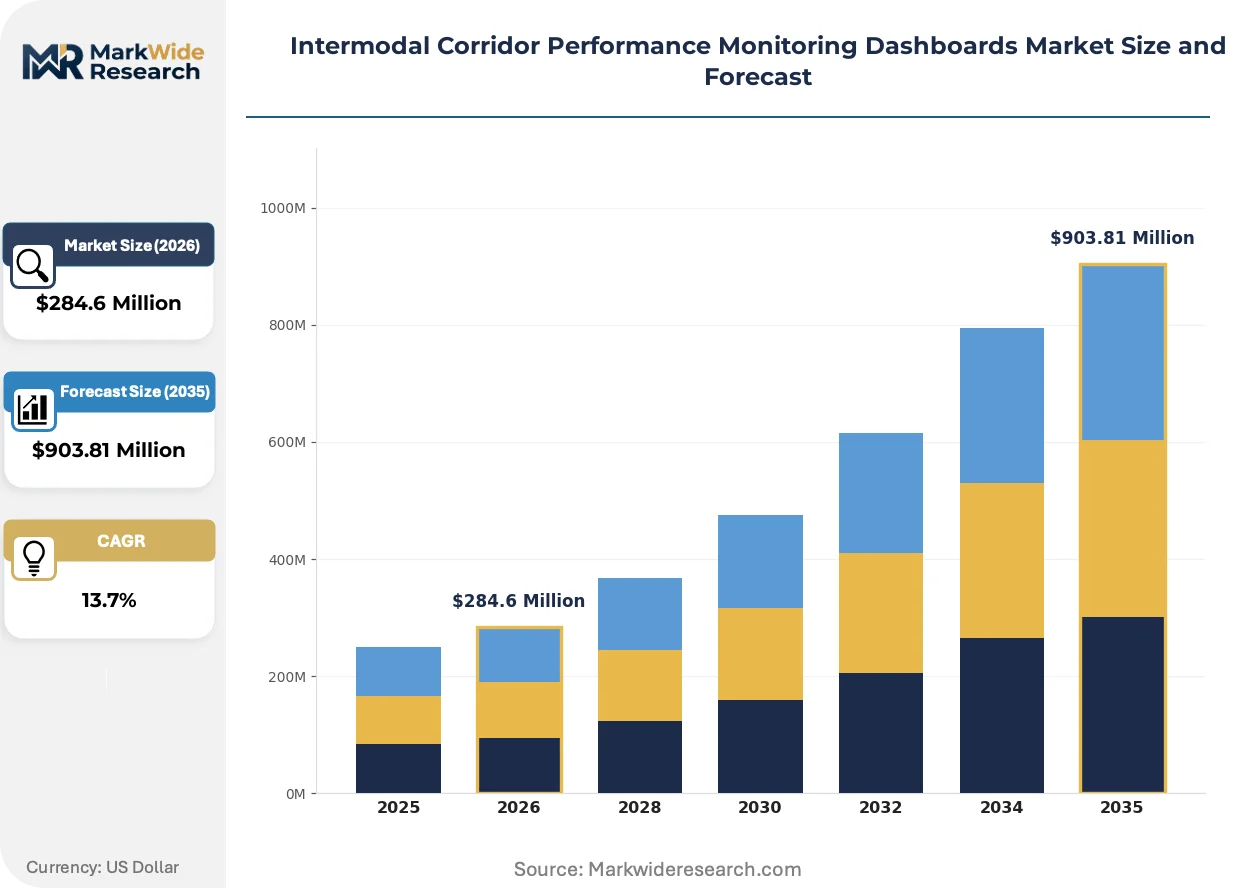
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $903.81 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Type: Real-Time Analytics, Predictive Analytics, Reporting, Visualization Platforms, Alert Systems Use Case: Freight Tracking, Route Optimization, Delay Analysis, Capacity Planning, Asset Utilization End User: Logistics Providers, Freight Forwarders, Port Authorities, Rail Operators, Shipping Companies |
| Companies Covered | Wabtec, project44, SAP, Oracle, Hitachi Rail, Siemens Mobility, Trimble, Cognizant, Blue Yonder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intermodal Corridor Performance Monitoring Dashboards Market Trends and Innovations
Telemetry fusion architectures are displacing single-mode tracking as the baseline expectation, with buyers demanding seamless handoff visibility across rail, truck, and vessel legs.
Digital twin platforms are automating corridor capacity planning by ingesting live sensor streams and generating synthetic load scenarios. Deutsche Bahn's freight division has deployed these systems across the Rhine-Alpine axis, compressing infrastructure investment decision cycles from months to weeks. The technology is automating what previously required manual dispatch coordination and spreadsheet-based forecasting.
REACH substance restrictions are reshaping hardware procurement as dashboard vendors face compliance audits for sensors containing restricted heavy metals. Industrial IoT manufacturers must now certify component supply chains down to the smelter level. European deployments face the strictest documentation burdens, with some vendors shifting final assembly to Switzerland to exploit Swissmedic's mutual recognition agreements.
Control tower consolidation is altering buyer behavior as large freight forwarders absorb dashboard functionality into captive platforms rather than licensing standalone tools. Kuehne+Nagel and DSV have built internal analytics units, squeezing independent software vendors out of top-tier accounts. This pattern is most pronounced in Germany and the Netherlands, where 3PL concentration creates sufficient scale for in-house development.
Intermodal Corridor Performance Monitoring Dashboards Market Segmentation
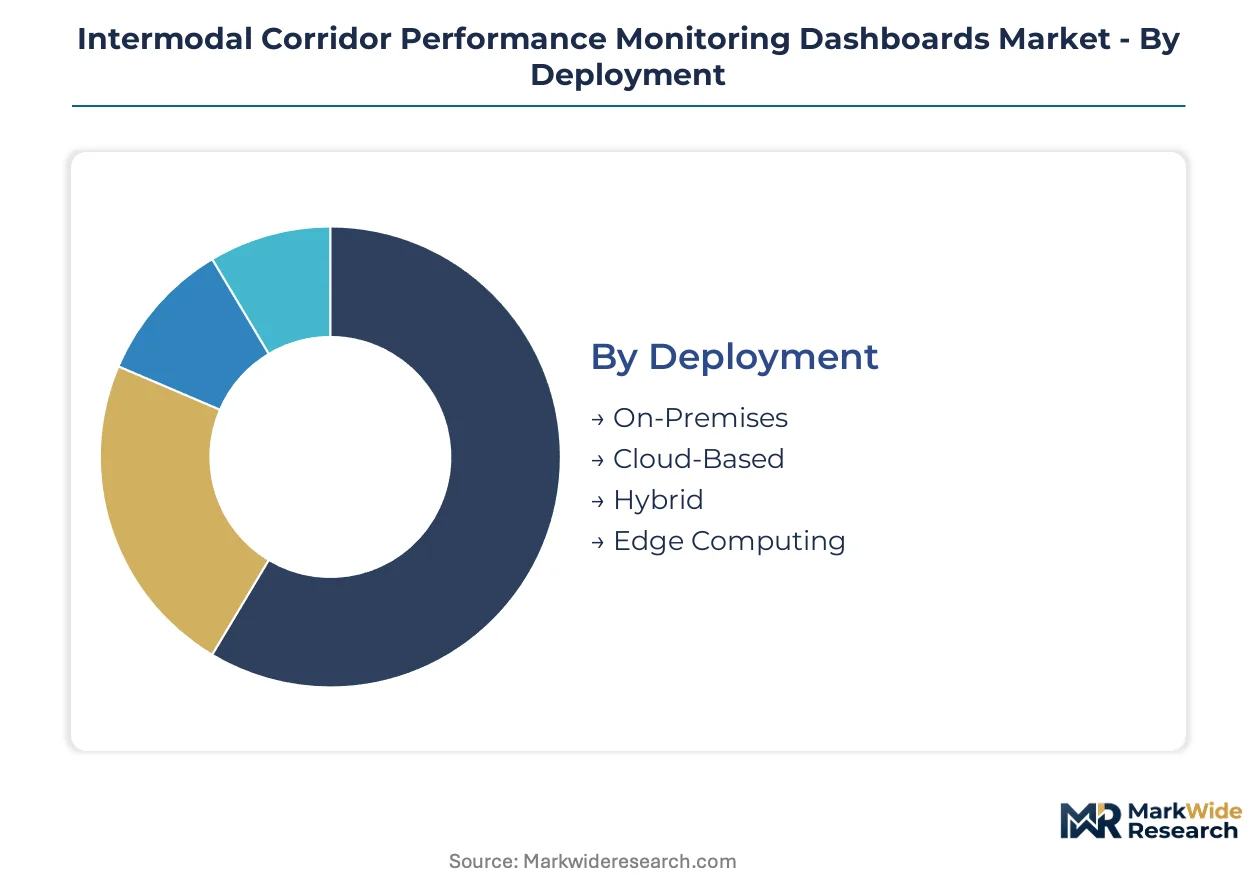
Deployment architecture determines latency tolerance and data sovereignty posture for corridor operators. Solution differentiation concentrates in predictive capabilities versus visualization depth. End-user procurement patterns diverge sharply between asset-heavy rail operators and asset-light freight forwarders.
Deployment:
Customization intensity spans from rigid on-premises cages to elastic cloud fabrics, with hybrid architectures occupying the negotiated middle ground for latency-sensitive corridors.
- Cloud-Based:Elastic compute pools accommodate seasonal freight surges without capital commitment. European operators favor these deployments to satisfy GDPR residency requirements through regional AWS, Azure, and GCP zones. The EU Green Deal's audit trail mandates accelerate cloud migration as operators seek immutable logging infrastructure.
- Edge Computing:Ruggedized gateways process telemetry within 50 milliseconds of sensor generation, enabling autonomous handoff decisions in remote corridor segments. Germany's Rhine-Alpine corridor deploys these nodes where fiber backhaul remains uneconomical. Hardware costs run 3-4x equivalent cloud capacity.
- On-Premises:Captive data centers serve operators with classified defense cargo or those blocking external connectivity for competitive secrecy. Indian Dedicated Freight Corridor deployments favor this model pending domestic cloud maturation.
- Hybrid:Tiered architectures keep sensitive signaling data local while pushing analytics workloads to cloud. North American Class I railroads standardize on this pattern to balance FRA audit requirements with computational flexibility.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Edge Computing.
Solution Type:
Margin pools concentrate in platforms that anticipate failure rather than document it, with visualization commoditizing fastest.
- Predictive Analytics:Machine learning models ingest GPS, EDI, and IoT streams to flag congestion 4-6 hours before cascade failures. Deutsche Bahn compresses infrastructure investment cycles using these tools across the Rhine-Alpine axis. CSRD-aligned carbon forecasting modules command premium pricing in European procurement.
- Real-Time Analytics:Stream processing engines calculate dwell times, velocity consistency, and handoff reliability with sub-second refresh. Mature revenue base with thinning margins as open-source alternatives proliferate.
- Visualization Platforms:Multimodal control towers aggregate rail, truck, and vessel telemetry into unified operational pictures. Kuehne+Nagel and DSV have internalized this functionality, squeezing independent vendors from top-tier accounts.
- Reporting:Scheduled dashboard exports satisfy regulatory documentation requirements. F-Gas Regulation compliance audits drive refresh cycles for refrigerated intermodal operators.
- Alert Systems:Threshold-based notifications trigger dispatcher intervention for dwell time excursions or reefer unit failures. REACH substance restrictions complicate sensor hardware procurement for these modules.
Predictive Analytics commands the steepest expansion trajectory. Real-Time Analytics anchors current revenue concentration.
Use Case:
Application depth correlates with modal complexity, with multimodal handoffs demanding richer instrumentation than single-mode tracking.
- Freight Tracking:GPS and EDI fusion provides location visibility across rail, truck, and vessel legs. Terminal operators in Germany mandate real-time dwell tracking to minimize container idle time during modal transfers.
- Route Optimization:Dynamic pathfinding recalculates corridors based on live congestion, weather, and infrastructure status. Digital twin convergence enables synthetic load scenario testing before committing assets.
- Delay Analysis:Root-cause decomposition identifies systemic failure patterns in handoff protocols. FRA safety investigations leverage these tools for incident reconstruction.
- Capacity Planning:Demand forecasting aligns infrastructure investment with projected freight volumes. India's Eastern and Western DFCs lack mature implementations, creating first-mover openings.
- Asset Utilization:Equipment rotation analytics minimize empty miles and chassis imbalance. Rail operators deploy these modules to optimize locomotive and flatcar deployment.
Freight Tracking absorbs the majority of current deployment spend. Route Optimization is climbing fastest as fuel volatility intensifies.
End User:
Procurement authority fragments between asset owners seeking operational control and intermediaries demanding visibility without infrastructure commitment.
- Freight Forwarders:Asset-light operators license dashboard functionality to maintain shipper relationships without capital deployment. Control tower consolidation pushes largest players toward captive development.
- Rail Operators:Class I railroads integrate telemetry with legacy signaling systems through protocol gateways. Wabtec dominates hardware-integrated deployments across North American corridors.
- Logistics Providers:Third-party operators balance multimodal coordination with shipper-specific reporting requirements. GDPR data residency blocks seamless aggregation when freight crosses into non-EU Balkan corridors.
- Port Authorities:Terminal operators mandate dwell tracking to minimize container idle time and demurrage exposure. Rotterdam and Hamburg anchor European demand concentration.
- Shipping Companies:Vessel operators extend visibility inland through integrated dashboard partnerships. Maersk and MSC pursue control tower consolidation similar to freight forwarders.
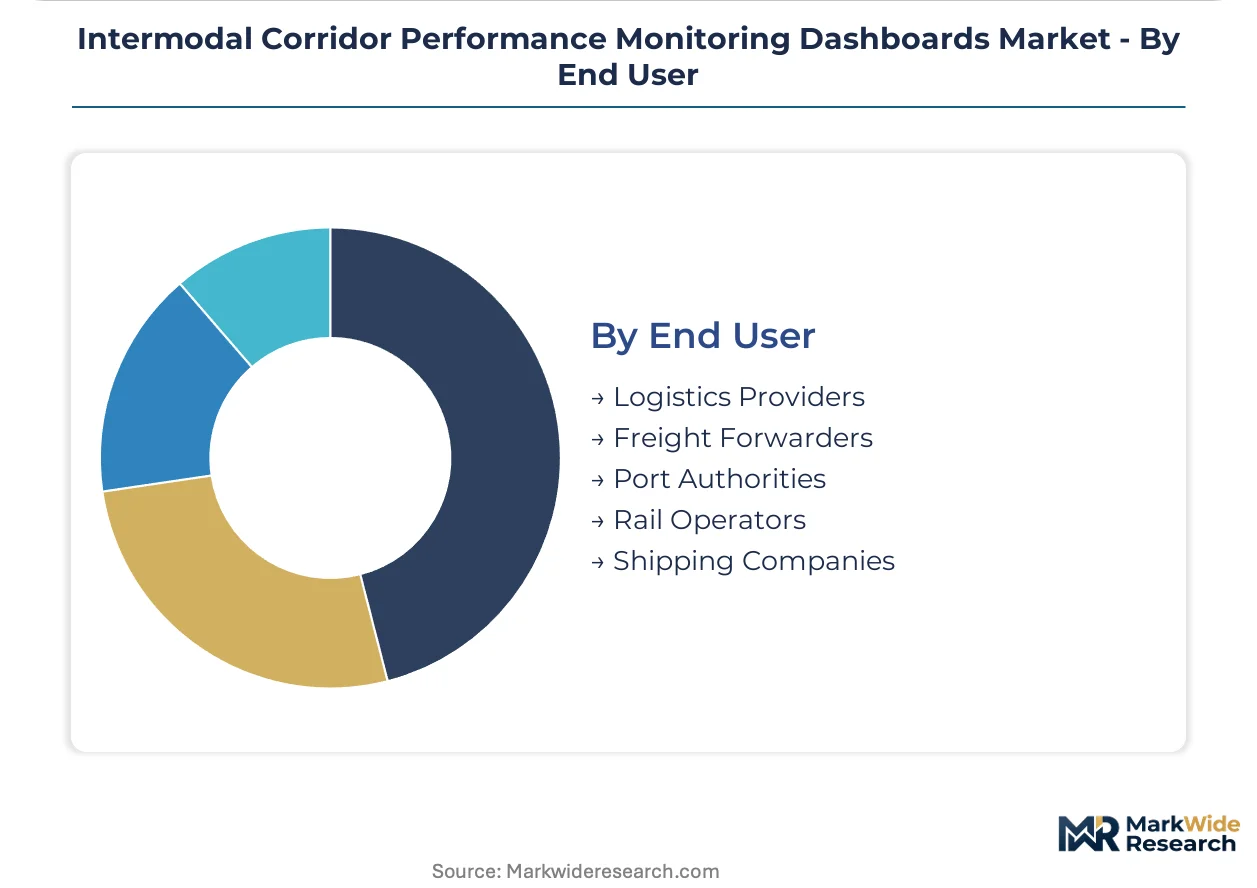
Rail Operators command the deepest per-seat deployment. Freight Forwarders are gaining share fastest as digital forwarding platforms scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Alpine corridor generates the densest freight telemetry flows in Europe, while the United States concentrates Class I railroad deployment capital across Chicago-to-Los Angeles corridors. India's Dedicated Freight Corridors lack mature monitoring infrastructure, creating first-mover openings for dashboard vendors.
Germany
The Rhine-Alpine corridor processes Europe's heaviest container volumes, forcing terminal operators to mandate real-time dwell tracking. The EU Green Deal's emissions transparency mandates accelerate dashboard procurement timelines. Deutsche Bahn's freight division anchors predictive analytics deployment across Baden-Württemberg and Bavaria.
United States
North American Class I railroads integrate telemetry with legacy signaling systems through protocol gateways. The Federal Railroad Administration enforces safety and interoperability standards that shape data collection protocols. Chicago's intermodal terminals concentrate edge computing deployments for autonomous handoff decisions.
India
The Eastern and Western Dedicated Freight Corridors lack mature monitoring infrastructure, creating cloud-native dashboard opportunities. The PLI scheme for logistics infrastructure accelerates capital deployment into corridor digitization. The Delhi-Mumbai Industrial Corridor anchors initial pilot deployments for freight tracking.
Netherlands
Rotterdam's port authority mandates dwell tracking to minimize container idle time and demurrage exposure. GDPR data residency requirements shape cloud deployment architecture for European operators. The Randstad logistics cluster concentrates freight forwarder demand for multimodal visibility platforms.
Japan
Tokyo-Osaka freight corridors demand high-velocity telemetry processing for just-in-time manufacturing supply chains. METI's digital infrastructure investment programs subsidize IoT gateway deployment. The Chubu region around Nagoya anchors automotive parts corridor monitoring.
Intermodal Corridor Performance Monitoring Dashboards Market Competitive Landscape
Top-tier vendors anchor hardware-integrated deployments, while cloud-native specialists compete on predictive analytics capabilities. The market structures around three strategic tiers: rail heritage conglomerates, enterprise software extenders, and logistics visibility pure-plays. Two dominant competitive moves are reshaping positioning: control tower consolidation by freight forwarders absorbing dashboard functionality in-house, and digital twin convergence combining physics-based simulations with live telemetry.
Among rail heritage conglomerates, Wabtec and Siemens Mobility exemplify the hardware-integrated archetype, leveraging signaling infrastructure relationships to dominate corridor deployments. SAP and Oracle occupy the enterprise software extender position, extending ERP data pipelines directly into freight operations. Within the logistics visibility tier, project44 represents the cloud-native approach, competing through API-first architectures and multimodal data fusion.
| Leading Market Players |
|---|
| Wabtec |
| project44 |
| SAP |
| Oracle |
| Hitachi Rail |
| Siemens Mobility |
| Trimble |
| Cognizant |
| Blue Yonder |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's emissions audit mandates gate qualified supply access and premium-tier pricing for dashboard vendors serving European corridors. Operators lacking carbon-accounting module certification face exclusion from Rhine-Alpine procurement cycles, compressing margins for commodity visualization providers while predictive analytics platforms capture pricing power.
Pricing Analysis
Capacity additions in India's Dedicated Freight Corridors are reshaping price floors for cloud-native dashboard deployments. Subscription tiers stratify across predictive, real-time, and basic visualization levels, with CSRD-aligned carbon forecasting commanding the widest spreads. Certification under EU Green Deal audit protocols drives price differentiation more than feature depth. Cost compression in visualization modules intensifies as open-source alternatives proliferate. Freight forwarders exhibit the sharpest price sensitivity; rail operators with captive infrastructure budgets show the least.
Supply Chain Analysis
REACH substance certification gates hardware procurement for sensor manufacturers serving European deployments. Taiwan, Germany, and the United States anchor semiconductor and industrial gateway supply. Dashboard assembly draws from rare earth elements for IoT sensors, specialized ASICs for edge processing, and ruggedized enclosures for rail environments. Single-source vulnerability concentrates in Taiwanese semiconductor fabs. Distribution runs through systems integrators with rail signaling expertise rather than direct vendor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive analytics functionality is expanding margin pools as operators trade up from commoditized visualization, with cloud-native architectures reducing delivery costs for vendors.
For Market Incumbents: Deploy digital twin convergence to lock in infrastructure planning relationships before platform consolidation accelerates. Integrate physics-based corridor simulations with live telemetry to create switching costs for Deutsche Bahn and North American Class I railroads. Absorb edge computing hardware capabilities to offset margin pressure from pure-play cloud competitors. CSRD-aligned carbon reporting modules represent the priority certification investment. For New Entrants and Emerging Players: API-first architectures open direct channels to mid-tier freight forwarders bypassing systems integrator markups. India's Eastern and Western Dedicated Freight Corridors offer the most penetrable geography, lacking mature incumbent relationships. Target cloud-native deployments for port authorities in Rotterdam and Hamburg seeking rapid procurement without legacy integration burdens. White-label predictive modules for logistics providers building captive control towers. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native visibility pure-plays because freight forwarder control tower consolidation is compressing standalone software valuations. The five-to-ten year viability window favors vendors with embedded rail signaling relationships over API-only challengers. Acquisition targets should demonstrate multimodal data fusion capabilities and EU regulatory compliance infrastructure. Watch for inflection when Indian DFC procurement shifts from on-premises to cloud-native specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Module Development | Machine learning congestion forecasting commands premium pricing from Deutsche Bahn and Rhine-Alpine operators. |
| Edge Computing Hardware Integration | Ruggedized gateways for remote corridor segments reduce latency below 50 milliseconds for autonomous handoff decisions. |
| Carbon Accounting Certification | EU Green Deal audit trail compliance gates market access for dashboard vendors serving European freight corridors. |
| Digital Twin Platform Convergence | Physics-based corridor simulations compress infrastructure investment cycles from months to weeks for rail planners. |
| API-First Architecture Deployment | Direct data pipelines bypass systems integrator markups and accelerate procurement for mid-tier freight forwarders. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged corridor operations directors at Class I railroads, terminal managers at Rotterdam and Hamburg port authorities, freight forwarder control tower architects, and IoT platform engineers at rail signaling vendors. Secondary validation incorporated Federal Railroad Administration safety filings, EU Green Deal implementation guidance, EDI protocol specifications from UN/CEFACT, and customs data on industrial gateway imports.
Historical performance metrics anchored projections across the modeling period. Segmentation dimensions included deployment architecture, solution type, use case application, and end-user procurement authority. CAGRs were derived from elasticity modeling of freight volume growth against dashboard penetration rates. Edge computing hardware cost curves and cloud infrastructure pricing trajectories informed deployment mix assumptions.
The model assumes a particular technology adoption path; alternative pathways for edge-to-cloud hybrid architectures would alter the outlook. Forecasts reflect assumptions about EU enforcement timelines for emissions tracking mandates and Indian cloud infrastructure maturation. Deviation in semiconductor supply availability or GDPR data residency interpretation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Automotive V2X Market