
 Smart EV Charger Market | 2026-2036
Smart EV Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Smart EV Charger Market Intelligence
The customer base for smart EV charging is broadening from individual vehicle owners to a diverse set of commercial and fleet operators. ChargePoint Holdings, Inc. leverages its extensive public charging network to serve these new commercial segments. Siemens AG competes by integrating charging hardware with its building management and grid software platforms. Wallbox N.V. specializes in residential and semi-public installations with a focus on user experience.
A smart EV charger is a networked charging station that allows two-way communication between an electric vehicle, the charging operator, and the utility grid. These units enable dynamic load management, remote diagnostics, and variable pricing based on grid conditions, often utilizing connectivity protocols like Wi-Fi or cellular. While AC chargers dominate residential installations, DC Fast Chargers represent the highest value segment for public and fleet charging stations. The development of bidirectional chargers is creating new opportunities for vehicle-to-grid services.
Regulations such as the EU's Corporate Sustainability Reporting Directive (CSRD) and the US Inflation Reduction Act (IRA) create incentives for commercial fleet electrification and smart charging deployment. Concurrently, standards like ISO 15118 ensure interoperability between vehicles and charging infrastructure across different manufacturers. Stakeholders must now decide between pursuing open, interoperable network models or closed, proprietary ecosystems for charging services.
Market Dynamics
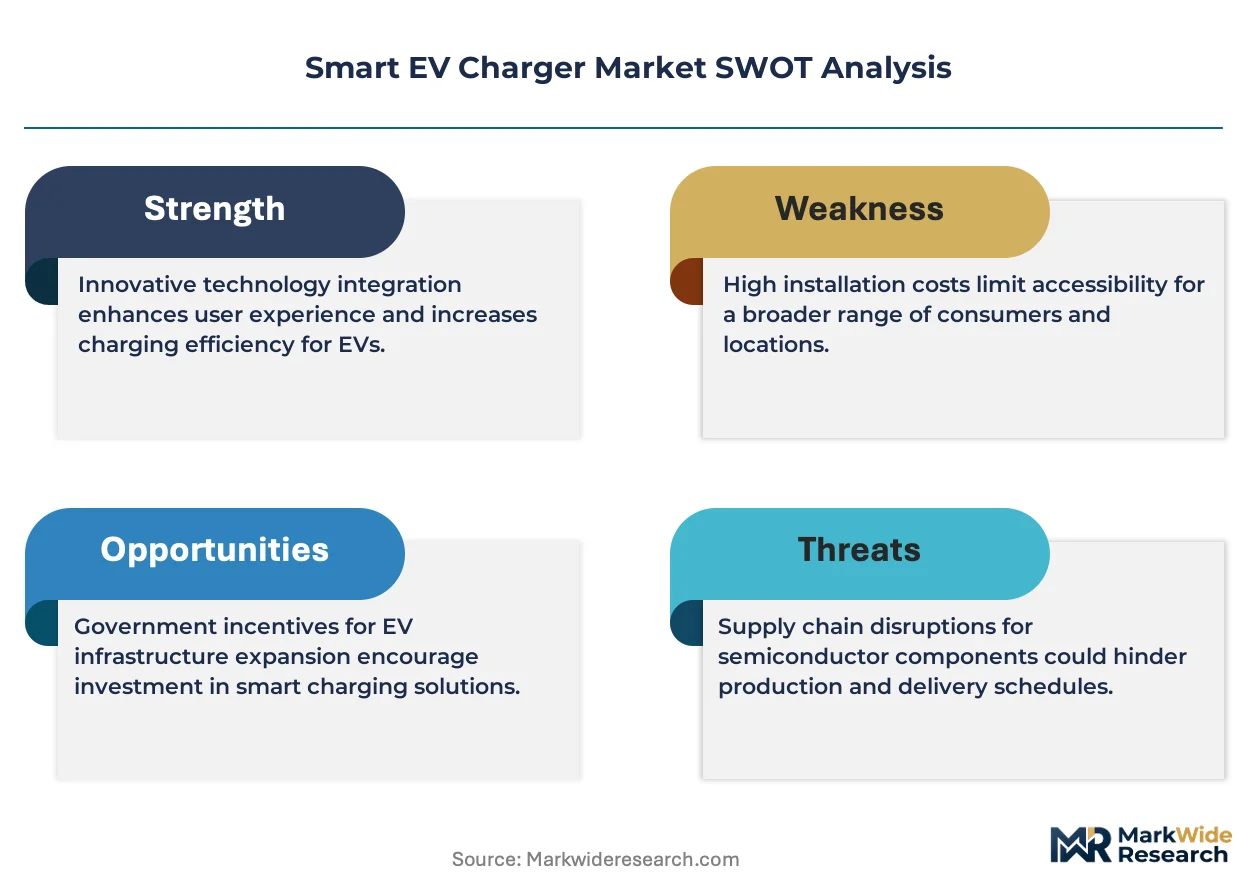
The central force shaping the smart EV charger market is the transition from a hardware-centric, consumer-driven model to a service-oriented, network-based ecosystem. This shift is propelled by regulatory mandates for intelligent charging and the operational demands of commercial fleet electrification, redefining the charger as a managed grid asset rather than a simple appliance.
Growth Catalysts
- Regulatory Mandates:The EU's Alternative Fuels Infrastructure Regulation (AFIR) requires all new publicly accessible chargers to support smart charging capabilities, creating a baseline demand for intelligent, connected hardware across member states.
- Corporate Fleet Electrification:The need for logistics and delivery companies to manage vehicle uptime and minimize energy costs drives demand for networked charging solutions that offer load management, remote monitoring, and integration with fleet telematics. - Bidirectional Charging Technology: The development of Vehicle-to-Grid (V2G) protocols and hardware unlocks new revenue streams for vehicle owners and grid operators through energy arbitrage and ancillary grid services, incentivizing investment in advanced chargers.
Market Restraints
- Grid Infrastructure Limitations:The deployment of high-power DC fast charging clusters is often constrained by the capacity of local electricity distribution networks, requiring costly and time-consuming grid upgrades that can delay projects.
- High Capital Expenditure:The significant upfront cost of DC fast charging hardware, coupled with complex installation and site preparation expenses, presents a substantial financial barrier for public charging operators and smaller businesses.
- Interoperability Gaps:Inconsistencies between different charging network protocols and proprietary payment systems create a fragmented user experience and hinder seamless roaming, which can slow broad consumer and commercial adoption.
Strategic Opportunities
- Software and Service Integration:There is a significant opportunity to bundle charging hardware with energy management software, building automation systems, and utility demand response platforms, creating integrated, high-value solutions for commercial clients.
- Vehicle-to-Grid (V2G) Services:The maturation of bidirectional charging enables new business models focused on selling stored energy from EV batteries back to the grid, providing frequency regulation and peak shaving services for utilities.
- Multi-Unit Dwelling Solutions:Developing scalable, power-managed charging solutions specifically for apartment buildings and condominiums represents a major opportunity, addressing a historically underserved segment of the residential market.
Industry Challenges
- System Integration Complexity:A primary operational hurdle is the complex software integration required to connect chargers with utility back-end systems, roaming platforms, payment processors, and diverse fleet management software, creating technical debt and delays.
- Evolving Compliance Standards:Hardware and software providers face the continuous challenge of updating products to comply with a rapidly changing landscape of standards, including ISO 15118 for communication and various regional cybersecurity requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart EV Charger Market |
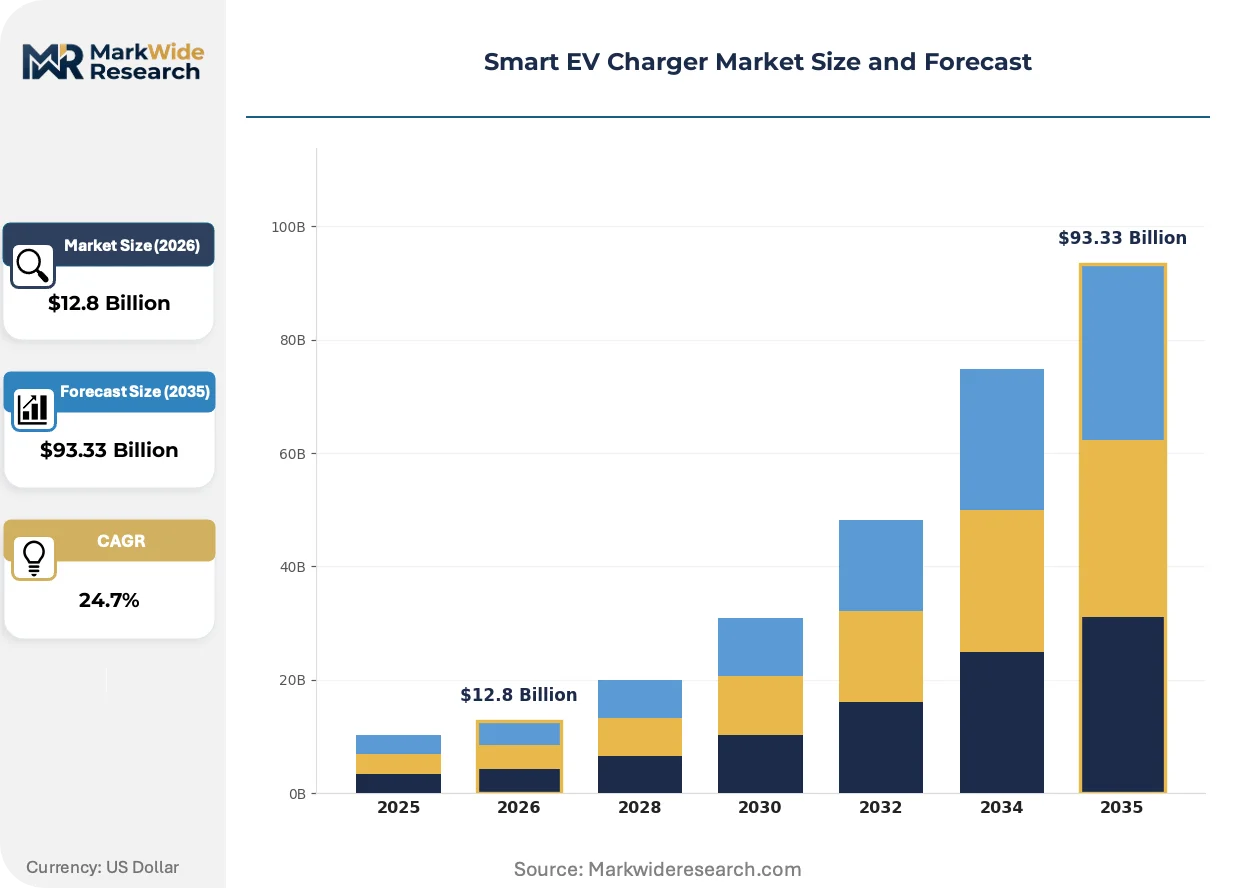
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $93.33 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Technology: AC Chargers, DC Fast Chargers, Wireless Chargers, Bidirectional Chargers Installation Type: Residential, Commercial, Public, Fleet Charging Stations Connectivity Protocol: Wi-Fi, Bluetooth, Zigbee, Ethernet, Cellular End User: Individual Vehicle Owners, Corporate Fleets, Fleet Operators, Car Rental Agencies |
| Companies Covered | Tesla, Inc., ChargePoint Holdings, Inc., ABB Ltd., Siemens AG, Schneider Electric, Eaton Corporation PLC, Wallbox N.V., EVBox Group, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart EV Charger Market Strategic Shifts & Innovations
The market's evolution is defined by the charger’s transformation from a passive electrical device into an intelligent, communicative node on the energy grid. This intelligence is enabling new services, business models, and interactions between vehicles, buildings, and utilities.
Bidirectional charging technology allows for two-way energy flow between an electric vehicle and the power grid. Fleet operators and utilities are the primary adopters in pilot programs to test grid stabilization and energy arbitrage use cases. This capability is unifying the distinct roles of transportation and energy storage, transforming EVs into mobile, distributed assets for the electrical grid.
The European Union's Corporate Sustainability Reporting Directive (CSRD) creates a significant compliance pull for advanced charging infrastructure. Its rules require large companies to provide detailed reports on their energy consumption and carbon footprint, including from their vehicle fleets. Commercial operators are now prioritizing smart charging systems with certified metering and robust data analytics to meet these new disclosure obligations.
A transition toward subscription-based Charging-as-a-Service (CaaS) models is altering equipment acquisition. This approach replaces the large, one-time capital outlay for hardware with a recurring operational fee that includes installation, software, and maintenance. The CaaS model is gaining the most traction in the commercial fleet and public charging sectors in Europe and North America.
Smart EV Charger Market Segmentation
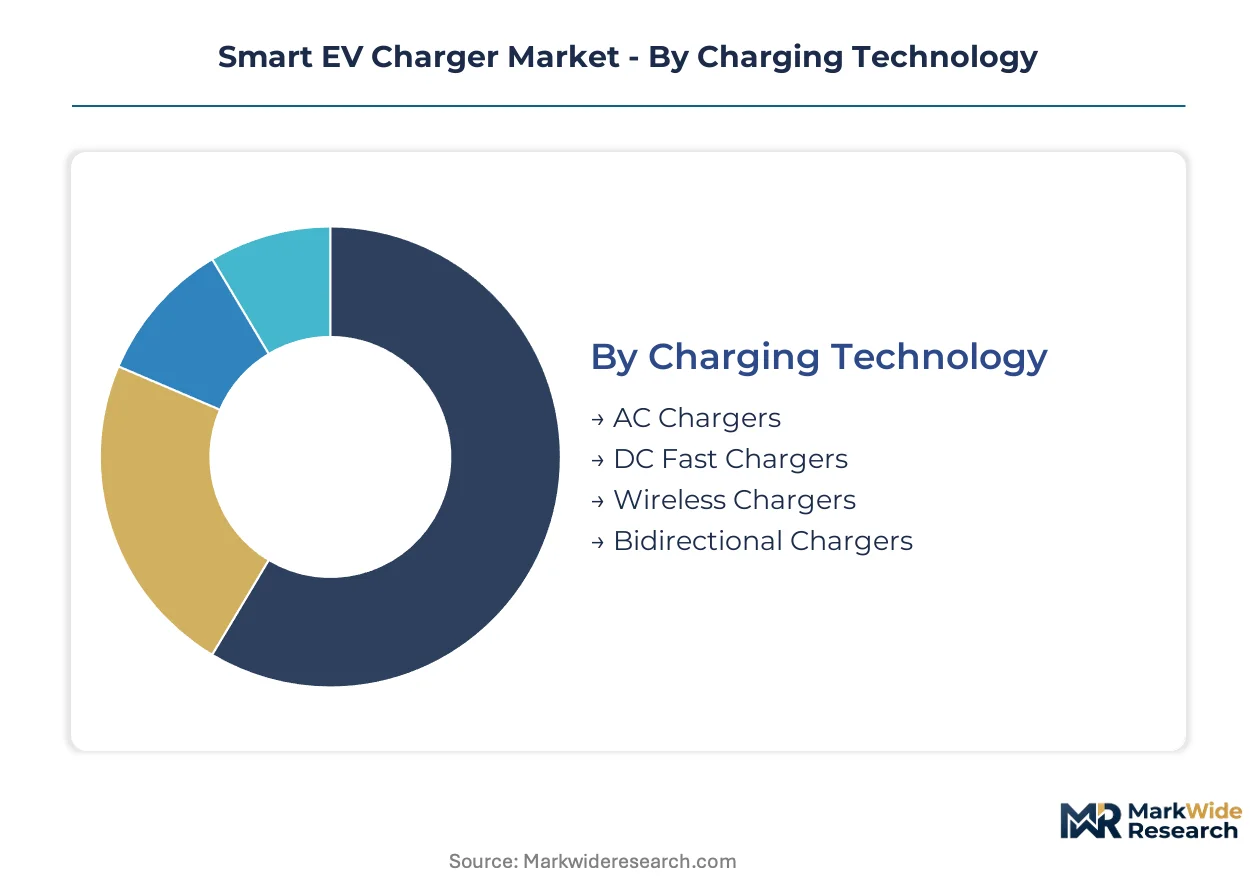
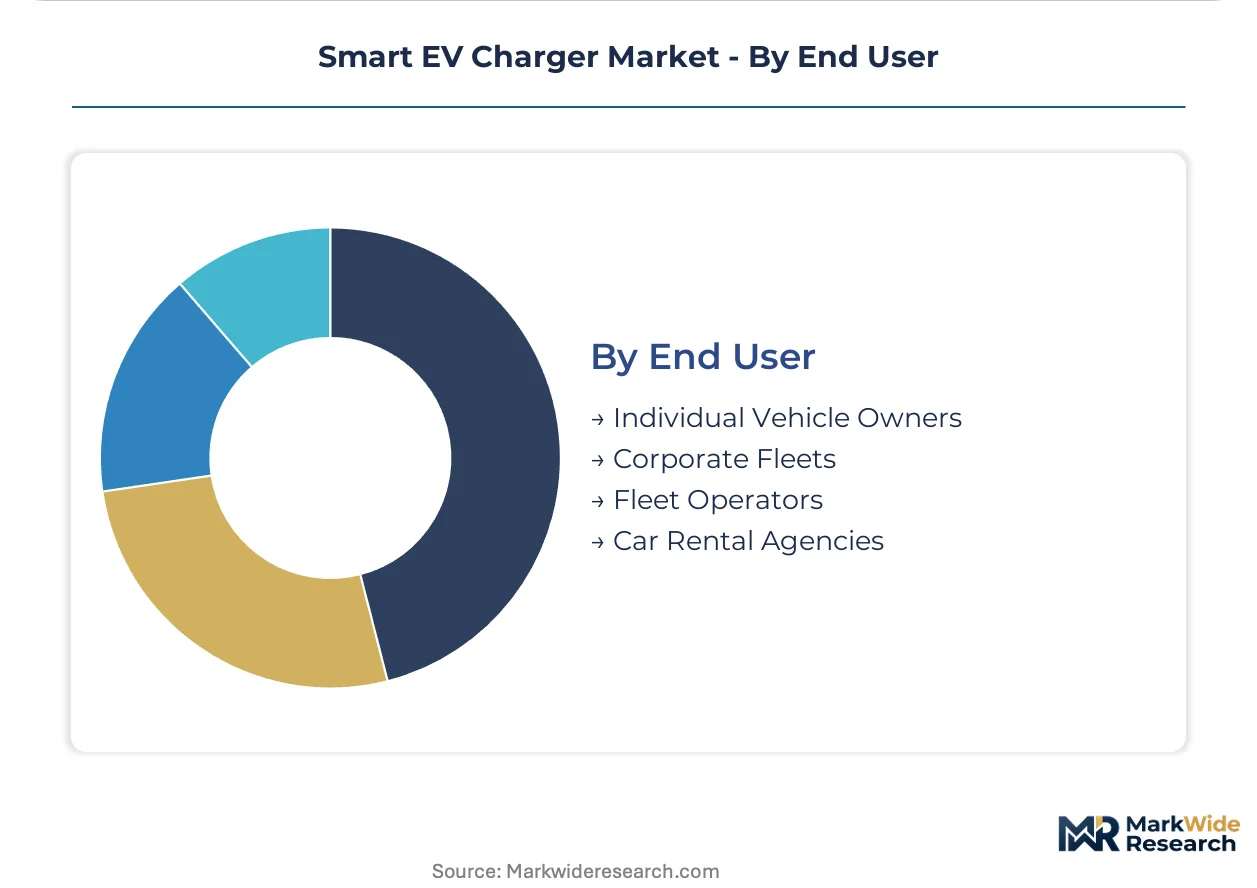
The segmentation of the smart EV charger market reveals distinct operational requirements and technological preferences across various user groups. Understanding these segments is crucial for manufacturers and service providers to tailor solutions that meet specific demand drivers, from charging speed to connectivity needs.
Charging Technology:
The choice of charging technology for smart EV chargers often hinges on the desired charging speed and specific application needs.
- DC Fast Chargers:These units deliver high-power direct current, enabling rapid recharging of electric vehicles in minutes rather than hours. Demand concentrates in public and fleet charging stations across Germany and the US, driven by the critical need for quick turnarounds and efficient grid asset management.
- Bidirectional Chargers:This advanced technology allows for two-way energy flow, enabling electric vehicles to not only draw power from the grid but also feed it back (Vehicle-to-Grid). Corporate fleets and utilities in Europe are primary adopters, leveraging these chargers for energy arbitrage and ancillary grid services.
- AC Chargers:Alternating current chargers dominate residential installations, offering convenient home charging with a strong focus on user experience and integration with smart home systems.
- Wireless Chargers:Utilizing inductive power transfer, these chargers offer a cable-free charging experience, particularly suited for niche applications such as automated parking and specialized fleet depots.
Volume sits with AC Chargers; growth tilts toward Bidirectional Chargers.
ilgences:
The installation type for smart EV chargers is primarily dictated by the user environment and energy management requirements.
- Public:These installations typically feature high-power DC fast chargers, forming high-density networks in urban centers. Demand concentrates in Germany and the US, spurred by programs like the US National Electric Vehicle Infrastructure (NEVI) program.
- Fleet Charging Stations:Designed for commercial logistics and delivery companies, these stations integrate with telematics for load management and remote monitoring. Logistics and delivery companies across Europe and North America drive demand for these managed solutions due to operational efficiency needs.
- Residential:Primarily consisting of AC chargers, these installations serve individual vehicle owners for convenient home charging. Residential installations prioritize ease of use and integration with household energy systems.
- Commercial:This category includes workplaces, retail locations, and semi-public venues, often integrating charging hardware with building management systems for optimized energy use.
The strategic importance of Public installations is rising, while Fleet Charging Stations are experiencing accelerated deployment.
Connectivity Protocol:
The selection of a connectivity protocol for smart EV chargers is driven by the technical requirements for data exchange and network reliability.
- Cellular:This protocol enables wide area network communication, facilitating remote diagnostics, variable pricing, and ubiquitous coverage for charging networks. Public and fleet charging networks across the US and Europe rely on cellular for broad reach and data transmission.
- Ethernet:As a wired local area network solution, Ethernet provides high bandwidth and low latency connectivity for robust system integration. Commercial and multi-unit dwelling installations in Germany and the UK utilize Ethernet for reliable building integration.
- Wi-Fi:A local wireless network option, Wi-Fi is common in residential installations, offering user convenience and integration with home networks.
- Bluetooth:This short-range wireless technology is used for localized control, enabling mobile app integration and proximity-based interactions with charging stations.
- Zigbee:A low-power mesh network protocol, Zigbee is often employed for smart home integration and efficient energy management within residential smart charging ecosystems.
Cellular protocols offer broad reach, whereas Ethernet provides high-reliability connectivity for fixed sites.
End User:
End-user segments for smart EV chargers are differentiated by their operational priorities and scale of charging infrastructure required.
- Corporate Fleets:These entities require managed charging solutions, often integrated with telematics and advanced load management capabilities. Logistics and delivery companies across Europe drive demand, influenced by regulations such as the EU's Corporate Sustainability Reporting Directive (CSRD).
- Individual Vehicle Owners:This segment primarily utilizes residential AC chargers, prioritizing user experience, app control, and cost-effective home charging. Demand from Germany and the US reflects a focus on convenience and energy cost management for personal vehicles.
- Fleet Operators:This category encompasses large-scale charging needs, with a strong focus on vehicle uptime, route optimization, and minimizing overall energy costs.
- Car Rental Agencies:These operators primarily rely on public charging network access and fast charging capabilities for quick vehicle turnarounds, alongside remote monitoring of vehicle state of charge.
Corporate Fleets are driving advanced software integration, while Individual Vehicle Owners prioritize ease of use and cost-effectiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for smart EV charging solutions concentrates in regions with high electric vehicle adoption and robust regulatory support for intelligent grid integration. These regional dynamics are shaped by government incentives, infrastructure development programs, and the specific energy management needs of local grids and commercial operations.
United States
Corporate fleets and individual vehicle owners drive significant demand for smart EV chargers across the United States. The US National Electric Vehicle Infrastructure (NEVI) program mandates intelligent charging capabilities for federally funded public stations. California's dense urban centers are seeing substantial investment in public DC fast charging networks.
Germany
Germany experiences strong demand for smart EV chargers from commercial operators and urban network buildouts. The EU's Alternative Fuels Infrastructure Regulation (AFIR) requires smart charging capabilities for all new publicly accessible chargers. High-density charging networks are rapidly expanding in metropolitan areas such as Hamburg.
China
China's massive electric vehicle market fuels substantial demand for integrated smart charging solutions. Government initiatives support the deployment of advanced charging infrastructure to manage grid stability. Urban hubs like Shenzhen are developing comprehensive smart charging ecosystems with integrated payment systems.
United Kingdom
The United Kingdom sees demand for smart EV chargers across both residential and expanding public networks. UK government policies encourage smart charging capabilities to optimize energy use and grid balancing. Ethernet connectivity is increasingly utilized in commercial and multi-unit dwelling installations in London.
Netherlands
The Netherlands demonstrates significant demand for smart EV charging, driven by high EV penetration rates. National grid operators incentivize smart charging to facilitate dynamic load management and grid stability. Amsterdam's urban environment actively deploys public charging infrastructure, often integrating with local energy management systems.
Smart EV Charger Market Key Industry Players
Established producers occupy the standard tier, offering robust AC and DC charging hardware, while emerging entrants pursue software-defined services and bidirectional charging technologies. The market structure exhibits a tiered consolidation, with large industrial conglomerates competing alongside specialized EV charging infrastructure providers. Key strategic archetypes include hardware manufacturers, software platform developers, and integrated solution providers. Dominant competitive moves involve strategic partnerships for network expansion and portfolio diversification into energy management services.
Integrated solution providers such as Siemens AG and ChargePoint Holdings, Inc. exemplify the convergence of hardware manufacturing with advanced software platforms. Siemens AG, a German industrial conglomerate, anchors its position by integrating charging hardware with comprehensive building management and grid software platforms. ChargePoint Holdings, Inc., a US-based company, leverages its extensive public charging network to serve diverse commercial and fleet segments. Wallbox N.V., a Spanish company, represents a specialist archetype, focusing on residential and semi-public installations with an emphasis on user experience and smart home integration. These companies showcase distinct approaches to market capture, ranging from broad industrial integration to focused consumer solutions.
| Leading Market Players |
|---|
| Tesla, Inc. |
| ChargePoint Holdings, Inc. |
| ABB Ltd. |
| Siemens AG |
| Schneider Electric |
| Eaton Corporation PLC |
| Wallbox N.V. |
| EVBox Group |
| Delta Electronics |
| Others |
Cost & Logistics Intelligence
Bidirectional charging technology, as a key innovation, simultaneously reshapes cost economics and supply concentration within the smart EV charger market. This advanced capability necessitates specialized hardware and sophisticated software, driving up unit costs while centralizing the supply of critical components to fewer, more advanced manufacturers.
Pricing Analysis
Volume concentrates in AC chargers with tighter margins, while DC fast chargers and integrated software solutions command higher margins. Subscription-based Charging-as-a-Service (CaaS) models dominate commercial fleet segments, reducing upfront capital expenditure for operators. Price differentiation stems from advanced software features, Vehicle-to-Grid (V2G) capabilities, and brand reputation. Pricing pressure originates from the high capital expenditure required for DC fast charging infrastructure. Individual vehicle owners exhibit the highest price sensitivity, prioritizing cost-effective home charging solutions.
Supply Chain Analysis
Reverse logistics for smart EV chargers involve managing end-of-life hardware, component recovery, and software updates for legacy units. Geographic supply concentrates in China for electronic components and manufacturing, Germany for industrial electronics, and the US for advanced software platforms. The supply chain sources from critical raw materials like power semiconductors, microcontrollers, and specialized wiring harnesses. Geopolitical disruptions affecting electronics manufacturing hubs present a structural supply chain risk. Distribution for large commercial clients often occurs through direct sales, while residential and smaller commercial segments rely on channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a supply-constrained story, where the limited capacity of local electricity distribution networks props up pricing for integrated grid-aware solutions. Grid infrastructure limitations frequently delay high-power DC fast charging deployments, creating a premium for efficient, scalable systems.
For Market Incumbents:Anchor core hardware offerings by developing comprehensive software platforms that integrate energy management and grid services. Integrate advanced services like V2G to counter new entrants focusing solely on CaaS models, which threaten traditional hardware sales. Invest heavily in R&D for next-generation bidirectional charging to maintain technological leadership. Expand public charging networks strategically in high-density urban centers to leverage existing infrastructure.
For New Entrants and Emerging Players:Energy service providers offer a strong channel for new entrants to penetrate the smart EV charger market. Focus on underserved segments like multi-unit dwellings with scalable, power-managed charging solutions. Target commercial fleets with flexible, subscription-based CaaS models to reduce their upfront capital costs. Prioritize user experience and seamless integration with existing building management systems to differentiate offerings.
For Investors and Strategic Acquirers:Exit pathways concentrate in software-defined charging platforms and V2G technology specialists. Long-term viability remains strong, driven by mandated electrification and grid modernization initiatives across major economies. Acquire specialized V2G technology firms or regional CaaS providers with strong software integration capabilities. Watch for accelerating utility adoption of V2G services as a critical inflection point for investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies charging hardware with grid and building management systems, enhancing solution value. |
| V2G Technology Development | Unlocks new revenue streams through energy arbitrage and ancillary grid services. |
| CaaS Model Expansion | Lowers customer acquisition barriers for commercial and fleet operators by reducing CapEx. |
| Multi-Unit Dwelling Solutions | Addresses a significant underserved residential market segment with scalable power management. |
| Interoperability Standard Adoption | Ensures seamless vehicle-to-charger communication across diverse vehicle and network brands. |
Research Approach
Multi-period observation of EV adoption rates and charging infrastructure deployment anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary interviews involved fleet managers, utility grid operators, EV owners, and charging network developers. Secondary validation drew from regulatory mandates like the EU's AFIR and the US NEVI program, EV sales data, and corporate sustainability reports. This approach ensured robust bottom-up and top-down triangulation of market estimates.
An input-output matrix structured the quantitative analytical framework across the analysis window. Segmentation dimensions modeled included charging technology, installation type, connectivity protocol, and end-user segments. Compound annual growth rates were derived from historical trends and projected market drivers. Key industry-specific forecast inputs included electric vehicle penetration rates and grid modernization investment schedules.
Caveats apply where regulatory shifts or unforeseen technological breakthroughs could materially shift the outlook. Forecasts reflect current market assumptions regarding EV adoption and infrastructure development. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
North America Electric Vehicle Charging Cable Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Copper in Electric Vehicle Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market