
 Electric Vehicle Fast and Rapid Charger Market | 2026-2036
Electric Vehicle Fast and Rapid Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Fast and Rapid Charger Market Insights
The split between premium high-power charging and commodity Level 2 deployment is realigning capital allocation across the value chain. Tesla, Inc. leverages its proprietary Supercharger network to lock in recurring utilization rates at strategic corridor locations. ABB Ltd. anchors its position through industrial-scale manufacturing of liquid-cooled 350 kW dispensers for highway-adjacent sites. ChargePoint, Inc. competes across both tiers, navigating fleet procurement cycles with modular hardware that scales from 50 kW depot installations to 350 kW public hubs.
Electric vehicle fast and rapid chargers are high-power electrical systems that convert grid alternating current to direct current at outputs ranging from 50 kW to 350 kW, delivering energy to battery electric vehicles through conductive connectors with active thermal management. Their primary commercial purpose is to minimize charging downtime for passenger, commercial, and heavy-duty vehicles operating on fixed or variable routes. DC charger deployments now dominate margin pools at highway and urban fast-charging locations where utilization rates justify higher capital intensity, while Level 2 charger volumes sustain broader residential and workplace penetration where dwell times accommodate slower replenishment. Connector type fragmentation persists as a structural friction, with CCS hardware capturing European and North American procurement specifications while CHAdeMO maintains residual fleet commitments in select Asian markets.
The US Department of Transportation and the Federal Energy Regulatory Commission shape demand through National Electric Vehicle Infrastructure formula funding and interconnection queue reforms that accelerate grid-tied charger deployment. Europe's Alternative Fuels Infrastructure Regulation and the F-Gas Directive constrain refrigerant choices in liquid-cooled systems while mandating minimum coverage density along core transport corridors. China's Ministry of Industry and Information Technology enforces GB/T compatibility and dual carbon timelines that filter market access for foreign equipment suppliers. Stakeholders must monitor how evolving grid interconnection standards and carbon accounting rules for embodied charger hardware reshape procurement criteria and supplier qualification thresholds.
Market Dynamics
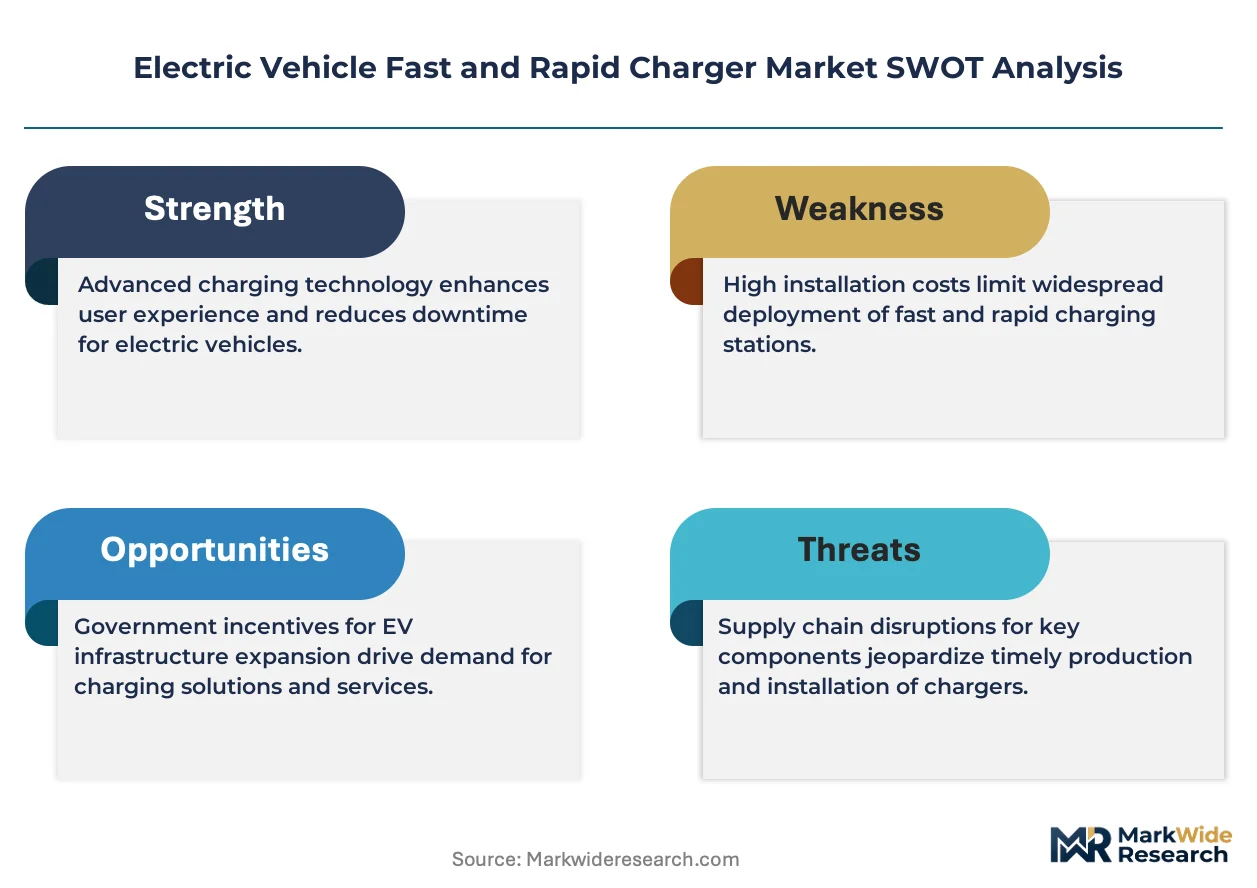
Capital allocation now pivots on charger utilization rates versus hardware margin capture, with fleet operators demanding guaranteed uptime clauses that transfer operational risk from buyers to equipment suppliers and network operators.
Growth Catalysts
- NEV infrastructure mandates:China's MIIT enforces annual installation quotas along national highway corridors, compelling state-grid affiliates to tender multi-thousand-unit dispenser contracts.
- Fleet electrification deadlines:California Air Resources Board mandates require Class 4-8 truck operators to phase out diesel by 2036, accelerating depot fast-charger procurement cycles.
- Liquid-cooled cable systems:Thermal management advances enable sustained 350 kW output without conductor bulk, reducing site footprint requirements by forty percent versus air-cooled predecessors.
Market Restraints
- Silicon carbide supply concentration:Power semiconductor fabrication clusters in Taiwan and Germany create single-source vulnerability for 800V-compatible inverter modules.
- Grid interconnection queues:US Federal Energy Regulatory Commission backlog extends utility service activation timelines to eighteen months for 1 MW+ highway sites.
- Copper price volatility:Conductor raw material swings compress dispenser manufacturing margins when contracts lock in fixed pricing.
Strategic Opportunities
- India's PLI scheme for auto:Production-linked incentives for electric two-wheeler and three-wheeler manufacturing create parallel charging infrastructure demand in tier-two cities.
- Vehicle-to-grid integration:Bidirectional power flow protocols enable fleet operators to monetize battery assets as grid stabilization reserves.
- ISO 15118-20 plug-and-charge:Automated authentication standards eliminate payment friction, reducing dwell-time variance at high-utilization corridor locations.
Industry Challenges
- High-voltage technician scarcity:Qualified electricians certified for 1000V DC installation command premium wages, constraining deployment velocity.
- KBA type-approval timelines:Germany's Federal Motor Transport Authority certification extends hardware launch cycles by nine to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Fast and Rapid Charger Market |
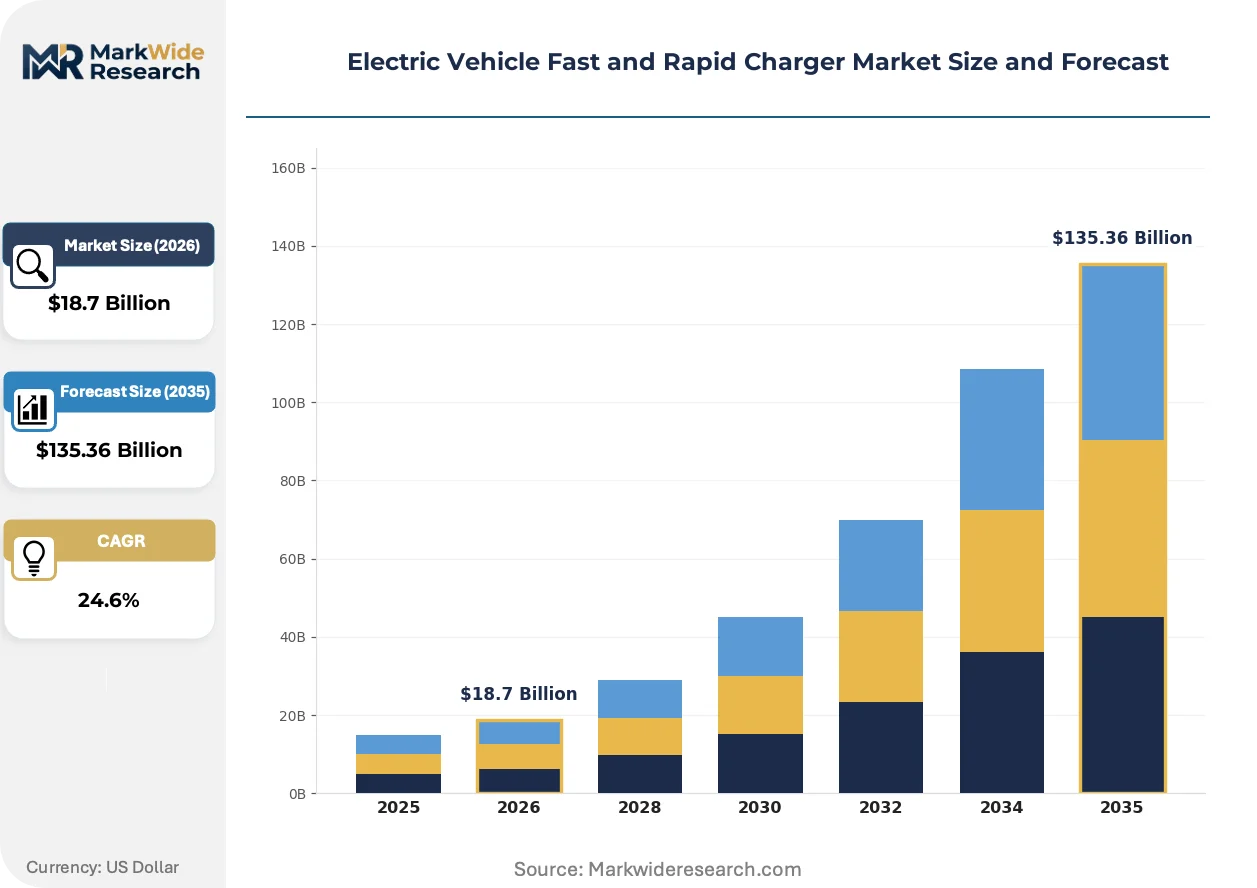
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: AC Charger, DC Charger, Level 2 Charger, Supercharger Installation Type: Commercial, Residential, Public, Fleet Power Rating: 50 kW, 100 kW, 150 kW, 350 kW Connector Type: CHAdeMO, CCS, Tesla, Others |
| Companies Covered | Tesla, Inc., ChargePoint, Inc., ABB Ltd., EVgo Services LLC, Electrify America, Delta Electronics, Inc., EVBox, Eaton, Star Charge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Fast and Rapid Charger Market Trends and Innovations
Hardware differentiation is collapsing into software-defined power management, where over-the-air firmware updates and dynamic load-balancing algorithms now determine competitive positioning more than physical dispenser specifications.
Silicon carbide MOSFETs in power conversion modules slash switching losses and enable compact 350 kW rectifier cabinets. European highway operators specify SiC-based hardware for new corridor tenders. Air-cooled IGBT legacy architectures is overtaking premium procurement specifications only in emerging markets with lower duty-cycle requirements.
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in liquid-cooled systems, forcing suppliers to qualify CO2-based or dielectric fluid alternatives. Equipment manufacturers face recertification costs and supply chain requalification. German KBA documentation requirements extend approval timelines for modified thermal architectures.
Fleet procurement departments now contract for charging-as-a-service rather than capital equipment ownership, transferring utilization risk to network operators. Logistics operators in the Netherlands and California lead this transition. Payment unbundling from hardware acquisition compresses vendor margins while locking in decade-long service revenue streams for integrated providers.
Electric Vehicle Fast and Rapid Charger Market Segmentation
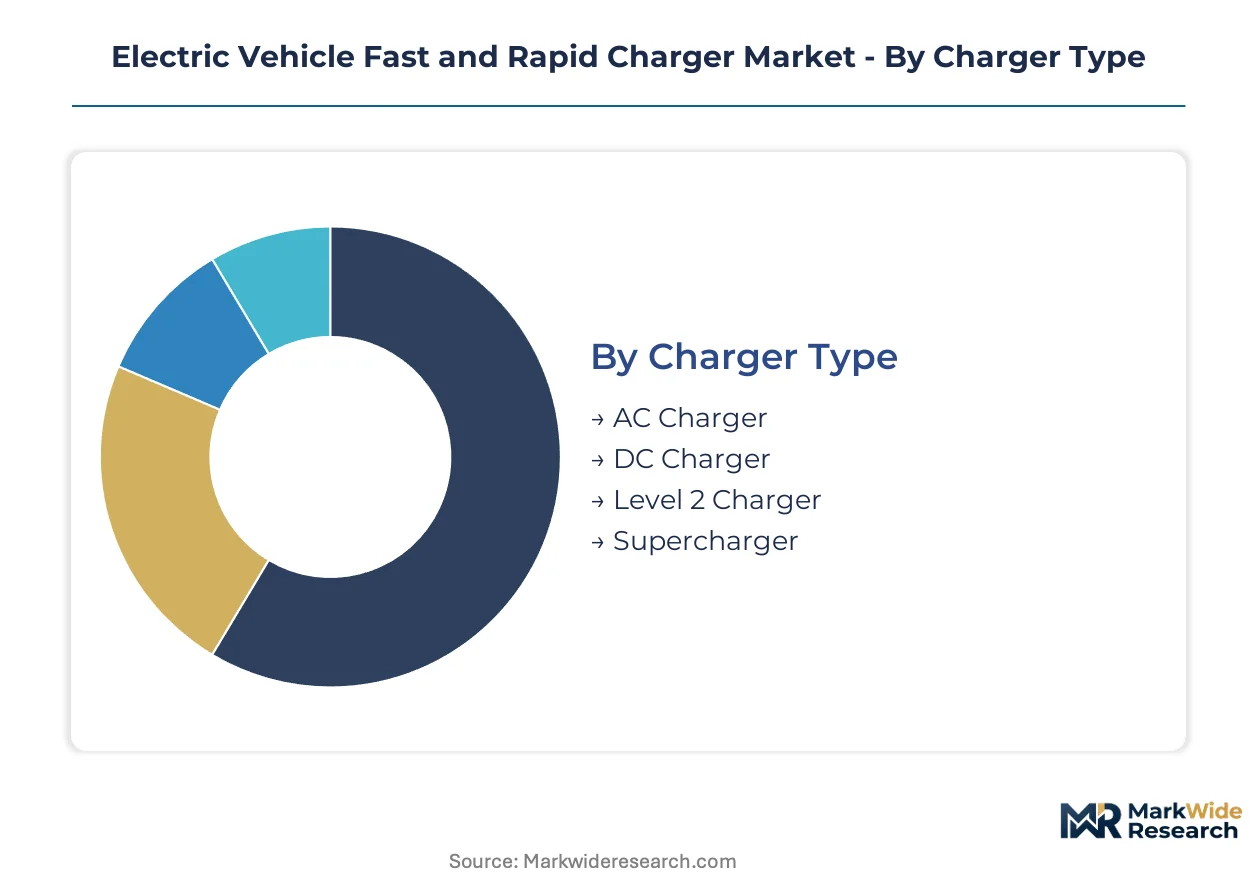
Segmentation in the Electric Vehicle Fast and Rapid Charger Market reveals how capital deployment, regulatory compliance, and utilization economics concentrate across hardware specifications and deployment contexts. Procurement patterns diverge sharply between fleet operators optimizing for total cost of ownership and highway operators maximizing throughput per site.
Charger Type:
Capital intensity varies dramatically across charger architectures, with liquid-cooled DC systems commanding five to eight times the upfront investment of AC alternatives.
- DC Charger:High-power rectifier cabinets convert grid AC to direct current at 50-350 kW outputs, enabling sub-hour replenishment for battery electric vehicles. Fleet depots in California and highway corridors across Germany absorb the majority of procurement volume as operators prioritize minimizing vehicle downtime.
- Supercharger:Proprietary high-power dispensers integrate tightly with network management software to lock in recurring utilization through seamless authentication protocols. Tesla's corridor strategy in the United States and select European markets demonstrates how closed ecosystems capture premium pricing power.
- AC Charger:Onboard vehicle inverters limit output to slower replenishment rates suitable for residential garages and workplace parking with extended dwell periods.
- Level 2 Charger:Mid-power alternating current systems dominate workplace and multi-unit residential installations where overnight or workday charging aligns with vehicle utilization patterns.
Most installed capacity flows through DC Charger deployments. Expansion is steepest in Supercharger networks as proprietary ecosystems consolidate corridor control.
Installation Type:
Customer procurement logic splits between operational expenditure models for fleet operators and capital ownership structures for public network developers.
- Fleet:Depot-based installations serving Class 4-8 trucks and delivery vans require guaranteed uptime clauses and charging-as-a-service contracts that transfer utilization risk to network operators. California's Air Resources Board mandates and Netherlands logistics electrification deadlines concentrate demand in these two markets.
- Public:Highway-adjacent and urban fast-charging hubs prioritize high-throughput locations with 24/7 accessibility and dynamic pricing algorithms. China's MIIT corridor quotas and EU Alternative Fuels Infrastructure Regulation density requirements shape procurement specifications.
- Commercial:Retail and hospitality sites deploy chargers as customer acquisition tools rather than profit centers, accepting lower utilization in exchange for dwell-time extension.
- Residential:Single-family home installations favor lower-power AC units with minimal installation complexity, though multi-unit dwelling penetration remains constrained by electrical infrastructure upgrades.
Contract values concentrate in Fleet installations. Volume growth is climbing the fastest in Public deployments as government funding programs accelerate corridor buildout.
Power Rating:
Site electrical infrastructure requirements and vehicle battery acceptance rates determine viable power tiers for specific deployment contexts.
- 350 kW:Liquid-cooled cable systems enable sustained high-output delivery that reduces heavy-duty truck charging sessions to under forty-five minutes. European highway tenders and select US interstate corridors specify this tier for commercial vehicle compatibility.
- 150 kW:Mid-high power output matches current-generation passenger electric vehicle battery acceptance curves without requiring full site electrical upgrades.
- 100 kW:Entry-level fast charging serves urban locations with constrained grid connections and secondary corridor routes with moderate traffic density.
- 50 kW:Legacy fast-charging specification now deployed primarily in emerging markets and fleet depot settings with predictable dwell schedules.
Procurement volume clusters at 150 kW for passenger vehicle optimization. The steepest expansion trajectory belongs to 350 kW as heavy-duty electrification mandates harden.
Connector Type:
Regional standardization and vehicle fleet composition lock procurement decisions into specific hardware specifications with limited interoperability.
- CCS:Combined Charging System hardware dominates European and North American procurement specifications, with dual-cable dispensers supporting both CCS1 and CCS2 variants for cross-border compatibility.
- CHAdeMO:Japanese-origin standard maintains residual fleet commitments across select Asian markets and early electric vehicle adopter segments requiring backward compatibility.
- Tesla:Proprietary connector format transitioning toward North American Charging Standard designation, with network opening requirements in the United States pressuring multi-connector dispenser configurations.
- Others:China's GB/T standard and emerging regional specifications serve protected domestic markets with limited foreign equipment access.
CCS connectors carry the majority of new installed capacity. GB/T deployments are expanding most quickly within China's protected procurement environment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Germany's automotive belt and China's Yangtze River Delta anchor charger hardware development. Procurement decisions concentrate where regulatory mandates intersect with manufacturing scale.
United States
Fleet electrification deadlines and highway corridor buildout drive procurement volume. The Federal Energy Regulatory Commission interconnection queue reforms compress utility service timelines for 1 MW+ sites. California's Central Valley logistics hubs absorb depot charging contracts as CARB mandates harden.
China
State-grid affiliates tender multi-thousand-unit dispenser contracts under MIIT installation quotas. GB/T connector standardization filters market access toward domestic suppliers. Shenzhen and Shanghai manufacturing clusters produce liquid-cooled 350 kW systems for highway corridor deployment.
Germany
Trans-European corridor density requirements concentrate investment in interoperable 350 kW hubs. KBA certification timelines extend hardware launch cycles by nine to fourteen months. Baden-Württemberg industrial zones host power electronics fabrication for SiC-based rectifier modules.
Netherlands
Logistics operators contract charging-as-a-service rather than capital equipment ownership. EU Alternative Fuels Infrastructure Regulation shapes procurement specifications for port-adjacent sites. Rotterdam harbor districts pilot bidirectional power flow protocols for fleet grid stabilization.
India
PLI scheme incentives for electric two-wheeler manufacturing create parallel charging demand in tier-two cities. Central Electricity Authority standards govern grid interconnection for 50 kW+ installations. Tamil Nadu and Karnataka industrial corridors attract dispenser assembly investments.
Electric Vehicle Fast and Rapid Charger Market Competitive Landscape
Top-tier vendors anchor proprietary network control, while mid-tier equipment fabricators compete on modular hardware specifications. The market structures around three distinct competitive tiers: integrated network operators, industrial-scale manufacturers, and regional system integrators. Dominant moves include strategic partnerships between network developers and fleet operators, plus backward integration into power semiconductor sourcing.
Within the integrated network tier, Tesla, Inc. and ChargePoint, Inc. exemplify divergent ecosystem strategies. Tesla occupies a position as a closed-system anchor with proprietary connector protocols and captive utilization rates. ChargePoint represents the open-network archetype, competing across both fleet depot and public highway segments with modular hardware platforms. ABB Ltd. anchors the industrial-manufacturing tier, supplying liquid-cooled dispenser systems to third-party network operators and highway concessionaires.
| Leading Market Players |
|---|
| Tesla, Inc. |
| ChargePoint, Inc. |
| ABB Ltd. |
| EVgo Services LLC |
| Electrify America |
| Delta Electronics, Inc. |
| EVBox |
| Eaton |
| Star Charge |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement departments demanding charging-as-a-service contracts rather than capital equipment ownership are compressing upfront hardware margins while locking network operators into decade-long service revenue streams. This unbundling forces manufacturers to absorb utilization risk and recalibrate pricing models around guaranteed uptime clauses rather than unit economics.
Pricing Analysis
The bundled-versus-unbundled service split now dominates pricing architecture across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled 350 kW systems with full maintenance from air-cooled mid-power units and basic depot installations. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because fleet operators negotiate volume guarantees. Commercial retail sites show highest price sensitivity; highway corridor operators show lowest due to throughput optimization priorities.
Supply Chain Analysis
Regional distribution centers in Germany's Baden-Württemberg industrial zone and China's Yangtze River Delta manufacturing clusters anchor hub-and-spoke patterns for power electronics and dispenser assembly. Silicon carbide MOSFETs, liquid-cooled cable assemblies, and high-voltage rectifier cabinets draw from Taiwan, Germany, and China respectively. Single-source vulnerability for 800V-compatible inverter modules concentrates fabrication risk. Distribution runs through state-grid affiliates in China and specialized EV infrastructure distributors in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturing in China's protected procurement environment versus selling into Europe's KBA-certified premium tier captures a regulatory-driven margin spread.
For Market Incumbents: Anticipate margin compression from fleet charging-as-a-service contracts by deepening backward integration into silicon carbide sourcing and securing captive supply of power semiconductors. Defensive consolidation through acquisition of regional system integrators with established utility interconnection relationships neutralizes emerging entrant threats.
For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass incumbent distributor networks and accelerate pilot-to-scale conversion timelines. White-space targets include India's tier-two city two-wheeler charging and bidirectional vehicle-to-grid integration for Dutch logistics operators. The most penetrable segment is fleet depot charging with guaranteed uptime service models.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated manufacturers possessing in-house SiC module fabrication and established KBA certification pathways. Long-term viability hinges on software-defined power management capabilities and dynamic load-balancing algorithms. The signal to watch is F-Gas Regulation recertification timelines for CO2-based thermal systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Sourcing | Captive supply of power semiconductors insulates margins from Taiwan-Germany fabrication concentration. |
| Charging-as-a-Service Platform Launch | Fleet operators in California and Netherlands transfer utilization risk to network operators through subscription models. |
| KBA Certification Fast-Track Investment | Germany's nine-to-fourteen-month approval timelines create barrier to entry for uncertified competitors. |
| Bidirectional V2G Protocol Development | Rotterdam harbor pilots monetize fleet battery assets as grid stabilization reserves under EU AFIR frameworks. |
| CO2-Based Thermal System Recertification | F-Gas Regulation phase-down forces qualification of dielectric fluid alternatives with extended approval cycles. |
Research Methodology
Bottom-up fleet operator demand modeling reconciled against top-down dispenser manufacturing capacity tracking forms the analytical core of this study. Primary interviews with network development executives, fleet procurement managers, utility interconnection specialists, and power electronics fabrication engineers combine with secondary validation from MIIT installation quota disclosures, KBA type-approval registries, FERC interconnection queue data, and EU AFIR corridor density mandates.
Input-output matrix framing maps charger power ratings against installation types and connector standards across the projection horizon. Segmentation dimensions include charger architecture, deployment context, power tier, and regional regulatory cluster. CAGRs derive from installed base penetration curves and fleet electrification mandate compliance schedules. Forecast inputs incorporate silicon carbide supply constraints and grid interconnection timeline distributions.
Copper price volatility, KBA certification delays, and MIIT policy recalibration are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Battery Swapping Charging Infrastructure Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle AC Charging Pile Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
Combined Charging System Market