
 Global Solar Battery Charger Market | 2026-2036
Global Solar Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Battery Charger Market Outlook
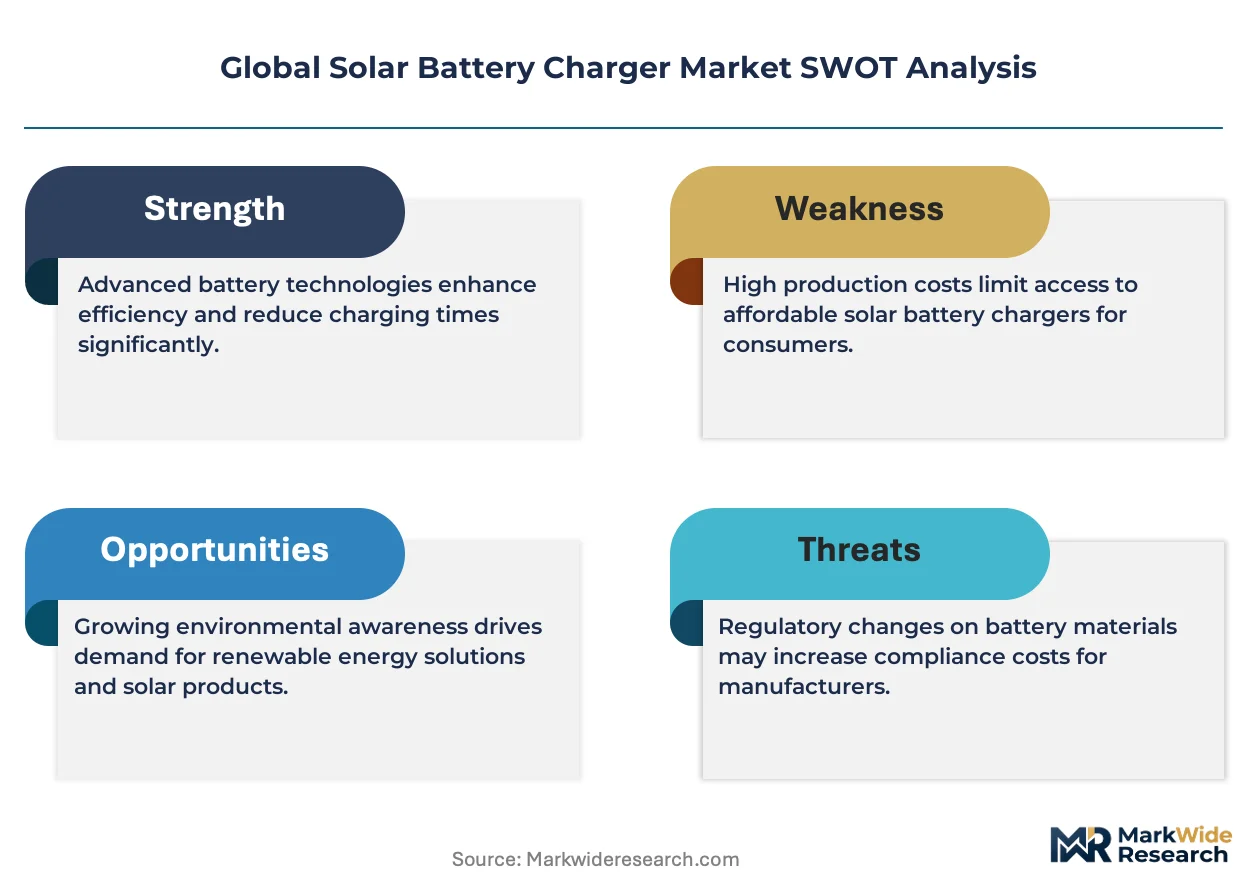
Photovoltaic engineering talent scarcity is bifurcating the competitive landscape between integrated manufacturers and assembly-only competitors. Goal Zero leverages captive R&D in Utah to sustain premium positioning across portable charger lines. Renogy anchors its cost structure through direct-to-consumer channel control in North American fixed installation segments. EcoFlow differentiates via power electronics specialization in solar generator systems above 50W output.
A solar battery charger converts photovoltaic energy into stored electrical capacity through integrated charge controllers and lithium or lead-acid battery banks, typically achieving 18-22% panel efficiency in monocrystalline configurations and serving primary purposes in off-grid power delivery and emergency backup. Portable chargers dominate unit volumes among outdoor enthusiasts and residential users seeking mobile energy independence. Fixed installations command stronger margin pools in commercial and industrial applications where 20W-50W and above-50W capacity bands justify higher upfront capital. Thin-film technology segments face pressure from bifacial module gains in integrated solar kits where rear-side albedo capture boosts total energy yield.
The US Federal Communications Commission governs electromagnetic emissions from smart-charging circuitry, while the EPA Energy Star program shapes consumer efficiency expectations for residential-grade equipment. India's BIS mandates safety testing for lithium-based storage imports, directly affecting market access timelines for foreign suppliers. China's Ministry of Ecology and Environment enforces dual carbon goals that accelerate domestic thin-film manufacturing consolidation. Stakeholders must monitor evolving certification reciprocity between national regulators as product portability blurs traditional geographic market boundaries.
Market Dynamics
Photovoltaic engineering talent scarcity is bifurcating the competitive landscape between integrated manufacturers and assembly-only competitors, with captive R&D capabilities determining margin capture across portable and fixed installation segments.
Growth Catalysts
- Lithium-ion cell cost compression:Battery pack economics are improving as gigafactory scale effects propagate through supply chains, enabling sub-50W portable chargers to reach price points accessible to mass-market outdoor enthusiasts.
- India's BIS certification push:Mandatory safety testing for lithium-based storage imports is concentrating demand among certified suppliers, accelerating formalization of previously fragmented rural electrification procurement.
- Bifacial module gains:Rear-side albedo capture in integrated solar kits is displacing thin-film alternatives in above-50W fixed installations where total energy yield justifies higher upfront capital.
Market Restraints
- Polysilicon supply concentration:China's Ministry of Ecology and Environment dual carbon goals are accelerating domestic manufacturing consolidation, creating input cost volatility for non-integrated assemblers dependent on spot markets.
- Photovoltaic conversion ceiling:Monocrystalline configurations face theoretical efficiency limits near 26%, compressing differentiation potential among panel suppliers competing on performance metrics alone.
- Lead-acid substitution pressure:Legacy battery chemistry remains entrenched in price-sensitive rural segments across South Asia, slowing lithium penetration despite superior cycle life.
Strategic Opportunities
- India's rural electrification gaps:Off-grid segments in Bihar, Uttar Pradesh, and Rajasthan present concentrated demand for sub-20W portable chargers where grid extension remains economically unviable.
- Smart-charging circuitry integration:FCC electromagnetic emissions governance is creating certification-driven preference shifts toward integrated power electronics that combine solar input, battery management, and DC output in single enclosures.
- Direct-to-consumer channel control:North American fixed installation segments are witnessing disintermediation of traditional electrical distributors as manufacturers deploy proprietary e-commerce platforms with embedded sizing tools.
Industry Challenges
- Power electronics specialization deficit:MPPT algorithm development and GaN switching expertise reside in limited talent pools concentrated in Utah, Shenzhen, and Munich engineering clusters.
- Multi-jurisdiction certification timelines:Reciprocity gaps between India's BIS, China's GB standards, and US FCC testing protocols extend product launch cycles for portable designs targeting cross-border sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Battery Charger Market |
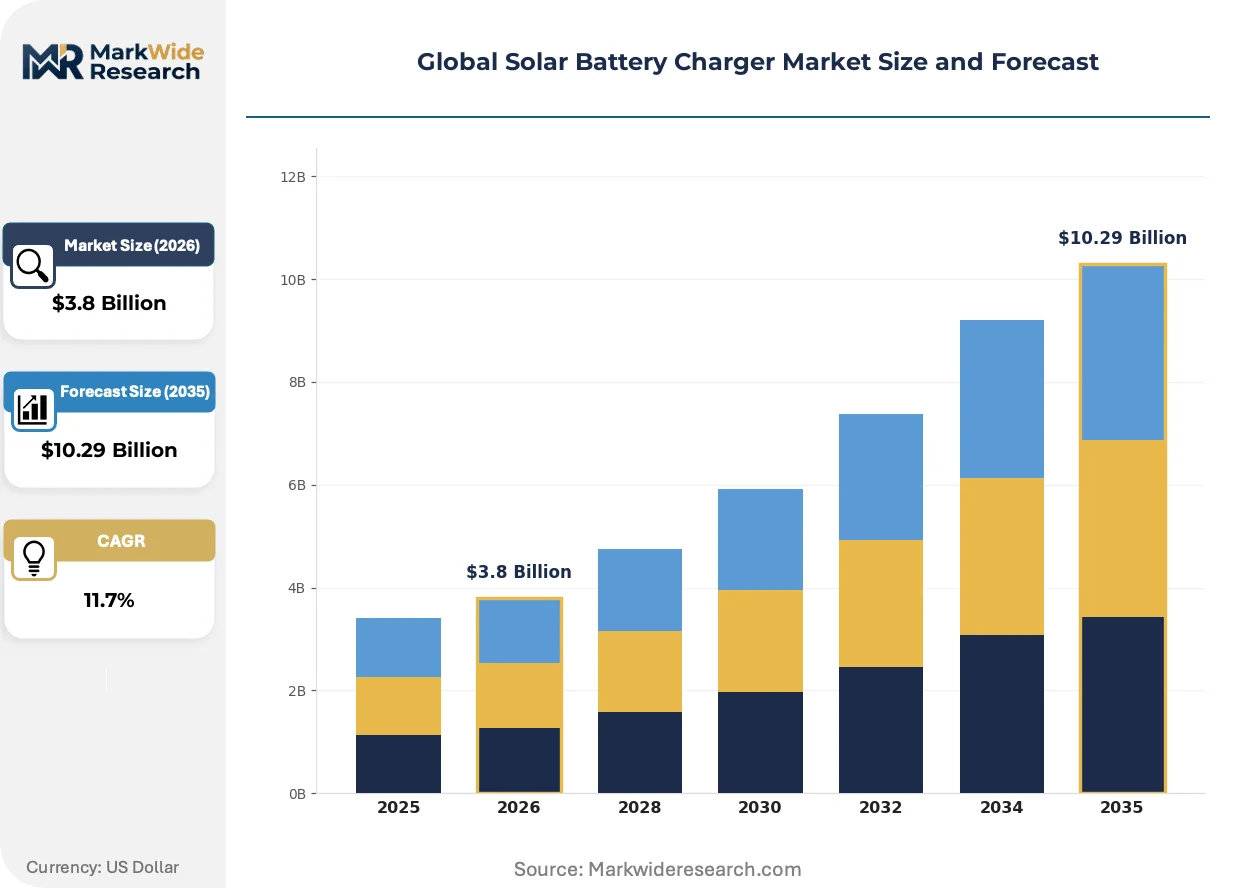
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Fixed Installations, Integrated Solar Kits, Solar Generator Systems End User: Residential Users, Commercial Users, Outdoor Enthusiasts, Industrial Applications Charging Capacity: 5W-10W, 10W-20W, 20W-50W, Above 50W Technology: Photovoltaic Cells, Thin-Film Technology, Bifacial Modules, Solar Films |
| Companies Covered | Anker Innovations, Goal Zero, EcoFlow, Jackery, Renogy, Voltaic Systems, RavPower, BioLite, Solar Technology International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Battery Charger Market Strategic Shifts
Active materials research and power semiconductor advances are compressing form factors while expanding output capabilities, reshaping competitive positioning across the capacity spectrum from pocket-sized emergency units to residential backup systems.
Gallium nitride switching technology is replacing silicon MOSFETs in DC-DC conversion stages, enabling charge controllers to operate at higher frequencies with reduced thermal losses. Marine and aviation backup power buyers are adopting GaN-based designs for weight-critical applications. The technology is miniaturizing enclosure volumes by 40-60% compared to conventional silicon architectures while maintaining equivalent power throughput.
EPA Energy Star program efficiency benchmarks are tightening standby power consumption limits for residential-grade equipment, forcing redesigns of always-on monitoring circuitry. Manufacturers serving North American fixed installation segments are integrating low-power microcontrollers to maintain certification eligibility. Above-50W solar generator systems face the most stringent compliance testing timelines as the program phases in updated measurement protocols.
Outdoor enthusiasts are migrating from retail big-box purchases toward manufacturer-direct subscriptions bundling hardware with cloud-based energy monitoring. Renogy and EcoFlow have deployed mobile applications capturing usage telemetry to drive accessory attach rates and warranty renewals. This behavioral shift is most visible in the US and Australian markets where cellular connectivity enables real-time panel performance optimization.
Global Solar Battery Charger Market Segmentation
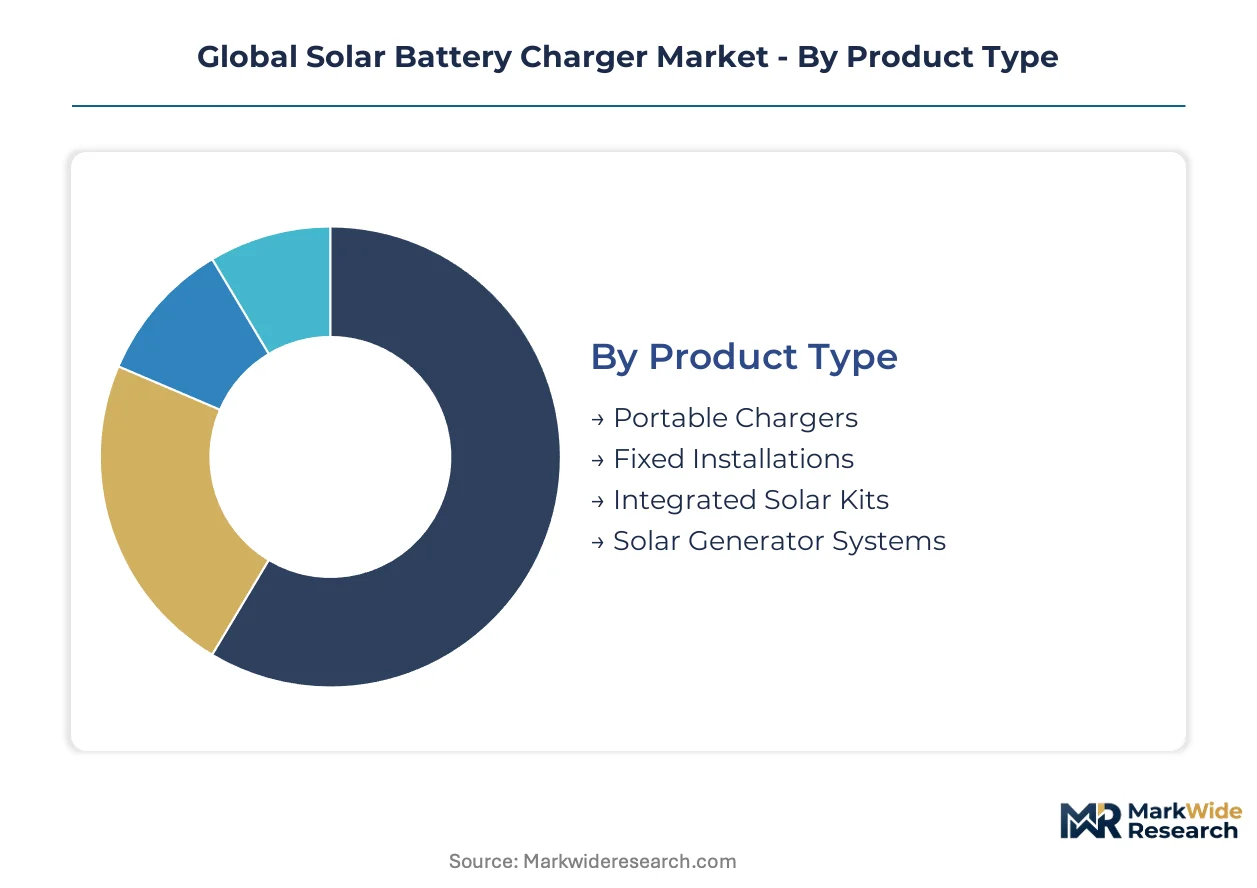
Solar battery charger segmentation reveals how channel strategies bifurcate between impulse retail for portable units and project-driven procurement for fixed installations. Understanding these flow patterns clarifies where margin pools concentrate versus where volume scales.
Product Type:
Portable chargers move through outdoor retail and direct-to-consumer channels, while fixed installations route through electrical distributors and EPC contractors with embedded financing.
- Portable Chargers:Pocket-sized units integrating monocrystalline panels with lithium-ion banks, typically 5W-20W output. Demand concentrates among US and Australian outdoor enthusiasts where cellular-enabled energy monitoring drives subscription attach rates. Lithium cell cost compression is accelerating mass-market accessibility.
- Fixed Installations:Permanently mounted arrays with external battery housing, common in 20W-50W and above-50W configurations. Commercial and industrial buyers in Germany and Japan prioritize these for backup power where grid reliability concerns justify upfront capital. Bifacial module integration is displacing legacy thin-film alternatives.
- Integrated Solar Kits:Pre-wired panel-controller-battery combinations targeting DIY residential installation.
- Solar Generator Systems:All-in-one power stations above 50W with AC inverter output, popular in California and Texas residential backup segments.
Portable chargers dominate installed base. Fixed installations are where expansion concentrates.
End User:
Customer type determines pricing power, with industrial buyers commanding volume discounts and residential segments absorbing premium positioning.
- Residential Users:Homeowners purchasing backup power or off-grid primary supply, typically in 10W-50W capacity bands. Demand clusters in Florida and Arizona where hurricane preparedness and grid instability drive procurement. EPA Energy Star efficiency benchmarks shape product selection criteria.
- Outdoor Enthusiasts:Campers, RV owners, and remote workers prioritizing mobility over capacity. This segment in the US and Canada is migrating from retail big-box toward manufacturer-direct subscriptions bundling hardware with cloud monitoring.
- Commercial Users:Small businesses and remote facilities requiring reliable off-grid power.
- Industrial Applications:Mining, telecom, and agricultural operations with 24/7 power requirements.
Residential users anchor volume. Outdoor enthusiasts are climbing the fastest in revenue per unit terms.
Charging Capacity:
Capacity bands align with use-case intensity, from pocket emergency units to whole-building backup systems.
- 5W-10W:Emergency phone charging and LED lighting, dominant in rural India where BIS-certified lithium imports are concentrating supply among formal vendors. Uttar Pradesh and Bihar procurement programs favor this band for unelectrified households.
- 10W-20W:Small appliance and multiple device charging, common in camping and recreational vehicle applications.
- 20W-50W:Mid-range residential and commercial backup where GaN switching technology is compressing enclosure volumes by 40-60%. Germany's residential segment shows strongest uptake here.
- Above 50W:Whole-building backup and industrial primary power. Japan's METI efficiency standards and California's SGIP incentives are accelerating adoption where total cost of ownership calculations favor lithium over lead-acid.
5W-10W commands unit volume. Above 50W captures margin concentration.
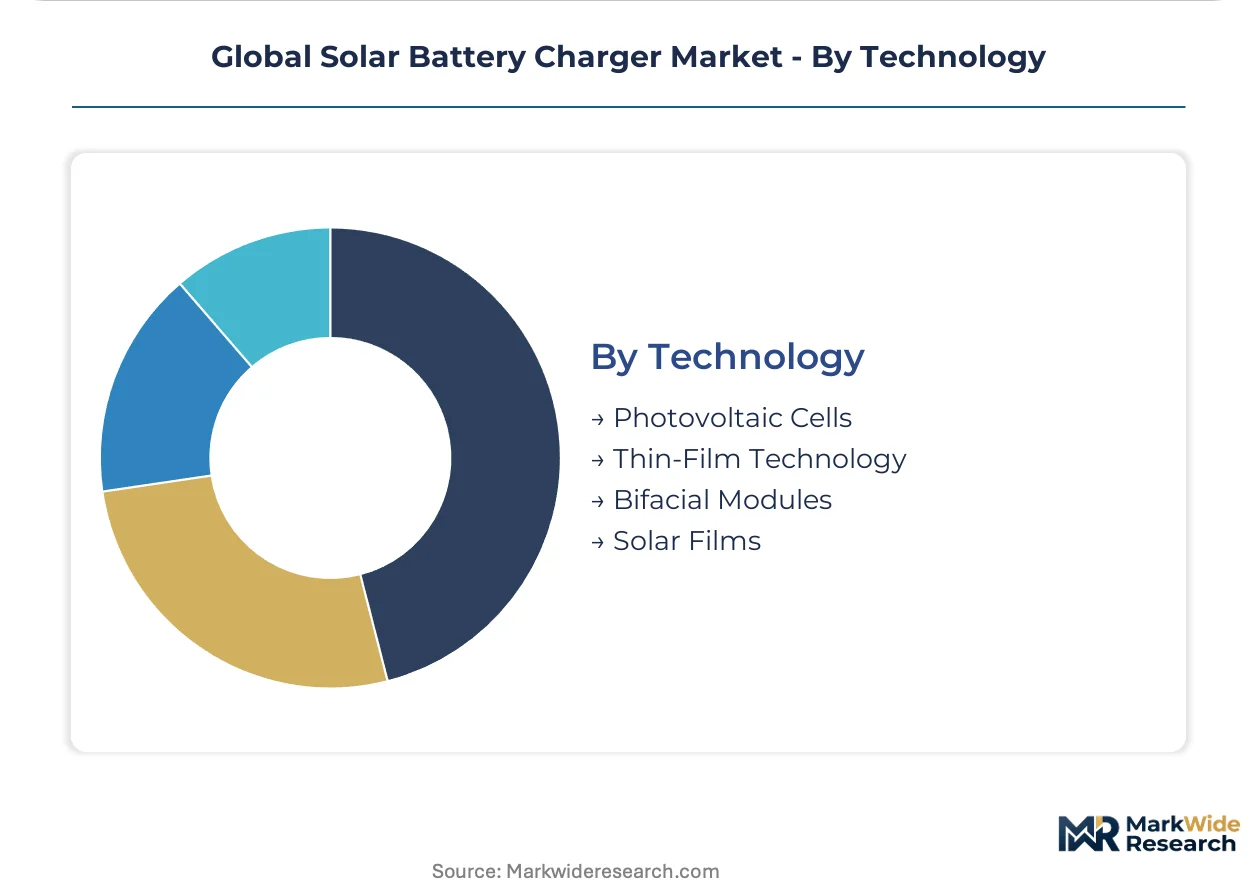
Technology:
Cell chemistry and module architecture determine efficiency ceilings and manufacturing cost structures.
- Photovoltaic Cells:Monocrystalline silicon configurations achieving 18-22% conversion efficiency in standard test conditions. China's MEE dual carbon goals are consolidating domestic manufacturing, creating input cost volatility for non-integrated assemblers.
- Bifacial Modules:Dual-sided panels capturing rear-side albedo reflection, boosting total energy yield 10-20% in high-reflectivity environments. Integrated solar kits above 50W are adopting this technology fastest in Australia and the southwestern US.
- Thin-Film Technology:Cadmium telluride and CIGS alternatives with lower efficiency but temperature coefficient advantages.
- Solar Films:Flexible amorphous silicon for weight-critical applications in aviation and marine backup power.
Photovoltaic cells dominate manufacturing scale. Bifacial modules are gaining share fastest in premium integrated kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification mandates for lithium-based storage imports anchor the dominant geography, concentrating formal supply among certified vendors while accelerating rural electrification procurement across South Asian off-grid segments.
United States
Outdoor enthusiasts and residential backup buyers drive portable charger demand, particularly in Florida and Arizona where hurricane preparedness shapes purchasing. The FCC governs electromagnetic emissions from smart-charging circuitry, creating certification-driven preference shifts. Utah hosts concentrated photovoltaic engineering talent pools that sustain captive R&D capabilities among integrated manufacturers.
Germany
Commercial and industrial buyers prioritize fixed installations in 20W-50W capacity bands where grid reliability concerns justify upfront capital. The EU Green Deal and national efficiency standards accelerate bifacial module adoption over legacy thin-film alternatives. Engineering clusters in Munich concentrate GaN switching expertise and MPPT algorithm development capabilities.
India
Rural electrification gaps in Bihar, Uttar Pradesh, and Rajasthan present concentrated demand for sub-20W portable chargers where grid extension remains economically unviable. BIS mandates safety testing for lithium-based storage imports, directly affecting market access timelines for foreign suppliers. Formal procurement programs favor certified lithium vendors over lead-acid entrenched in price-sensitive segments.
Japan
Residential backup segments show strongest uptake of above-50W solar generator systems where METI efficiency standards and total cost of ownership calculations favor lithium chemistry. Grid instability concerns in earthquake-prone regions justify premium positioning for integrated power electronics. Tokyo and Osaka engineering clusters specialize in power semiconductor advances for DC-DC conversion miniaturization.
Australia
Outdoor enthusiasts and remote workers migrate toward manufacturer-direct subscriptions bundling hardware with cloud-based energy monitoring. Cellular connectivity enables real-time panel performance optimization in US and Australian markets. High-reflectivity environments in the southwestern interior accelerate bifacial module gains in integrated solar kits above 50W.
Global Solar Battery Charger Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive R&D capabilities determining margin capture across portable and fixed installation segments. The competitive landscape bifurcates between Utah-based engineering clusters sustaining premium positioning and Shenzhen-scale manufacturing anchoring cost structures. Three archetypes dominate: integrated manufacturers with captive photovoltaic engineering, assembly-only competitors dependent on spot markets, and power electronics specialists focused on GaN switching and MPPT algorithms. Dominant competitive moves include direct-to-consumer channel control and smart-charging circuitry integration combining solar input, battery management, and DC output in single enclosures.
Within the integrated manufacturer tier, Goal Zero and Renogy exemplify divergent strategic positions, with the former leveraging captive R&D in Utah and the latter anchoring cost structure through North American channel control. EcoFlow occupies a position among power electronics specialists targeting above-50W solar generator systems. These three companies represent the competitive spectrum from premium engineering-driven positioning to scale-driven manufacturing efficiency and specialized semiconductor integration.
| Leading Market Players |
|---|
| Anker Innovations |
| Goal Zero |
| EcoFlow |
| Jackery |
| Renogy |
| Voltaic Systems |
| RavPower |
| BioLite |
| Solar Technology International |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for polysilicon feedstock lock in both supply access and price visibility for integrated manufacturers, while assembly-only competitors remain exposed to spot market volatility amplified by China's MEE dual carbon enforcement.
Pricing Analysis
North American fixed installations command 40-60% premiums over South Asian portable units due to FCC certification costs and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates GaN-enabled smart chargers from basic silicon-controller designs. Cost compression in lithium-ion cells is intensifying because gigafactory scale effects propagate through supply chains. Rural Indian households in Bihar and Uttar Pradesh exhibit highest price sensitivity, while Japanese residential backup buyers absorb premium positioning for above-50W solar generator systems.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for North American distributors dependent on Chinese module imports. Manufacturing concentrates in China, South Korea, and Vietnam for photovoltaic cells and lithium-ion battery packs. Polysilicon, gallium nitride semiconductors, and aluminum enclosures feed final assembly. Single-source vulnerability persists for GaN switching components concentrated in Utah and Munich engineering clusters. Distribution runs through direct-to-consumer platforms for portable chargers and electrical distributor networks for fixed installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between manufacturer-direct subscription platforms and cloud-based energy monitoring ecosystems is reshaping customer acquisition economics, creating platform-economics inflection where hardware margins decouple from recurring revenue streams.
For Market Incumbents: Consolidate captive R&D capabilities in photovoltaic engineering and power electronics to defend against Shenzhen-scale assemblers eroding margin pools. Deepen backward integration into lithium cell supply through long-term offtake agreements with Chinese gigafactory operators. Prioritize BIS certification investment to lock in formal procurement access across India's rural electrification programs.
For New Entrants and Emerging Players: Lead with unmet demand in India's sub-20W portable charger segment where BIS mandates have disqualified informal suppliers. Target Uttar Pradesh and Rajasthan state procurement programs with certified lithium-based designs displacing entrenched lead-acid vendors. Deploy direct-to-consumer channels with embedded sizing tools to bypass traditional electrical distributor markups.
For Investors and Strategic Acquirers: Power electronics specialists with GaN switching expertise and MPPT algorithm development capabilities represent priority acquisition archetypes. Long-term viability hinges on semiconductor integration depth rather than assembly scale. Monitor EPA Energy Star standby power consumption benchmark tightening as inflection indicator for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Integration | Miniaturizes charge controller enclosures 40-60% while reducing thermal losses for aviation and marine buyers. |
| BIS Certification Acceleration | Unlocks formal procurement access across India's rural electrification programs in Bihar and Rajasthan. |
| Direct-to-Consumer Platform Deployment | Disintermediates traditional electrical distributors in North American fixed installation segments. |
| Smart-Charging Circuitry Consolidation | Combines solar input, battery management, and DC output to meet FCC electromagnetic emissions governance. |
| Bifacial Module Adoption | Captures rear-side albedo reflection in Australian and southwestern US high-reflectivity environments. |
Study Parameters
A spread of perspectives from EPC contractors, outdoor retail buyers, lithium cell procurement managers, and power electronics engineers converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from customs trade data, SEC filings of listed energy equipment manufacturers, IEA renewable energy deployment reports, and BIS certification registries. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segmentation dimensions modeled include product type, charging capacity band, end-user archetype, and cell chemistry across the projection horizon. CAGRs derived from fitted growth curves applied to disclosed production capacities and regional electrification program budgets. Industry-specific forecast inputs incorporated polysilicon spot price trajectories and EPA Energy Star standby power consumption benchmark phase-in timelines.
Forecasts assume regulatory continuity in US FCC electromagnetic emissions governance, India's BIS lithium storage mandates, and China's MEE dual carbon enforcement; material policy shifts would require re-modeling. Specific risks include tariff exposure on Chinese module imports and reciprocity gaps between national certification protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Portable Battery Station Market
Batteries
Battery Maintainer Market
Batteries
Cobalt-Free Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Zinc Ion Batteries Market
Batteries
Inverter Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Japan Mobile Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Mobile Battery Market
Batteries
Battery Binders Market
Batteries
France Rechargeable Battery Market
Batteries
East Europe Battery Market
Batteries
Automotive AGM Battery Market