
 Asia-Pacific Electric Vehicle Charging Cable Market | 2026-2036
Asia-Pacific Electric Vehicle Charging Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Vehicle Charging Cable Market Analytics
High-temperature silicone insulation rated for 180°C continuous operation is reorganizing procurement priorities across the Asia-Pacific Electric Vehicle Charging Cable Market. TE Connectivity Ltd. leverages its connector-cable integration expertise to dominate high-voltage architectures in Japan and South Korea. Sumitomo Electric Industries, Ltd. anchors regional supply through backward integration into copper conductor drawing and compound extrusion. Leoni AG specializes in flexible fast-charging assemblies that withstand repeated bending cycles in commercial fleet depots.
Asia-Pacific electric vehicle charging cables are insulated conductor assemblies engineered to deliver power across AC Level 1 through DC ultra-fast protocols, with conductor gauges ranging from 2.5 mm² for residential trickle charging up to 95 mm² liquid-cooled configurations for 350 kW dispensers. Their primary purpose is to bridge the energy transfer gap between grid infrastructure and onboard vehicle battery management systems while maintaining thermal stability under sustained load. DC fast charging and ultra-fast charging segments command premium positioning due to material intensity and thermal management complexity, whereas Type 2 and GB/T connectors lead unit volume through regulatory alignment across China, South Korea, and Australia. Workplace charging and commercial fleet applications are expanding fastest as employer-sponsored electrification and logistics decarbonization programs proliferate.
China's NMPA and GB standards regime, India's BIS certification requirements, and Australia's Electrical Regulatory Authorities Council wiring rules collectively dictate cable fire-resistance ratings, electromagnetic compatibility thresholds, and connector interoperability mandates across the region. Manufacturers must navigate fragmented conformity assessment pathways that delay market entry by six to eighteen months for new product families. Stakeholders should monitor evolving thermal runaway propagation standards and liquid-cooled cable reliability data as power ratings climb beyond 500 kW.
Market Dynamics
China's GB standards regime and India's PLI scheme for auto component manufacturing are accelerating localization mandates across the Asia-Pacific Electric Vehicle Charging Cable Market, forcing multinational suppliers to establish captive extrusion and conductor-drawing capacity within the region.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for auto component manufacturing are pulling cable assembly lines into Maharashtra-Gujarat industrial corridor, reducing import dependence for domestic EV OEMs.
- Fleet electrification:Logistics operators across Southeast Asia are deploying DC fast-charging depots at scale, creating concentrated demand for liquid-cooled cable configurations rated above 150 kW.
- High-temperature silicone insulation:Continuous operation ratings of 180°C are enabling thinner conductor gauges without thermal derating, reducing copper intensity per meter.
Market Restraints
- Copper price volatility:Conductor materials represent 55-65% of cable bill-of-materials, exposing margins to London Metal Exchange fluctuations without effective hedging mechanisms for mid-tier assemblers.
- Conformity assessment fragmentation:China's NMPA, India's BIS, and Australia's Electrical Regulatory Authorities Council maintain non-harmonized testing protocols, extending product validation cycles.
- Technical ceiling at 500 kW:Thermal runaway propagation risks and liquid-cooling reliability uncertainties are constraining power rating extensions beyond current ultra-fast charging thresholds.
Strategic Opportunities
- Indonesia's nickel-copper integration:Downstream cable producers can secure captive conductor supply by locating near Morowali industrial park, leveraging the country's mineral processing investments.
- Workplace charging mandates:Employer-sponsored electrification programs in South Korea and Australia are creating distributed AC Level 2 installation demand outside public infrastructure.
- Vehicle-to-grid convergence:Bidirectional charging protocols are requiring reinforced cable architectures with integrated communication layers, opening premium product tiers.
Industry Challenges
- Electromagnetic compatibility engineering:Shielding design for 350 kW+ dispensers demands specialized simulation capabilities scarce outside Japan and South Korea.
- Certification timeline compression:Six-to-eighteen month approval windows for new product families across multiple national regimes strain R&D-to-revenue cycles.
- Liquid-cooled assembly reliability:Coolant channel integrity under repeated flexing cycles remains unproven at commercial fleet utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Vehicle Charging Cable Market |
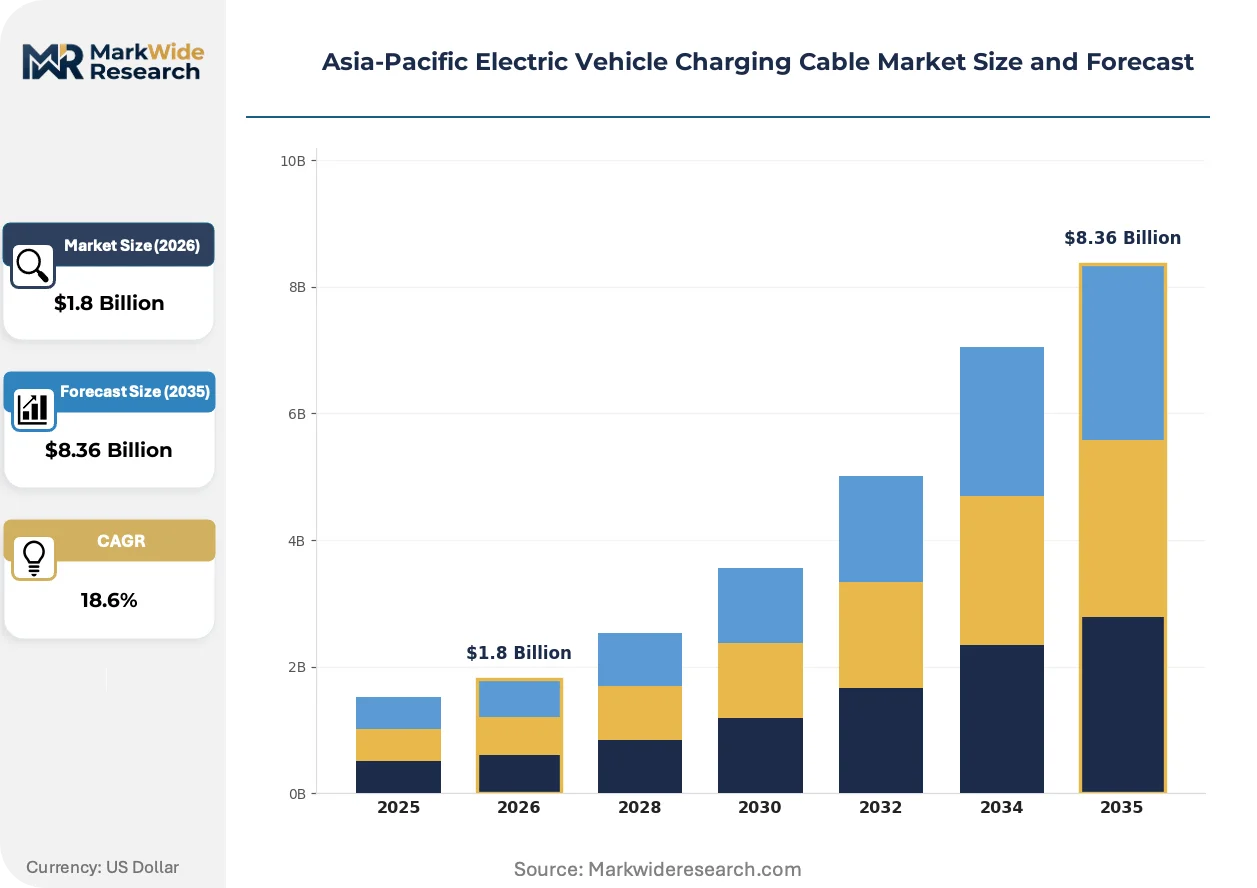
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1, Type 2, CHAdeMO, CCS1, GB/T Charging Level: Level 1, Level 2, DC Fast Charging, Ultra-Fast Charging Application: Public Charging Stations, Commercial Fleets, Residential Use, Workplace Charging End User: Electric Bus Operators, Fleet Management, Vehicle Manufacturers, Energy Service Providers |
| Companies Covered | TE Connectivity Ltd., Leoni AG, Aptiv PLC, Sumitomo Electric Industries, Ltd., HUBER+SUHNER AG, Phoenix Contact GmbH & Co. KG, Nexans S.A., Sinbon Electronics Co., Ltd., Dyden Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Vehicle Charging Cable Market Evolving Landscape
Material science advances and regulatory tightening are compressing product lifecycles across the Asia-Pacific Electric Vehicle Charging Cable Market, favoring suppliers with integrated compound formulation and extrusion capabilities.
Liquid-cooled conductor architectures rated for 350 kW continuous operation are supplanting air-insulated assemblies in commercial fleet depot specifications. Japanese and South Korean charging network operators are mandating these configurations for new installations above 150 kW. The technology is compressing thermal management system footprints while extending peak power duration.
China's NMPA is tightening GB standards for fire-resistance ratings and electromagnetic compatibility thresholds. Cable manufacturers must now submit to extended thermal propagation testing before market authorization. South Korean and Australian regulators are observing these protocols for potential adoption, creating anticipatory compliance investments.
Direct procurement relationships between fleet operators and cable assemblers are displacing distributor-mediated transactions in high-volume segments. Tier-one charging network developers in China and India are issuing multi-year supply agreements with technical collaboration clauses. This pattern concentrates demand validation with end-users possessing in-house testing capabilities.
Asia-Pacific Electric Vehicle Charging Cable Market Segmentation
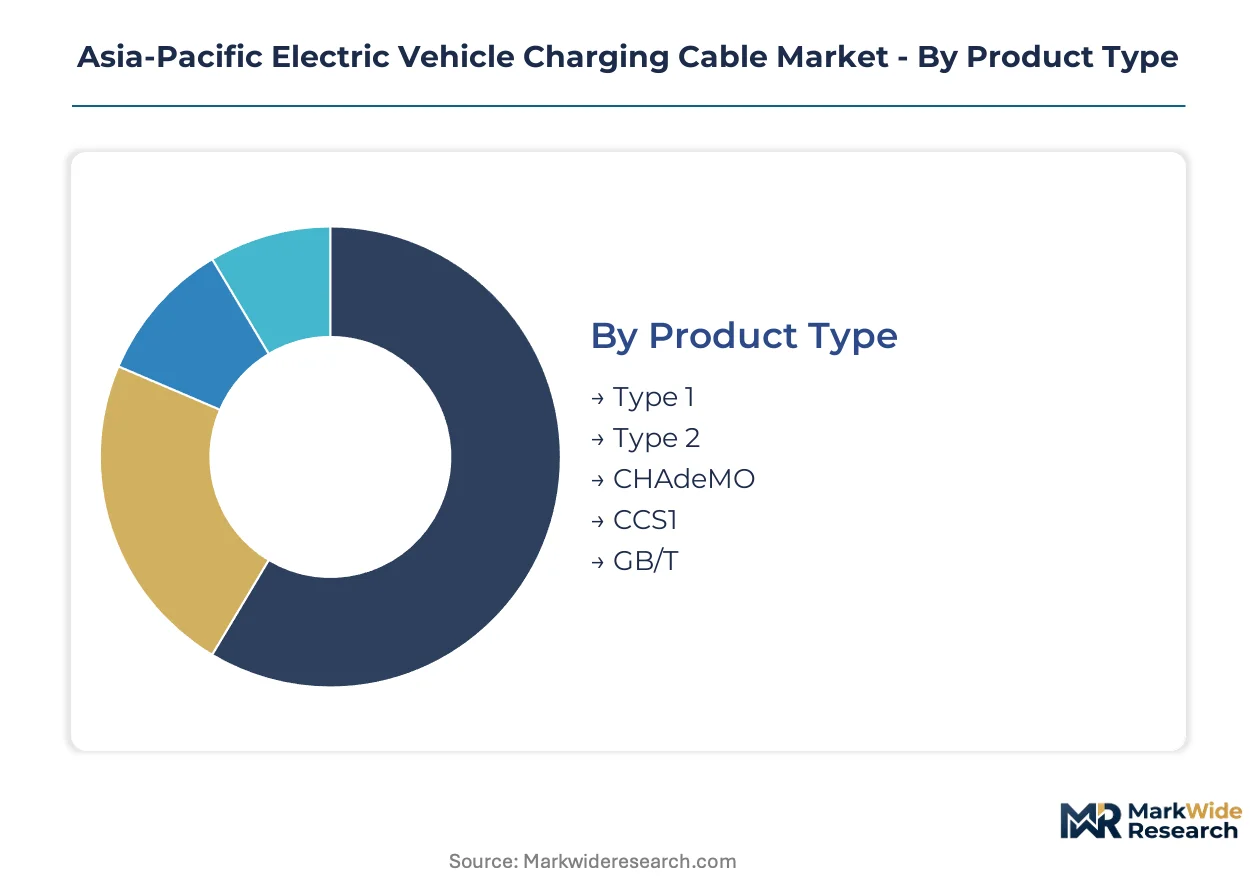
Segmentation in the Asia-Pacific Electric Vehicle Charging Cable Market reveals how technical specifications, power protocols, and end-use environments fragment procurement requirements. Understanding these divisions exposes where cable assemblers must customize conductor gauges, insulation ratings, and connector geometries to capture contract value.
Product Type:
Margin pools concentrate in connectors aligned with national regulatory regimes and high-voltage architectures requiring specialized shielding engineering.
- GB/T:China's national standard dominates unit volume through NMPA-mandated interoperability for domestic OEMs. GB/T connectors incorporate unique pin configurations and communication protocols that lock out non-certified suppliers. Demand concentrates in Shanghai, Beijing, and Shenzhen public networks where state-backed charging operators deploy at scale.
- Type 2:European-derived connectors anchor South Korean and Australian installations through regulatory harmonization with EU technical standards. These configurations support three-phase AC charging up to 43 kW, making them preferred for workplace and residential wallbox deployments. South Korea's charging network operators are mandating Type 2 compatibility for new AC infrastructure subsidies.
- Type 1:Single-phase AC connectors retain installed base in legacy Japanese residential installations and early Australian EV adopter households.
- CHAdeMO:Japanese-developed DC fast-charging protocol maintains presence in Nissan-dominated fleets and early public infrastructure across Southeast Asia.
- CCS1:Combined charging system variant serves imported European and North American EV models in Australian and South Korean premium segments.
GB/T holds installed capacity. Type 2 is rotating up the share rankings across South Korea and Australia as AC workplace charging expands.
Charging Level:
Application intensity and thermal management complexity determine where cable producers extract premium pricing versus competing on copper efficiency.
- Ultra-Fast Charging:Liquid-cooled 350 kW+ configurations command the highest material intensity per meter, with 95 mm² conductors and integrated coolant channels. TE Connectivity and Sumitomo Electric anchor supply for Japanese and South Korean network operators specifying these for commercial fleet depots. Reliability data under repeated flexing cycles remains limited at commercial utilization rates.
- DC Fast Charging:50-150 kW air-insulated assemblies serve as the workhorse for public highway corridor installations across China and India. Maharashtra-Gujarat industrial corridor fleet operators are concentrating procurement here for intracity logistics electrification.
- Level 2:7-22 kW AC configurations dominate residential and workplace volume through lower copper intensity and simpler termination requirements.
- Level 1:Trickle-charging 2.5 mm² cables persist in legacy residential segments with minimal infrastructure investment.
DC Fast Charging holds installed capacity. Ultra-Fast Charging is expanding most quickly as fleet electrification timelines accelerate.
Application:
Procurement authority structures and utilization intensity separate segments with long-term supply agreements from spot-market transactions.
- Commercial Fleets:Logistics operators across Indonesia, Thailand, and Vietnam are issuing multi-year technical collaboration agreements with cable assemblers possessing in-house electromagnetic compatibility testing. These contracts specify liquid-cooled architectures for depot charging above 150 kW. Direct procurement relationships are displacing distributor channels.
- Workplace Charging:Employer-sponsored electrification programs in South Korea and Australia are creating distributed AC Level 2 demand outside public infrastructure buildouts. Installation specifications prioritize flexible assemblies for repeated plugging cycles in multi-user parking structures.
- Public Charging Stations:State-backed network operators in China and India concentrate demand validation through centralized tender processes with extended thermal propagation testing requirements.
- Residential Use:Single-family home installations favor cost-optimized Type 2 or GB/T configurations with basic weatherproofing.
Public Charging Stations hold installed capacity. Commercial Fleets is climbing the fastest as logistics decarbonization programs proliferate.
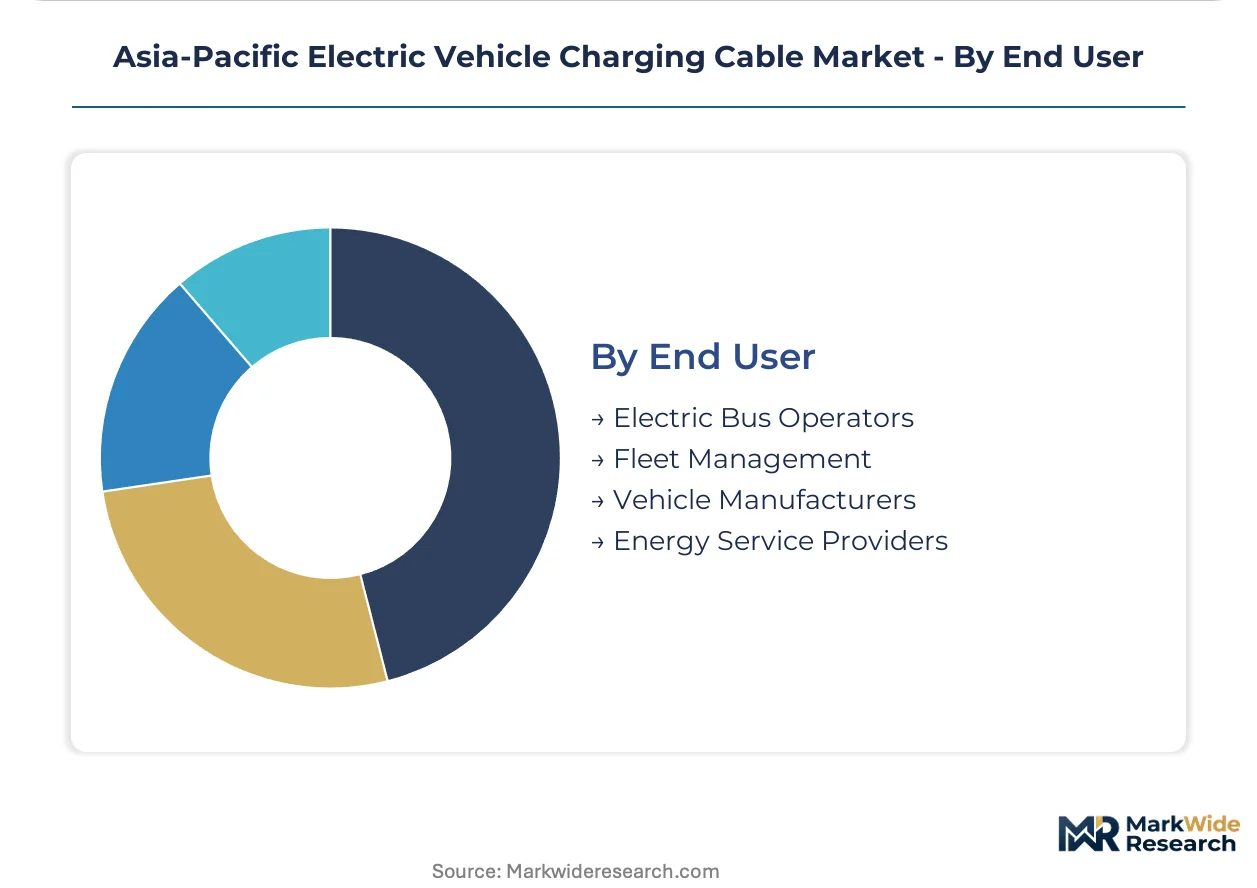
End User:
Technical specification authority and volume concentration determine whether cable producers engage directly with end-users or through vehicle OEM intermediaries.
- Fleet Management:Southeast Asian logistics operators possess in-house testing capabilities that validate cable performance under actual depot conditions. These stakeholders are driving liquid-cooled specification adoption and compressing product validation cycles. Direct relationships with assemblers enable customized conductor gauge optimization for specific route duty cycles.
- Electric Bus Operators:Municipal and state transit authorities in China and India specify high-utilization charging infrastructure with 24/7 operational requirements. Procurement emphasizes fire-resistance ratings and thermal runaway containment under NMPA and BIS protocols.
- Vehicle Manufacturers:OEMs bundle charging cables with new EV sales, favoring standardized configurations that minimize SKU complexity across model ranges.
- Energy Service Providers:Utility-affiliated charging network developers aggregate demand across multiple customer types, prioritizing interoperability certification efficiency.
Vehicle Manufacturers hold installed capacity. Fleet Management is gaining share fastest as direct procurement patterns consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for conductor materials and connector assemblies is narrowing across the Asia-Pacific Electric Vehicle Charging Cable Market as localization mandates intensify. Export-oriented cable producers in China and South Korea are redirecting capacity toward domestic fleet electrification programs. Regional trade flows are reorganizing around mineral processing investments in Indonesia and India's component manufacturing incentives.
China
State-backed charging network operators in Shanghai, Beijing, and Shenzhen are deploying GB/T-compliant infrastructure at scale. The NMPA enforces extended thermal propagation testing and electromagnetic compatibility thresholds under tightening GB standards. Yangtze River Delta manufacturing clusters are absorbing multinational extrusion capacity to satisfy domestic content requirements.
India
Maharashtra-Gujarat industrial corridor fleet operators are concentrating procurement for intracity logistics electrification. The BIS certification regime mandates fire-resistance ratings and connector interoperability testing that extends product validation cycles. Cable assembly lines are migrating into the corridor under PLI scheme incentives for auto component manufacturing.
Japan
Commercial fleet depots in Kanto and Kansai regions are specifying liquid-cooled architectures above 150 kW. METI oversees technical standards for high-voltage shielding design and electromagnetic compatibility engineering. Chubu manufacturing bases anchor supply for domestic charging network operators and Southeast Asian export markets.
South Korea
Employer-sponsored electrification programs in Seoul Capital Area are driving distributed AC Level 2 workplace installations. The MFDS and national charging infrastructure subsidies mandate Type 2 compatibility for new AC infrastructure. Busan-Ulsan industrial complexes host backward-integrated producers serving domestic and regional demand.
Australia
Premium EV segments in New South Wales and Victoria are importing CCS1 configurations for European and North American vehicle models. The Electrical Regulatory Authorities Council wiring rules dictate cable fire-resistance ratings and installation standards. Workplace charging mandates in commercial districts are expanding Type 2 specification demand outside public infrastructure.
Asia-Pacific Electric Vehicle Charging Cable Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing integrated compound formulation and extrusion capabilities. The vendor base organizes around three strategic archetypes: connector-cable integration specialists, backward-integrated copper processors, and flexible assembly engineers serving commercial fleet depots. Consolidation pressure is mounting as certification timelines compress and power ratings climb beyond 350 kW. Dominant competitive moves include captive conductor supply arrangements and multi-year technical collaboration agreements with fleet operators.
Within the diversified industrial tier, TE Connectivity Ltd., Sumitomo Electric Industries, Ltd., and Leoni AG exemplify contrasting capability configurations. TE Connectivity occupies a position emphasizing connector-cable integration for high-voltage architectures. Sumitomo Electric anchors regional supply through upstream control over copper conductor drawing and compound extrusion. Leoni AG sits within the flexible fast-charging assembly segment, representing specialization in configurations that withstand repeated bending cycles. These three entities collectively illustrate how technical differentiation around thermal management, material integration, and mechanical durability is fragmenting competitive positioning across the Asia-Pacific Electric Vehicle Charging Cable Market.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| Leoni AG |
| Aptiv PLC |
| Sumitomo Electric Industries, Ltd. |
| HUBER+SUHNER AG |
| Phoenix Contact GmbH & Co. KG |
| Nexans S.A. |
| Sinbon Electronics Co., Ltd. |
| Dyden Corporation |
| Others |
Value Network & Pricing Analysis
High-temperature silicone insulation replacing conventional thermoplastic compounds is redrawing procurement geography across the Asia-Pacific Electric Vehicle Charging Cable Market while compressing per-meter copper intensity and altering margin structures for compound formulators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Asia-Pacific Electric Vehicle Charging Cable Market. Pricing stratifies across premium liquid-cooled configurations, standard air-insulated DC assemblies, and economy-grade AC Level 2 cables differentiated by certification grade under NMPA and BIS protocols. Cost compression in standard tiers is intensifying because mid-tier assemblers lack effective London Metal Exchange hedging mechanisms. Fleet management operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, whereas residential distributors face acute margin pressure.
Supply Chain Analysis
Just-in-time inventory strategies dominate conductor procurement for high-volume assemblers, though strategic stockpiling of silicone compounds persists among Japanese and South Korean producers anticipating NMPA regulatory tightening. Manufacturing gravity centers on China, Japan, and South Korea, with raw material dependencies spanning Chilean copper cathode, Indonesian nickel for alloy conductors, and German specialty silicone formulations. Single-source vulnerability concentrates in liquid-cooled channel extrusion equipment. Distribution runs through direct technical collaboration agreements between cable assemblers and fleet operators, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Electric Vehicle Charging Cable Market functions as a regulatory-moat industry where GB standards and BIS certification entrenchment creates switching costs that lock out non-compliant suppliers.
For Market Incumbents: Compound backward integration into copper conductor drawing and compound extrusion to defend against emerging Chinese producers leveraging Yangtze River Delta manufacturing clusters. Prioritize captive silicone formulation capabilities as NMPA thermal propagation testing requirements tighten. Certification investment represents the critical lever for extending product validation timelines that strain R&D-to-revenue cycles for challengers. For New Entrants and Emerging Players: Anchor in Indonesia's Morowali industrial park to exploit nickel-copper integration opportunities and secure captive conductor supply outside established Yangtze River Delta and Busan-Ulsan manufacturing bases. Target workplace charging mandates across South Korea and Australia as the most penetrable segment, where employer-sponsored electrification programs lack dedicated cable assemblers with electromagnetic compatibility testing capabilities. Pursue technical collaboration agreements with mid-sized logistics operators seeking customized conductor gauge optimization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cable assembly specialists possessing in-house compound formulation but lacking connector-cable integration expertise. Five-to-ten year viability hinges on consolidation into diversified industrial conglomerates with multi-regional certification capabilities. Watch liquid-cooled cable reliability data under commercial fleet utilization rates as the inflection indicator for power rating extensions beyond current thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Conductor Drawing | Captive supply from Morowali and Yangtze River Delta clusters insulates margins from London Metal Exchange volatility. |
| Liquid-Cooled Assembly Certification Investment | NMPA thermal propagation testing alignment accelerates market authorization for 350 kW+ configurations in Chinese fleet depots. |
| Direct Procurement Relationship Development | Technical collaboration agreements with Southeast Asian logistics operators displace distributor-mediated transactions in high-volume segments. |
| Silicone Compound Formulation Capability | In-house production of 180°C-rated insulation compounds reduces dependence on German specialty chemical suppliers. |
| Electromagnetic Compatibility Testing Infrastructure | Proprietary shielding simulation capabilities scarce outside Japan and South Korea unlock premium positioning for ultra-fast charging architectures. |
Research Methodology
A spread of perspectives from charging network procurement directors, fleet management operators, cable assembly plant managers, and BIS certification consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, NMPA filing databases, IHS Markit vehicle registration data, and SEC disclosures from listed industrial conglomerates. Bottom-up unit economics triangulated against top-down regional electrification policy trajectories.
Segmentation dimensions modeled span connector protocol type, charging power level, application environment, and end-user procurement authority across the projection horizon. CAGRs derive from installed base growth curves, replacement cycle assumptions, and power rating upgrade pathways. Forecast inputs incorporate fleet electrification timelines from logistics operators, workplace charging mandate adoption rates, and liquid-cooled cable reliability maturation.
Material uncertainties — copper price volatility, regulatory timeline compression, and thermal runaway propagation standard evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding GB standards harmonization and PLI scheme incentive continuity. Revision becomes warranted when liquid-cooled assembly failure rates under commercial utilization cross thresholds that trigger network operator specification reversions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Wireless Electric Vehicle Charger Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Engineered Polymers in Electric Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Pantograph Charger Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
EV Charging Management Software Platform Market