
 Latin America Coiled Tubing Market | 2026-2036
Latin America Coiled Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Coiled Tubing Market Foresight
Digital well monitoring and real-time telemetry integration is fragmenting traditional coiled tubing service models across Latin America. Schlumberger Limited leverages proprietary automation platforms to anchor premium intervention contracts in Brazil's deepwater fields. Halliburton Company sustains manufacturing scale through dedicated regional supply chains. Baker Hughes Company differentiates via alloy-grade tubing specifications suited to high-pressure carbonate reservoirs.
Coiled tubing comprises continuous, seam-welded steel pipe manufactured in long single lengths, typically ranging from one to over six kilometers, spooled onto large-diameter reels for repeated deployment downhole without threaded connections. Its primary purpose centers on live-well intervention, drilling, and completion operations where rig mobilization costs prove prohibitive. Heavy wall coiled tubing commands the strongest margin pools where sour service and high-pressure applications dominate, while composite coiled tubing represents the fastest-growing type segment as operators seek corrosion resistance in offshore Brazilian pre-salt environments. Well intervention services generate the largest revenue share among service categories, though enhanced oil recovery applications are expanding fastest as mature fields across Mexico and Venezuela require production optimization.
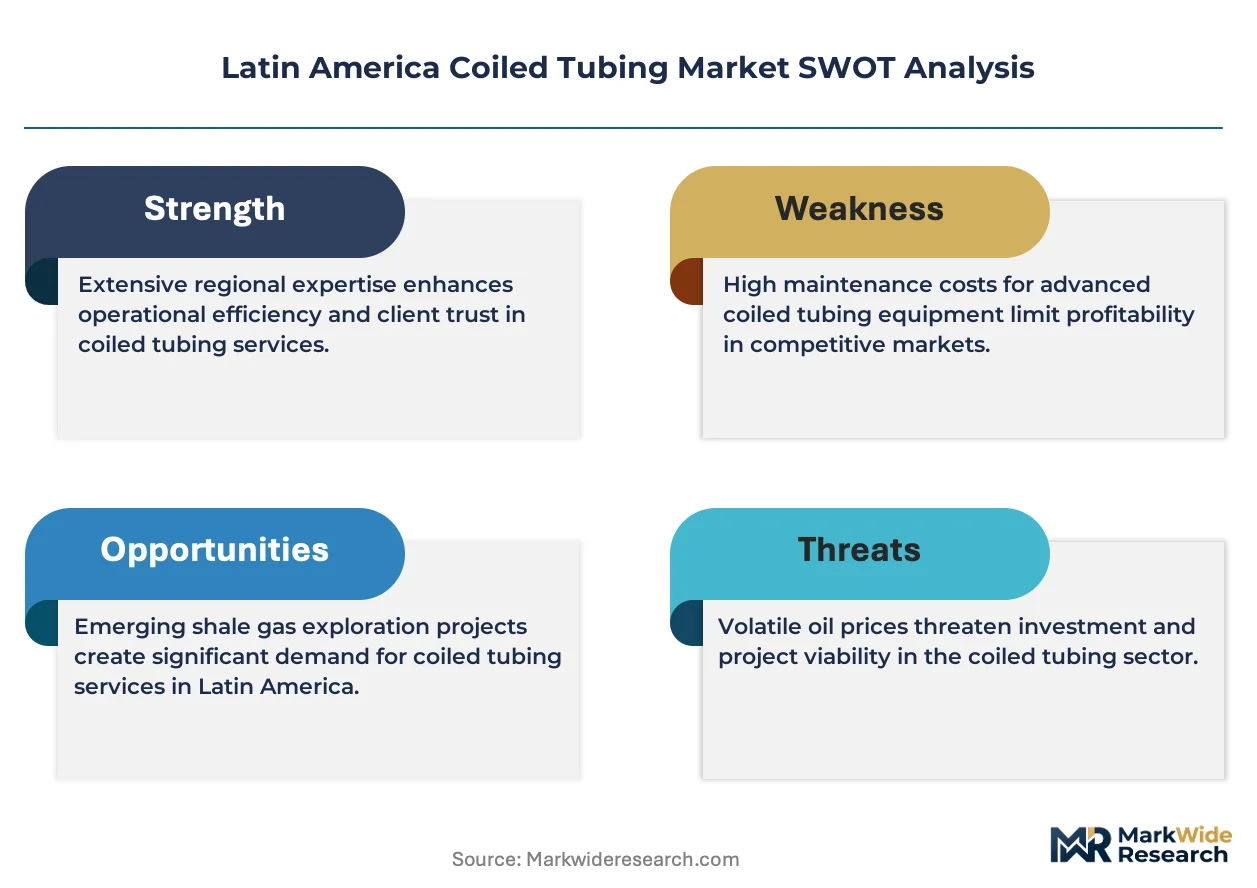
Brazil's ANP well integrity directives, Mexico's ASEA environmental compliance protocols, and Argentina's provincial hydrocarbon regulators collectively shape equipment certification requirements and operational permitting timelines across the region. These frameworks elevate barriers for non-compliant suppliers while creating structured demand for certified, traceable tubing inventories. Stakeholders must weigh capital allocation between conventional steel tubing expansion and composite material capabilities as regulatory pressure on corrosion management intensifies.
Market Dynamics
Brazil's ANP well integrity mandates are compressing equipment replacement cycles across Latin American coiled tubing fleets, forcing operators to accelerate capital deployment toward corrosion-resistant alloy and composite systems.
Growth Catalysts
- Pre-salt intervention intensity:Brazil's deepwater carbonate reservoirs require continuous live-well operations that only coiled tubing delivers, anchoring equipment demand in the Santos Basin.
- ANP Regulatory Directive 13/2019:Mandatory well integrity assessments every two years for high-pressure offshore wells are structurally expanding the addressable market for certified heavy-wall tubing.
- Enhanced oil recovery mandates:Mexico's mature Cantarell and Ku-Maloob-Zaap fields require nitrogen and chemical injection campaigns that deploy coiled tubing units for cost-effective wellbore access.
Market Restraints
- Alloy steel price volatility:Chromium-molybdenum grades essential for sour service tubing fluctuate with ferroalloy import costs, compressing fabrication margins for regional manufacturers.
- Brazilian equipment import dependency:Domestic reel manufacturing capacity concentrates in São Paulo industrial corridors, creating single-source vulnerability for large-diameter spooling systems.
- Composite tubing technical ceiling:Thermoplastic-lined strings face pressure rating limitations below 10,000 psi that exclude them from Argentina's Vaca Muerta shale fracturing operations.
Strategic Opportunities
- Argentina Vaca Muerta shale expansion:Neuquén Basin operators are piloting coiled tubing drilling for lateral extensions where conventional rig economics fail.
- Real-time telemetry integration:Downhole sensor fusion with fiber-optic-enabled tubing strings is creating premium service tiers for pre-salt monitoring contracts.
- Mexico ASEA environmental compliance:Stricter well abandonment protocols are mandating coiled tubing-deployed cement squeezes and plug setting across offshore platforms.
Industry Challenges
- Specialized welder certification gaps:Seam-welding technicians qualified to API 5ST standards for continuous tubing remain scarce across Latin American fabrication yards.
- Multi-vendor system integration:Operators combining Schlumberger automation platforms with third-party tubing strings face telemetry protocol mismatches that delay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Coiled Tubing Market |
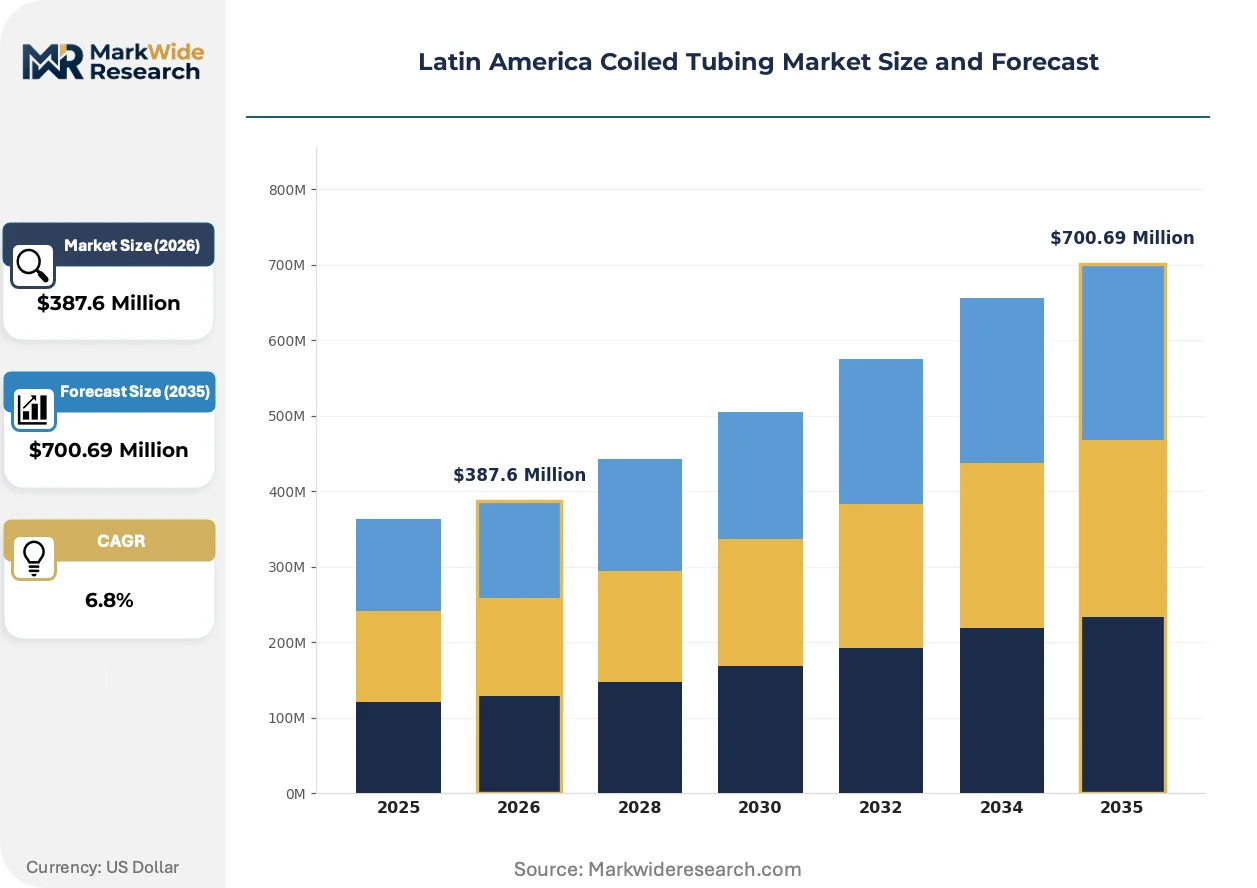
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard Coiled Tubing, Heavy Wall Coiled Tubing, Small Diameter Coiled Tubing, Composite Coiled Tubing Service Type: Well Intervention, Drilling, Logging, Cementing End User: Oil & Gas Operators, Service Companies, Offshore Drillers, Onshore Producers Application: Well Completion, Workover Operations, Enhanced Oil Recovery, Pipeline Repair |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Tenaris, Weatherford International, National Oilwell Varco, Jereh Group, Royal IHC, Calfrac Well Services Ltd., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Coiled Tubing Market Shifts & Advancements
Digital intervention architectures are fragmenting traditional service bundling across Latin American offshore fields, creating pressure for equipment suppliers to embed sensing and automation capabilities directly into tubing systems.
Composite-lined coiled tubing is hybridizing steel strength with polymer corrosion resistance for Brazilian pre-salt carbon dioxide injection campaigns. Petrobras and international operators are trialing these strings in the Santos Basin at accelerating frequency. The technology is hybridizing equipment procurement criteria, forcing suppliers to certify dual-material systems rather than conventional steel grades alone.
ANP Resolution 847/2021 mandates real-time well monitoring data transmission to regulatory servers for all high-pressure offshore interventions. This framework is structurally elevating capital requirements for service companies to deploy fiber-optic-enabled tubing and surface data acquisition units. Deepwater pre-salt contractors face the steepest compliance costs, accelerating consolidation among intervention specialists capable of integrated digital-physical service delivery.
Integrated service contracting is displacing equipment rental models across Mexican offshore platforms. Pemex and private operators now demand bundled tubing deployment, downhole tool operation, and real-time diagnostics from single vendors rather than fragmented supplier tiers. This pattern concentrates most visibly in the Bay of Campeche, where platform logistics complexity rewards vendor consolidation.
Latin America Coiled Tubing Market Segmentation
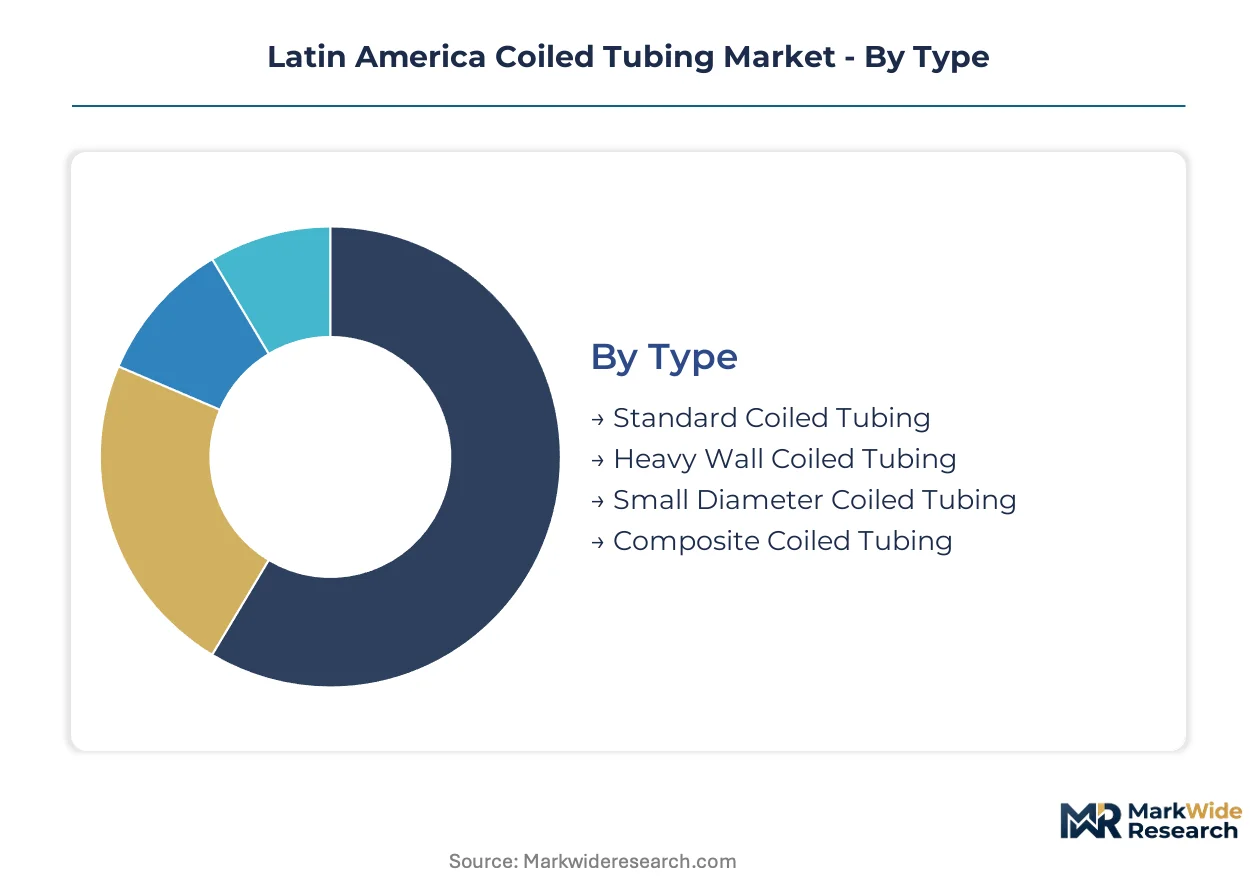
Equipment specification tiers in Latin American coiled tubing markets command distinct service intensity profiles. After-sales maintenance contracts, recertification cycles, and field engineering support vary dramatically across material grades and operational depths, creating segmented margin architectures for suppliers.
Type:
After-sales-service intensity escalates with corrosion resistance requirements and pressure rating thresholds, positioning composite and heavy-wall systems as premium service categories.
- Heavy Wall Coiled Tubing:Chromium-molybdenum alloy construction rated for sour service environments above 10,000 psi. Demand concentrates in Brazil's Santos Basin pre-salt fields where ANP well integrity mandates accelerate replacement cycles.
- Composite Coiled Tubing:Hybrid steel-polymer construction delivering corrosion immunity for carbon dioxide injection campaigns. Neuquén Basin operators in Argentina are piloting these strings for extended-reach laterals where conventional steel fatigue limits intervene.
- Standard Coiled Tubing:API 5ST-certified carbon steel grades dominating mature onshore workover markets across Mexico's southern fields.
- Small Diameter Coiled Tubing:Sub-1.75-inch specifications for slimhole interventions and through-tubing fishing operations in Venezuela's aging infrastructure.
By volume, standard grades lead across Latin American rental fleets. By growth pace, composite systems are expanding most quickly as offshore corrosion management intensifies.
Service Type:
Contract bundling patterns differentiate margin capture, with integrated service packages displacing standalone equipment rental across deepwater markets.
- Well Intervention:Live-well operations including nitrogen lifting, acid squeezing, and mechanical fishing. Brazil's pre-salt carbonate reservoirs require continuous intervention access that only coiled tubing delivers.
- Enhanced Oil Recovery:Chemical and gas injection campaigns deploying coiled tubing for precise wellbore placement. Mexico's Cantarell field redevelopment anchors regional demand for nitrogen foam injection services.
- Drilling:Underbalanced and re-entry drilling for lateral extensions where conventional rig economics fail.
- Logging:Conveyance of wireline tools in deviated wellbores where gravity descent proves insufficient.
- Cementing:Squeeze cementing and plug setting for well abandonment compliance under Mexico's ASEA protocols.
Well intervention commands the largest revenue share. Enhanced oil recovery applications are gaining share fastest as mature field optimization accelerates.
End User:
Procurement authority concentration varies with operational scale, with national oil companies driving specification standards across the region.
- Oil & Gas Operators:Petrobras, Pemex, and YPF dictate equipment certification requirements through integrated service contracts that bundle tubing deployment with real-time diagnostics.
- Service Companies:Schlumberger, Halliburton, and Baker Hughes maintain captive tubing inventories aligned to proprietary automation platforms.
- Offshore Drillers:Deepwater contractors facing ANP Resolution 847/2021 real-time monitoring mandates for high-pressure interventions.
- Onshore Producers:Provincial operators in Argentina's Mendoza and Chubut regions sourcing standard grades for conventional workover programs.
Oil and gas operators dominate capital deployment. Service companies are expanding inventory fastest through dedicated regional supply chains.
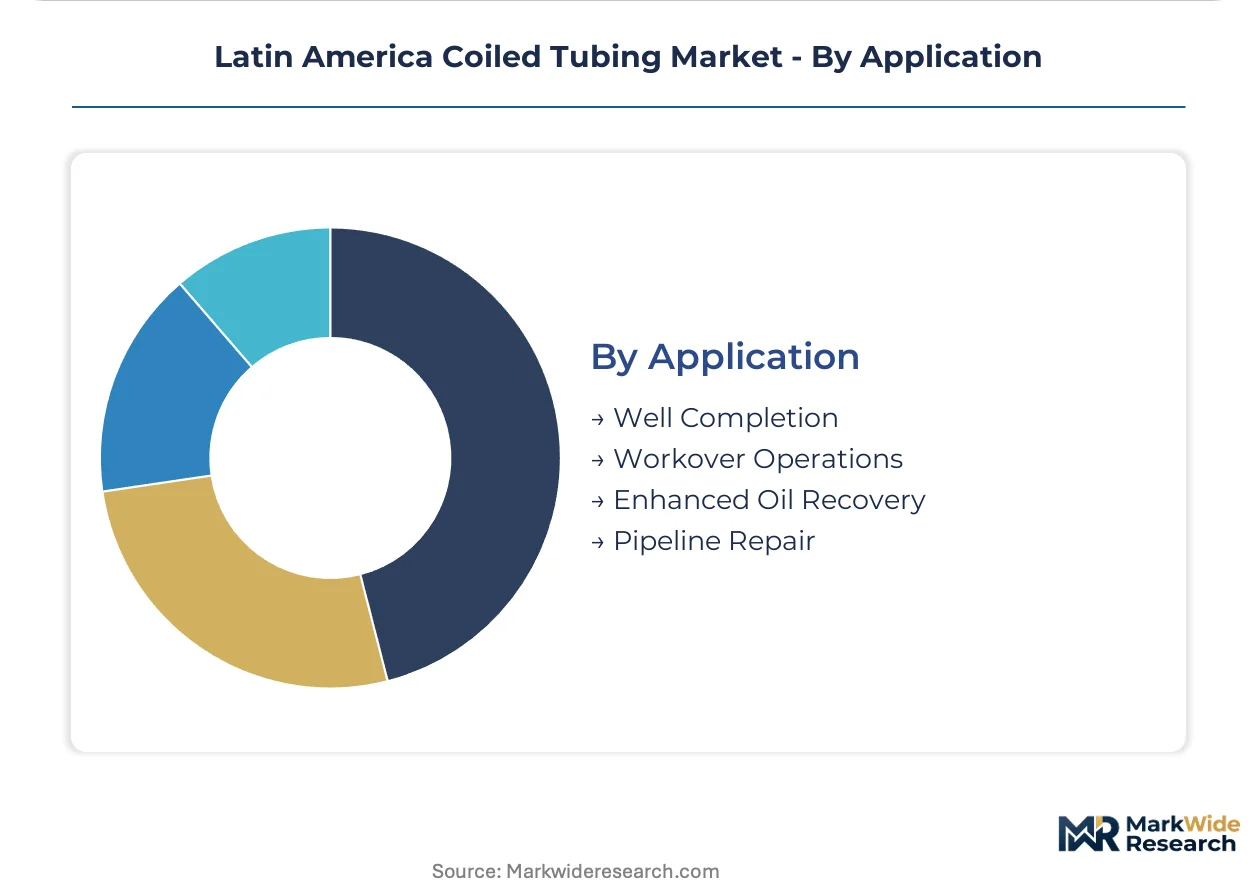
Application:
Regulatory compliance timelines reshape demand cyclicality, with abandonment mandates creating structural demand floors independent of oil price volatility.
- Enhanced Oil Recovery:Nitrogen and chemical injection for mature field revitalization. Mexico's Ku-Maloob-Zaap complex requires continuous coiled tubing access for production optimization campaigns.
- Workover Operations:Sand cleanouts, scale removal, and tubing replacement in producing wells. Brazil's Campos Basin fields generate recurring demand for heavy-wall strings in high-pressure environments.
- Well Completion:Fracturing and perforating operations in Vaca Muerta shale where coiled tubing drilling pilots are expanding.
- Pipeline Repair:Internal coating and structural reinforcement for subsea flowline integrity.
Workover operations represent the largest installed base. Enhanced oil recovery shows the steepest expansion trajectory as basin maturity deepens across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated service contractors concentrate procurement authority across Latin American coiled tubing markets, with national oil companies dictating certification standards through bundled intervention contracts.
Brazil
Petrobras drives heavy-wall tubing demand through continuous pre-salt well intervention campaigns in the Santos Basin. ANP Resolution 847/2021 mandates real-time monitoring data transmission to regulatory servers for all high-pressure offshore operations. Macaé and Rio de Janeiro industrial corridors host the densest concentration of coiled tubing service bases and reel maintenance facilities.
Mexico
Pemex and private operators require nitrogen foam injection services for mature field revitalization across the Cantarell and Ku-Maloob-Zaap complexes. ASEA environmental compliance protocols mandate coiled tubing-deployed cement squeezes for well abandonment operations. Ciudad del Carmen and Campeche serve as the primary logistics hubs for Bay of Campeche offshore platforms.
Argentina
YPF and international shale operators pilot coiled tubing drilling for Vaca Muerta lateral extensions where conventional rig economics fail. Provincial hydrocarbon regulators in Neuquén impose equipment traceability requirements that elevate certified inventory standards. Neuquén Basin drilling clusters around Añelo and Rincón de los Sauces generate concentrated demand for extended-reach tubing strings.
Chile
ENAP and private concessionaires deploy slimhole intervention strings for mature onshore fields in the Magallanes Basin. The country's national energy regulator enforces well integrity assessment cycles that accelerate equipment replacement timelines. Punta Arenas and Tierra del Fuego host the southernmost coiled tubing service infrastructure in the Americas.
Colombia
Ecopetrol and independent operators utilize standard-grade tubing for workover campaigns in the Llanos and Middle Magdalena basins. ANH hydrocarbon agency directives require documented corrosion management plans for all artificial lift installations. Bogotá and Villavicencio anchor the procurement and field engineering support networks for eastern plains operations.
Latin America Coiled Tubing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Latin American coiled tubing markets. The vendor base stratifies into three tiers: integrated oilfield service conglomerates with captive tubing inventories, regional equipment fabricators with dedicated supply chains, and niche composite material specialists. Two dominant competitive moves define current positioning: strategic partnerships between tubing manufacturers and automation platform providers, and geographic expansion through dedicated service bases in Brazil and Mexico.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company anchor premium intervention contracting through proprietary automation platforms and captive equipment inventories. These Houston-based entities exemplify the channel-control archetype, bundling tubing deployment with real-time diagnostics to displace fragmented rental models. Their positioning reflects the structural shift toward single-vendor accountability for complex deepwater operations.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Tenaris |
| Weatherford International |
| National Oilwell Varco |
| Jereh Group |
| Royal IHC |
| Calfrac Well Services Ltd. |
| Others |
Supply & Pricing Matrix
Freight corridors connecting Houston to Macaé concentrate logistics costs for heavy-wall coiled tubing shipments, compressing margins for regional fabricators while amplifying price premiums for certified alloy grades in Brazil's pre-salt basins.
Pricing Analysis
Cost-plus contracts indexed to ferroalloy price benchmarks dominate procurement for chromium-molybdenum tubing strings. Price differentiation rests on API 5ST certification tier and sour-service rating, with premium heavy-wall systems commanding substantial markups over standard carbon grades. Pricing pressure stems from Brazilian import dependency for large-diameter reel systems, forcing distributors to absorb currency volatility. National oil companies exhibit lowest price sensitivity due to bundled service mandates, while provincial onshore operators in Argentina and Mexico drive hardest bargain on standard-grade rentals.
Supply Chain Analysis
Tariff exposure between the United States and Brazil elevates landed costs for seamless tubing coil imports. Manufacturing concentrates in the United States, China, and Italy for base steel feedstock, with domestic reel fabrication limited to São Paulo industrial corridors. Raw material dependencies center on chromium-molybdenum ferroalloys, high-strength carbon steel slabs, and thermoplastic liner polymers. Single-source vulnerability pervades large-diameter spooling system procurement. Distribution runs through integrated service company inventories rather than independent rental pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power concentrates among Petrobras, Pemex, and YPF through integrated contracting mandates, fragmenting procurement authority away from fragmented equipment rental tiers.
For Market Incumbents: Insulate captive market positions by deepening backward integration into alloy steel feedstock sourcing and securing exclusive reel maintenance contracts in Macaé and Ciudad del Carmen. Certification investment in ANP Resolution 847/2021-compliant fiber-optic telemetry systems defends against automation-platform displacement by Schlumberger and Halliburton. For New Entrants and Emerging Players: Establish a beachhead in Argentina's Vaca Muerta shale coiled tubing drilling pilots, where conventional rig economics fail and incumbent service density remains lowest. Target Neuquén Basin operators with extended-reach composite string offerings, leveraging provincial equipment traceability requirements as qualification wedge. Go-to-market angle: partner with regional automation specialists to bypass proprietary platform lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap regional fabricators with certified API 5ST welding capabilities but lacking digital integration scale. Long-term viability hinges on composite material transition and real-time telemetry bundling. Acquisition archetype: São Paulo-based reel manufacturers with ANP-certified maintenance facilities. Signal to watch: Pemex integrated service contract awards shifting from three-year to five-year terms, indicating vendor consolidation appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Feedstock | Captive chromium-molybdenum sourcing insulates Brazilian fabricators from ferroalloy import volatility. |
| Fiber-Optic Telemetry Certification | ANP Resolution 847/2021 compliance unlocks premium pre-salt intervention contracting tiers. |
| Composite String Manufacturing Scale-Up | Hybrid steel-polymer systems address corrosion mandates in Santos Basin carbon dioxide injection campaigns. |
| Regional Service Base Expansion | Dedicated Macaé and Campeche facilities reduce logistics costs for deepwater platform mobilization. |
| Extended-Reach Drilling Partnerships | Vaca Muerta lateral pilots create differentiated positioning where conventional rig economics fail. |
Research Methodology
Desk research of trade flow databases, API certification registries, and ANP regulatory filings preceded structured interviews with coiled tubing operations managers, procurement leads at national oil companies, and regional equipment fabricators. Primary fieldwork with Schlumberger, Halliburton, and Baker Hughes automation platform specialists was cross-validated against Petrobras and Pemex contract award disclosures. Secondary sources included SEC 10-K filings, Brazilian customs import records, and industry association maintenance fleet surveys. Bottom-up equipment unit economics were triangulated against top-down national intervention spending estimates.
Assumptions held fixed include ANP well integrity directive enforcement intensity, Pemex procurement centralization trajectory, and Vaca Muerta shale development pace. Variables stress-tested encompass ferroalloy price volatility bands, Brazilian real exchange rate sensitivity, and composite tubing pressure rating advancement timelines. Segmentation modeling spanned material grade tier, service type bundling, and operational depth classification. CAGRs were derived from installed base replacement cycles and greenfield pre-salt development schedules across the projection horizon.
Stress conditions across oil price bands, regulatory enforcement intensity, and alloy import tariff regimes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding national oil company capital allocation priorities and equipment certification standard evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market