
 Electric Vehicle Safe Charging Inlet Market | 2026-2036
Electric Vehicle Safe Charging Inlet Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Safe Charging Inlet Market Insights
UL 2251 qualification for electric vehicle charging couplers is reorganizing competitive entry barriers across the supply base. TE Connectivity leverages deep automotive connector heritage to sustain qualification throughput across North American OEM programs. Amphenol anchors its position through integrated electromagnetic interference filtering within inlet assemblies. PHOENIX CONTACT competes on industrial-grade sealing architectures that extend operational life in harsh-climate deployments.
An electric vehicle safe charging inlet is an electromechanical interface that establishes secure power transfer between external charging equipment and onboard battery systems, typically incorporating temperature sensing, locking actuators, and IP-rated environmental sealing to prevent arc faults and moisture ingress during high-current sessions. AC inlets retain volume leadership in residential and workplace installations where overnight charging dominates, while DC fast-charging inlets capture expanding margin pools as commercial fleets and highway corridor operators prioritize rapid turnaround times. Combined inlet configurations occupy a growing niche by reducing vehicle-side part proliferation for OEMs serving dual-standard markets.
FDA oversight of materials in medical-grade mobility applications and NHTSA crash-safety protocols for high-voltage component integrity shape design verification requirements in the United States, while IEC 62196 and ECE R100 govern mechanical and electrical interoperability across European and Asian type-approval pathways. OEM procurement teams must monitor evolving ISO 17409 thermal cycling test severity and emerging cybersecurity appendices to IEC standards that will gate market access for next-generation inlet designs. Stakeholders should weigh certification backlog timelines against platform launch schedules when selecting supply partners.
Market Dynamics
Commercial fleet electrification mandates across China, Germany, and the United States are compressing supplier qualification timelines while IEC 62196 and UL 2251 certification backlogs reshape competitive entry barriers.
Growth Catalysts
- Fleet Electrification Mandates:Commercial operators in California and the European Union face binding zero-emission vehicle procurement quotas that accelerate hardware replacement cycles.
- IEC 62196 Harmonization:Cross-border standard alignment reduces OEM engineering duplication across European and Asian type-approval pathways.
- Silicon Carbide Power Electronics:Higher switching frequencies enable compact thermal management within inlet assemblies, supporting faster charge rates without footprint expansion.
Market Restraints
- Copper and Silver Price Volatility:Contact plating materials face commodity market swings that compress margin visibility for tier-two suppliers.
- Chinese Supply Concentration:Rare-earth magnet and precision stamping capacity clusters in Jiangsu and Guangdong provinces create single-source vulnerability.
- UL 2251 Testing Bottlenecks:Limited North American laboratory capacity extends qualification timelines by six to nine months for new entrant designs.
Strategic Opportunities
- Indian Charging Infrastructure:Bureau of Indian Standards certification pathways for combined AC-DC inlets remain underpenetrated relative to projected EV sales growth.
- V2G Bidirectional Hardware:Integration of power export capability opens aftermarket revenue streams for residential and commercial energy arbitrage.
- US Inflation Reduction Act:Domestic content bonuses for federally funded charging projects incentivize North American assembly investment.
Industry Challenges
- Thermal Simulation Expertise Scarcity:Finite element analysis for high-current contact heating requires specialized electromechanical engineers concentrated in automotive hubs.
- Legacy Vehicle Retrofit Complexity:Aftermarket inlet upgrades face CAN bus protocol incompatibilities with first-generation battery management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Safe Charging Inlet Market |
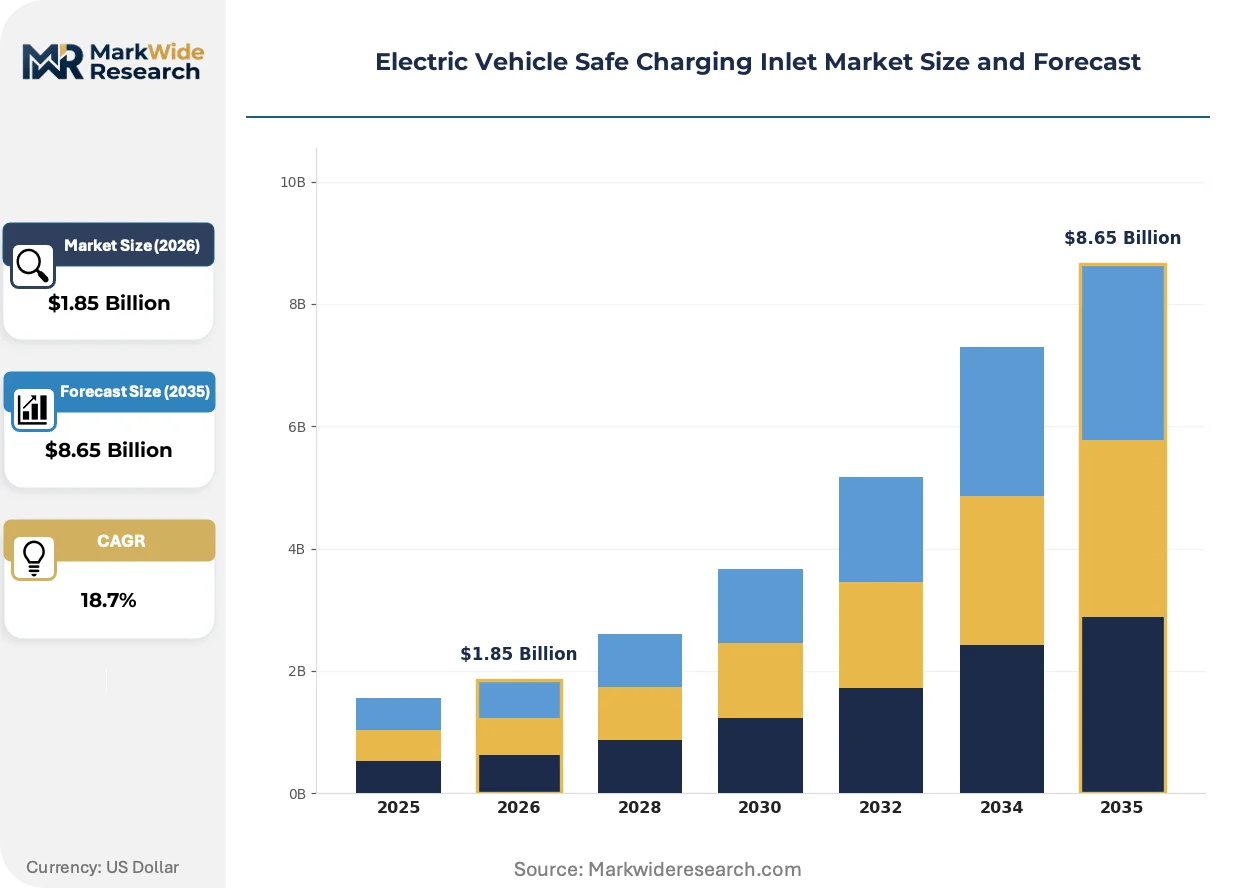
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Inlets, DC Inlets, Combined Inlets, Waterproof Inlets Installation Type: Wall-Mounted, Floor-Mounted, Portable, OEM Charging Speed: Slow Charging, Fast Charging, Ultra-Fast Charging, Standard Charging End User: Residential Users, Commercial Fleets, Public Charging Stations, Municipalities |
| Companies Covered | TE Connectivity, PHOENIX CONTACT, Amphenol, REMA Technology, ITT Cannon, YAZAKI, Schaffner, Suzhou DUOSIDA Technology, Besen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Safe Charging Inlet Market Trends and Innovations
Active materials and intelligent thermal management are compressing inlet form factors while cybersecurity appendices to IEC standards and fleet procurement centralization reshape vendor selection criteria.
Liquid-cooled contact systems is supplanting passive air-cooled designs in 350kW+ highway corridor applications. European and Chinese highway operators specify these inlets for commercial truck charging where dwell time minimization drives total cost of ownership calculations. This thermal architecture is supplanting legacy forced-air approaches that fail under sustained high-current duty cycles, narrowing the qualified supplier base to firms with sealed cooling loop expertise.
EU Cybersecurity Resilience Act implementation timelines are forcing hardware designers to embed secure boot and firmware attestation within inlet control modules. Automotive OEMs must demonstrate end-to-end encryption for locking actuator commands before type approval. German and French passenger vehicle programs face the earliest enforcement windows, compressing development schedules for 2027 platform launches.
Centralized fleet procurement departments now specify outcome-based availability contracts rather than unit hardware purchases. Logistics operators in the United States and Netherlands negotiate guaranteed uptime percentages with penalty clauses, transferring operational risk to charging hardware suppliers. This contracting shift concentrates volume with vendors capable of predictive maintenance analytics and rapid field service deployment.
Electric Vehicle Safe Charging Inlet Market Segmentation
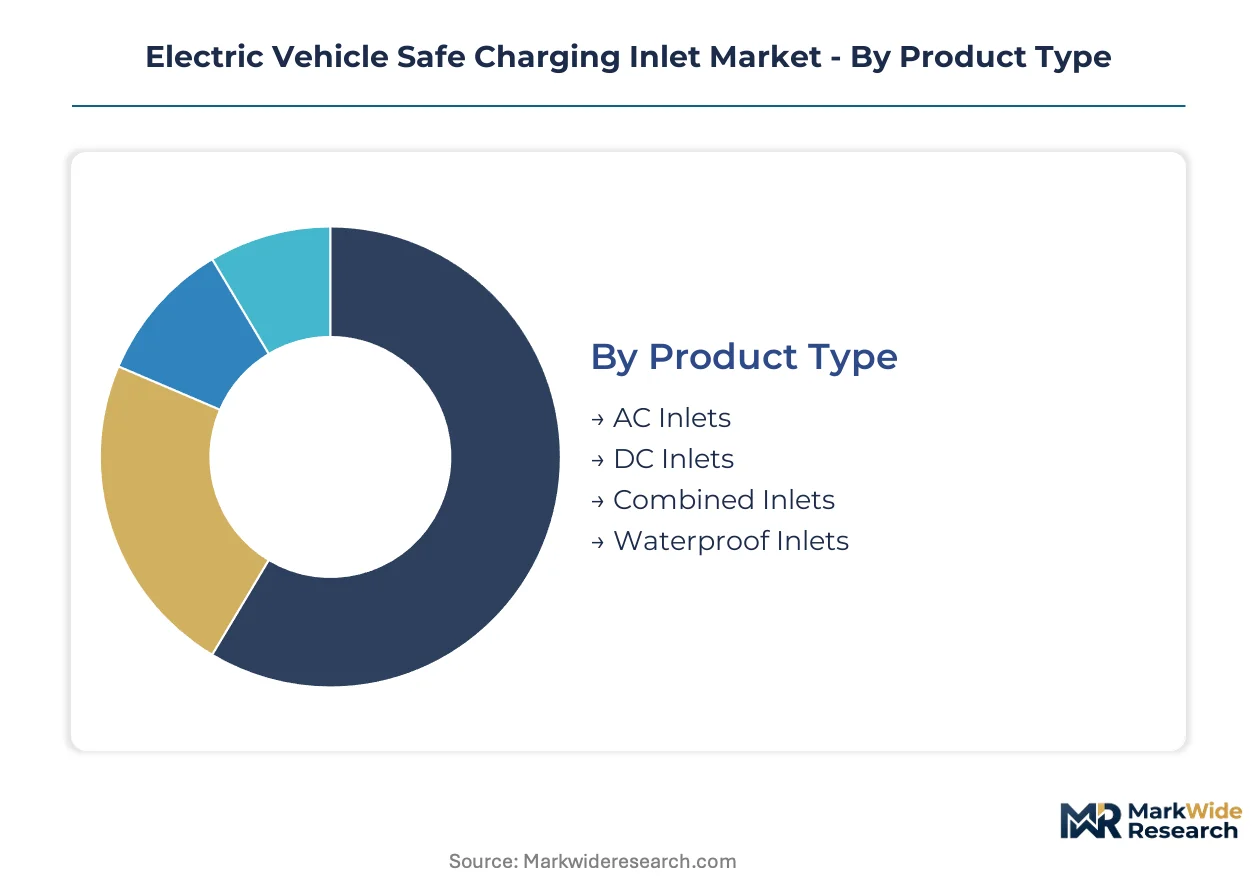
Segmentation in the electric vehicle safe charging inlet market reveals distinct technical and commercial fault lines. Product architecture, installation modality, charge rate capability, and end-use economics each create separate competitive arenas with diverging margin structures and qualification barriers.
Product Type:
Combined inlets face the most acute substitution pressure as OEMs weigh dedicated AC or DC architectures against unified solutions that reduce vehicle-side complexity.
- AC Inlets:These single-phase or three-phase interfaces handle up to 43kW for residential and workplace overnight charging cycles. Demand concentrates in Germany and China where garage-installed Level 2 hardware dominates private vehicle charging patterns, though IEC 62196 Type 2 and Type 1 regional variants force connector diversification.
- DC Inlets:High-current designs incorporating liquid-cooled contacts support 150kW to 350kW highway corridor sessions. Fleet operators in the United States prioritize CCS1 configurations for commercial truck electrification mandates, compressing supplier qualification timelines for UL 2251 certification.
- Combined Inlets:Integrated AC-DC architectures reduce OEM part proliferation for dual-standard markets. These assemblies face cost penalties against dedicated alternatives while offering simplified vehicle packaging.
- Waterproof Inlets:IP67-rated sealing systems target marine, construction, and extreme-climate deployments. Niche volume follows outdoor infrastructure expansion in Nordic municipalities and coastal Chinese provinces.
AC inlets retain volume leadership; DC inlets hold the steepest expansion curve.
Installation Type:
Cost tier stratification separates capital-intensive fixed infrastructure from lower-entry mobile alternatives, with OEM-integrated designs commanding premium engineering margins.
- Wall-Mounted:Bracket-fixed assemblies dominate residential garage and workplace parking bay deployments. These installations leverage existing electrical infrastructure in German single-family housing and Chinese apartment complex retrofits.
- Floor-Mounted:Pedestal and bollard configurations serve curbside public charging and fleet depot environments. Municipal procurement in the Netherlands and California specifies these for urban streetscape integration.
- Portable:Detachable inlet cables and adapters address emergency charging and cross-border compatibility needs. Lower price points attract aftermarket consumers facing connector standard fragmentation.
- OEM:Vehicle-integrated assemblies built to platform-specific thermal and packaging requirements. These contracts lock in multi-year supply agreements with qualification barriers that exclude second-tier vendors.
Wall-mounted hardware captures the largest installed base; OEM integration delivers the highest per-unit margins.
Charging Speed:
Application-driven segmentation separates overnight residential cycles from commercial turnaround economics, with thermal management complexity escalating across speed tiers.
- Slow Charging:Up to 3.7kW AC interfaces for residential overnight replenishment. These legacy designs face displacement by standard-speed alternatives in new vehicle platforms.
- Standard Charging:7kW to 22kW AC systems balancing installation cost against dwell time reduction. Workplace and multi-unit residential deployments in the United States and Germany favor this bandwidth.
- Fast Charging:50kW to 150kW DC configurations serving urban retail and fleet depot applications. Retail operators in China specify these for 30-to-60-minute shopping session alignment.
- Ultra-Fast Charging:350kW+ liquid-cooled architectures for highway corridor commercial truck and passenger vehicle turnaround. European highway operators mandate these for transcontinental freight electrification corridors.
Standard charging maintains the broadest addressable footprint; ultra-fast architectures are expanding most quickly.
End User:
Customer-type concentration shapes procurement modality, with centralized fleet purchasing diverging from fragmented residential decision-making.
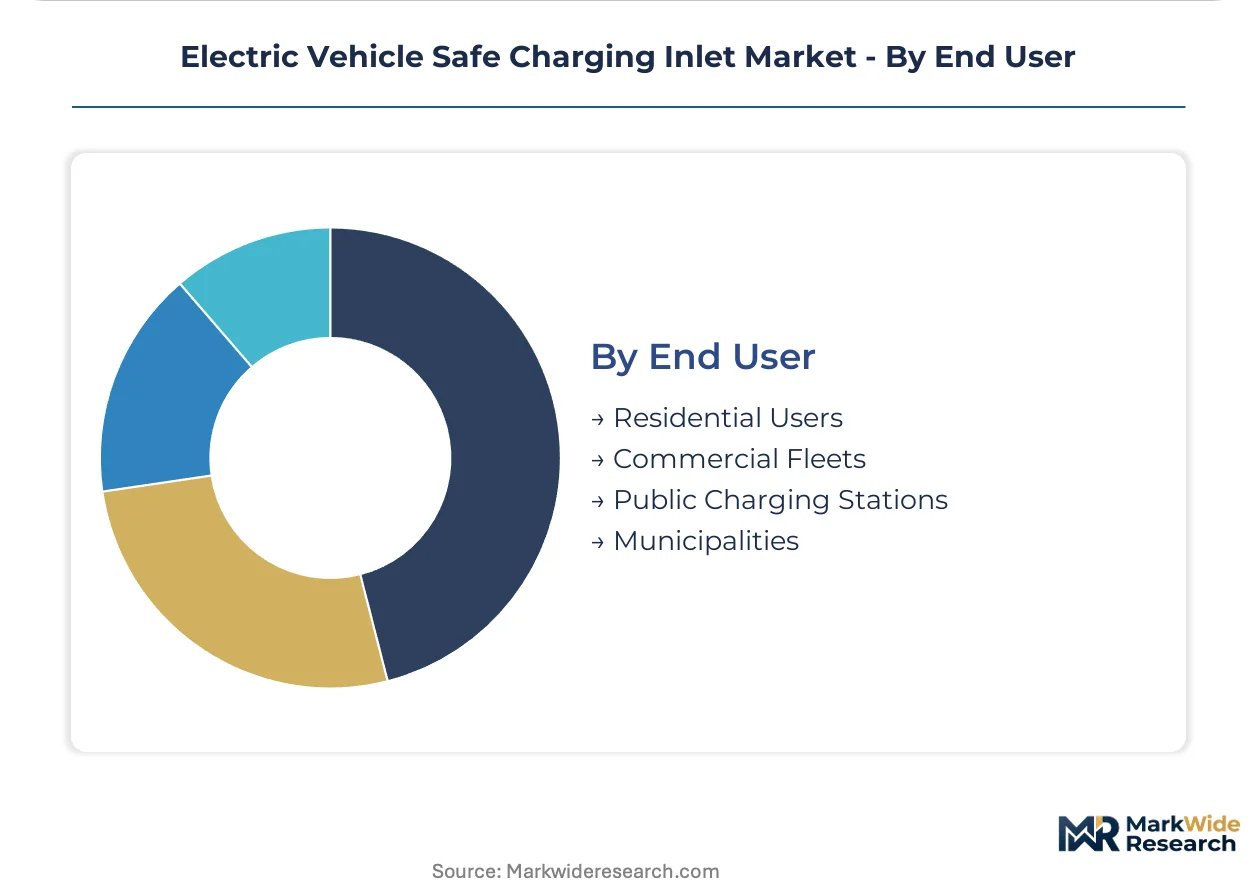
- Residential Users:Individual vehicle owners selecting garage-installed or portable solutions. Price sensitivity and installation convenience dominate purchase criteria in suburban United States and Chinese tier-two cities.
- Commercial Fleets:Logistics and delivery operators negotiating outcome-based availability contracts. Centralized procurement departments in California and the Netherlands specify guaranteed uptime percentages with penalty clauses.
- Public Charging Stations:Retail, hospitality, and highway operators deploying destination and corridor infrastructure. Revenue-per-session economics drive fast and ultra-fast charging speed selection.
- Municipalities:Government entities integrating curbside and transit depot charging into urban planning. Bureaucratic procurement cycles extend vendor qualification timelines relative to private sector counterparts.
Commercial fleets are gaining share fastest; residential users maintain the largest absolute unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators in California, logistics buyers in the Netherlands, and municipal procurement departments in Shanghai represent the three dominant buyer archetypes compressing supplier qualification timelines across major EV charging inlet markets.
United States
Fleet electrification mandates in California and federal tax incentives under the Inflation Reduction Act accelerate hardware procurement for commercial truck depots. NHTSA crash-safety protocols for high-voltage component integrity extend design verification cycles for OEM-integrated assemblies. Manufacturing concentrates in Michigan and Ohio automotive corridors where tier-one suppliers co-locate with domestic OEM platform engineering centers.
Germany
Highway corridor operators prioritize 350kW liquid-cooled architectures for transcontinental freight electrification, compressing supplier selection for ultra-fast charging hardware. ECE R100 governs mechanical and electrical interoperability alongside emerging EU Cybersecurity Resilience Act requirements for secure boot capabilities in inlet control modules. Industrial clusters in Bavaria and Baden-Württemberg host precision stamping and electromagnetic filtering specialists serving premium passenger vehicle programs.
China
State-backed charging infrastructure deployment outpaces private vehicle sales growth, with municipal governments in Shanghai and Shenzhen specifying combined AC-DC inlet configurations for public networks. GB standards and MIIT regulations shape domestic certification pathways that diverge from IEC harmonization efforts. Manufacturing gravity centers on Jiangsu and Guangdong provinces where rare-earth magnet supply and precision contact stamping capacity face single-source concentration risks.
Netherlands
Urban curbside charging procurement by municipal governments drives demand for IP67-rated floor-mounted pedestal configurations. Centralized fleet purchasing departments negotiate outcome-based availability contracts with guaranteed uptime percentages, transferring operational risk to hardware suppliers. Logistics operators in the Randstad region specify fast-charging hardware for 30-to-60-minute turnaround cycles aligned with distribution center operations.
India
Bureau of Indian Standards certification pathways for combined AC-DC inlets remain underpenetrated relative to projected EV sales growth in Maharashtra and Karnataka state markets. Central Electricity Authority technical standards for charging infrastructure safety create regulatory clarity gaps that extend vendor qualification timelines. Automotive component clusters in Pune and Chennai attract tier-two suppliers seeking proximity to emerging domestic OEM electrification programs.
Electric Vehicle Safe Charging Inlet Market Competitive Landscape
Player mix skews toward diversified connector conglomerates with automotive heritage, industrial-grade sealing specialists, and electromagnetic interference filtering experts. Market structure concentrates around tier-one suppliers capable of managing multi-year OEM platform agreements with embedded thermal management and cybersecurity capabilities. Strategic archetypes include automotive-heritage diversified conglomerates, industrial sealing architecture specialists, and electromagnetic compatibility component integrators. Competitive moves center on qualification throughput acceleration and North American laboratory capacity expansion to bypass UL 2251 testing bottlenecks.
Among automotive-heritage diversified conglomerates, TE Connectivity and YAZAKI occupy positions leveraging deep OEM connector engineering relationships across North American and Japanese vehicle programs. Amphenol sits within the electromagnetic filtering specialist tier, while PHOENIX CONTACT exemplifies industrial-grade sealing architecture capabilities for harsh-climate deployments. These three anchors represent distinct competitive vectors—automotive qualification throughput, integrated signal integrity, and environmental resilience—that shape procurement team vendor selection criteria.
| Leading Market Players |
|---|
| TE Connectivity |
| PHOENIX CONTACT |
| Amphenol |
| REMA Technology |
| ITT Cannon |
| YAZAKI |
| Schaffner |
| Suzhou DUOSIDA Technology |
| Besen |
| Others |
Pricing and Supply Chain Analysis
Ninety-day qualification backlogs at UL 2251 testing laboratories concentrate pricing power among incumbent suppliers with pre-certified architectures while compressing margin visibility for tier-two vendors awaiting approval. This lead-time asymmetry rewards automotive-heritage conglomerates with existing OEM platform relationships and penalizes new entrants facing extended cash-conversion cycles.
Pricing Analysis
Cost-plus contracts indexed to copper and silver commodity benchmarks dominate procurement between tier-one suppliers and commercial fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates UL 2251-certified assemblies with liquid-cooled contacts from uncertified alternatives and generic aftermarket adapters. Cost compression in standard-speed AC inlets is intensifying because Chinese manufacturers with captive stamping capacity are exporting below European production costs. Residential users exhibit highest price sensitivity, while OEM integration teams prioritize thermal performance over unit economics.
Supply Chain Analysis
Inventory buffers of rare-earth magnets and precision copper stampings have compressed to three-to-four weeks across Jiangsu and Guangdong manufacturing clusters, exposing downstream assemblers to spot-market volatility. Production gravity centers on China, Germany, and the United States, with contact plating and electromagnetic filtering components drawing from Japanese and South Korean specialty metal suppliers. Single-source vulnerability in Jiangsu rare-earth magnet capacity creates tariff-agnostic supply risk regardless of trade policy shifts. Distribution runs through tier-one automotive supplier networks rather than open-market channels, locking aftermarket access behind OEM service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle safe charging inlet market exhibits cyclical recovery characteristics as fleet electrification mandates compress replacement cycles and resuscitate capital expenditure timelines deferred during platform consolidation periods.
For Market Incumbents: Fortify qualification throughput advantages by expanding North American laboratory partnerships to bypass UL 2251 bottlenecks. Deepen backward integration into liquid-cooled contact systems to defend margin position against silicon carbide thermal management disruptors. Prioritize cybersecurity certification investment ahead of EU Cybersecurity Resilience Act enforcement windows.
For New Entrants and Emerging Players: Anchor in Indian combined AC-DC inlet certification pathways where Bureau of Indian Standards approval remains underpenetrated relative to state-level EV adoption curves in Maharashtra and Karnataka. Target municipal procurement departments in Nordic municipalities specifying IP67-rated floor-mounted configurations for curbside deployment. Pursue joint development agreements with European highway corridor operators seeking 350kW liquid-cooled architectures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant automotive connector divisions lacking EV-specific thermal management capabilities. Five-to-ten-year viability hinges on cybersecurity-integrated control module expertise rather than legacy contact physics. Monitor UL 2251 certification backlog durations as inflection indicator for incumbent pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| North American Laboratory Capacity Expansion | UL 2251 testing throughput acceleration compresses new entrant qualification timelines by six to nine months. |
| Liquid-Cooled Contact System Backward Integration | Captive cooling loop production insulates margins from specialty thermal component spot-market volatility. |
| Cybersecurity Control Module Development | Secure boot and firmware attestation capabilities satisfy EU Cybersecurity Resilience Act type-approval requirements. |
| Indian BIS Certification Pathway Investment | Early-mover advantage in combined AC-DC inlet approval captures Maharashtra and Karnataka state procurement cycles. |
| Fleet Availability Contract Capability Buildout | Predictive maintenance analytics and rapid field service deployment satisfy outcome-based uptime guarantees with penalty clauses. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement directors, commercial fleet maintenance managers, and charging infrastructure deployment contractors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against IEC 62196 certification databases, NHTSA high-voltage component safety filings, UL 2251 test laboratory capacity reports, and customs trade data for copper and silver contact plating materials. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around fleet electrification mandate enforcement timelines and commodity price volatility bands shaped the forecast framework. Modeled dimensions span product architecture, installation modality, charging speed tier, and end-user procurement type, with additional granularity on regional regulatory cluster alignment. CAGRs derived from segment-level volume build-ups incorporating vehicle production forecasts and content-per-vehicle assumptions. Silicon carbide power electronics adoption curves and cybersecurity certification penetration rates served as industry-specific demand drivers.
Decision-makers should treat outputs as directional under stable regulatory enforcement and commodity price assumptions; material deviation in UL 2251 backlog durations or rare-earth magnet supply disruptions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Public EV Charger Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market