
 France Electric Vehicle Charging Equipment Market | 2026-2036
France Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Charging Equipment Market Insights
Vehicle-to-grid bidirectional power flow is tilting charger architecture toward dual-use hardware. Schneider Electric SE leverages its energy management software to anchor grid-integrated charging deployments. DBT-CEV sustains manufacturing scale through specialized DC fast charger production for highway corridors. Izivia competes via its dominant position within the Corri-Door public charging network.
France electric vehicle charging equipment comprises conductive power transfer systems rated from 3.7 kW residential AC units to 350 kW DC fast chargers, incorporating power electronics, cooling subsystems, and communication protocols for grid interaction. AC chargers occupy the volume base across residential and workplace installations where dwell times accommodate slower replenishment. DC fast chargers capture concentrated margin pools along autoroute service stations and fleet depots where throughput economics prioritize speed. Smart chargers are gaining structural traction as utilities and energy providers deploy load-balancing firmware to manage grid stress.
France's national regulator for energy, the Commission de Régulation de l'Énergie, oversees grid connection tariffs that directly shape charger deployment economics. The EU Green Deal and France's Loi de Programmation Pluriannuelle de l'Énergie mandate transport decarbonization pathways that hardwire charging infrastructure into municipal planning permits. ANSM and CNIL frameworks govern data privacy for connected charging transactions. Stakeholders must monitor how grid tariff reforms and local permitting timelines redistribute deployment incentives across metropolitan and rural catchments.
Market Dynamics
Vehicle-to-grid bidirectional power flow is forcing charger architecture toward dual-use hardware capable of both replenishment and grid stabilization services. This structural shift reconfigures deployment economics across residential, commercial, and highway corridor installations.
Growth Catalysts
- EU Green Deal:France's Loi de Programmation Pluriannuelle de l'Énergie mandates transport decarbonization pathways that hardwire charging infrastructure into municipal planning permits.
- Fleet electrification:Commercial operators across Île-de-France and Auvergne-Rhône-Alpes are scaling depot charging programs that anchor DC fast charger demand.
- Smart grid integration:Utilities deploy load-balancing firmware to manage grid stress, expanding addressable market for bidirectional-capable units.
Market Restraints
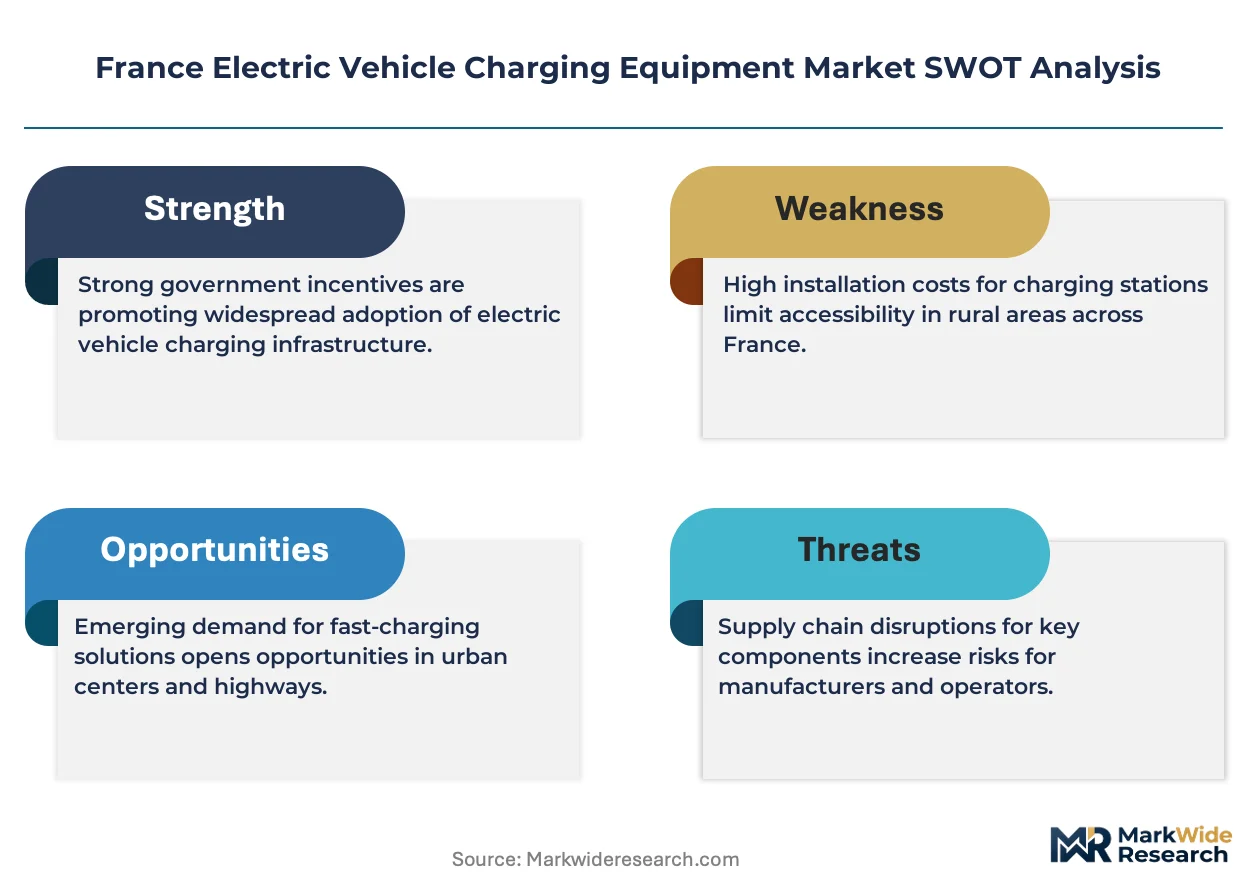
- Grid connection tariffs:Commission de Régulation de l'Énergie tariff structures compress deployment margins in rural catchments where utilization rates lag metropolitan corridors.
- Power electronics concentration:Semiconductor supply for high-frequency inverters concentrates among East Asian foundries, exposing lead time volatility.
- AC charger commoditization:Residential 3.7-22 kW units face margin compression as manufacturing scales without sufficient service differentiation.
Strategic Opportunities
- Corri-Door network expansion:Highway corridor gaps between Paris, Lyon, and Bordeaux present white space for ultra-fast 350 kW deployment.
- Workplace charging mandates:Emerging obligations for commercial parking installations create captive demand pools in tertiary urban zones.
- Vehicle-to-home convergence:Bidirectional residential units enabling domestic energy arbitrage represent an underdeveloped hardware category.
Industry Challenges
- Installation workforce scarcity:Certified electricians capable of high-voltage grid connections remain concentrated in major metropolitan labor markets.
- Permitting timeline variability:Local authority processing for grid connection approvals creates deployment scheduling uncertainty across départements.
- Interoperability certification:Protocol compliance across multiple charging network operators generates firmware validation burdens for equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Charging Equipment Market |
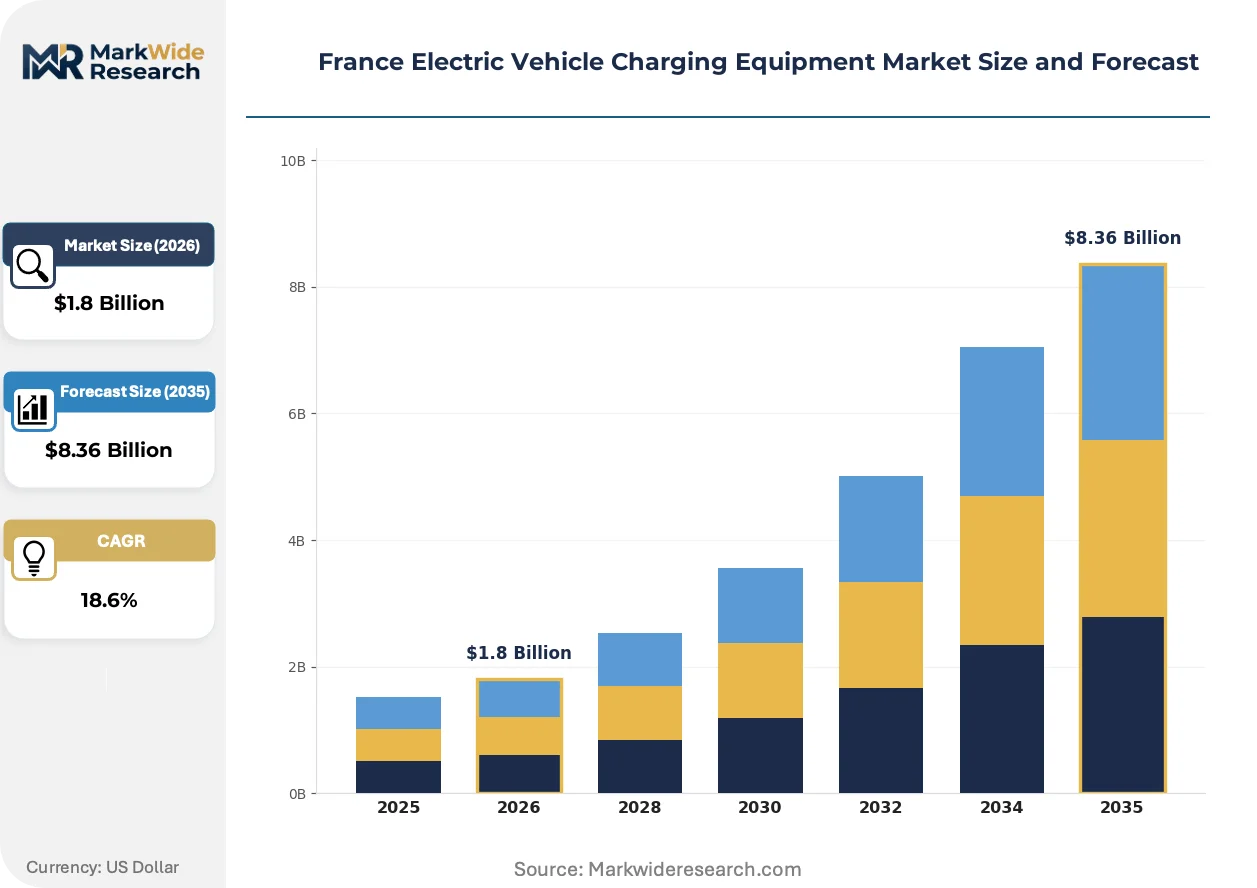
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers, Smart Chargers Installation Type: Residential, Commercial, Public, Fleet, Workplace Application: Personal Vehicles, Shared Mobility, Commercial Fleets, Government Vehicles, Car Rentals End User: Utilities, Energy Providers, Fleet Operators, Property Managers, Parking Services |
| Companies Covered | DBT-CEV, Izivia, Schneider Electric SE, Engie, TotalEnergies, ABB Ltd, Siemens AG, Legrand, EVBox Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Charging Equipment Market Trends and Innovations
Hardware architecture is converging with energy management software as charger functionality extends beyond replenishment into grid services. This evolution redefines vendor capability requirements and procurement evaluation criteria.
Silicon carbide power semiconductors are displacing traditional silicon IGBTs in DC fast charger inverters due to superior thermal efficiency and switching frequency. Highway corridor operators and fleet depots are adopting these units to minimize cooling subsystem footprint. The technology is migrating from premium 350 kW highway installations toward mid-power 150 kW commercial deployments as cost curves compress.
France's CNIL data privacy framework is tightening consent requirements for connected charging transactions that capture driver location and payment data. Equipment vendors must embed privacy-by-design protocols into firmware architecture to maintain network access eligibility. This regulatory pressure most affects public charging network operators who aggregate cross-operator roaming data.
Fleet procurement is consolidating around total-cost-of-ownership models that weight energy management software capabilities equally with hardware specifications. Energy service companies are displacing traditional equipment distributors as primary vendor relationships for large commercial operators. This shift concentrates most visibly in Île-de-France logistics and last-mile delivery electrification programs.
France Electric Vehicle Charging Equipment Market Segmentation
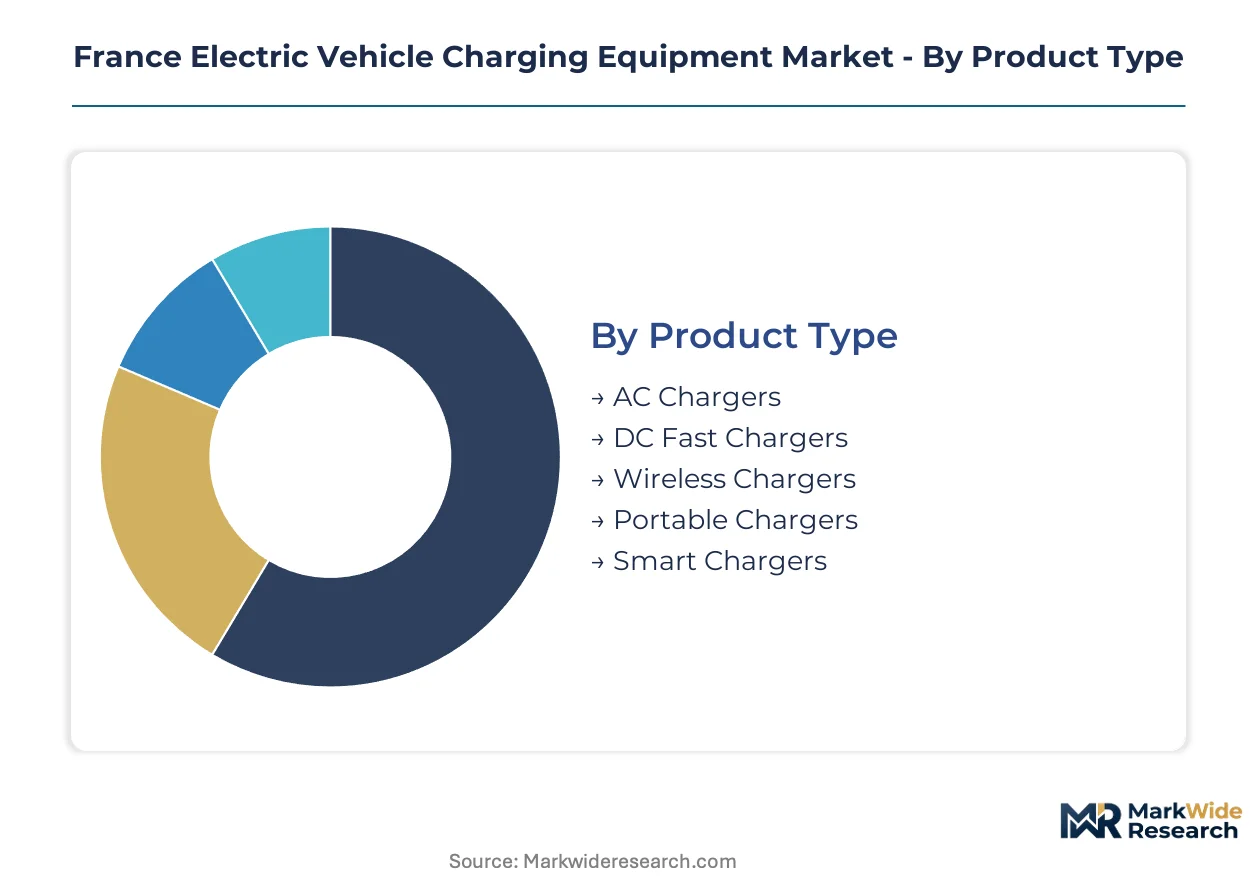
Segmentation in the France electric vehicle charging equipment market reveals how deployment economics vary across power ratings, site constraints, and customer procurement patterns. Equipment vendors must align hardware specifications with distinct utilization profiles and grid connection tariffs.
Product Type:
Power rating and current type determine installation infrastructure requirements and margin structures across the French market.
- AC Chargers:Conductive power transfer systems rated 3.7-22 kW utilizing onboard vehicle inverters for DC conversion. Demand concentrates in residential Île-de-France suburbs and Auvergne-Rhône-Alpes apartment complexes where overnight dwell times accommodate slower replenishment cycles.
- DC Fast Chargers:Offboard power electronics delivering 50-350 kW direct current with active cooling subsystems for high-frequency switching. Highway corridor operators along A6, A7, and A10 autoroutes prioritize these units for throughput economics at Corri-Door network stations.
- Wireless Chargers:Inductive power transfer systems utilizing magnetic resonance coils embedded in parking surfaces.
- Portable Chargers:Mobile 3.7-7.4 kW units with interchangeable plug configurations for emergency replenishment.
- Smart Chargers:Grid-integrated units with load-balancing firmware and vehicle-to-grid bidirectional capability.
AC chargers command the established base. The steepest expansion runs through smart chargers with bidirectional power flow.
Installation Type:
Site ownership and access control shape deployment timelines and utilization rate economics across metropolitan and rural catchments.
- Residential:Single-family home installations with dedicated meter connections and 3.7-22 kW wall-mounted units. Bordeaux and Lyon metropolitan peripheries show concentrated retrofit demand as building codes tighten parking electrification requirements.
- Commercial:Retail and hospitality parking installations with networked payment systems and variable pricing tariffs. Commission de Régulation de l'Énergie tariff reforms compress margins where utilization rates lag highway corridors.
- Public:Municipal street parking and open-access charging plazas with roaming interoperability mandates.
- Fleet:Dedicated depot installations for logistics and last-mile delivery operators with high-power DC hubs.
- Workplace:Employer-sponsored parking infrastructure with time-of-use incentives for employee vehicles.
Fleet installations anchor high-margin DC fast charger volumes. Workplace mandates are gaining share fastest as tertiary urban zones hardwire obligations into commercial permits.
Application:
Vehicle utilization intensity and duty cycles determine charging speed requirements and site hardware specifications.
- Personal Vehicles:Privately owned passenger cars with mixed urban and interurban usage patterns. Paris metropolitan households drive demand for residential and workplace installations where overnight and daytime dwell periods align with AC replenishment economics.
- Commercial Fleets:High-mileage logistics, delivery, and service vehicles with predictable depot return schedules. Île-de-France last-mile operators prioritize 150-350 kW DC hubs for rapid turnaround between shifts.
- Shared Mobility:Car-sharing and ride-hailing fleets with distributed public charging dependency.
- Government Vehicles:Municipal and state fleet electrification programs with centralized procurement.
- Car Rentals:Airport and urban location fleets with customer-operated charging requirements.
Personal vehicles dominate installed base volumes. Commercial fleets show the steepest capacity expansion as logistics electrification accelerates.
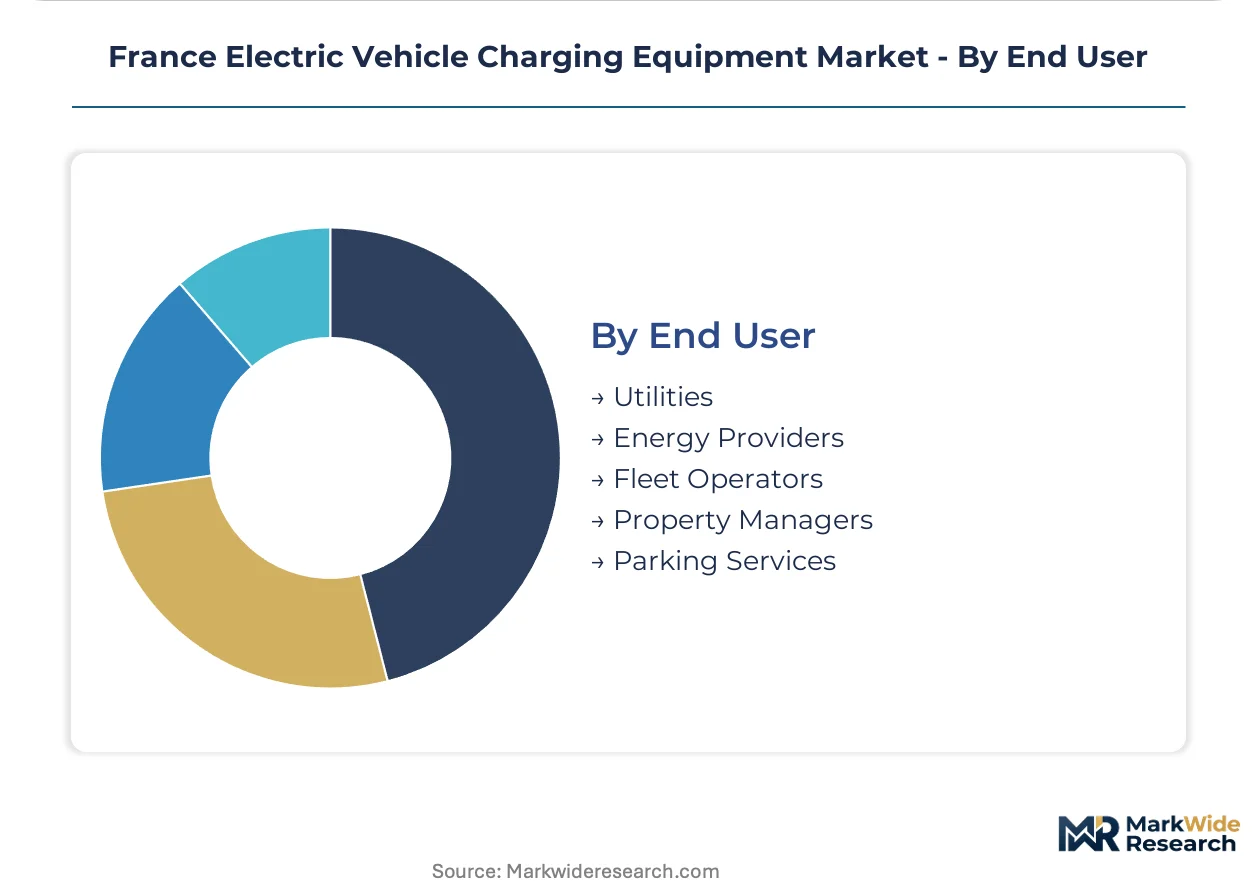
End User:
Procurement authority and energy management capabilities determine vendor relationship structures and service contract terms.
- Utilities:Grid operators deploying charging infrastructure as network edge assets with load-balancing integration. Électricité de France and Enedis anchor smart charger procurement for demand response programs.
- Fleet Operators:Commercial vehicle owners with total-cost-of-ownership procurement models weighting software capabilities equally with hardware specifications.
- Energy Providers:Retail electricity suppliers bundling charging services with tariff optimization.
- Property Managers:Residential and commercial building owners navigating multi-tenant installation cost allocation.
- Parking Services:Specialized operators managing public and private parking assets with roaming network integration.
Utilities control grid-integrated deployment pipelines. Fleet operators are climbing fastest as energy service companies displace traditional equipment distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports high-power charging components to French highway corridor operators along the A6 and A7 autoroutes. This cross-border equipment flow anchors the bilateral supply relationship between Europe's two largest EV charging markets.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg manufacture power electronics for 350 kW highway installations. The KBA enforces electromagnetic compatibility standards that French importers must certify against. Stuttgart-based engineering firms supply cooling subsystems to Corri-Door network expansion projects.
Spain
Barcelona and Madrid metropolitan zones drive cross-border demand for bidirectional charging hardware compatible with French grid protocols. Spanish energy regulators align with EU Green Deal implementation timelines that synchronize deployment permits across the Pyrenees corridor. Zaragoza logistics hubs source French-manufactured depot charging systems for fleet electrification programs.
Italy
Lombardy and Emilia-Romagna automotive suppliers integrate French charging interfaces into premium EV platforms. Italy's Ministry of Infrastructure mandates charging infrastructure in new commercial developments, creating reference architectures that French regulators observe. Turin-based fleet operators pilot vehicle-to-grid systems interoperable with French energy management software.
Netherlands
Randstad urban agglomerations deploy charging density models that French municipalities replicate in Paris and Lyon metropolitan planning. Dutch grid operators pioneer load-balancing tariffs that CRE evaluates for adaptation to French connection cost structures. Eindhoven technology clusters export smart charging firmware to French utility partnerships.
Belgium
Brussels-based EU institutions coordinate cross-border roaming standards that French network operators implement. Flanders industrial zones manufacture connector hardware for the Combined Charging System protocol dominant in French public installations. Antwerp port electrification programs source high-power DC equipment from French suppliers for heavy-duty vehicle applications.
France Electric Vehicle Charging Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Energy service companies and utility-backed operators command deployment pipelines through bundled service contracts. Equipment manufacturers concentrate margin capture in high-power DC segments while ceding residential AC volumes to price-driven assemblers. Dominant competitive moves include strategic partnerships between hardware vendors and energy management platforms, plus geographic expansion through public charging network concessions.
Among France-based specialists, DBT-CEV and Izivia occupy distinct archetype positions. DBT-CEV exemplifies the manufacturing-scale specialist focused on highway corridor hardware production. Izivia represents the network-integrated operator leveraging dominant positioning within public charging infrastructure. Schneider Electric SE anchors the diversified industrial conglomerate tier, drawing on energy management software capabilities to compete across residential, commercial, and grid-integrated deployment segments.
| Leading Market Players |
|---|
| DBT-CEV |
| Izivia |
| Schneider Electric SE |
| Engie |
| TotalEnergies |
| ABB Ltd |
| Siemens AG |
| Legrand |
| EVBox Group |
| Others |
Pricing and Supply Chain Analysis
Rhine-Alpine corridor freight costs transmit semiconductor pricing volatility into French charger manufacturing, concentrating margin pressure on DC fast charger producers while enabling silicon carbide premium tiers to sustain differentiation against commoditized AC residential units.
Pricing Analysis
Silicon carbide inverter pricing gaps separate current-generation 350 kW highway units from prior-generation silicon IGBT systems and emerging gallium nitride laboratory prototypes. Three-tier pricing structure across premium bidirectional units, standard DC fast chargers, and economy AC residential tiers reflects certification grade and cooling subsystem complexity. Pricing pressure stems from AC charger commoditization as East Asian assemblers scale 3.7-22 kW production. Fleet operators show least price sensitivity due to total-cost-of-ownership procurement models, while residential buyers concentrate price elasticity.
Supply Chain Analysis
Export controls on wide-bandgap semiconductor manufacturing equipment limit flows from Netherlands ASML licensing to Chinese foundries, reshaping sourcing geography. Power electronics concentrate in Taiwan, South Korea, and Germany. Silicon carbide substrates and high-frequency magnetic components constitute critical input dependencies. Single-source vulnerability runs through Dutch photolithography equipment for advanced inverter chips. Distribution runs through energy service companies displacing traditional equipment distributors for fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage grid connection labor scarcity constrains deployment velocity across rural départements, privileging vendors with captive installation capabilities or utility partnerships over pure hardware manufacturers.
For Market Incumbents: Build regulatory compliance moats by embedding CNIL privacy-by-design protocols and CRE tariff optimization algorithms into firmware architecture. Consolidate position through backward integration into silicon carbide semiconductor sourcing and capacity expansion in Auvergne-Rhône-Alpes manufacturing clusters. Defend against energy service company displacement by bundling predictive maintenance software with hardware procurement. For New Entrants and Emerging Players: Pursue workplace charging mandates in tertiary urban zones outside Paris, Lyon, and Bordeaux metropolitan cores where incumbent network density remains lowest. Target Corri-Door highway corridor gaps between major autoroute intersections for ultra-fast 350 kW deployment. Establish go-to-market partnerships with commercial real estate developers navigating new parking electrification permit requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerate charging divisions lacking dedicated energy management software capabilities. Long-term viability hinges on vehicle-to-grid interoperability certification and utility demand response program integration. Monitor CRE grid tariff reform announcements as inflection signals for rural deployment margin redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Migration | Reduces cooling footprint for 350 kW Corri-Door highway installations. |
| Vehicle-to-Grid Certification Investment | Unlocks Électricité de France demand response revenue streams. |
| Workplace Mandate Compliance Partnership | Captures tertiary urban commercial permit-driven captive demand. |
| Energy Service Company Acquisition | Secures fleet operator procurement relationships against hardware commoditization. |
| Rural Installation Workforce Development | Addresses certified electrician scarcity compressing département deployment timelines. |
Research Methodology
A standing panel of utility planning officers, fleet procurement directors, charging network operations managers, and CRE regulatory specialists provided ongoing calibration against market developments. Primary interviews with equipment manufacturers, energy service companies, and commercial real estate developers combined with secondary validation from ANSM device filings, CNIL privacy compliance databases, SEC 10-K disclosures, and customs import records for power electronics. Bottom-up unit deployment tracking triangulated against top-down energy demand projections.
Scenario bracketing anchored low, base, and high cases around CRE grid tariff reform timing and silicon carbide cost curve compression rates. Segmentation modeling spanned power rating tiers, installation site types, vehicle application categories, and end-user procurement authority across the projection horizon. CAGRs derived from installation run-rate extrapolation weighted by utilization economics and regional permit approval velocity. Forecast inputs incorporated fleet electrification program announcements and EU Green Deal implementation milestone tracking.
Sensitivities concentrate around semiconductor supply lead times and local authority permitting timeline variability. Forecasts reflect documented assumptions on utility load-balancing tariff adoption curves and workplace mandate enforcement intensity. Material shifts in export control regimes for wide-bandgap semiconductor manufacturing equipment or CRE grid connection cost restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Electric Vehicle DC Fast Charging Station Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market