
 Electric Vehicle Charger Operations and Maintenance Services Market | 2026-2036
Electric Vehicle Charger Operations and Maintenance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Charger Operations and Maintenance Services Market Analytics
The capability gap between self-operated networks and third-party service specialists is collapsing as charger density rises and OEM warranty periods expire. ABB leverages its electrification hardware installed base to anchor long-term service contracts across European markets. ChargePoint, Inc. competes through its integrated software platform that combines remote diagnostics with dispatched technician networks. SEAM Group differentiates by occupying the industrial safety certification niche, applying its electrical reliability expertise to high-availability fleet depots.
Electric Vehicle Charger Operations and Maintenance Services encompass the technical activities required to sustain charging infrastructure performance, including remote monitoring systems that track connector temperature, power output stability, and network communication latency to ensure 99 percent uptime compliance. These services prevent revenue loss from disabled ports and protect asset value for owners who lack in-house electrical engineering capacity. Preventive maintenance contracts currently lead the service type segment because they convert unpredictable repair costs into fixed operational expenditures that fleet operators prefer for budget planning. DC Fast Chargers represent the fastest-growing technology segment within maintenance portfolios due to their higher component stress, liquid cooling complexity, and critical role in highway corridor economics where downtime carries disproportionate revenue impact.
NHTSA guidelines on charging equipment safety inspections and EPA energy efficiency standards for grid-connected infrastructure shape service scope requirements and technician certification thresholds in the United States. The EU Green Deal and F-Gas Regulation drive refrigerant-handling protocols for cooled cable systems in European DC fast charging deployments. Stakeholders must decide whether to build captive service organizations or outsource to specialized providers as charger network scale crosses the threshold where internal maintenance economics deteriorate.
Market Dynamics
The expiration of OEM warranty periods across early charger deployments is forcing asset owners to choose between building captive service teams or outsourcing to specialized providers as network density crosses economic thresholds.
Growth Catalysts
- Fleet electrification mandates:Commercial vehicle operators in California and Germany face binding zero-emission deadlines that require contracted maintenance to guarantee uptime for revenue-critical charging assets.
- NHTSA reliability standards:Proposed federal uptime requirements for highway corridor chargers are converting reactive repair models into preventive service contracts with SLA-backed performance guarantees.
- Liquid-cooled cable proliferation:High-power charging stations above 350kW deploy thermal management systems that demand specialized refrigerant-handling technicians and recurring inspection protocols.
Market Restraints
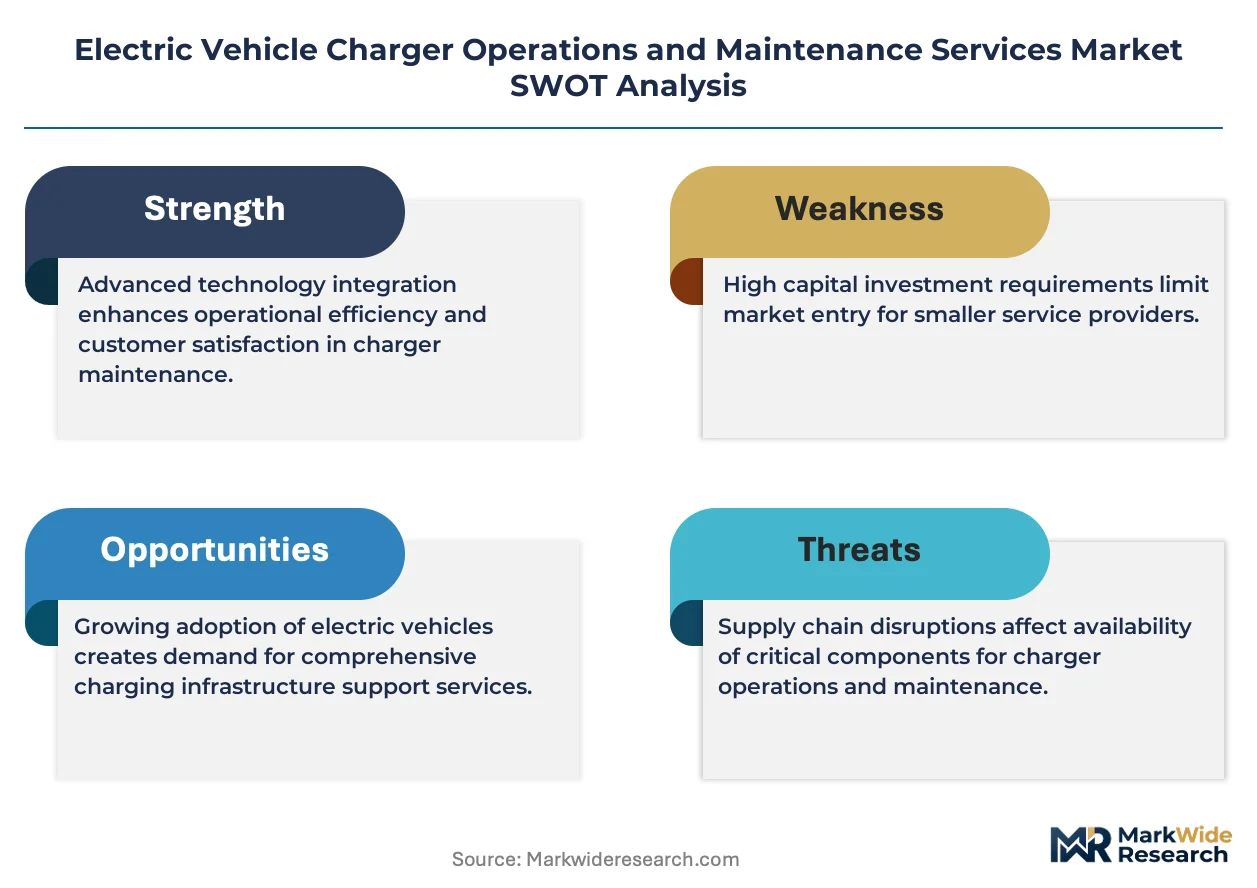
- Copper price volatility:Cable replacement and power electronics repair costs fluctuate with commodity markets, compressing fixed-price contract margins for service providers.
- Semiconductor supply concentration:Power module shortages from East Asian foundries extend lead times for control board replacements and delay outage restoration.
- Interoperability certification delays:Multi-vendor network operators face fragmented testing requirements from the Open Charge Alliance and local grid codes that prolong commissioning timelines.
Strategic Opportunities
- India's PLI scheme for charging infrastructure:Domestic manufacturing incentives are attracting service providers to establish local technician training centers ahead of fleet scale-up.
- Vehicle-to-grid integration:Bidirectional charging deployments create new revenue streams for providers who certify inverter maintenance and grid synchronization capabilities.
- EU F-Gas technician certification:Refrigerant-handling mandates for cooled cable systems create regulatory moats for European service specialists with existing HVAC credentials.
Industry Challenges
- High-voltage electrical certification scarcity:The shortage of technicians qualified for 1000V DC systems limits dispatch capacity during concurrent outage events.
- Legacy payment system integration:Service providers must maintain expertise in obsolete OCPP 1.6 protocols while migrating customers to 2.0.1 architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Charger Operations and Maintenance Services Market |
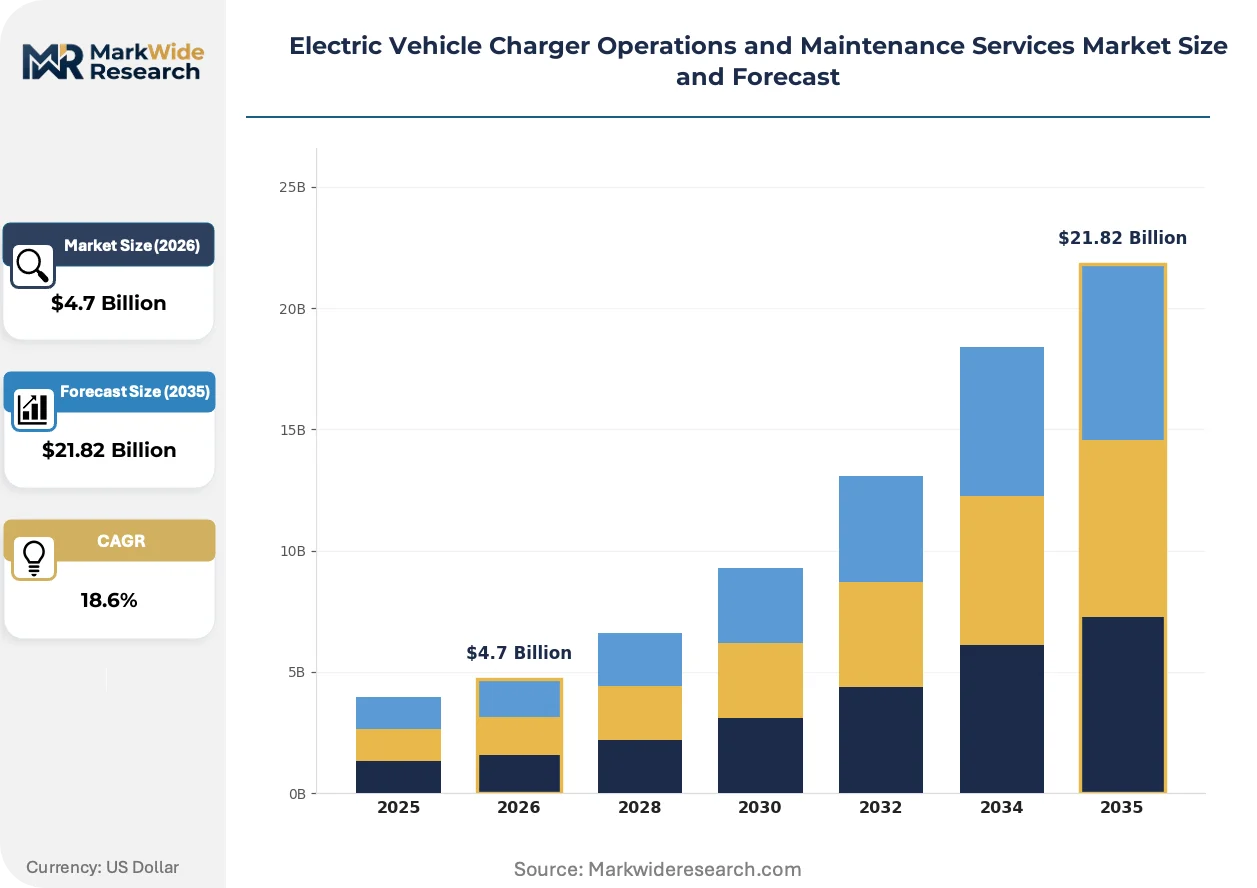
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Monitoring, Repair, Preventive Maintenance, Installation End User: Fleet Operators, Charging Network Providers, Retail Locations, Government Facilities Technology: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Charging Contract Type: Service Level Agreement, Pay-Per-Use, Subscription, Project-Based |
| Companies Covered | ChargePoint, Inc., ABB, bp pulse, EVA Global, SEAM Group, Chargerhelp!, BTC Power, eFaraday, Pearce Renewables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Charger Operations and Maintenance Services Market Evolving Landscape
Service delivery models are bifurcating between software-native remote diagnostics platforms and field-heavy technician networks as charger complexity outpaces owner technical capacity.
Predictive maintenance algorithms are fragmenting traditional scheduled service intervals by analyzing connector temperature cycles, power quality anomalies, and cable flexure data to dispatch interventions before hard failures occur. Fleet operators with centralized telematics infrastructure adopt these systems fastest, compressing the addressable market for time-based preventive contracts.
The EU Green Deal's embodied carbon disclosure requirements for infrastructure procurement are extending service scope to include component lifecycle documentation and end-of-life recycling coordination. Network operators bidding for public concession contracts must now certify circular economy protocols for power electronics and cable assemblies.
Buyer concentration among multi-thousand-unit fleet operators is compressing vendor selection cycles toward integrated platform providers who bundle hardware, software, and maintenance under unified SLAs. Single-point accountability reduces procurement friction for logistics companies managing mixed-vendor charging estates across multiple states or countries.
Electric Vehicle Charger Operations and Maintenance Services Market Segmentation
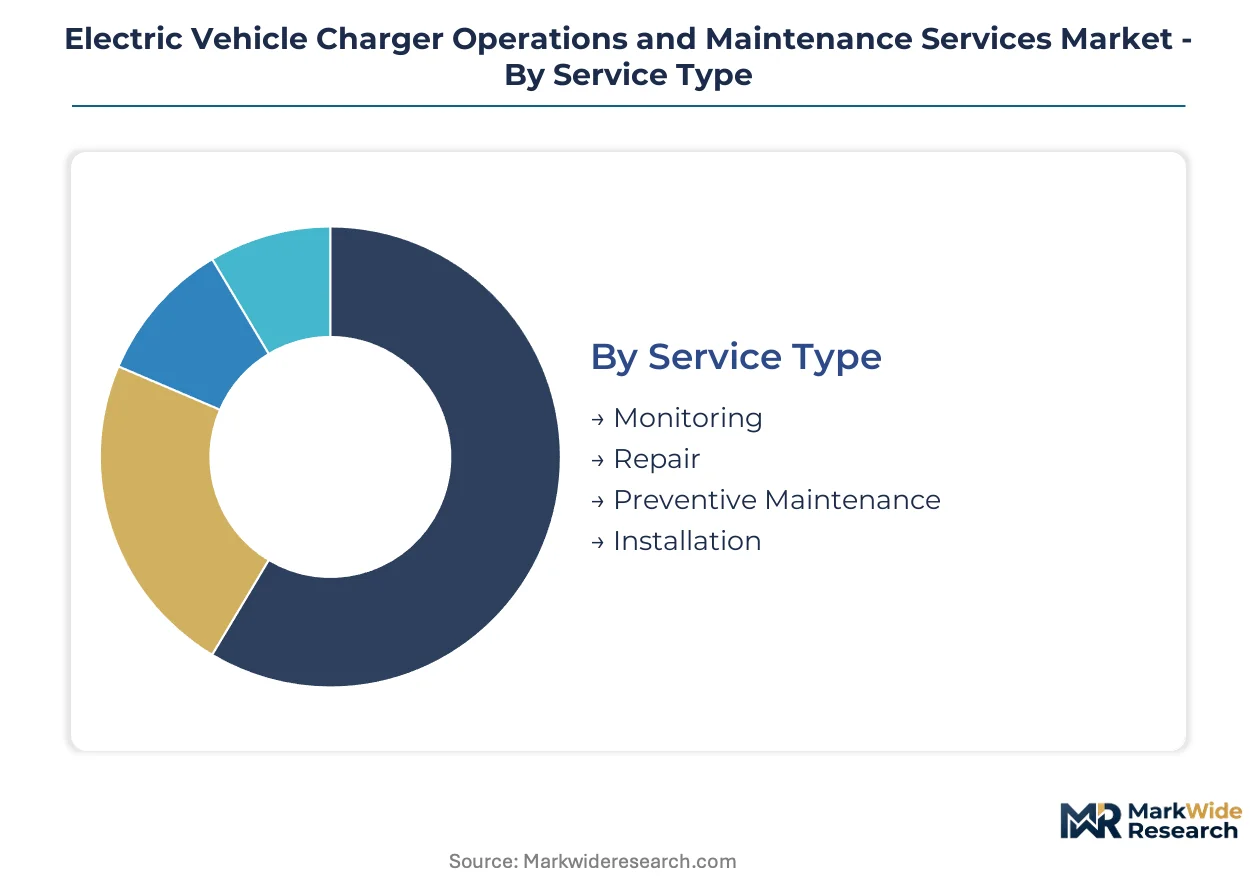
Service segmentation in EV charger operations and maintenance reveals how procurement patterns split between asset owners seeking cost predictability and those prioritizing operational flexibility. Contract structures and technology tiers determine whether providers capture recurring revenue or transactional margins.
Service Type:
German fleet operators drive contracted preventive maintenance volumes domestically, while US highway corridor operators export service specifications through NHTSA reliability mandates.
- Preventive Maintenance:Scheduled inspections, component replacement cycles, and thermal management calibration convert unpredictable repair costs into fixed operational expenditures. Fleet operators in California and Germany prefer these contracts for budget planning under binding zero-emission deadlines.
- Monitoring:Remote diagnostics platforms track connector temperature, power output stability, and network communication latency to ensure uptime compliance. Demand concentrates among charging network providers managing multi-thousand-unit estates across dispersed geographies.
- Repair:Reactive dispatch services address hard failures in power electronics and cable assemblies. Copper price volatility compresses fixed-price contract margins for these interventions.
- Installation:Commissioning services encompass electrical infrastructure connection, interoperability certification, and grid synchronization. India's PLI scheme for charging infrastructure attracts providers establishing local technician training centers.
Preventive maintenance holds the largest share; momentum sits with monitoring as predictive algorithms displace scheduled intervals.
End User:
Cost tier segmentation separates high-volume fleet operators seeking unified SLAs from fragmented retail locations tolerating pay-per-use arrangements.
- Fleet Operators:Logistics companies and commercial vehicle operators manage mixed-vendor charging estates across multiple states or countries. These buyers compress vendor selection cycles toward integrated platform providers bundling hardware, software, and maintenance.
- Charging Network Providers:Highway corridor operators and urban fast-charging networks face NHTSA uptime requirements converting reactive repair models into preventive service contracts with performance guarantees.
- Retail Locations:Shopping centers and hospitality venues deploy Level 2 chargers as amenity infrastructure with lower utilization rates. These sites tolerate longer response times and project-based service engagements.
- Government Facilities:Municipal depots and public transit electrification projects prioritize safety certification and compliance documentation. EU Green Deal embodied carbon disclosure requirements extend service scope to component lifecycle documentation.
Fleet operators command the highest contract values; government facilities are expanding most quickly under procurement mandates.
Technology:
Application intensity determines maintenance complexity, with highway-corridor DC fast chargers demanding specialized refrigerant-handling technicians unavailable in residential Level 1 service markets.
- DC Fast Chargers:High-power stations above 350kW deploy liquid-cooled cable systems with thermal management complexity. EU F-Gas Regulation drives refrigerant-handling protocols creating regulatory moats for European service specialists.
- Level 2 Chargers:Mid-power AC infrastructure dominates workplace and residential deployments. These units experience lower component stress but require broader geographic technician coverage due to dispersed installation patterns.
- Level 1 Chargers:Standard residential outlets require minimal maintenance intervention. Service providers rarely contract separately for these units, folding them into broader estate management agreements.
- Wireless Charging:Inductive pad systems demand coil alignment calibration and foreign object detection maintenance. Vehicle-to-grid integration creates new revenue streams for providers certifying inverter maintenance capabilities.
Level 2 chargers maintain installed base dominance; DC fast chargers show the steepest expansion trajectory as highway corridor density rises.
Contract Type:
Customer type segmentation tracks how buyer sophistication shapes risk allocation between providers and asset owners.
- Service Level Agreement:Multi-year contracts with uptime guarantees and penalty clauses. Fleet operators and charging network providers prefer these for revenue-critical assets where downtime carries disproportionate financial impact.
- Subscription:Fixed monthly fees covering preventive maintenance and discounted repair rates. Retail locations favor this structure for budget predictability without capital commitment.
- Pay-Per-Use:Transactional pricing for discrete interventions without ongoing commitment. Government facilities occasionally use this for legacy equipment outside primary contract scope.
- Project-Based:One-time engagements for installation, commissioning, or major overhauls. India's emerging market attracts project-based providers ahead of scaled fleet deployment.
Service level agreements capture the premium tier; subscription models are gaining share fastest among mid-market adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators command pricing premiums for preventive maintenance contracts that US highway corridor operators struggle to match under fragmented procurement regimes. This asymmetry reflects divergent regulatory enforcement and utility-backed infrastructure mandates across the two markets.
United States
California's binding zero-emission commercial vehicle deadlines drive contracted maintenance demand among logistics operators managing mixed-vendor charging estates. NHTSA reliability standards for highway corridor uptime are converting reactive repair models into SLA-backed preventive contracts. The I-95 corridor from Boston to Washington concentrates service provider dispatch networks for DC fast charger maintenance.
Germany
Utility-backed charging infrastructure mandates accelerate service outsourcing as network density crosses internal maintenance thresholds. The EU F-Gas Regulation creates regulatory moats for technicians certified in refrigerant-handling for liquid-cooled cable systems. The Rhine-Ruhr metropolitan region anchors the densest concentration of third-party service specialists serving fleet depots.
China
State Grid Corporation's nationwide charging network expansion generates demand for localized maintenance capabilities across provincial markets. MIIT standards for high-voltage electrical safety shape technician certification requirements for 1000V DC systems. The Yangtze River Delta around Shanghai hosts the largest concentration of independent service providers outside state-owned utilities.
India
The PLI scheme for charging infrastructure attracts service providers establishing technician training centers ahead of fleet scale-up. Central Electricity Authority grid codes for EV charging stations mandate interoperability certification that prolongs commissioning timelines. The Delhi-Mumbai Industrial Corridor concentrates early deployment of maintenance contracts for commercial vehicle electrification.
United Kingdom
Highway England's rapid charging fund specifications require 99 percent uptime guarantees that favor integrated service providers over fragmented repair networks. The UK Net Zero Strategy accelerates public sector fleet electrification with bundled maintenance procurement. The Midlands region around Birmingham hosts emerging specialist training facilities for high-power charging thermal management.
Electric Vehicle Charger Operations and Maintenance Services Market Competitive Landscape
Concentration sits with electrification hardware incumbents leveraging installed base advantages to anchor long-term service contracts. The vendor base fragments across software-native diagnostics platforms, field-heavy technician networks, and industrial safety certification specialists. Three archetypes dominate: integrated hardware-service providers, pure-play software platforms, and electrical reliability specialists crossing over from industrial safety markets. Competitive moves center on captive technician training investments and predictive maintenance algorithm development.
Within the integrated platform tier, ABB and ChargePoint, Inc. exemplify contrasting approaches to service bundling. ABB leverages its electrification hardware footprint across European markets to lock in preventive maintenance contracts. ChargePoint, Inc. competes through software-native remote diagnostics combined with dispatched technician networks. SEAM Group occupies the industrial safety certification niche, applying electrical reliability expertise to high-availability fleet depot requirements.
| Leading Market Players |
|---|
| ChargePoint, Inc. |
| ABB |
| bp pulse |
| EVA Global |
| SEAM Group |
| Chargerhelp! |
| BTC Power |
| eFaraday |
| Pearce Renewables |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation technician certification gates both service provider qualification and contract pricing tiers simultaneously. Buyers with refrigerant-handling mandates pay configured-to-order premiums for cooled-cable maintenance, while standard preventive contracts compete on technician density and response-time guarantees.
Pricing Analysis
Configured-to-order pricing for liquid-cooled cable maintenance commands spreads over standard Level 2 service contracts. Subscription models dominate fleet operator procurement, converting unpredictable repair costs into fixed operational expenditures. Price differentiation hinges on SLA uptime guarantees and F-Gas certification tiers. Copper price volatility is compressing fixed-price repair margins because commodity fluctuations pass through to cable replacement costs. Retail locations show highest price sensitivity, while highway corridor operators absorb premiums for 99 percent uptime guarantees.
Supply Chain Analysis
China and South Korea anchor power module fabrication for DC fast charger control electronics. Germany and the United States produce specialized high-voltage cable assemblies and thermal management components. Semiconductor supply concentration in East Asian foundries creates single-source vulnerability for control board replacements. Distribution runs through electrification hardware OEMs and third-party service networks to fleet depots and charging network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV charger maintenance sits in early-cycle expansion as fleet electrification mandates force asset owners from self-operation to contracted service models.
For Market Incumbents: Consolidate technician training investments around high-voltage DC certification and predictive maintenance algorithm development. Hardware OEMs with installed base advantages should deepen captive service penetration before pure-play software platforms scale dispatched networks. The threat of integrated platform providers bundling diagnostics and field service demands faster certification pipeline expansion in Germany and California. For New Entrants and Emerging Players: Lead with refrigerant-handling capabilities in European markets where EU F-Gas Regulation creates regulatory moats. India's PLI scheme for charging infrastructure offers the most penetrable geography for technician training center establishment ahead of fleet scale-up. A go-to-market angle targeting government facilities under embodied carbon disclosure requirements captures procurement mandates faster than fragmented retail location competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across DC fast charger service portfolios as liquid-cooled cable proliferation demands specialized equipment and certification investments. Long-term viability favors providers with unified software-field service platforms over fragmented repair networks. Acquisition targets should show technician density in the I-95 corridor or Rhine-Ruhr region. The signal to watch is NHTSA reliability standard finalization converting reactive repair volumes to preventive contract structures.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Expansion | F-Gas and high-voltage DC credentials create regulatory moats in European and US markets. |
| Predictive Maintenance Platform Development | Remote diagnostics displace scheduled intervals and compress addressable market for time-based contracts. |
| Geographic Dispatch Network Density | Concentrated technician coverage in highway corridors reduces SLA penalty exposure. |
| Backward Integration into Spare Parts Inventory | Captive supply of power modules and cable assemblies insulates against semiconductor lead time volatility. |
| Vehicle-to-Grid Certification Investment | Bidirectional charging maintenance capabilities unlock new revenue streams from grid synchronization services. |
Research Methodology
Cross-validation between primary fieldwork and regulatory filing analysis anchors the qualitative findings. Interviews with fleet operations directors, charging network asset managers, field service technicians, and utility electrification planners combined with secondary validation from NHTSA guidance documents, EU F-Gas Regulation filings, and SEC disclosures from electrification hardware OEMs. Bottom-up service contract value estimates triangulate against top-down infrastructure deployment projections.
Sensitivity analysis around copper price trajectories and semiconductor lead time assumptions tests forecast robustness across the projection horizon. Segmentation dimensions include service type, charger technology tier, contract structure, and end-user category. CAGRs derive from installed base growth curves and maintenance intensity coefficients by power level. Forecast inputs incorporate fleet electrification mandate timelines and warranty expiration schedules from early charger deployments.
The analysis sits within stated boundaries; outcomes outside NHTSA reliability standard adoption or EU Green Deal enforcement trajectories would require recalibration. Forecasts reflect assumptions about technician certification pipeline expansion and commodity price stabilization. Recalibration cycles align with material shifts in fleet electrification deadlines or refrigerant-handling regulatory amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Global EV Charging Adapter Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Portable Charging Units Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Solar Carport Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger Market