
 Saudi Arabia Solar Energy Market | 2026-2036
Saudi Arabia Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Solar Energy Market Analytics
Single-axis tracking systems paired with bifacial photovoltaic modules is reconfiguring energy yield profiles for utility-scale installations across the Kingdom. ACWA Power anchors the project development pipeline through long-term offtake structures and local consortium leadership. JinkoSolar leverages high-efficiency monocrystalline cell production to compete on levelized cost metrics in tender rounds. First Solar differentiates through thin-film cadmium telluride technology optimized for high-temperature desert operating conditions.
Solar energy in Saudi Arabia encompasses photovoltaic and concentrated solar power systems engineered to convert irradiance into electricity, with utility-scale plants typically specifying module efficiencies above twenty-one percent and operating temperatures up to eighty-five degrees Celsius for desert deployment. Photovoltaic systems dominate current capacity additions, while concentrated solar power with thermal storage captures premium margin pools through dispatchable evening supply. Utility-scale installations lead deployment volumes, though commercial rooftop segments show structural acceleration as net-metering frameworks mature.
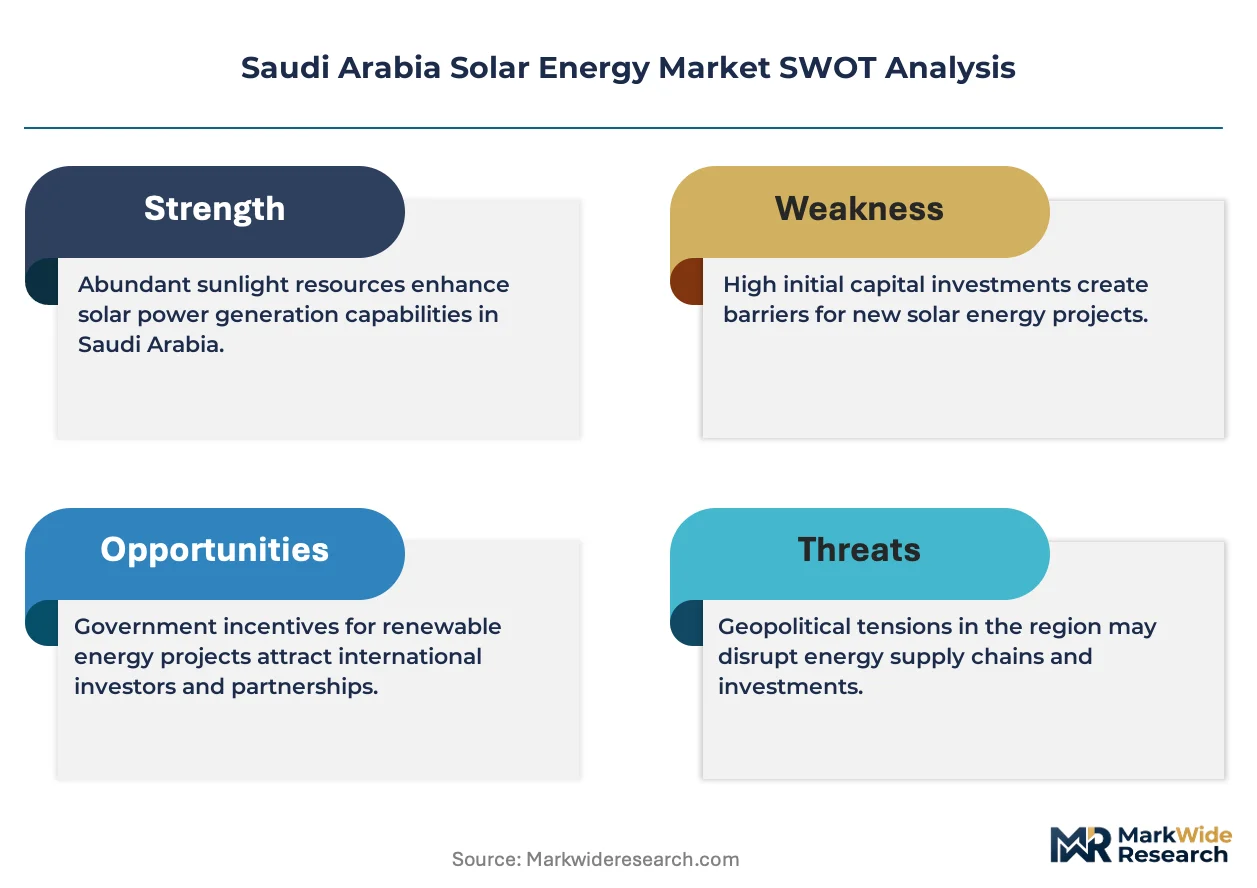
SFDA and the Saudi Electricity Regulatory Authority shape market access through grid interconnection standards and power purchase agreement templates, while the Saudi Green Initiative and Vision 2030 targets mandate renewable procurement quotas for state-linked industrial consumers. Stakeholders must monitor auction clearing prices and localization requirements as the Kingdom scales domestic module assembly capacity.
Market Dynamics
Bifacial photovoltaic modules paired with single-axis tracking systems are compressing levelized cost thresholds for utility-scale installations across the Kingdom's desert corridors. This technology convergence is forcing developers to reconfigure plant layouts and procurement specifications to capture bifacial gain coefficients.
Growth Catalysts
- Saudi Green Initiative procurement quotas:State-linked industrial offtakers in petrochemical and desalination complexes face binding renewable energy mandates under Vision 2030 targets.
- Western Province irradiance concentration:Gigawatt-scale project clusters near Tabuk and Neom leverage superior solar resource profiles for capacity factor optimization.
- Bifacial module technology maturation:Rear-side energy capture from albedo reflection is improving plant economics without proportional land footprint expansion.
Market Restraints
- Polysilicon supply concentration:Upstream ingot and wafer production concentrates in East Asian manufacturing hubs, exposing Saudi projects to input cost volatility and logistics bottlenecks.
- Desert thermal derating:Module operating temperatures reaching eighty-five degrees Celsius impose efficiency penalties on crystalline silicon technologies during peak irradiance hours.
- Grid interconnection standards:Saudi Electricity Regulatory Authority technical codes create procedural friction for utility-scale project commissioning timelines.
Strategic Opportunities
- Concentrated solar power with thermal storage:Molten salt systems capture premium margin pools through dispatchable evening supply to industrial offtakers requiring baseload reliability.
- Commercial rooftop acceleration:Net-metering framework maturation unlocks distributed generation potential across Riyadh and Jeddam commercial building stock.
- Domestic module assembly localization:Saudi Green Initiative incentive structures support in-country manufacturing capacity to satisfy local content requirements in tender rounds.
Industry Challenges
- EPC contractor capability scarcity:Gigawatt-scale project pipelines exceed available engineering and construction workforce with desert deployment experience.
- Hybrid integration complexity:Co-location of photovoltaic and concentrated solar power systems with battery storage requires novel control system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Solar Energy Market |
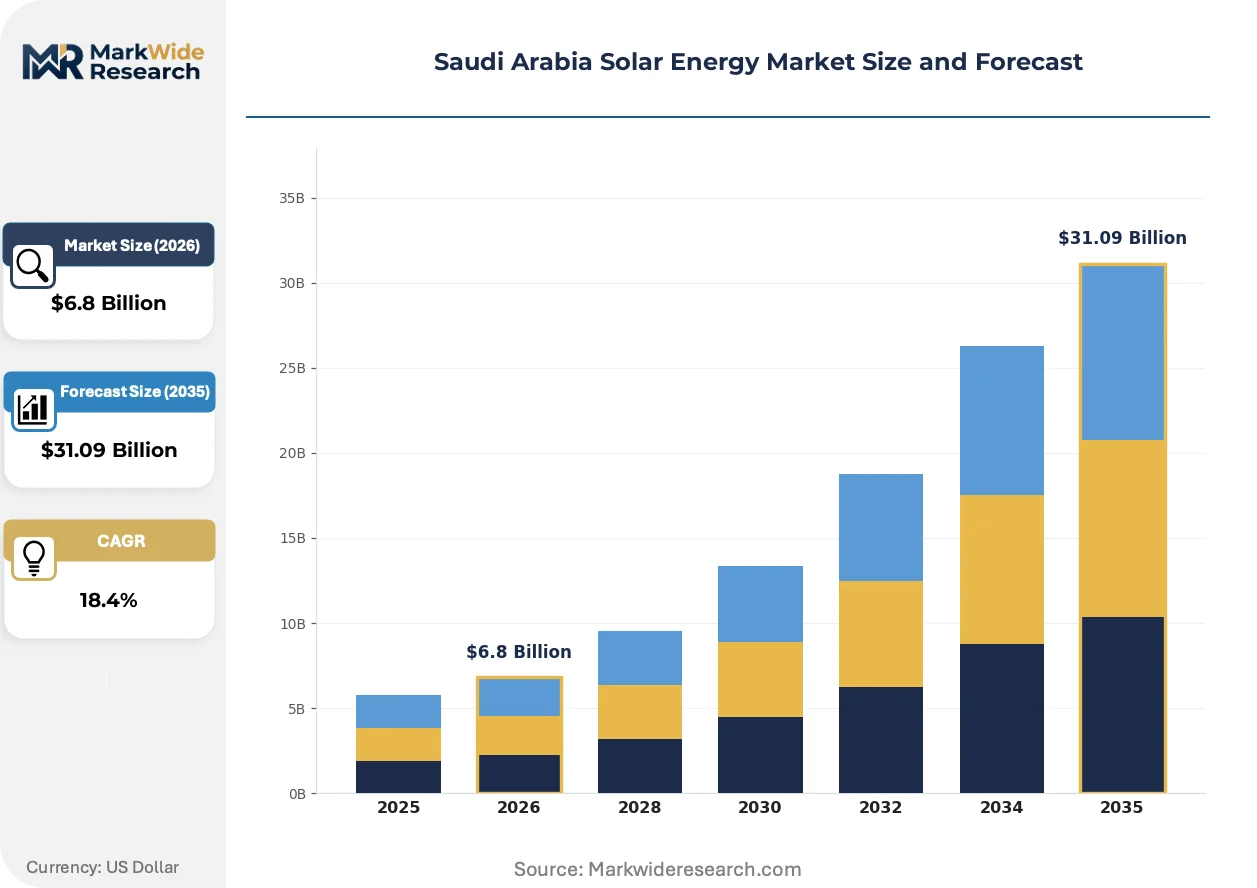
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
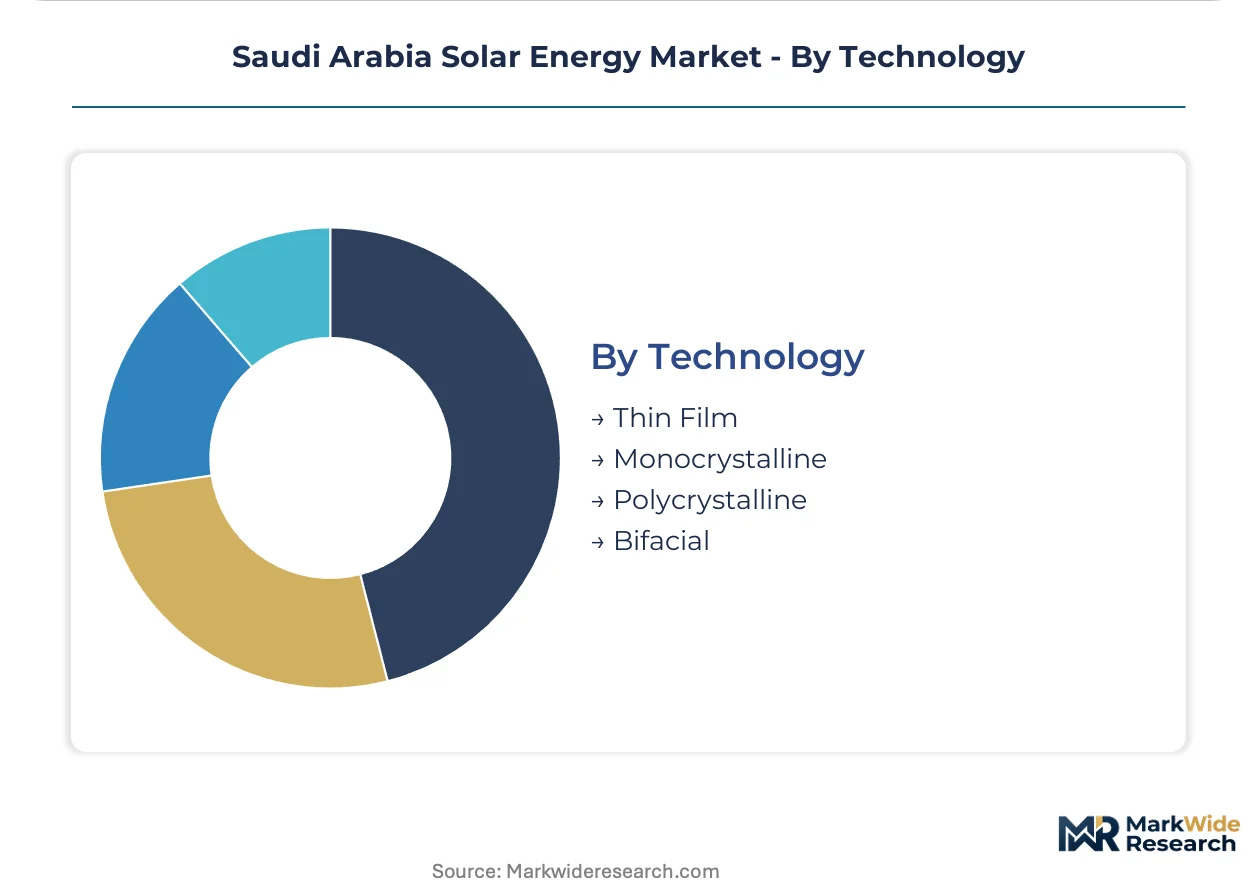
| Segmentation | Product Type: Photovoltaic Systems, Concentrated Solar Power, Solar Thermal, Solar Batteries End User: Residential, Commercial, Industrial, Government Installation Type: Ground-mounted, Rooftop, Off-grid, Utility Scale Technology: Thin Film, Monocrystalline, Polycrystalline, Bifacial |
| Companies Covered | Larsen & Toubro, NextPower Arabia, ACWA Power, PowerChina Guizhou Engineering, First Solar, JinkoSolar, EDF Renewables, Badeel, Saudi Aramco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Solar Energy Market Evolving Landscape
Technology convergence and procurement model evolution are compressing development cycles for utility-scale solar installations across the Kingdom. Three distinct shifts are reconfiguring competitive positioning and project economics.
Digital twin platforms are digitizing plant design and performance optimization workflows for Saudi solar developers. ACWA Power and consortium partners deploy these systems to simulate bifacial gain coefficients and tracking alignment before construction. This capability is digitizing risk allocation between EPC contractors and equity investors in long-term offtake structures.
Saudi Electricity Regulatory Authority grid codes are mandating reactive power capability and frequency response standards for utility-scale solar inverters. These technical requirements are forcing inverter suppliers to redesign power electronics for desert thermal environments. Western Province projects near Tabuk face the most stringent compliance timelines as transmission capacity expands.
Industrial offtakers are consolidating procurement through multi-site power purchase agreements with single counterparties. Petrochemical complexes in Jubail and Yanbu are aggregating demand to secure volume-discounted tariffs and simplify contract administration. This pattern concentrates buyer leverage and compresses developer margins in competitive tender rounds.
Saudi Arabia Solar Energy Market Segmentation
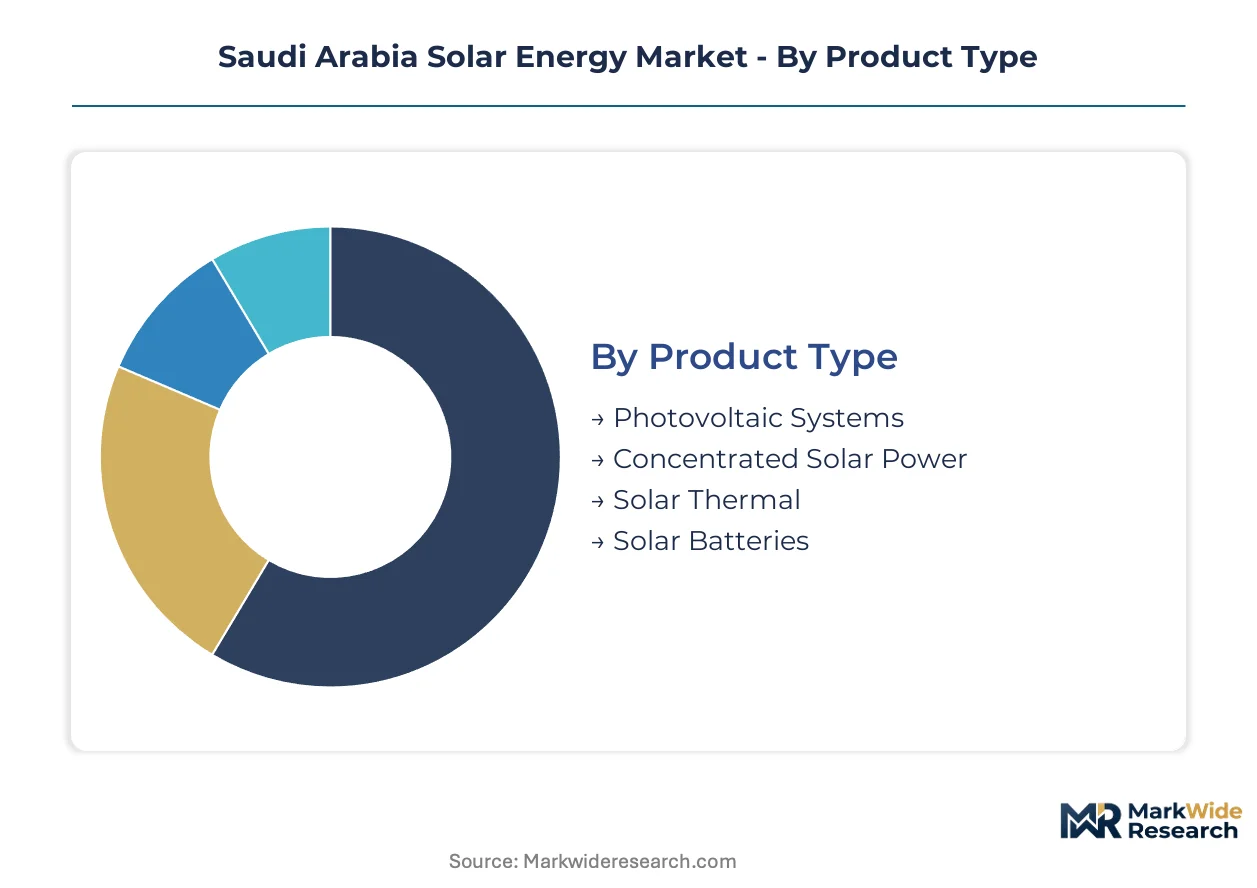
Segmentation reveals distinct procurement patterns across Saudi Arabia's solar energy market. Technology choices and installation configurations vary sharply between state-linked industrial offtakers and distributed commercial adopters. Understanding these divides shapes equipment specification and channel strategy for market participants.
Product Type:
After-sales service intensity escalates with system complexity and thermal storage integration.
- Photovoltaic Systems:Crystalline silicon and thin-film modules convert direct and diffuse irradiance into direct current electricity, with utility-scale installations specifying module efficiencies above twenty-one percent. Demand concentrates in Western Province gigawatt-scale clusters near Tabuk and Neom, driven by Saudi Green Initiative procurement quotas binding state-linked industrial offtakers.
- Concentrated Solar Power:Parabolic trough and solar tower configurations use mirrors to concentrate irradiance onto heat transfer fluids, enabling molten salt thermal storage for dispatchable evening supply. Petrochemical complexes in Jubail and Yanbu anchor demand for this technology, seeking baseload reliability that photovoltaic cannot provide without battery augmentation.
- Solar Thermal:Flat-plate and evacuated tube collectors generate low-to-medium temperature heat for water heating and industrial process applications.
- Solar Batteries:Lithium-ion and emerging solid-state storage systems buffer intermittency for hybrid solar installations.
Photovoltaic systems hold the largest share; momentum sits with concentrated solar power's dispatchable evening supply premium.
End User:
Cost tier stratification separates state-backed volume procurement from self-financed distributed adoption.
- Industrial:Petrochemical and desalination complexes procure multi-hundred-megawatt installations through competitive tenders with twenty-to-twenty-five-year power purchase agreements. Jubail and Yanbu industrial cities anchor this segment, where Saudi Green Initiative mandates enforce binding renewable procurement quotas.
- Commercial:Retail, hospitality, and logistics facilities deploy rooftop and carport installations under maturing net-metering frameworks. Riyadh and Jeddah building stock concentrates demand, with electricity tariff exposure driving payback period calculations.
- Residential:Villa and apartment rooftop systems serve high-income households in Riyadh, Jeddah, and Dammam.
- Government:Municipal buildings, universities, and healthcare facilities procure through centralized procurement frameworks administered by the Saudi Electricity Regulatory Authority.
Industrial offtakers command the largest procurement volumes; commercial rooftop deployment is expanding most quickly as net-metering frameworks mature.
Installation Type:
Geography dictates configuration, with desert corridors favoring ground-mounted utility scale and urban density pushing rooftop alternatives.
- Ground-mounted:Fixed-tilt and single-axis tracking arrays occupy desert land parcels with minimal shading and superior albedo for bifacial gain. Tabuk and Neom project zones concentrate this installation type, where land availability and irradiance profiles optimize capacity factors.
- Utility Scale:Gigawatt-scale project clusters integrate high-voltage grid interconnection and centralized operations centers. Western Province transmission expansion timelines shape deployment pacing for this segment.
- Rooftop:Commercial and residential building-integrated systems leverage existing structural footprints without land acquisition.
- Off-grid:Remote industrial sites and rural settlements deploy standalone systems with battery storage and diesel backup.
Ground-mounted installations dominate capacity additions; utility scale projects are gaining share fastest through gigawatt-scale tender rounds.
Technology:
Module efficiency and thermal tolerance separate premium specifications from commodity procurement.
- Monocrystalline:Single-crystal silicon wafers deliver the highest commercial efficiencies, with passivated emitter and rear contact architectures exceeding twenty-two percent in laboratory conditions. Western Province utility-scale projects specify this technology for capacity factor maximization, though desert thermal derating to eighty-five degrees Celsius imposes real-world penalties.
- Bifacial:Dual-sided modules capture rear-side irradiance reflected from desert sand albedo, with single-axis tracking amplifying gain coefficients. Neom and Tabuk project developers specify this technology combination to compress levelized costs without proportional land expansion.
- Thin Film:Cadmium telluride and copper indium gallium selenide technologies tolerate high-temperature desert operating conditions with lower temperature coefficients than crystalline silicon.
- Polycrystalline:Multi-crystal silicon wafers trade efficiency for manufacturing cost advantages in price-sensitive procurement rounds.
Monocrystalline technology holds the largest installed base; bifacial modules are climbing the fastest as tracking system penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports photovoltaic modules and concentrated solar power expertise to neighboring Gulf Cooperation Council markets while importing polysilicon and high-efficiency cells from East Asian manufacturing hubs. The Kingdom's Western Province irradiance corridors anchor domestic deployment, with project economics shaped by domestic content requirements and Saudi Electricity Regulatory Authority grid codes.
Western Region
Tabuk and Neom anchor gigawatt-scale project clusters leveraging superior solar resource profiles and land availability for bifacial tracking installations. SFDA and the Saudi Electricity Regulatory Authority enforce grid interconnection standards and power purchase agreement templates that shape developer procurement. The Neom gigaproject zone concentrates utility-scale deployment where single-axis tracking systems optimize capacity factors.
Eastern Province
Jubail and Yanbu industrial cities host petrochemical complexes procuring concentrated solar power with molten salt thermal storage for dispatchable evening supply. The Saudi Green Initiative mandates binding renewable procurement quotas for state-linked industrial offtakers. ACWA Power leads project development through long-term offtake structures with these industrial clusters.
Riyadh
Commercial rooftop installations accelerate across Riyadh's retail and logistics building stock as net-metering frameworks mature. The Saudi Electricity Regulatory Authority administers centralized procurement for government buildings, universities, and healthcare facilities. Distributed generation potential concentrates in the capital's commercial zones where electricity tariff exposure drives payback calculations.
Mecca Province
Desalination complexes in the province scale solar procurement under Vision 2030 renewable targets for industrial water production. SFDA technical codes intersect with water utility regulations to shape project commissioning timelines. Taif and surrounding areas host hybrid installations where photovoltaic and battery storage address peak demand periods.
Saudi Arabia Solar Energy Market Competitive Landscape
On the supply side, the industry is structured around project developers, technology suppliers, and engineering contractors competing through localization credentials and long-term offtake structuring. Tiered competitive dynamics separate consortium leaders with balance-sheet capacity from equipment specialists and construction partners. Strategic archetypes include integrated developers controlling project pipelines, module manufacturers competing on efficiency metrics, and EPC contractors with desert deployment experience. Dominant competitive moves center on joint venture formation with Saudi industrial partners and backward integration into polysilicon sourcing.
Within the integrated developer tier, ACWA Power exemplifies consortium leadership through local partnership structures and long-term power purchase agreement origination. JinkoSolar and First Solar represent contrasting technology archetypes—monocrystalline silicon versus thin-film cadmium telluride—each occupying positions shaped by thermal tolerance requirements and efficiency specifications in desert operating conditions. Larsen & Toubro anchors the EPC contractor segment with construction execution capabilities.
| Leading Market Players |
|---|
| Larsen & Toubro |
| NextPower Arabia |
| ACWA Power |
| PowerChina Guizhou Engineering |
| First Solar |
| JinkoSolar |
| EDF Renewables |
| Badeel |
| Saudi Aramco |
| Others |
Value Network & Pricing Analysis
East Asian polysilicon manufacturing clusters anchor upstream capacity for Saudi project developers, translating ingot supply tightness into volatile module pricing that compresses developer margins during tender rounds. Western Province gigawatt-scale installations face the sharpest cost transmission as procurement quotas accelerate under Vision 2030 mandates.
Pricing Analysis
Crystalline silicon module pricing stratifies across premium monocrystalline PERC, standard polycrystalline, and emerging next-generation heterojunction tiers, with bifacial gain coefficients commanding fifteen-to-twenty percent premiums over monofacial equivalents. Price differentiation rests on efficiency certification tiers and thermal derating performance guarantees under SFDA technical codes. Cost compression in standard-tier procurement intensifies as Chinese manufacturers expand wafer capacity, while petrochemical offtakers in Jubail and Yanbu demonstrate lowest price sensitivity due to baseload reliability requirements.
Supply Chain Analysis
Export control regimes on semiconductor manufacturing equipment constrain polysilicon purification technology transfers to emerging manufacturing hubs, limiting Saudi localization ambitions for ingot production. Module assembly draws from Chinese cell and glass suppliers, South Korean inverter electronics, and domestic Saudi steel for tracking structures. Single-source vulnerability concentrates in high-purity quartz crucibles for monocrystalline ingot pulling. Distribution runs through ACWA Power-led consortium structures that aggregate EPC contractor procurement across multiple project phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering workforce scarcity with desert deployment experience constrains execution capacity as gigawatt-scale pipelines expand, creating bottlenecks that favor developers with captive construction capabilities.
For Market Incumbents: Insulate project margins through backward integration into module assembly capacity within Saudi industrial zones, satisfying local content requirements that increasingly weight tender scoring. Lock in polysilicon offtake agreements with East Asian suppliers before capacity expansion cycles flood spot markets. Defend against emerging Chinese EPC entrants by embedding digital twin capabilities that de-risk construction timelines for equity investors. For New Entrants and Emerging Players: Mid-scale commercial rooftops in Riyadh and Jeddah represent the most penetrable entry point, as net-metering framework maturation outpaces incumbent developer attention focused on utility-scale tenders. Solar thermal integration for industrial process heat in Taif desalination complexes offers technology differentiation away from commoditized photovoltaic procurement. Pursue channel partnerships with Saudi construction conglomerates lacking renewable energy capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors concentrated solar power developers with molten salt storage capabilities, as evening dispatch premiums widen against photovoltaic-plus-battery economics. Long-term viability hinges on securing industrial offtaker relationships before procurement consolidates around ACWA Power-led consortia. Watch auction clearing price trajectories in Saudi Electricity Regulatory Authority tender rounds as the inflection signal for margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Module Assembly Localization | Satisfies Saudi Green Initiative local content requirements that increasingly determine tender award outcomes. |
| Long-term Polysilicon Supply Agreement | Locks input costs against East Asian manufacturing hub volatility that disrupts project financing. |
| Digital Twin Platform Deployment | De-risks bifacial tracking system performance for equity investors in Western Province desert installations. |
| Molten Salt Thermal Storage Integration | Captures premium tariffs from Jubail petrochemical offtakers requiring dispatchable evening baseload supply. |
| EPC Contractor Capability Development | Addresses workforce scarcity that delays commissioning timelines for gigawatt-scale Neom project clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with utility planning officers at Saudi Electricity Company, IPP project developers managing Western Province installations, EPC contractors with desert deployment experience, and grid operators overseeing transmission expansion timelines. Secondary validation incorporated IEA renewable energy market analyses, FERC-style regulatory filings with the Saudi Electricity Regulatory Authority, project development databases tracking Neom and Tabuk tender rounds, and customs records for module import flows. Bottom-up capacity addition estimates were triangulated against top-down Vision 2030 target allocations.
Calibration against historical auction clearing prices and installed cost trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type bifurcation between photovoltaic and concentrated solar power, installation scale tiers from distributed commercial rooftops to utility-scale gigawatt clusters, and regional regulatory frameworks distinguishing Western Province grid codes from Eastern Province industrial offtake structures. CAGRs were derived from capacity factor assumptions tied to bifacial gain coefficients and single-axis tracking penetration rates.
Macroeconomic conditions sit as an overlay; deviation in global polysilicon spot pricing or Saudi riyal-dollar exchange rate stability would shift the trajectory. Forecasts reflect assumptions around SFDA technical code enforcement timelines and Saudi Green Initiative procurement quota stringency. Material shifts in export control regimes affecting semiconductor manufacturing equipment access would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
Frameless Solar Panel Market