
 Minibar Refrigerators Market | 2026-2036
Minibar Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Minibar Refrigerators Market Analytics
The capital-intensity divergence between integrated compressor manufacturers and modular assembly specialists is unwinding traditional margin structures. Dometic Group AB leverages captive thermoelectric module production to sustain pricing power across European hospitality supply chains. Hisense International Co., Ltd. anchors volume competitiveness through integrated compressor manufacturing in Shandong province. Indel B S.p.A. specializes in absorption-cooled units for marine applications where silent operation commands premium positioning.
Minibar refrigerators are self-contained cooling appliances designed for confined spaces, typically operating between 0°C and 8°C with capacities under 150 liters and power draws below 100 watts for thermoelectric variants. These units serve hospitality and marine sectors where noise suppression, dimensional constraints, and 24-hour operational reliability override energy efficiency priorities. The compressor segment dominates value capture due to superior cooling density, though thermoelectric platforms are gaining share in boutique hotel retrofits where silent operation outweighs efficiency penalties. Drawer configurations command the fastest expansion trajectory as luxury properties prioritize ergonomic room layouts and concealed amenity integration.
The EU F-Gas Regulation and REACH framework constrain refrigerant selection and material composition for units sold across member states, while the US EPA SNAP program governs hydrofluorocarbon transitions in North American markets. China's GB standards for household appliance energy efficiency create compliance thresholds that favor scaled manufacturers with in-house testing laboratories. Stakeholders must monitor refrigerant chemistry transitions and cooling technology substitution curves as regulatory phase-downs accelerate platform decisions.
Market Dynamics
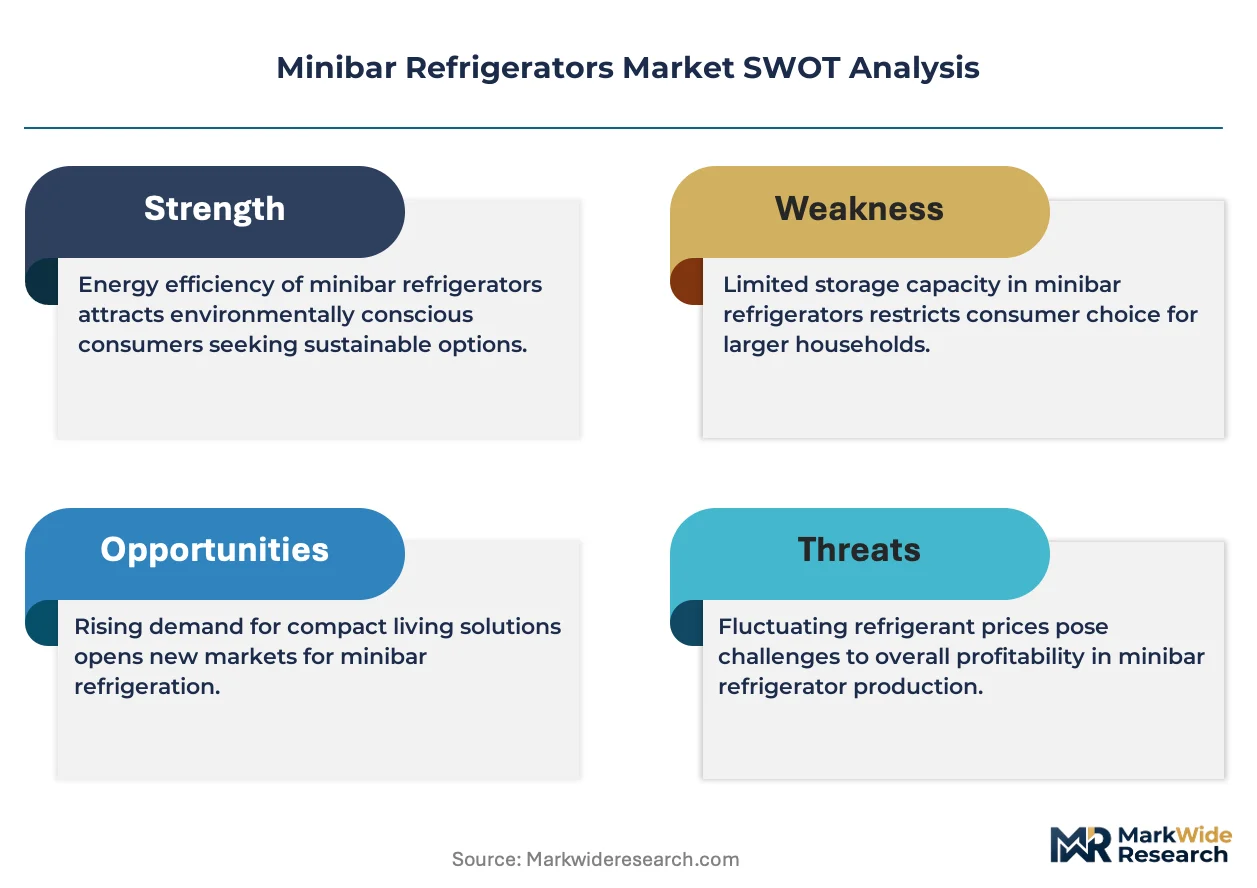
The EU F-Gas Regulation's hydrofluorocarbon phase-down is forcing manufacturers to abandon compressor-dependent platforms and retool for thermoelectric and absorption cooling architectures. This regulatory compression is reshaping capital allocation across European supply chains and accelerating technology substitution curves.
Growth Catalysts
- Tourism Infrastructure Investment:Boutique hotel chains in Thailand, Vietnam, and Indonesia are expanding room amenity budgets to differentiate guest experiences through premium in-room appliances.
- Silent Operation Premium:Absorption-cooled units command positioning power in marine applications where noise suppression overrides efficiency penalties, opening specialized revenue pools.
- REACH Framework Compliance:Material composition standards across EU member states are filtering out low-tier competitors and consolidating demand around scaled testing-capable manufacturers.
Market Restraints
- Refrigerant Chemistry Volatility:Hydrofluorocarbon supply constraints and substitution costs are elevating unit economics for compressor-based platforms.
- Supply Concentration Risk:Integrated compressor manufacturing clusters in Shandong province create geographic dependency for volume-competitive sourcing.
- Thermoelectric Efficiency Ceiling:Peltier module cooling density limitations restrict application in high-ambient-temperature environments.
Strategic Opportunities
- Drawer Configuration Expansion:Luxury properties are prioritizing ergonomic room layouts and concealed amenity integration, creating white space for modular form factors.
- China Dual Carbon Goals:National energy efficiency mandates under MEE oversight are accelerating demand for low-power thermoelectric variants in domestic hospitality.
- Marine Retrofit Cycles:Silent absorption technology is penetrating yacht and cruise refurbishment channels as owners upgrade legacy compressor units.
Industry Challenges
- Thermoelectric Module Sourcing:Captive production capabilities are concentrated among limited suppliers, creating qualification bottlenecks for new market entrants.
- Multi-Regulatory Certification Overlap:Simultaneous compliance with EU F-Gas, REACH, and US EPA SNAP programs extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minibar Refrigerators Market |
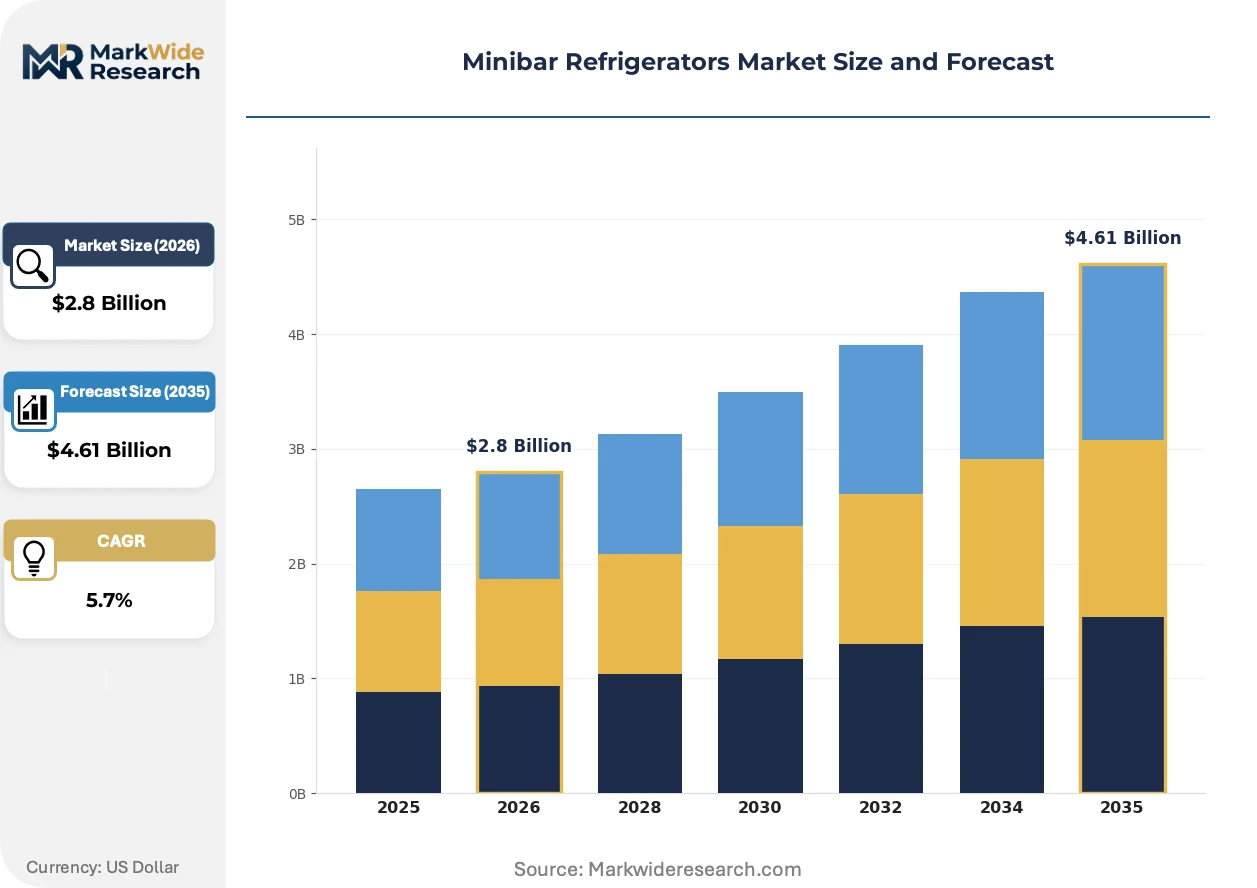
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Double Door, Drawer, Mini End User: Hotels, Cruise Ships, Offices, Home Use Cooling Technology: Compressor, Thermoelectric, Absorption, Ionic Size: Under 50 Liters, 50-100 Liters, 100-150 Liters, Above 150 Liters |
| Companies Covered | Dometic Group AB, ISM Makine Elektrik Sanayi ve Ticaret A.Ş., Koolatron, Royal Minibars, Minibar Systems, Indel B S.p.A., Hisense International Co., Ltd., Felix Storch (Summit Appliance), Tefcold A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minibar Refrigerators Market Evolving Landscape
Cooling platform diversification is fragmenting established supply relationships and creating new competitive axes around noise performance, energy draw, and refrigerant chemistry rather than pure cooling density.
Thermoelectric cooling architecture is fragmenting traditional compressor dominance in hospitality applications. Boutique hotel operators are specifying Peltier-based units for guest room retrofits where silent overnight operation outweighs efficiency trade-offs. This technology shift is compressing margin pools for legacy compressor specialists while rewarding captive module producers.
The EU F-Gas Regulation mandates an 80% hydrofluorocarbon phase-down by 2030, prohibiting high-global-warming-potential refrigerants in new equipment. Manufacturers are redirecting R&D expenditure toward absorption and thermoelectric alternatives. European hospitality supply chains are experiencing the fastest platform turnover as procurement specifications harden against compressor-based bids.
Buyer preference is rotating toward concealed amenity integration rather than standalone appliance visibility. Luxury property developers are specifying drawer-configured units that blend into millwork and furniture systems. This specification shift is most pronounced in Southeast Asian resort construction, where architectural aesthetics command procurement priority over standalone performance metrics.
Minibar Refrigerators Market Segmentation
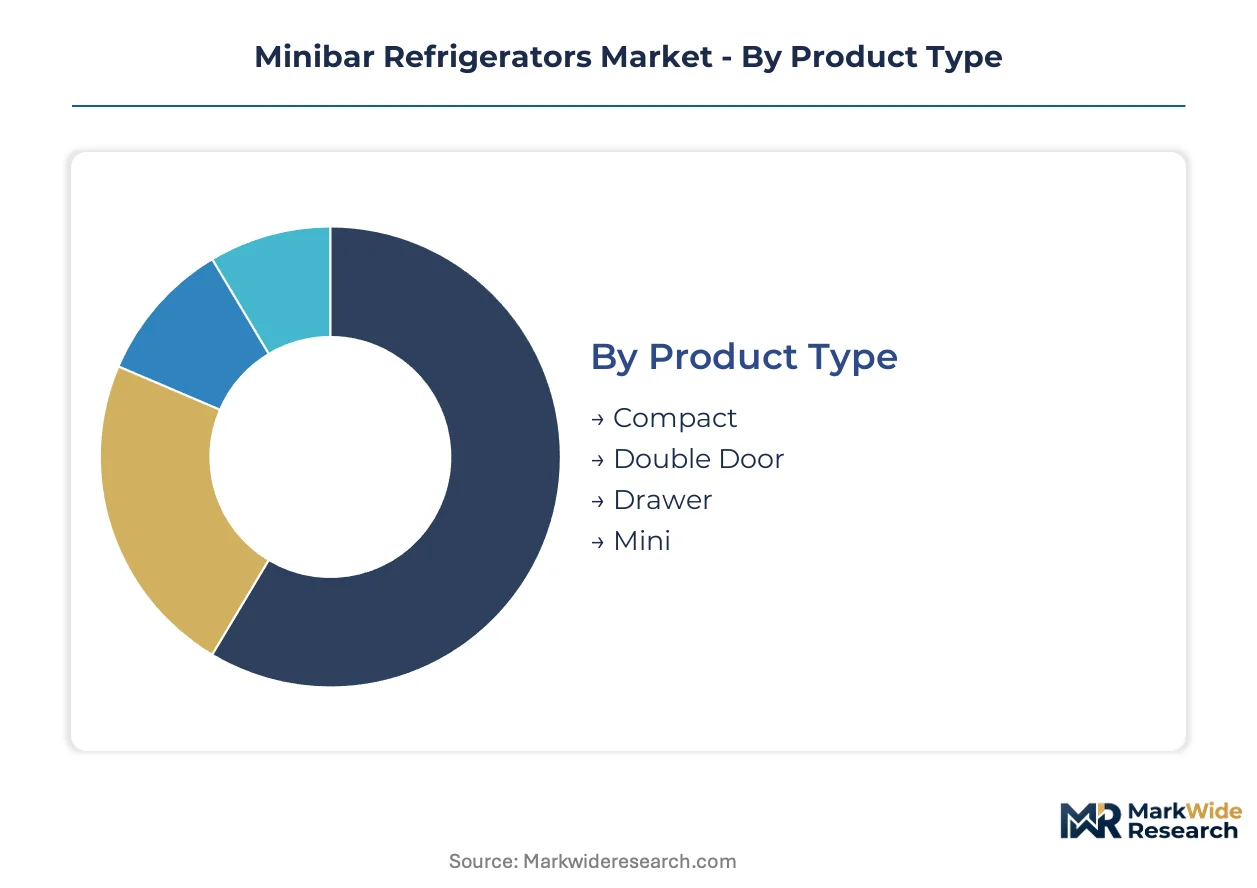
Segmentation in the minibar refrigerator market reveals how cooling technology substitution and hospitality procurement priorities are reallocating demand across form factors and capacity tiers. Understanding these divides exposes where margin compression threatens incumbent positions and where new platform architectures capture specification momentum.
Product Type:
Thermoelectric and absorption alternatives are displacing compressor-dependent form factors fastest in segments where silent operation commands premium positioning.
- Compact:Traditional upright single-door units dominate existing hotel room installations. Procurement concentrates in mid-tier hospitality chains across Thailand and Vietnam where capital expenditure constraints favor proven cooling density over noise performance.
- Drawer:Concealed pull-out configurations integrate into millwork and furniture systems. Luxury resort developers in Indonesia specify these for ergonomic room layouts where aesthetic integration overrides standalone appliance visibility, expanding most quickly within premium new construction.
- Double Door:Separate freezer-refrigerator compartments serve extended-stay suites and serviced apartments. Demand clusters in urban business hotels across Vietnam.
- Mini:Ultra-small sub-30-liter units target space-constrained cabin retrofits on cruise vessels. Marine refit channels in Southeast Asian shipyards drive specification.
Compact units anchor the volume base while drawer configurations gain share at the steepest rate.
End User:
Procurement sophistication varies sharply across customer types, with marine buyers prioritizing noise suppression and hospitality chains weighing total cost of ownership against guest satisfaction metrics.
- Hotels:The dominant demand channel spanning boutique properties to international chains. Boutique operators across Thailand, Vietnam, and Indonesia are expanding amenity budgets to differentiate guest experiences through premium in-room appliances.
- Cruise Ships:Marine applications impose strict noise and vibration standards. Absorption-cooled units command positioning power where silent operation overrides efficiency penalties, opening specialized revenue pools in yacht and cruise refurbishment.
- Offices:Corporate pantry and executive suite installations favor compact thermoelectric units for low maintenance and minimal acoustic disruption.
- Home Use:Residential secondary refrigeration for entertainment spaces and home bars. Demand fragments across price-sensitive consumers and luxury home integration projects.
Hotels anchor the volume base while cruise ships gain share through marine retrofit cycles.
Cooling Technology:
Regulatory phase-downs are forcing platform decisions that favor thermoelectric and absorption architectures in applications where efficiency trade-offs are acceptable.
- Compressor:Vapor-compression systems deliver superior cooling density and temperature stability. The EU F-Gas Regulation's hydrofluorocarbon phase-down is elevating unit economics and compressing margin pools for legacy specialists.
- Thermoelectric:Peltier-based solid-state cooling eliminates moving parts and refrigerant compliance burden. Boutique hotel retrofits across Europe specify these where silent overnight operation outweighs efficiency penalties.
- Absorption:Heat-driven ammonia-water systems operate silently without electrical compressors. Marine and luxury hospitality applications command premium positioning.
- Ionic:Emerging electrocaloric and magnetocaloric technologies in early commercialization. Niche pilot deployments test viability for ultra-low-noise environments.
Compressor technology anchors the volume base while thermoelectric platforms climb the fastest on regulatory pressure.
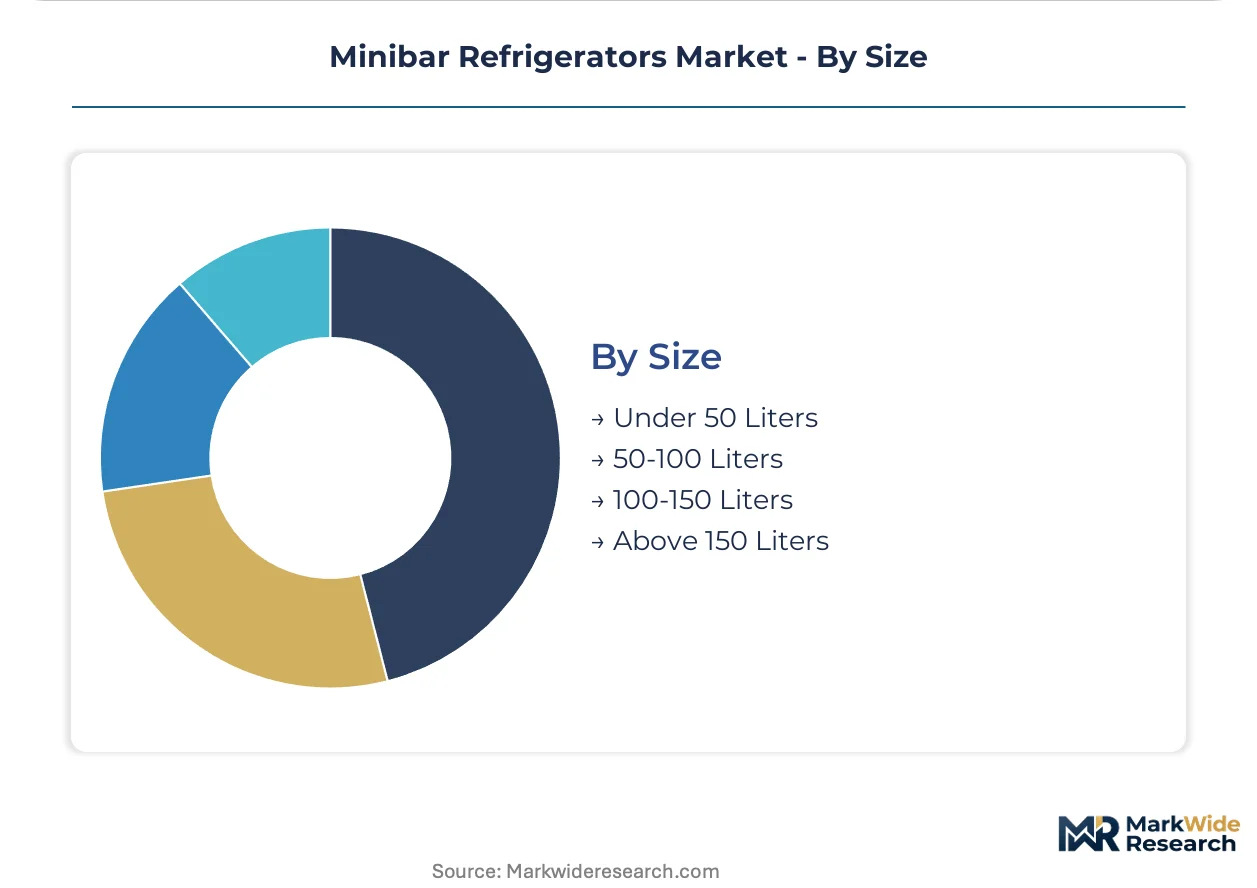
Size:
Capacity selection tracks room category stratification and regional hospitality standards, with tropical climates demanding higher cooling density per liter.
- Under 50 Liters:Standard guest room specification for individual beverage and snack storage. Volume concentrates in Southeast Asian mid-tier hotel construction.
- 50-100 Liters:Extended-stay and suite configurations accommodating longer guest durations. Premium positioning in Indonesian resort developments.
- 100-150 Liters:Executive suite and specialty hospitality applications. Limited demand outside luxury tier.
- Above 150 Liters:Exceeds conventional minibar definition, serving niche residential and commercial pantry roles. Marginal market presence.
Under 50-liter units anchor the volume base while 50-100-liter segments expand on extended-stay hospitality growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European hospitality supply chains where regulatory compliance costs filter out low-tier competitors, while Southeast Asian markets reward volume-scaled manufacturers with integrated production bases.
Germany
Boutique hotel operators across Bavaria and Baden-Württemberg specify silent thermoelectric units for guest room retrofits. The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs that elevate unit economics for compressor-dependent platforms. Industrial clusters around Stuttgart and Munich host testing-capable manufacturers with in-house REACH compliance laboratories.
China
Domestic hospitality chains under MEE oversight accelerate procurement of low-power thermoelectric variants aligned with dual carbon goals. GB standards for household appliance energy efficiency create compliance thresholds favoring scaled producers. Shandong province anchors integrated compressor manufacturing clusters serving export markets across Southeast Asia.
Thailand
Boutique hotel chains in Bangkok and Phuket expand room amenity budgets to differentiate guest experiences through premium in-room appliances. The country's national energy efficiency regulator enforces cooling performance standards for imported hospitality equipment. Manufacturing zones around Chonburi and Rayong concentrate assembly operations for regional tourism infrastructure projects.
United States
Corporate pantry installations and extended-stay hospitality operators favor compact thermoelectric units for minimal acoustic disruption. The EPA SNAP program governs hydrofluorocarbon transitions in North American markets, compressing development timelines for multi-regional suppliers. Distribution and specification activity clusters around Dallas-Fort Worth and Atlanta hospitality supply corridors.
Italy
Marine refit channels in Genoa and La Spezia drive specification of absorption-cooled units where silent operation commands premium positioning. ECHA oversight of REACH framework compliance filters material composition for units sold across EU member states. Lombardy-based manufacturers specialize in yacht and cruise refurbishment applications.
Minibar Refrigerators Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with captive thermoelectric module producers sustaining pricing power against volume-scaled compressor integrators. The vendor base organizes around three strategic archetypes: integrated manufacturers with backward control over cooling platforms, modular assembly specialists sourcing components from concentrated supply clusters, and marine-focused absorption technology providers. Dominant competitive moves include portfolio diversification across cooling architectures and geographic expansion into Southeast Asian tourism infrastructure corridors.
Among European specialists, Dometic Group AB and Indel B S.p.A. exemplify divergent platform strategies—one anchored in thermoelectric module production, the other in absorption-cooled marine applications. Hisense International Co., Ltd. represents the scale-driven archetype with integrated manufacturing bases. These three occupy positions across distinct competitive vectors: captive technology control, premium marine specialization, and volume-cost competitiveness.
| Leading Market Players |
|---|
| Dometic Group AB |
| ISM Makine Elektrik Sanayi ve Ticaret A.Ş. |
| Koolatron |
| Royal Minibars |
| Minibar Systems |
| Indel B S.p.A. |
| Hisense International Co., Ltd. |
| Felix Storch (Summit Appliance) |
| Tefcold A/S |
| Others |
Value Network & Pricing Analysis
Thermoelectric module substitution for compressor-dependent cooling platforms simultaneously shifts supply geography toward East Asian semiconductor corridors and compresses pricing power for legacy refrigerant-based manufacturers. This input transition redraws procurement economics as buyers weigh silent-operation premiums against efficiency trade-offs across hospitality and marine segments.
Pricing Analysis
The customization-premium spread separates drawer-configured millwork-integrated units from standard upright compact models by certification grade and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels tracks cooling technology architecture, with absorption-cooled marine units commanding positioning power through noise suppression certification. Cost compression in compressor-based tiers intensifies because EU F-Gas Regulation phase-downs elevate refrigerant chemistry costs. Mid-tier hospitality chains in Thailand and Vietnam exhibit highest price sensitivity, while luxury resort developers in Indonesia prioritize ergonomic integration over unit economics.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Shenzhen port clusters constrain just-in-time delivery windows for thermoelectric module procurement from Shandong and Jiangsu manufacturing bases. Component sourcing draws from concentrated Peltier module production in China, compressor manufacturing clusters in Shandong province, and absorption system specialists in Italy. Single-source vulnerability around captive thermoelectric module producers creates qualification bottlenecks for new entrants seeking REACH compliance. Distribution runs through hospitality supply chain integrators serving Southeast Asian tourism corridors and marine refit channels in Mediterranean shipyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in minibar refrigeration hinge on cooling technology interoperability as regulatory phase-downs force substitution decisions across buyer procurement specifications. The shift from vapor-compression to solid-state architectures creates winner-take-most dynamics around module supply control and certification capability.
For Market Incumbents: Consolidate backward integration into thermoelectric module production or absorption system engineering to defend margin pools against modular assembly specialists. Dometic Group AB's captive Peltier manufacturing demonstrates how upstream control over cooling platforms sustains pricing power when EU F-Gas Regulation compresses compressor-dependent competitors. Capacity addition in Southeast Asian assembly zones captures tourism infrastructure investment flows without sacrificing technology differentiation. For New Entrants and Emerging Players: Differentiate on silent-operation certification for marine retrofit channels where absorption-cooled units command premium positioning against legacy compressor installations. The yacht and cruise refurbishment segment in Italian and Southeast Asian shipyards represents the most penetrable white space, with procurement specifications hardening against noise and vibration standards. A go-to-market angle anchored on REACH pre-certification and millwork integration partnerships bypasses incumbent hospitality supply chain lock-in. For Investors and Strategic Acquirers: The market sits at a regulatory-driven substitution phase that favors technology-integrated specialists over pure-play volume manufacturers. Long-term viability across the projection horizon rests on cooling platform diversification and geographic exposure to Southeast Asian tourism growth. Acquisition target archetypes include captive thermoelectric module producers and marine-focused absorption technology providers. The signal to watch is EU F-Gas Regulation enforcement acceleration compressing compressor platform margins faster than substitution timelines allow.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoelectric Module Captive Production | Backward integration into Peltier manufacturing secures supply continuity under REACH and EU F-Gas compliance pressure. |
| Drawer Configuration Product Line Expansion | Millwork-integrated form factors capture luxury hospitality specification shifts in Indonesian and Thai resort developments. |
| Marine Certification Investment | Silent-operation validation for absorption platforms penetrates yacht refit channels in Genoa and La Spezia corridors. |
| Southeast Asian Assembly Footprint | Regional production proximity to Thailand and Vietnam hotel construction reduces logistics exposure and tariff friction. |
| Multi-Regulatory Pre-Certification | Simultaneous EU F-Gas, REACH, and EPA SNAP compliance shortens procurement qualification cycles for hospitality chains. |
Research Methodology
Cross-validation between primary hospitality procurement interviews and secondary regulatory filing analysis anchors the qualitative findings on cooling technology substitution dynamics. Hotel engineering directors, marine refit contractors, and hospitality supply chain managers provided operational perspective on specification priorities. EU F-Gas Regulation implementation timelines, ECHA REACH substance restrictions, and EPA SNAP program updates supplied compliance boundary conditions. Bottom-up unit shipment analysis triangulates against top-down hospitality construction spending estimates across Southeast Asian markets.
Sensitivity analysis on thermoelectric adoption curves and compressor phase-down timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include cooling technology platform, form factor configuration, end-user category, and regional regulatory cluster. CAGRs derive from installed base turnover rates and new construction penetration assumptions. Industry-specific forecast inputs incorporate tourism infrastructure investment pipelines and marine vessel refurbishment cycles.
Material uncertainties — refrigerant chemistry substitution costs, thermoelectric module supply concentration, and Southeast Asian tourism demand volatility — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement consistency and buyer specification inertia. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electric Ranges Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Space Heaters Market
Appliances
Qatar Microwave Ovens Market
Appliances
Toaster Ovens Market
Appliances
Europe Household Electric Grills Market
Appliances
Garments Steamer Market
Appliances
French Door Refrigerator Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Mini Refrigerator Market
Appliances
Laundry Dryer Market
Appliances
Clothing Iron Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
Portable Dishwasher Market
Appliances
GCC Dishwashers Market
Appliances
India Washing Machine Market