
 India Washing Machine Market | 2026-2036
India Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
India Washing Machine Market Foresight
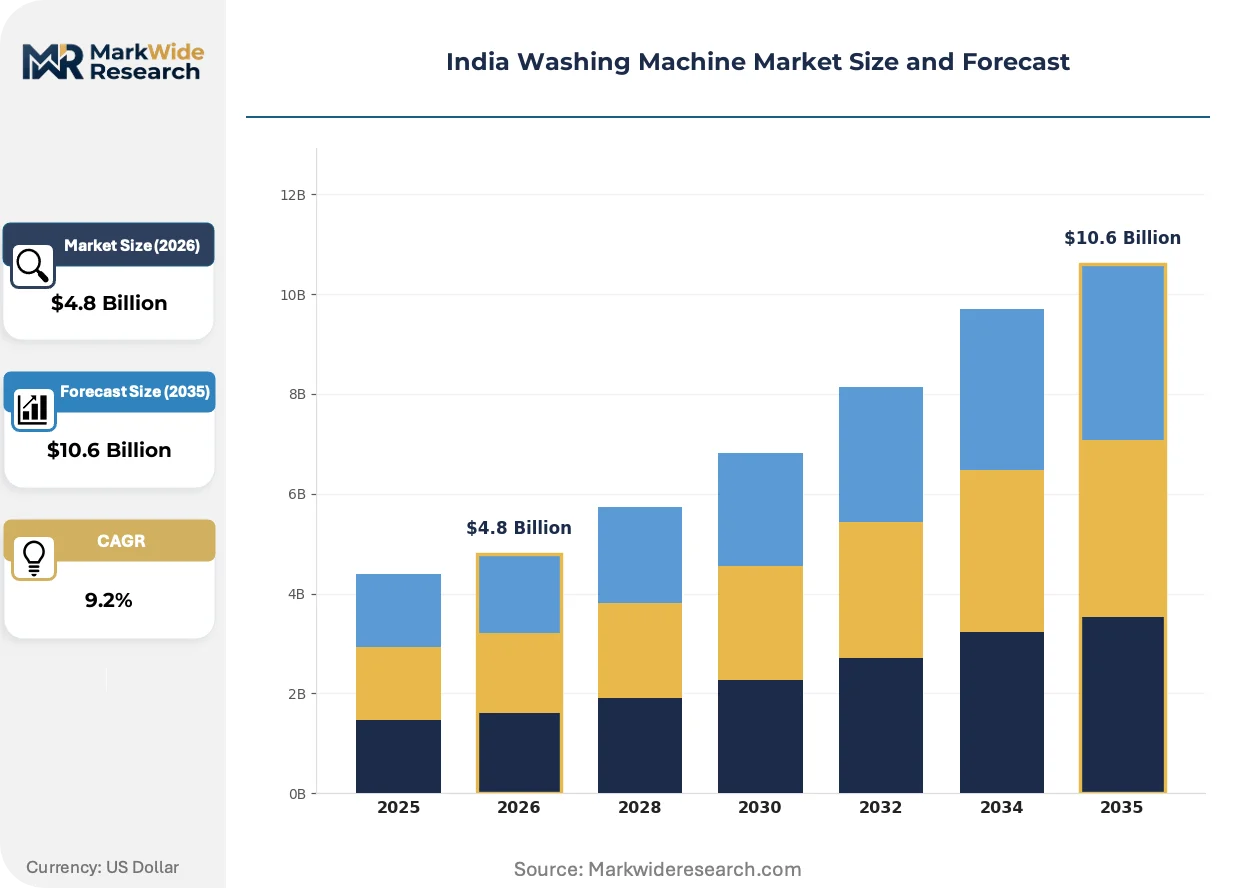
Consumer durables financing through NBFC-led EMI schemes and retailer credit programs is rewriting competitive access across India. LG Electronics sustains manufacturing scale through its Noida and Pune facilities, while IFB Industries specializes in front-load engineering for hard-water conditions prevalent in western India. Godrej & Boyce leverages its backward integration into compressor and motor production to control input costs. Samsung India Electronics anchors premium positioning through connected appliance ecosystems.
A washing machine is an electromechanical appliance employing drum rotation, water circulation, and centrifugal extraction to clean textiles, with spin speeds typically ranging from 400 to 1,400 revolutions per minute. Front-load configurations achieve higher extraction efficiency and reduced water consumption compared to top-load alternatives, making them preferred in water-scarce municipalities. Fully automatic systems command the dominant revenue share as urban consumers prioritize convenience over semi-automatic price advantages. Smart technology integration represents the fastest-expanding technology segment, though inverter motor platforms capture the deepest margin pools through energy-label premiums and replacement parts revenue.
BIS mandates star ratings for energy consumption, while the CEA enforces standby power limits under appliance efficiency regulations. The PLI scheme for white goods manufacturing is reshaping where supply localizes and which component ecosystems develop domestically. Stakeholders must monitor how state-level water tariff reforms and municipal sewage capacity expansions alter product specification requirements across India's heterogeneous urban infrastructure.
Market Dynamics
NBFC-led consumer durables financing is rewriting competitive access across India, collapsing upfront purchase barriers for households previously excluded from automatic washing machine ownership.
Growth Catalysts
- PLI scheme for white goods:Production-linked incentives are reshaping where supply localizes and which motor and compressor ecosystems develop domestically.
- Hard-water engineering specialization:Front-load platforms optimized for mineral-heavy municipal supplies are capturing preference in Gujarat and western Maharashtra.
- Tier-2 electrification:Improved grid reliability and piped water access in secondary cities are converting semi-automatic users to fully automatic systems.
Market Restraints
- Copper and steel input volatility:Drum and motor raw material cost swings compress margin visibility for manufacturers lacking backward integration into component production.
- CEA standby power limits:Compliance engineering for idle-state consumption ceilings adds certification overhead without consumer-facing differentiation.
- Semi-automatic substitution persistence:Price-sensitive rural segments continue prioritizing two-tub units where water scarcity permits manual intervention.
Strategic Opportunities
- Smart appliance convergence:IoT-enabled diagnostics and usage analytics are hybridizing with inverter motor platforms to create subscription-style after-sales revenue streams.
- Tamil Nadu urban corridor:Chennai and Coimbatore metropolitan clusters show disposable income trajectories supporting premium front-load penetration ahead of national averages.
- BIS star-rating premiums:Five-star energy label differentiation commands measurable price escalation in electricity-tariff-sensitive municipalities.
Industry Challenges
- Inverter motor technician scarcity:Field service networks lack density of trained personnel for variable-frequency drive diagnostics, elongating repair cycles.
- State-level water tariff heterogeneity:Municipal pricing reforms alter water-consumption sensitivity calculations, forcing SKU fragmentation across state boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Washing Machine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Load, Front Load, Semi-Automatic, Fully Automatic Technology: Smart Technology, Inverter Technology, Conventional, Eco-Friendly Capacity: 6 kg, 7 kg, 8 kg, Above 8 kg End User: Households, Commercial Use, Lodging, Self-Service Laundries |
| Companies Covered | Haier Group Corporation, Godrej & Boyce Mfg. Co. Ltd., LG Electronics Inc., BSH Home Appliances, Panasonic Corporation, Samsung India Electronics Ltd, IFB Industries Ltd., Electrolux AB, Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Washing Machine Market Shifts & Advancements
Product architecture is converging around energy efficiency and connected functionality, with regulatory pressure and infrastructure heterogeneity forcing specification divergence across India's urban hierarchy.
Inverter motor technology is hybridizing with conventional induction drives across the mid-market tier, enabling real-time load sensing and variable spin-speed optimization. Tier-2 city households are adopting these platforms fastest as electricity tariff visibility improves. The technology is hybridizing service revenue models toward predictive maintenance subscriptions rather than transactional part replacement.
BIS energy-efficiency labeling mandates are compressing the viable product portfolio toward four-star and five-star certified units. Manufacturers must redesign drum and heating element configurations to meet tightened consumption ceilings. Maharashtra and Gujarat distribution channels are prioritizing compliant SKUs to preempt regulatory enforcement variance across state warehousing.
Retailer credit programs are displacing cash transactions in semi-urban catchments, with NBFC partnerships embedding financing into point-of-sale workflows. Appliance specialty chains and organized retail formats are capturing share from independent dealers through integrated EMI origination. This shift concentrates in Gujarat and Tamil Nadu where formal credit penetration outpaces northern hinterlands.
India Washing Machine Market Segmentation
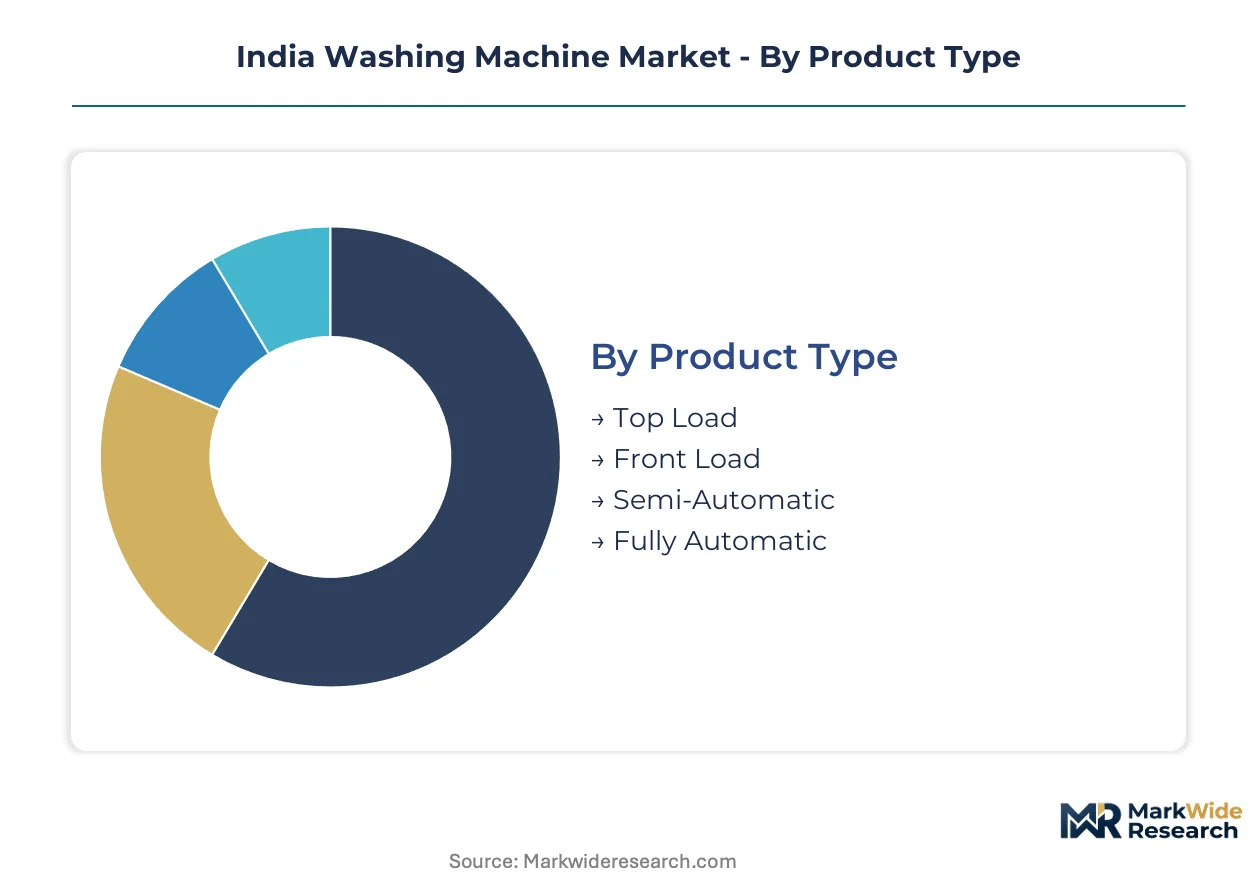
Segmentation in India's washing machine market reveals distinct replacement cycles and upgrade pathways. Product architecture, motor technology, load capacity, and end-use application each create separate margin pools and distribution requirements.
Product Type:
Replacement velocity varies sharply across configurations, with semi-automatic units cycling fastest through rural trade-in channels while front-load platforms exhibit extended ownership horizons in urban households.
- Fully Automatic:Single-drum systems integrate wash and spin cycles without manual transfer, commanding preference in Maharashtra and Tamil Nadu metros where piped water pressure supports uninterrupted operation. Urban consumers prioritize time savings over semi-automatic price advantages, accelerating conversion from two-tub units.
- Front Load:Horizontal-axis drums achieve extraction efficiencies above 1,200 RPM with reduced water consumption, capturing preference in Gujarat municipalities facing scarcity pricing. Hard-water engineering specialization by IFB Industries and LG Electronics targets mineral-heavy western Indian supplies.
- Top Load:Vertical-axis configurations dominate replacement demand in Tier-2 electrification corridors, offering mid-market price positioning between semi-automatic economy and front-load premium tiers.
- Semi-Automatic:Two-tub units persist in price-sensitive rural segments across northern hinterlands where manual water intervention remains acceptable and electricity reliability fluctuates.
Fully automatic systems dominate installed base. Front load is where expansion concentrates.
Technology:
Cost tier stratification separates premium inverter platforms from conventional induction drives, with smart connectivity commanding subscription revenue potential at the apex.
- Inverter Technology:Variable-frequency drive motors enable real-time load sensing and spin-speed optimization, capturing BIS five-star label premiums in electricity-tariff-sensitive municipalities. Tier-2 city households adopt these platforms fastest as tariff visibility improves.
- Smart Technology:IoT-enabled diagnostics and usage analytics hybridize with motor platforms to create predictive maintenance revenue streams, though penetration concentrates in Chennai and Coimbatore metropolitan clusters ahead of national averages.
- Conventional:Fixed-speed induction motors retain share in sub-15,000 rupee price bands where energy efficiency certification carries limited consumer salience.
- Eco-Friendly:Reduced water and detergent consumption specifications align with municipal conservation mandates in water-scarce Gujarat and Rajasthan urban centers.
Inverter technology dominates installed base. Smart technology is where expansion concentrates.
Capacity:
Volume concentration tracks household size and income trajectories, with nuclear family formation pushing demand toward mid-range load specifications.
- 7 kg:The standard configuration for three-to-four-member urban households balances space constraints against wash frequency, representing the largest revenue pool across Maharashtra and Gujarat distribution channels.
- 8 kg:Larger drum specifications capture preference in Tamil Nadu's Coimbatore corridor where joint family structures persist and disposable income trajectories support premium penetration.
- 6 kg:Compact units serve single-person and elderly households in Mumbai and Pune high-rise apartments with space-constrained utility configurations.
- Above 8 kg:Heavy-load platforms address commercial use and large joint families, with limited penetration outside institutional procurement channels.
7 kg dominates installed base. 8 kg is where expansion concentrates.
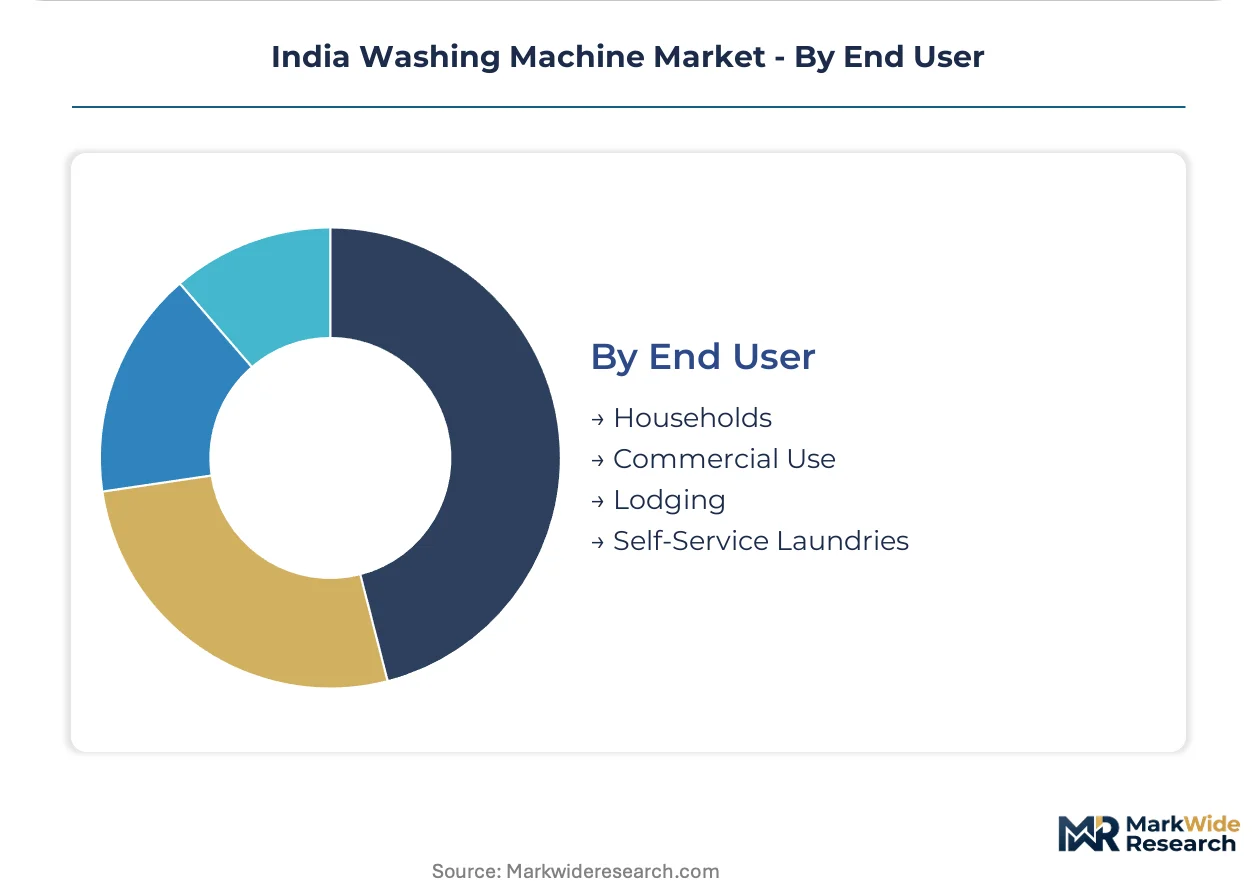
End User:
Application type determines service network density and financing integration requirements, with commercial installations demanding faster response commitments than residential accounts.
- Households:Residential segment absorbs the dominant volume share, with NBFC-led EMI schemes collapsing upfront purchase barriers for first-time automatic washing machine buyers in Tier-2 cities.
- Commercial Use:Hotels, hospitals, and institutional laundries specify industrial-grade durability and rapid-cycle throughput, sourcing through specialized B2B distributors with maintenance contract bundling.
- Lodging:Budget hotels and guesthouses in Tamil Nadu and Karnataka tourism corridors drive demand for compact 6-7 kg units with simplified controls and reduced service intervention requirements.
- Self-Service Laundries:Coin-operated and card-payment installations emerge in Bengaluru and Hyderabad tech corridors, replicating urban density models from East Asian metropolitan markets.
Households dominate installed base. Commercial use is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's washing machine trade balance tilts toward import dependency for high-efficiency motor controllers and precision-engineered drum assemblies, while domestic assembly concentrates in western and southern industrial corridors. The PLI scheme for white goods manufacturing is redrawing where component ecosystems localize.
Maharashtra
Mumbai and Pune metropolitan clusters absorb premium front-load volume as nuclear family formation accelerates and high-rise utility configurations demand space-efficient appliances. The state's electricity regulator enforces tariff slabs that amplify five-star BIS label premiums. Manufacturing scale concentrates in Pune's Chakan industrial belt where LG Electronics and IFB Industries anchor assembly operations.
Gujarat
Ahmedabad and Surat municipalities drive demand for hard-water-optimized engineering as mineral-heavy municipal supplies degrade conventional drum coatings. The state's urban development authority mandates water conservation fixtures in new construction, elevating front-load specifications. Sanand industrial corridor hosts expanding compressor and motor component fabrication feeding western India distribution networks.
Tamil Nadu
Chennai and Coimbatore clusters exhibit disposable income trajectories supporting smart-connected appliance penetration ahead of national adoption curves. The state's electricity board implements time-of-use tariffs that incentivize inverter motor platforms with programmable delay functions. Sriperumbudur electronics manufacturing zone attracts white goods component suppliers seeking port access for import-export logistics.
Karnataka
Bengaluru's tech corridor generates demand for IoT-enabled diagnostics among early-adopter households with connected home ecosystems. The state's energy department mandates appliance efficiency disclosures in retail channels, compressing non-compliant SKU viability. Peenya industrial area hosts ancillary motor winding and control panel fabrication serving southern India assembly plants.
Delhi-NCR
The capital region's replacement cycle accelerates as aging semi-automatic units exit service in favor of fully automatic upgrades among middle-income colonies. The Central Electricity Authority enforces standby power limits that reshape product design specifications for national distribution. Noida manufacturing facilities leverage Uttar Pradesh industrial incentives to serve northern hinterland demand.
India Washing Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in motor, compressor, and drum fabrication. The vendor base organizes around three archetypes: diversified electronics conglomerates with captive distribution, dedicated appliance engineering houses with hard-water specialization, and domestic manufacturing groups with backward integration into critical components. Competitive moves concentrate on inverter motor platform proliferation and NBFC financing partnership origination to collapse upfront purchase barriers.
Within the diversified electronics tier, LG Electronics Inc. and Samsung India Electronics Ltd exemplify platform integrators leveraging connected appliance ecosystems for premium positioning. Godrej & Boyce Mfg. Co. Ltd anchors the domestic manufacturing archetype through captive component production. IFB Industries Ltd occupies the engineering-specialist position with front-load platforms optimized for western Indian water conditions. Haier Group Corporation represents the Chinese multinational vector with scale-driven assembly operations.
| Leading Market Players |
|---|
| Haier Group Corporation |
| Godrej & Boyce Mfg. Co. Ltd. |
| LG Electronics Inc. |
| BSH Home Appliances |
| Panasonic Corporation |
| Samsung India Electronics Ltd |
| IFB Industries Ltd. |
| Electrolux AB |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in Noida and Pune assembly corridors compresses supplier pricing power while accelerating component localization bids under the PLI scheme. Manufacturers absorb margin pressure through captive motor and compressor production, passing residual cost volatility into tiered product positioning across Maharashtra and Gujarat distribution channels.
Pricing Analysis
Household buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with BIS five-star certification and inverter motor platforms commanding measurable premiums in electricity-tariff-sensitive municipalities. Price differentiation hinges on energy-efficiency grade and after-sales service bundling, while cost compression in semi-automatic tiers intensifies due to persistent rural demand for two-tub units. Price sensitivity concentrates among first-time automatic washing machine purchasers in Tier-2 electrification corridors, whereas Chennai and Coimbatore metropolitan clusters exhibit reduced elasticity for smart-connected configurations.
Supply Chain Analysis
LG Electronics and Godrej & Boyce hold dominant contract-manufacturing capacity across western and northern India industrial belts. Geographic supply concentration centers on Maharashtra, Gujarat, and Tamil Nadu assembly corridors, with critical dependencies on imported high-efficiency motor controllers and precision-engineered drum assemblies. Single-source vulnerability for variable-frequency drive components threatens production continuity, while distribution runs through organized retail chains and NBFC-integrated EMI origination networks displacing independent dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as Tier-2 city electrification and piped water access create distinct specification requirements across heterogeneous urban infrastructure, rewarding specialized engineering over standardized national portfolios.
For Market Incumbents: Entrench inverter motor platform dominance through technician training network densification, addressing field service scarcity that elongates repair cycles. Deepen backward integration into compressor production to buffer copper and steel input volatility threatening margin visibility. Prioritize BIS five-star certification preemption as the Central Electricity Authority tightens standby power limits. For New Entrants and Emerging Players: Establish a beachhead in hard-water-optimized front-load engineering for Gujarat and western Maharashtra municipalities where mineral-heavy supplies degrade conventional drum coatings. Target self-service laundry installations in Bengaluru and Hyderabad tech corridors replicating East Asian metropolitan density models. Pursue NBFC financing partnership origination to collapse upfront purchase barriers in semi-urban catchments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among inverter motor platform operators with predictive maintenance subscription capabilities hybridizing IoT diagnostics. Long-term viability favors component suppliers with captive supply of motor controllers and drum assemblies serving multiple OEM assembly networks. Monitor state-level water tariff reform implementation as inflection indicator for SKU fragmentation intensity across state boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Motor Platform Proliferation | BIS five-star label premiums capture electricity-tariff-sensitive households in Maharashtra and Gujarat municipalities. |
| NBFC Financing Partnership Origination | Retailer credit programs displace cash transactions in Tier-2 city semi-urban catchments. |
| Hard-Water Engineering Specialization | Front-load optimization for mineral-heavy western Indian supplies creates defendable technical differentiation. |
| Predictive Maintenance Subscription Launch | IoT-enabled diagnostics hybridize with motor platforms to create annuity revenue streams. |
| Technician Training Network Densification | Variable-frequency drive diagnostic capability shortage elongates repair cycles and erodes brand equity. |
Research Methodology
Cross-validation between primary interviews with plant engineers, aftermarket service heads, and category buyers at organized retail chains anchors the qualitative findings, while secondary validation draws from BIS certification databases, CEA appliance efficiency filings, and customs records tracking motor controller import flows. Bottom-up triangulation across regional distribution channel audits converges with top-down reconciliation against PLI scheme disbursement disclosures and state-level electricity regulatory commission tariff orders.
Calibration against historical replacement cycle patterns and electrification rollout timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, motor technology tier, load capacity specification, and end-use application type. CAGRs derive from regression analysis of household formation rates, disposable income trajectories, and municipal infrastructure investment pipelines feeding demand elasticity estimates.
Macroeconomic conditions sit as an overlay; deviation in copper and steel commodity price indices, rupee exchange rate volatility, and state-level water tariff reform implementation would shift the trajectory. Quarterly review of PLI scheme localization milestones, NBFC disbursement velocity, and BIS certification compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Asia-Pacific Microwave Oven Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Laundry Dryer Market
Appliances
Electric Yogurt Maker Market
Appliances
Small Appliances Market
Appliances
Europe Household Electric Grills Market
Appliances
Qatar Dishwashers Market
Appliances
Egypt Microwave Ovens Market
Appliances
Global Home Ice Maker Market
Appliances
United States Washing Machine Market
Appliances
North America Microwave Oven Market
Appliances
China Induction Hobs Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Conveyor Dishwasher Market
Appliances
US Electric Rice Cooker Market
Appliances
Induction Cooktops Market