
 Household Beauty Appliances Market | 2026-2036
Household Beauty Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Household Beauty Appliances Market Foresight
Subscription leasing and asset-light distribution models are rewriting competitive access in household beauty appliances, allowing emerging brands to bypass heavy capital requirements. Panasonic Corporation leverages its vertical integration in motor and heating technologies to sustain cost advantages across hair dryer and curling iron portfolios. Dyson Limited differentiates through proprietary airflow engineering and occupies the premium tier with direct-to-consumer channel control. Conair Corporation competes on manufacturing scale and navigates mass-market retail with broad SKU coverage.
Household beauty appliances encompass electrically powered personal grooming devices operating at voltages from 110 to 240V, incorporating ceramic, tourmaline, or titanium heating elements with temperature controls typically ranging between 150°C and 230°C for thermal styling tools, designed for non-professional use in residential settings. Facial cleansers employing sonic oscillation or rotating brush heads at frequencies between 100 and 300 Hz dominate unit volume, while LED therapy devices using red and blue wavelengths between 415 nm and 660 nm represent the fastest-growing technology segment as at-home skin treatment adoption broadens. Hair dryers with ionic technology command margin concentration due to consumer willingness to pay for frizz-reduction claims, whereas UV sterilization attachments remain nascent outside East Asian markets.
EMA medical device oversight and REACH chemical restrictions in Europe shape material selection and biocompatibility testing for devices making dermatological claims, while CE marking requirements enforce electrical safety standards across all powered units sold in EU member states. The US FDA regulates laser and light-based devices above specific power thresholds, creating compliance barriers for LED therapy entrants. Stakeholders must monitor evolving classification boundaries between cosmetic and medical devices as regulators respond to at-home treatment intensity levels.
Market Dynamics
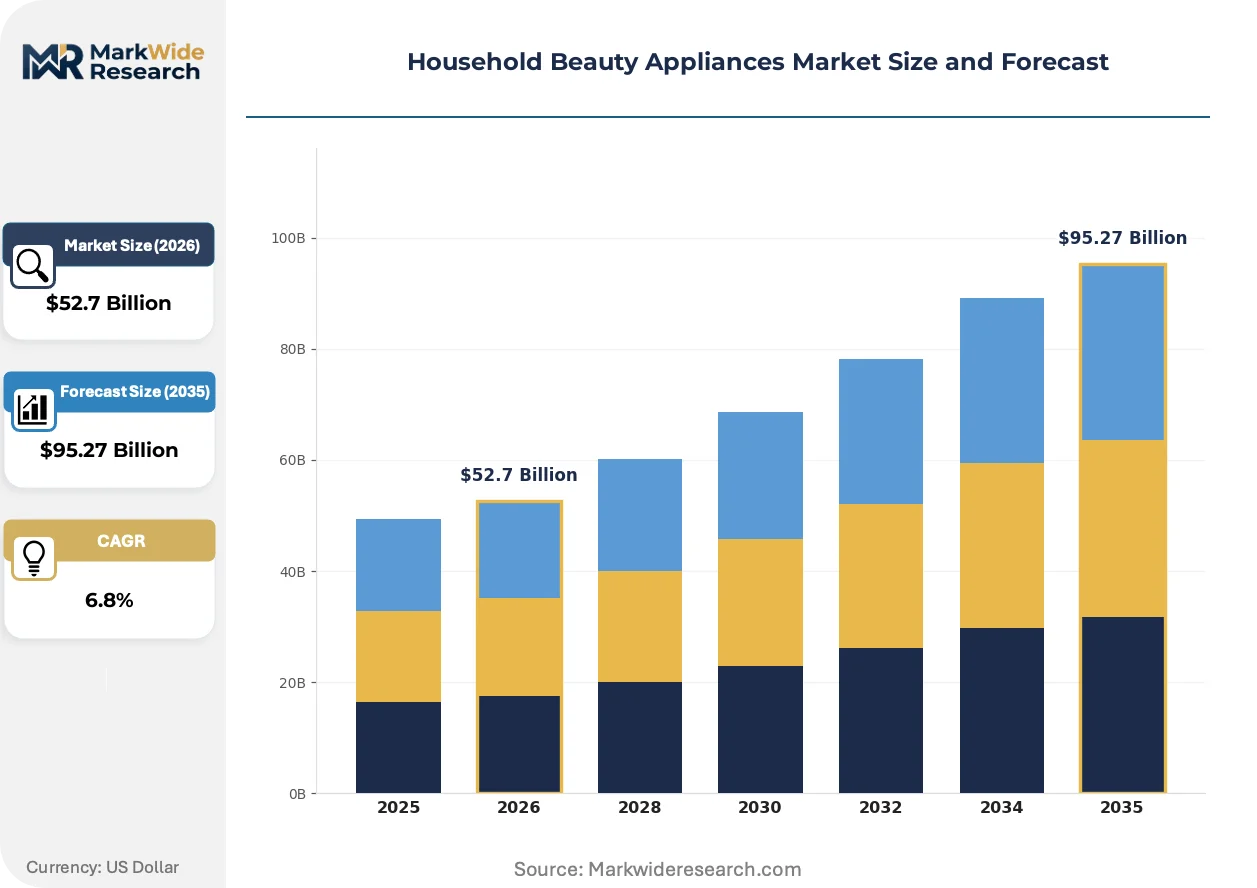
Subscription leasing models are restructuring competitive access in household beauty appliances, allowing emerging brands to bypass capital-heavy distribution infrastructure and challenge established incumbents through asset-light market entry.
Growth Catalysts
- Ionic technology penetration:Consumer willingness to pay premium prices for frizz-reduction claims is concentrating margin in hair dryers with ceramic and tourmaline heating elements.
- REACH compliance acceleration:ECHA restrictions on hazardous substances in heating elements and electronic components are forcing material upgrades that extend product lifecycles and justify replacement cycles.
- Professional stylist segment expansion:Service-at-home models are proliferating across North America and Western Europe, creating bulk procurement channels for salon-grade residential devices.
Market Restraints
- Heating element cost volatility:Ceramic and titanium raw material prices fluctuate with energy costs, compressing margins on mid-tier thermal styling tools.
- East Asian supply concentration:UV sterilization attachment manufacturing clusters heavily in China and South Korea, creating single-source vulnerability for brands seeking hygiene differentiation.
- FDA power thresholds:Laser and light-based devices above specified wattage face classification as medical devices, creating compliance barriers that delay LED therapy market entry.
Strategic Opportunities
- India domestic upgrading:Local consumers are transitioning from basic to premium devices as BIS certification builds trust in electrical safety standards.
- Sonic-LED convergence:Facial cleansers combining oscillation technology with red-blue wavelength therapy are opening premium price tiers previously segmented by function.
- Direct-to-consumer channel control:Brands bypassing traditional retail markup structures capture margin and customer data simultaneously.
Industry Challenges
- Biocompatibility testing timelines:EMA medical device oversight for dermatological claims extends certification cycles by 8-14 months.
- CE marking documentation burden:Electrical safety standard verification across EU member states requires redundant testing protocols that strain mid-cap R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Beauty Appliances Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dryers, Electric Razors, Curling Irons, Facial Cleansers Application: Personal Care, Salon Use, Skin Treatment, Hair Styling End User: Consumers, Professional Stylists, Salons, Health Spas Technology: Heat Technology, UV Sterilization, Ionic Technology, LED Therapy |
| Companies Covered | Koninklijke Philips N.V., Panasonic Corporation, Conair Corporation, L'Oréal S.A., Home Skinovations Ltd., Helen of Troy, Tria Beauty, Inc., Nu Skin Enterprises Inc., Dyson Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Beauty Appliances Market Shifts & Advancements
Technology convergence and regulatory boundary shifts are compressing traditional product category definitions. Device manufacturers must now navigate overlapping cosmetic and medical classifications while integrating multiple therapeutic modalities into single platforms.
Ceramic-tourmaline composite heating elements are hybridizing thermal styling performance by combining even heat distribution with negative ion emission. Premium residential buyers in Germany and Japan are adopting these hybrids at twice the rate of conventional single-material tools. This fusion is compressing the performance gap between professional salon equipment and home-use devices, forcing mid-tier brands to reposition on price or abandon the segment.
EMA medical device oversight is tightening classification boundaries for LED therapy devices making collagen-stimulation or acne-treatment claims. Manufacturers must now submit clinical efficacy data previously reserved for pharmaceutical pathways. The red-wavelength segment above 630 nm faces the steepest compliance burden, with several EU member states requiring notified body intervention before market placement.
Salon operators are unbundling after-sales service from equipment procurement, creating standalone maintenance contracts that third-party technicians fulfill. This shift fragments the traditional manufacturer-dealer relationship in France and Italy. Channel intermediaries that built positions on installation and repair bundled with initial sale are losing recurring revenue to independent service networks.
Household Beauty Appliances Market Segmentation
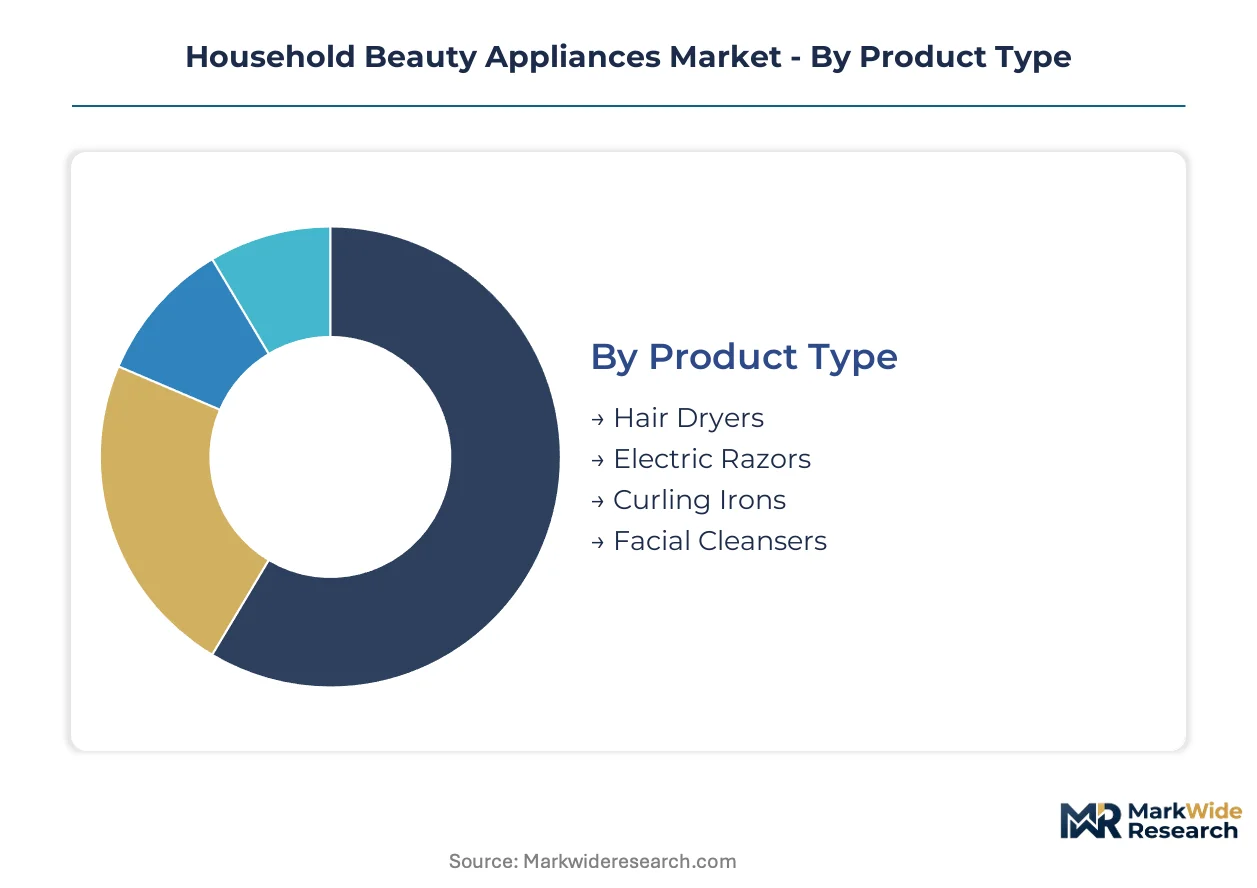
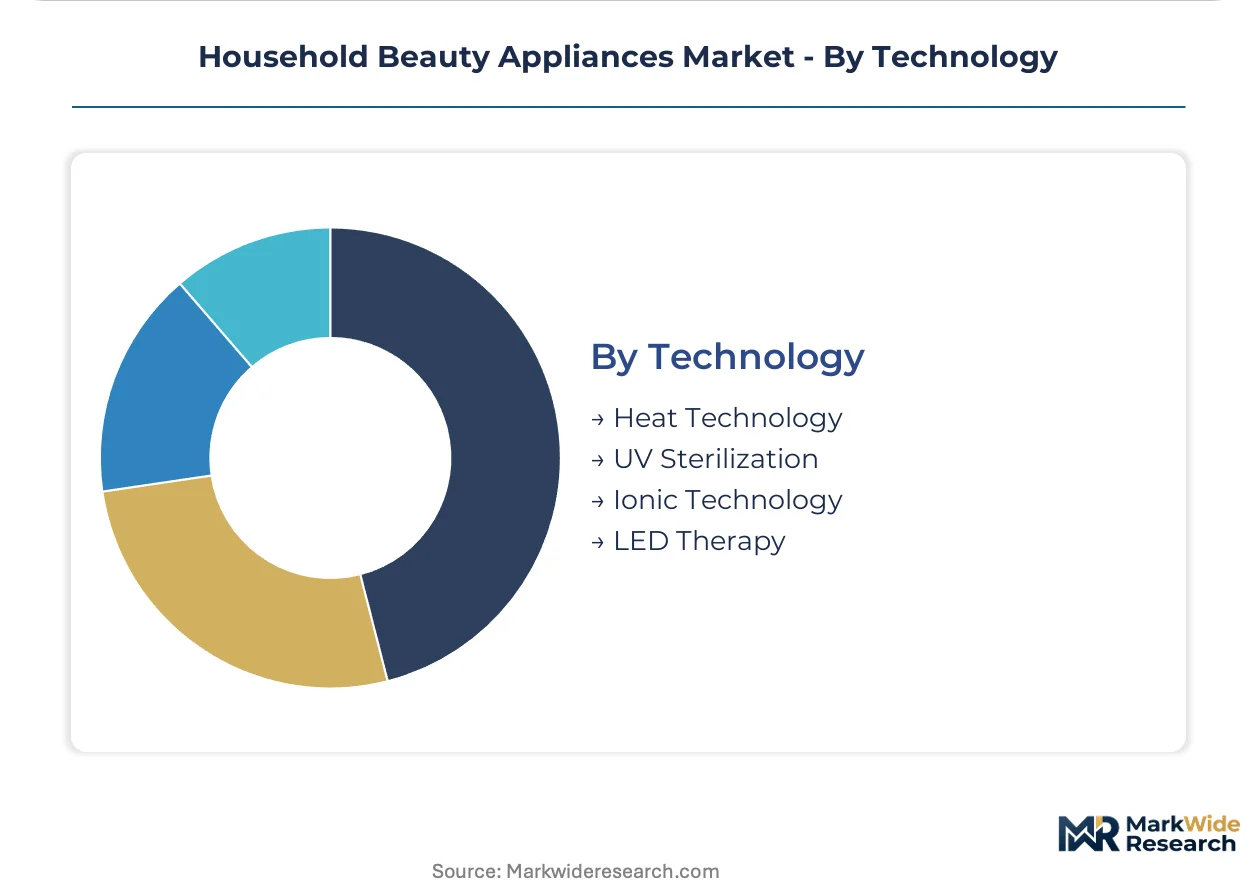
Segmentation in household beauty appliances reveals divergent margin structures across thermal versus light-based modalities. Manufacturers must align R&D portfolios with distinct regulatory pathways and replacement cycle dynamics.
Product Type:
Mature thermal tools dominate installed base volumes while emerging facial technologies capture premium positioning.
- Hair Dryers:Ceramic and tourmaline heating elements with ionic generators operate between 150°C and 230°C. Demand concentrates in Germany and Japan for hybrid ceramic-tourmaline composites as consumers accept 40-60% price premiums for frizz-reduction claims.
- Facial Cleansers:Sonic oscillation devices employing brush heads at 100-300 Hz frequencies represent the fastest-climbing segment. Korean and Chinese consumers drive volume as at-home skin treatment protocols displace clinic visits.
- Electric Razors:Rotary and foil cutting systems with lithium-ion power cells serve male grooming routines with 24-36 month replacement cycles.
- Curling Irons:Clamp-style and wand configurations using titanium barrels target styling enthusiasts seeking salon-equivalent curl formation.
Hair dryers retain volume leadership; facial cleansers hold the steepest expansion curve.
Application:
Cost tier stratification separates residential entry-level purchases from commercial-grade procurement specifications.
- Personal Care:Individual consumers purchasing for residential bathrooms and travel kits represent the foundational revenue layer with highest price sensitivity.
- Salon Use:Professional stylists operating mobile or home-based services now procure residential-grade devices with commercial durability expectations.
- Skin Treatment:LED therapy and microcurrent applications targeting collagen stimulation and acne management face FDA and EMA classification scrutiny.
- Hair Styling:Thermal tool deployment across daily grooming and special occasion preparation sustains replacement demand from heat element degradation.
Personal care anchors absolute volume; salon use applications are expanding most quickly.
End User:
Customer type determines channel configuration and service bundling requirements.
- Consumers:Individual purchasers through direct-to-consumer platforms and mass retail represent the default segmentation with lowest customer acquisition costs.
- Professional Stylists:Independent operators building mobile service businesses create bulk procurement channels previously served by salon distributors.
- Salons:Traditional brick-and-mortar operators are unbundling equipment from maintenance contracts, fragmenting manufacturer-dealer relationships in France and Italy.
- Health Spas:Wellness facilities integrating LED therapy into treatment menus require clinical-grade efficacy documentation for liability coverage.
Consumers dominate absolute transactions; professional stylists show the fastest user category growth.
Technology:
Supply concentration for electronic components shapes geographic sourcing strategies.
- Heat Technology:Ceramic, tourmaline, and titanium heating elements with thermostat controls constitute the mature core with established Chinese manufacturing clusters.
- LED Therapy:Red and blue wavelength devices between 415 nm and 660 nm face EMA medical device oversight for dermatological claims.
- Ionic Technology:Negative ion generators integrated into hair dryers command margin concentration through frizz-reduction marketing.
- UV Sterilization:Attachment modules for brush and tool hygiene remain concentrated in East Asian supply chains with limited Western adoption.
Heat technology retains installed base dominance; LED therapy climbs the fastest among emerging modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in household beauty appliances reveal concentrated manufacturing bases serving dispersed consumption markets. China maintains substantial trade surpluses in thermal styling tools and facial cleansing devices. Germany and Japan balance specialized component exports against premium finished goods imports.
China
Domestic brands capture escalating local demand for ionic hair dryers and LED therapy devices as urban consumers upgrade from basic models. MIIT enforces GB standards for electrical safety and electromagnetic compatibility across all powered personal care devices. Manufacturing clusters in Guangdong and Zhejiang provinces scale ceramic heating element production for export to Southeast Asian and European markets.
Germany
Professional stylists operating mobile services drive bulk procurement of salon-grade residential devices across North Rhine-Westphalia and Bavaria. ECHA REACH restrictions on hazardous substances in heating elements force material upgrades that extend product replacement cycles. Industrial concentration around Stuttgart and Munich supports precision motor manufacturing for premium hair dryer brands.
United States
Direct-to-consumer channel expansion accelerates as brands bypass traditional retail markup structures for margin capture. FDA regulates laser and light-based devices above specified power thresholds, creating compliance barriers for LED therapy entrants. Distribution networks concentrate around Los Angeles and New York metro areas for influencer marketing integration and logistics efficiency.
Japan
Consumers demonstrate elevated willingness to pay for hybrid ceramic-tourmaline thermal styling tools with frizz-reduction claims. METI oversees electrical appliance safety under the Electrical Appliance and Material Safety Law, requiring PSE marking for all powered devices. Manufacturing expertise clusters in Osaka-Kobe and Nagoya regions for precision heating element and motor component production.
India
Urban middle-class expansion generates demand for premium facial cleansers and hair styling devices as at-home grooming protocols displace salon visits. BIS certification requirements for electrical safety build consumer trust and accelerate formal market penetration. Industrial activity concentrates in Maharashtra and Gujarat for contract manufacturing of entry-level and mid-tier appliances.
Household Beauty Appliances Market Competitive Landscape
On the supply side, the industry is structured around tiered competition separating premium engineering specialists from mass-market scale operators. Panasonic Corporation and Dyson Limited anchor the premium tier through proprietary motor and airflow technologies. Mid-cap specialists compete on manufacturing efficiency and retail channel breadth. Dominant competitive moves include backward integration into heating element supply and direct-to-consumer channel bypass of traditional retail.
Among diversified electronics conglomerates, Koninklijke Philips N.V. and Panasonic Corporation represent archetypal positions combining consumer appliance heritage with healthcare adjacencies. Dyson Limited exemplifies the premium engineering specialist model. Conair Corporation occupies a position within the mass-market scale tier. L'Oréal S.A. represents beauty industry incumbents extending into device categories through brand leverage rather than native electronics capability.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Conair Corporation |
| L'Oréal S.A. |
| Home Skinovations Ltd. |
| Helen of Troy |
| Tria Beauty, Inc. |
| Nu Skin Enterprises Inc. |
| Dyson Limited |
| Others |
Supply & Pricing Matrix
Guangdong province manufacturing clusters anchor global ceramic heating element capacity, and their output discipline translates directly into pricing power for ionic hair dryer tiers. REACH compliance costs in Europe and FDA classification thresholds in the United States create natural price stratification that protects premium positioning against commoditization pressure from mass-market imports.
Pricing Analysis
Professional stylists anchor three-tier pricing structure across premium, standard, and economy levels, with salon-grade residential devices commanding 40-60% markups over basic consumer units. Price differentiation rests on certification grade—CE marking for EU access versus basic electrical safety for emerging markets—and brand premium for frizz-reduction technology claims. Pricing pressure stems from ceramic and titanium raw material cost volatility, which compresses margins on mid-tier thermal styling tools. Individual consumers purchasing through mass retail channels exhibit highest price sensitivity, while health spas integrating LED therapy demonstrate lowest sensitivity due to liability coverage requirements.
Supply Chain Analysis
Extended payment terms from East Asian component suppliers now stretch to 90-120 days, easing working capital pressure for brands assembling finished goods. Manufacturing concentrates in China, South Korea, and Japan, with ceramic heating elements and sonic motor assemblies drawing from established regional clusters. Raw material dependencies include tourmaline mineral feedstock, lithium-ion power cells, and precision thermostat controls. Single-source vulnerability pervades UV sterilization attachment sourcing, where Korean and Chinese suppliers dominate. Distribution runs through direct-to-consumer platforms and mass-market retail, with influencer marketing integration in Los Angeles and New York metro areas bypassing traditional markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as service-at-home models proliferate and unbundle traditional salon equipment procurement, creating niche entry points for specialized device manufacturers.
For Market Incumbents: Pre-empt subscription leasing encroachment by capturing professional stylist bulk procurement channels before emerging brands establish asset-light distribution. Backward integration into heating element supply secures margin against ceramic and titanium price volatility. Invest in EMA medical device certification pathways for LED therapy claims to defend positioning against beauty industry incumbents extending into device categories.
For New Entrants and Emerging Players: Mobile professional stylists in North America and Western Europe represent the most penetrable entry point, as this segment procures residential-grade devices with commercial durability expectations yet lacks dedicated supplier relationships. Sonic-LED convergence devices open premium tiers previously segmented by function, with Korean and Chinese consumers driving initial volume. Pursue direct-to-consumer channel control to capture margin and customer data simultaneously, bypassing fragmented manufacturer-dealer relationships in France and Italy.
For Investors and Strategic Acquirers: Long-term, this sits as a premiumization play because urban consumers across China, India, and Southeast Asia upgrade from basic to premium devices as electrical safety certification builds trust. Acquisition targets should emphasize brands with proprietary motor or airflow engineering and established direct-to-consumer infrastructure. Watch FDA classification boundary shifts for LED therapy devices as the inflection indicator—reclassification above specified power thresholds would reshape competitive access and valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses traditional retail markup structures for margin capture and customer data ownership. |
| EMA Medical Device Certification | Enables collagen-stimulation and acne-treatment claims in EU markets with clinical efficacy documentation. |
| Ceramic-Tourmaline Composite Development | Compresses performance gap between salon equipment and home-use devices in Germany and Japan. |
| Subscription Leasing Model | Allows emerging brands to bypass capital-heavy distribution infrastructure and challenge incumbents. |
| Backward Integration into Heating Elements | Secures supply against ceramic and titanium raw material price volatility affecting mid-tier tools. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with product development executives at device manufacturers, regulatory affairs leads navigating FDA and EMA classification, salon procurement managers, and direct-to-consumer channel heads; and secondary validation through SEC filings, MIIT GB standard disclosures, ECHA REACH restriction updates, and customs trade records. Bottom-up triangulation across product-level volume estimates and top-down macroeconomic sizing ensured convergence.
Forecast inputs incorporated technology segment growth curves, regional regulatory pathway timelines, and replacement cycle dynamics across thermal and light-based modalities. Segmentation dimensions modeled include product type, application tier, end-user archetype, and technology modality across the projection horizon. CAGRs derived from installed base expansion rates, premium tier penetration assumptions, and service-at-home model proliferation. Industry-specific inputs encompassed EMA medical device classification boundary shifts and BIS certification acceleration effects in India.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, cross-border tariff regimes, or semiconductor component availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and technology adoption curves. Macroeconomic contraction, accelerated REACH restriction expansion, or breakthrough battery technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Hairdryer Market
Appliances
North America Tumble Dryers Market
Appliances
Electric Rice Cooker Market
Appliances
Water Heater Market
Appliances
Microwave Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
United States Microwave Oven Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Small Electric Kettles Market
Appliances
Garments Steamer Market
Appliances
Toaster Ovens Market
Appliances
Induction Cooktops Market
Appliances
Asia-Pacific Microwave Oven Market
Appliances
GCC Microwave Oven Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Saudi Arabia Gas Hobs Market