
 Residential Cooker Hoods Market | 2026-2036
Residential Cooker Hoods Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Cooker Hoods Market Analytics
Multi-source component procurement is decoupling from the single-source steel sourcing that historically dominated cooker hood manufacturing. AB Electrolux leverages captive European stamping capacity to control stainless steel supply for its premium wall-mounted lines. Robert Bosch GmbH sustains dual-source motor contracts across Southeast Asia and Eastern Europe, insulating its assembly network from regional disruption. Whirlpool Corporation anchors North American distribution through dedicated logistics partnerships with big-box retailers, while Elica specializes in compact blower engineering for under-cabinet units aimed at urban apartments.
A residential cooker hood is a mechanical ventilation appliance installed above cooking surfaces, typically rated between 200 and 1200 cubic feet per minute extraction capacity, designed to remove airborne grease, combustion byproducts, smoke, odors, heat, and steam from kitchen environments. Wall-mounted and island configurations command the widest margin pools in premium segments where designer aesthetics and high-CFM performance justify elevated price points. Under-cabinet units dominate volume shipments across mass-market channels, though downdraft systems are gaining traction in open-plan layouts where overhead structures would obstruct sightlines. Smart controls integration represents the fastest-growing feature dimension, with Wi-Fi-enabled auto-sensing and filter-life monitoring now standard in mid-tier and above product lines.
ENERGY STAR in the United States, EU Ecodesign and CE marking in Europe, and China's GB standards collectively shape minimum efficiency thresholds, noise limits, and grease filtration requirements that determine market access for manufacturers. The US Environmental Protection Agency periodically tightens ENERGY STAR criteria, forcing redesign cycles that favor brushless DC motor platforms and multi-stage baffle filters. Stakeholders must monitor evolving building code adoption of makeup air requirements, as jurisdictions in California, Germany, and Ontario increasingly mandate compensating ventilation for high-extraction installations that depressurize tightly sealed homes.
Market Dynamics
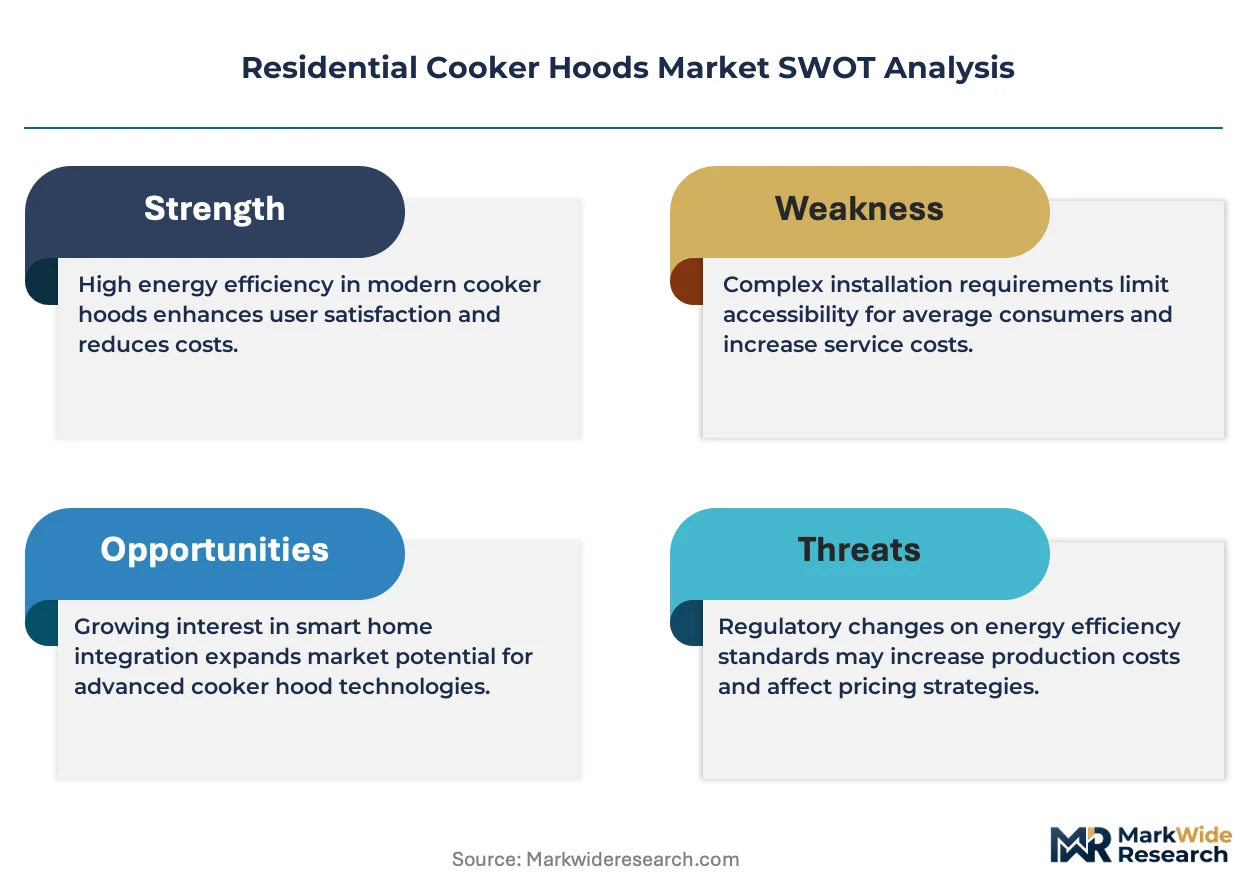
Brushless DC motor platforms are compressing energy consumption thresholds while EU Ecodesign and ENERGY STAR tighten minimum efficiency requirements, forcing simultaneous redesign of blower architectures and filter systems across all price tiers.
Growth Catalysts
- ENERGY STAR 8.0 Criteria:The US Environmental Protection Agency's tightened ventilation standards are pulling brushless DC motor adoption into mid-tier product lines, expanding addressable market for efficient blowers.
- Open-Plan Residential Construction:Premium housing developments in China, Germany, and the United States are specifying high-CFM island and downdraft configurations that command wider margin pools than standard wall-mounted units.
- Makeup Air Mandates:California Title 24 and Ontario building codes now require compensating ventilation for extraction rates above 400 CFM, expanding system scope and component attach rates.
Market Restraints
- Stainless Steel Input Volatility:Cold-rolled 304-grade stainless remains the dominant chassis material, with price swings at European and Asian mills compressing margin predictability for stamped-housing manufacturers.
- Regional Assembly Concentration:Motor winding and controller assembly clusters in Southeast Asia create single-source exposure for brands without dual-source contracts across Eastern Europe.
- Acoustic Performance Limits:Sone reduction below 3.0 at 600 CFM requires larger blower housings that conflict with under-cabinet space constraints in urban apartment kitchens.
Strategic Opportunities
- Smart Control Convergence:Wi-Fi-enabled auto-sensing and filter-life monitoring are creating attach-rate expansion in mid-tier lines where connectivity was previously absent.
- Retrofit Channel Penetration:Independent kitchen renovation contractors in Germany and the United States represent underdeveloped routes to market beyond big-box retail concentration.
- China GB Standard Alignment:Upcoming revisions to China's national ventilation efficiency standards will force domestic manufacturer consolidation, opening share for compliant imported platforms.
Industry Challenges
- Brushless Motor Controller Talent Scarcity:Firmware engineering for variable-speed blower control is concentrating at a handful of component suppliers, extending R&D timelines for in-house motor development.
- Multi-Jurisdiction Certification Overlap:Simultaneous ENERGY STAR, CE marking, and GB testing creates redundant laboratory cycles that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Cooker Hoods Market |
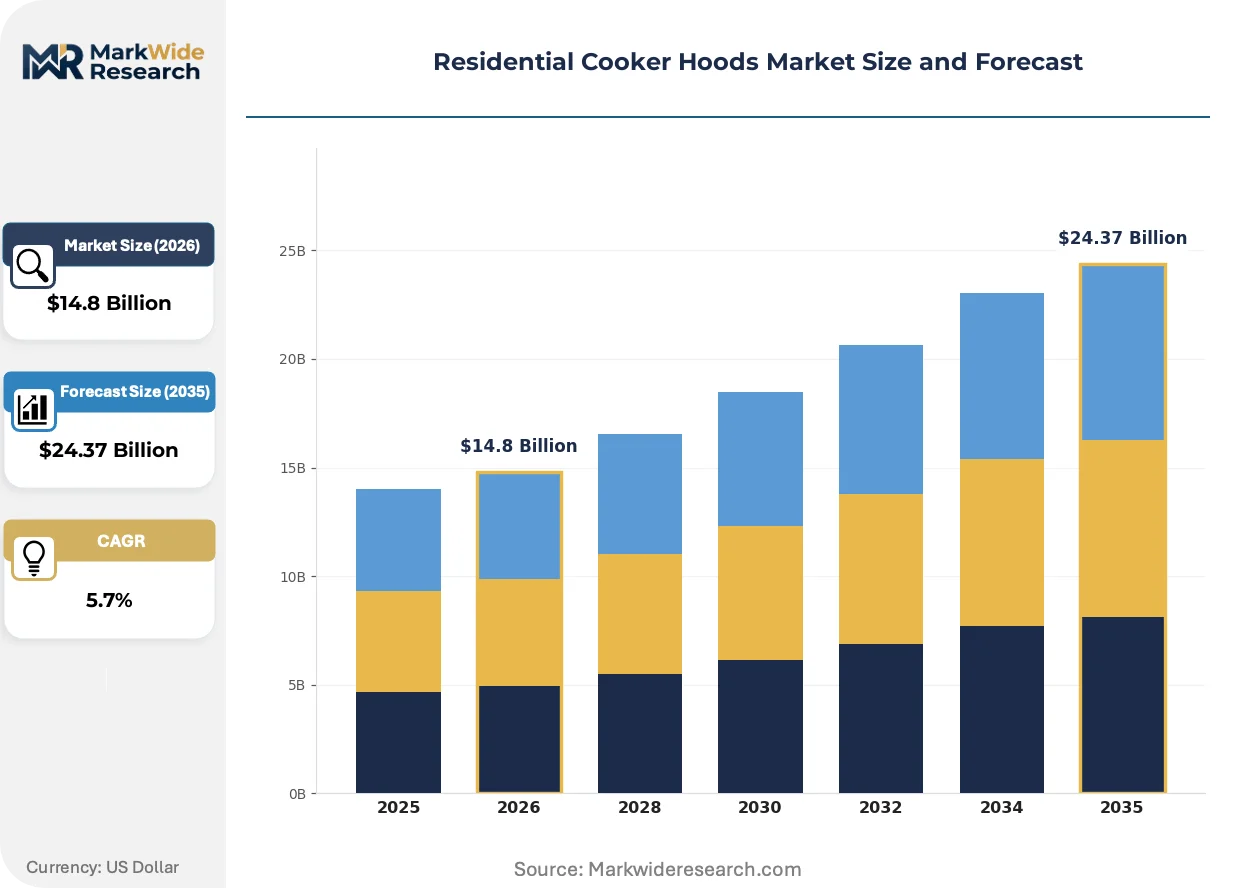
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Under-Cabinet, Wall-Mounted, Downdraft, Island Installation Type: Hardwired, Plug-In, Ducted, Ductless Material: Stainless Steel, Glass, Aluminum, Composite Feature: Ventilated, Non-Ventilated, Recirculating, Smart Controls |
| Companies Covered | AB Electrolux, Broan-NuTone, LLC, Robert Bosch GmbH, Whirlpool Corporation, Samsung Electronics, Elica, Panasonic Corporation, Haier Smart Home, KOBE Range Hoods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Cooker Hoods Market Evolving Landscape
Sensor-driven ventilation control and connected appliance ecosystems are compressing the feature gap between mid-tier and premium product lines, while regulatory tightening on energy and noise performance forces simultaneous hardware and software redesign.
Auto-sensing grease and particulate detection is automating extraction speed adjustment based on real-time cooking intensity rather than manual user selection. Mid-tier buyers in North American and Western European markets are adopting these systems at pace previously reserved for premium island configurations. This capability is automating the traditional trade-off between noise comfort and extraction performance, allowing sustained high-CFM operation only when sensor thresholds demand it.
EU Ecodesign 2024 ventilation efficiency thresholds are mandating multi-stage baffle filter architectures that reduce pressure drop across the grease capture stage. Manufacturers serving European markets are redesigning hood cavities to accommodate deeper filter stacks without increasing overall chassis height. Wall-mounted units between 30 and 36 inches face the steepest redesign burden, as these dimensions dominate retrofit replacement cycles where ceiling height constraints prevent dimensional expansion.
Builder and contractor procurement is consolidating around pre-certified product bundles that combine hood, ducting, and makeup air components into single-SKU offerings. Big-box retail and wholesale distribution in the United States are displacing independent HVAC supply houses for new construction volume. This channel compression is most visible in master-planned residential developments across California, Texas, and Florida where national builders specify uniform appliance packages across multi-hundred-unit phases.
Residential Cooker Hoods Market Segmentation
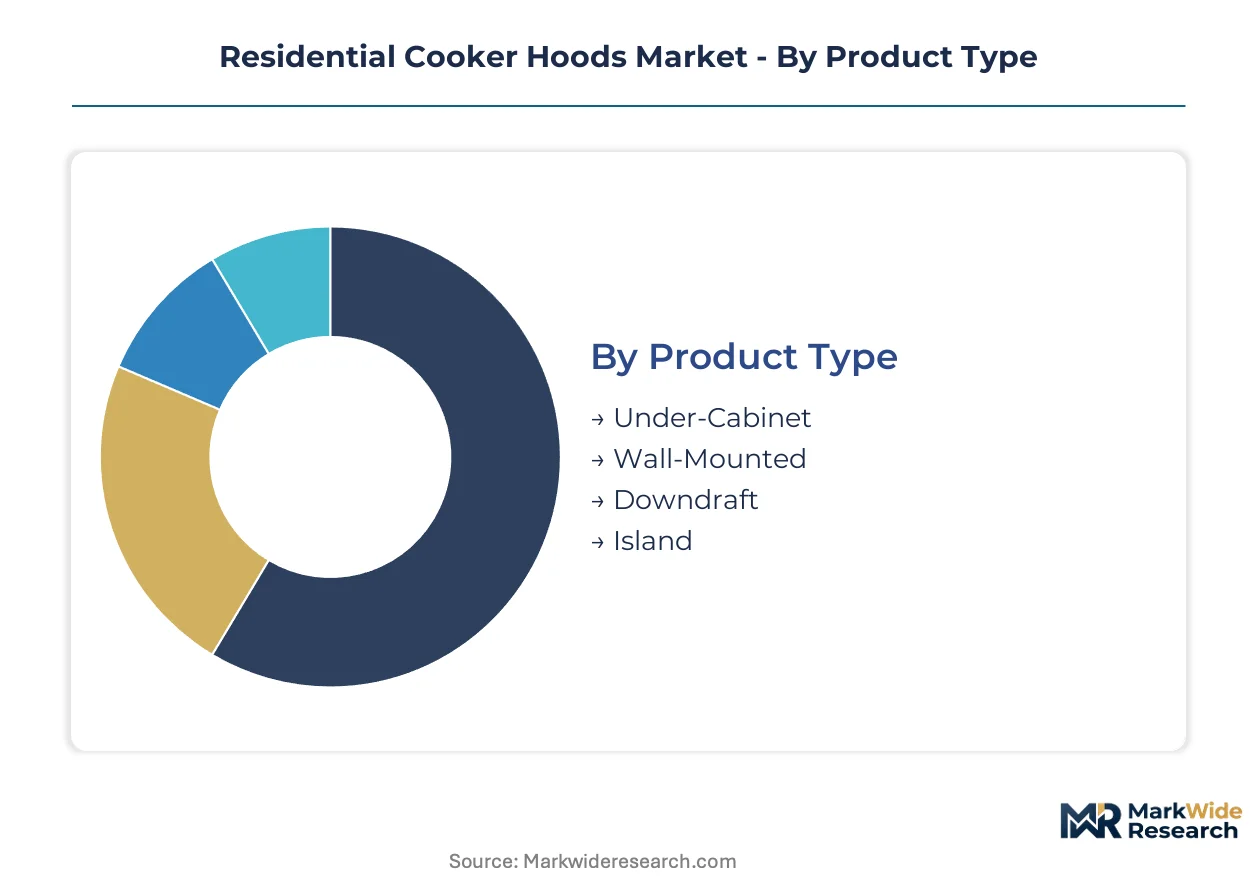
Segmentation in residential cooker hoods reveals how capital deployment, regulatory compliance, and installation constraints fragment manufacturing priorities. Each dimension carries distinct tooling requirements and margin profiles that reshape competitive positioning across price tiers.
Product Type:
Capital intensity peaks with island configurations requiring specialized blower engineering and structural mounting hardware.
- Under-Cabinet:Compact blower housings squeeze into confined spaces above ranges in urban apartments. Volume concentrates in mass-market channels across Germany and the United States where kitchen renovation rates remain elevated, though acoustic performance limits below 3.0 sones constrain design flexibility.
- Wall-Mounted:Chimney-style enclosures dominate premium retrofit cycles with designer aesthetic premiums. Demand clusters in open-plan layouts across China and North American suburban developments where ceiling height accommodates taller duct runs.
- Downdraft:Retractable blower systems integrate into cooktop surrounds for sightline preservation.
- Island:Suspended canopy designs require reinforced ceiling structures and high-CFM motors.
Most installed capacity flows through Under-Cabinet. Expansion is steepest in Island.
Installation Type:
Electrical and ventilation infrastructure requirements split procurement between new construction and replacement channels.
- Ducted:External exhaust systems achieve superior grease and odor removal through rigid or flexible metal ducting. California Title 24 and Ontario building codes now mandate makeup air integration for extraction above 400 CFM, expanding system scope and contractor attach rates.
- Ductless:Recirculating configurations with charcoal filtration suit multi-unit dwellings lacking external wall access. Adoption concentrates in older urban housing stock across European cities where structural modifications face heritage preservation constraints.
- Hardwired:Permanent electrical connections dominate new construction specifications.
- Plug-In:Corded installations facilitate replacement cycles without electrician involvement.
Ducted systems carry the highest average selling prices. Ductless configurations are climbing the fastest in metropolitan renovation.
Material:
Raw material volatility and finishing complexity determine sourcing strategies and margin predictability.
- Stainless Steel:Cold-rolled 304-grade dominates chassis fabrication with proven corrosion resistance and aesthetic durability. Price swings at European and Asian mills compress margin predictability for stamped-housing manufacturers serving mid-tier and premium lines.
- Glass:Tempered canopy panels enable designer transparency and integrated LED lighting. Demand concentrates in premium island and wall-mounted configurations across Chinese and German markets where visual minimalism commands price premiums.
- Aluminum:Lightweight extrusions reduce shipping costs for under-cabinet units.
- Composite:Engineered polymer blends absorb vibration and enable complex geometric forms.
Stainless steel absorbs the majority of material procurement spend. Glass is gaining share fastest in designer-configured premium tiers.
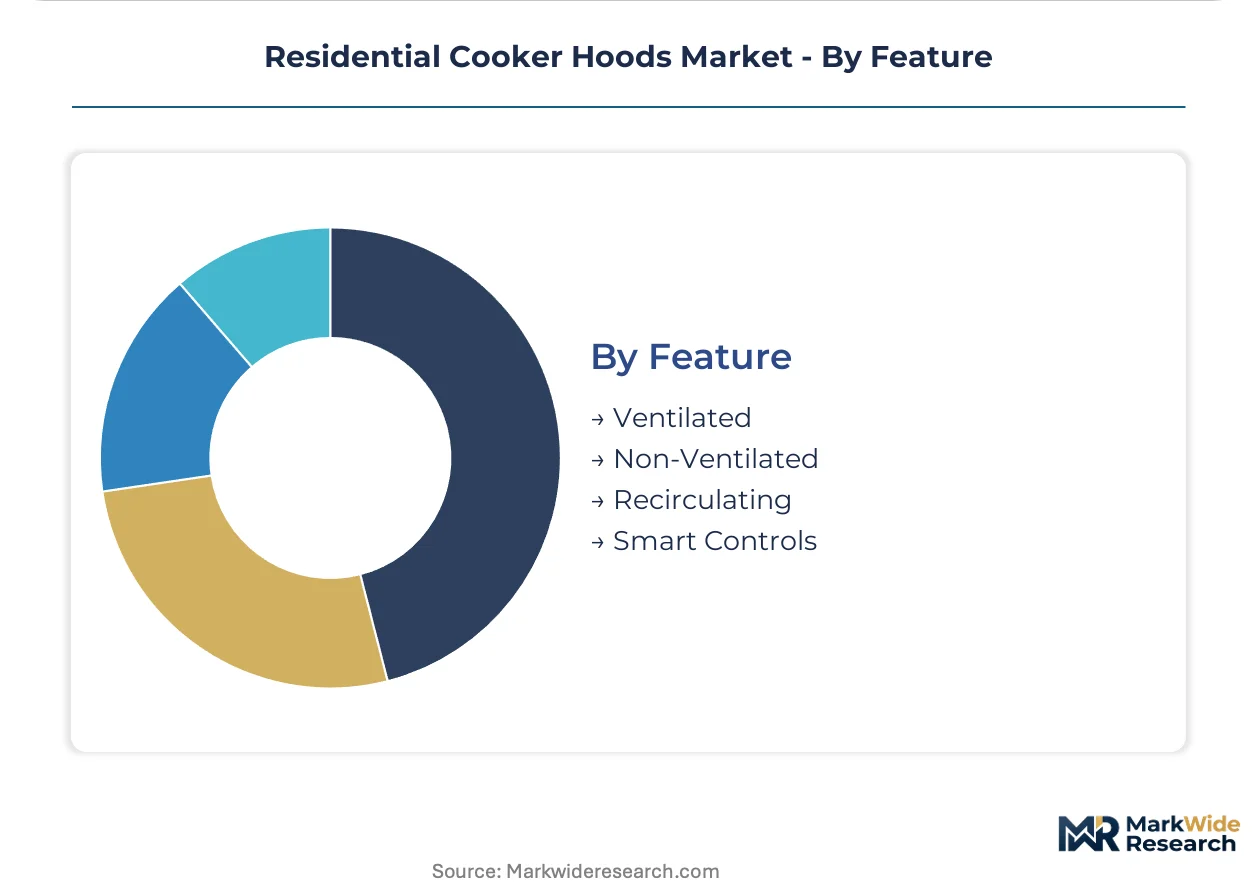
Feature:
Electronic content and connectivity integration are reshaping bill-of-materials composition and firmware development priorities.
- Smart Controls:Wi-Fi-enabled auto-sensing and filter-life monitoring automate extraction speed based on real-time cooking intensity. Mid-tier buyers in North American and Western European markets are adopting these systems at pace previously reserved for premium island configurations.
- Ventilated:Direct exhaust to exterior remains the performance standard for grease and combustion byproduct removal. ENERGY STAR 8.0 criteria and EU Ecodesign regulations are forcing brushless DC motor adoption to meet tightened efficiency thresholds.
- Non-Ventilated:Basic filtration without active extraction suits constrained installations.
- Recirculating:Charcoal-filtered internal processing enables deployment without ducting infrastructure.
Ventilated systems retain the largest installed base. Smart Controls represent the steepest expansion trajectory across all price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Pearl River Delta manufacturing corridor concentrates the largest share of motor winding and controller assembly capacity for residential ventilation appliances. Kitchen renovation rates in Germany and the United States sustain replacement demand for premium wall-mounted configurations. Regulatory divergence across ENERGY STAR, EU Ecodesign, and GB standards forces manufacturers to maintain parallel certification pipelines.
United States
California Title 24 mandates makeup air integration for extraction systems above 400 CFM, expanding contractor attach rates for system bundles. The EPA's ENERGY STAR 8.0 criteria tighten ventilation efficiency thresholds, forcing brushless DC motor adoption into mid-tier product lines. Big-box retail concentration in Texas and Florida channels volume through national builder procurement programs.
Germany
EU Ecodesign 2024 regulations mandate multi-stage baffle filter architectures that reduce pressure drop across grease capture stages. The country's national energy regulator enforces acoustic performance limits that constrain under-cabinet space utilization in urban apartments. Industrial clusters in North Rhine-Westphalia host captive stamping capacity for stainless steel chassis fabrication.
China
GB standard revisions for ventilation efficiency force domestic manufacturer consolidation, opening share for compliant imported platforms. MIIT oversees appliance efficiency labeling that shapes procurement decisions in premium housing developments. The Yangtze River Delta anchors motor controller assembly clusters serving brands across Southeast Asia.
Japan
METI administers JIS standards that set baseline requirements for grease filtration and noise emissions in residential kitchens. Compact blower engineering dominates demand in Tokyo's high-density apartment stock where ceiling height constraints prevent dimensional expansion. Osaka-based fabricators specialize in sensor-driven ventilation control systems.
Italy
Designer aesthetic premiums for chimney-style enclosures concentrate demand in Lombardy and Emilia-Romagna renovation markets. CE marking requirements align with EU Ecodesign thresholds for energy consumption and acoustic performance. The country's metalworking tradition supports specialized stainless steel finishing for premium island configurations.
Residential Cooker Hoods Market Competitive Landscape
Global majors compete with regional champions across certification compliance and channel access dimensions. The vendor base stratifies into three tiers: diversified appliance conglomerates with captive supply chains, specialized ventilation engineering houses with design differentiation, and contract manufacturers serving private-label programs. Consolidation pressure intensifies as ENERGY STAR, EU Ecodesign, and GB testing cycles extend product development timelines. Dominant competitive moves include backward integration into motor controller firmware development and geographic expansion through pre-certified product bundles.
Among diversified appliance conglomerates, AB Electrolux and Robert Bosch GmbH exemplify the captive manufacturing archetype, leveraging in-house stamping and dual-source motor contracts to insulate assembly networks from regional disruption. Whirlpool Corporation occupies a position within the North American channel concentration archetype, anchoring distribution through dedicated logistics partnerships with big-box retailers. These three companies represent distinct strategic postures: European-based vertical integration, German-engineered supply redundancy, and American retail scale penetration.
| Leading Market Players |
|---|
| AB Electrolux |
| Broan-NuTone, LLC |
| Robert Bosch GmbH |
| Whirlpool Corporation |
| Samsung Electronics |
| Elica |
| Panasonic Corporation |
| Haier Smart Home |
| KOBE Range Hoods |
| Others |
Value Network & Pricing Analysis
Brushless DC motor adoption is simultaneously compressing energy operating costs and concentrating controller firmware expertise among a handful of Southeast Asian suppliers, reshaping both manufacturing economics and procurement leverage for cooker hood assemblers across all price tiers.
Pricing Analysis
Input-cost pass-through from cold-rolled 304-grade stainless steel volatility dominates margin pressure for stamped-housing manufacturers serving mid-tier lines. Three-tier pricing structure across premium, standard, and economy levels separates designer glass-canopy island configurations from basic under-cabinet units, with ENERGY STAR 8.0 certification tier and brand heritage as primary price differentiation drivers. Pricing pressure stems from EU Ecodesign 2024 compliance costs forcing multi-stage baffle filter redesigns. Independent kitchen renovation contractors exhibit highest price sensitivity, while premium housing developers in China and Germany show lowest sensitivity to aesthetic premiums.
Supply Chain Analysis
Single-source vulnerability sits with brushless DC motor controller assembly clusters concentrated in China's Yangtze River Delta and Vietnam's northern industrial provinces. Raw material dependencies center on cold-rolled stainless steel from European and Asian mills, rare-earth magnets for motor platforms, and tempered glass for premium canopy fabrication. Supply chain risk manifests as tariff exposure on Chinese-sourced electronic components amid evolving trade policy. Distribution runs through big-box retail partnerships in the United States and dedicated HVAC wholesale channels in Germany, with builder-direct procurement consolidating in master-planned California and Texas developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in smart control attach-rate growth and premium island configuration demand, justified by brushless DC motor cost curves flattening efficiency premiums into mid-tier price bands.
For Market Incumbents: Extend firmware development capabilities in-house to reduce dependency on concentrated Southeast Asian controller suppliers, while simultaneously deepening captive stainless steel stamping capacity in North Rhine-Westphalia or comparable European industrial clusters. ENERGY STAR 8.0 and EU Ecodesign 2024 compliance timelines compress competitive response windows, making certification investment the critical defensive lever against specialized ventilation engineering houses. For New Entrants and Emerging Players: Independent kitchen renovation contractors in Germany and the United States represent an underserved buyer archetype with fragmented procurement patterns and limited brand loyalty. White-space targets include ductless recirculating configurations for European heritage-constrained urban housing and compact blower systems for Tokyo-style high-density apartments. A direct-to-contractor go-to-market angle bypasses big-box retail concentration. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers serving private-label programs without captive motor development or certification pipelines. Long-term viability across the five-to-ten year window favors targets with established ENERGY STAR, CE marking, and GB standard testing infrastructure. The signal to watch is consolidation among domestic Chinese manufacturers as GB standard revisions force compliance-driven exits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Controller Firmware | Reduces dependency on concentrated Southeast Asian suppliers and accelerates ENERGY STAR 8.0 compliance cycles. |
| Pre-Certified Product Bundle Expansion | Captures California Title 24 makeup air mandate attach-rate expansion through hood-ducting-makeup air single-SKU offerings. |
| Smart Control Platform Integration | Wi-Fi-enabled auto-sensing and filter-life monitoring compress the feature gap between mid-tier and premium lines. |
| Retrofit Channel Penetration | Independent kitchen renovation contractors in Germany and the United States offer underdeveloped routes beyond big-box retail. |
| GB Standard Alignment Investment | Upcoming China ventilation efficiency revisions will force domestic consolidation, opening share for compliant imported platforms. |
Research Methodology
Multiple input streams — primary interviews with appliance manufacturing executives, HVAC contractor network heads, and big-box retail category buyers; secondary validation through ENERGY STAR certified product listings, EU Ecodesign compliance databases, and customs trade records; plus regulatory filing analysis — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Historical shipment data was cross-referenced against panel input from motor controller suppliers and stainless steel distributors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, installation configuration, material composition, and feature tier, with CAGRs derived from regression analysis against housing construction permits and kitchen renovation expenditure indices.
Underlying measurement precision varies by segment; ducted wall-mounted and island configurations carry tighter precision than ductless recirculating systems due to more visible channel tracking. Forecasts reflect assumptions about regulatory enforcement continuity, raw material price stability, and smart control adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Brazil Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Electrical Appliances Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Built-In Appliance Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
Electric Household Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Built-In Hobs Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Household Appliance Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Small Home Appliances Market
Home Appliances
United States Laundry Appliances Market