
 Personal Care Appliances Market | 2026-2036
Personal Care Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Care Appliances Market Analysis
Connected sensor integration and AI-driven temperature control is fragmenting traditional hardware architectures across personal care appliances, forcing manufacturers to rebuild platforms around digital layer competencies. Koninklijke Philips N.V. anchors its position through proprietary SenseIQ thermal adaptation systems that sustain premium pricing in hair care. Panasonic Corporation leverages its battery chemistry heritage to dominate cordless shaving and grooming portfolios. Dyson Limited differentiates through in-house motor design and air multiplier engineering that extends its technical moat beyond conventional heating elements.
Personal care appliances comprise electrically powered devices engineered for individual grooming, hygiene, and aesthetic maintenance, typically incorporating heating elements rated between 1200W and 2200W, DC motors operating at 80,000–110,000 RPM, or ultrasonic transducers generating 6,000–8,000 vibrations per minute for skin cleansing and hair management applications. Hair dryers and electric shavers constitute the established volume base where manufacturing scale and replacement cycles generate predictable cash flows, while facial cleansing devices represent the fastest-expanding margin pool as dermatological endorsement and spa-at-home positioning command premium price points. Ionic and ceramic technologies concentrate in professional-grade segments where heat distribution uniformity and frizz reduction justify elevated price tiers, whereas cordless architectures penetrate travel and male grooming subcategories where portability overrides raw power specifications.
FDA oversight of laser and light-based devices, EU REACH compliance for nickel release in metal components, and Ecodesign Directive energy efficiency thresholds collectively elevate compliance costs while restricting market access for non-compliant imports. The EU Green Deal's extended producer responsibility frameworks are reshaping material selection and end-of-life collection obligations across European distribution channels. Stakeholders must monitor how battery chemistry regulations and right-to-repair mandates will reshape product architecture decisions and aftermarket service economics.
Market Dynamics
Cordless lithium-ion architectures are forcing manufacturers to reengineer thermal management systems around battery chemistry constraints rather than AC power assumptions, compressing product development cycles and elevating R&D spend thresholds.
Growth Catalysts
- EU Green Deal Extended Producer Responsibility:Mandates for end-of-life collection infrastructure are accelerating circular design investments among appliance manufacturers targeting European distribution channels.
- Professional salon procurement expansion:Licensed stylists in the United States are upgrading tool inventories as cordless runtime specifications now match corded performance benchmarks.
- AI-driven temperature modulation:Embedded sensor arrays enable real-time thermal adaptation that reduces heat damage claims and supports premium positioning.
Market Restraints
- Neodymium magnet supply concentration:High-performance DC motor production depends on rare earth processing capacity concentrated in China's Inner Mongolia refining corridor.
- FDA 510(k) clearance timelines:Laser and light-based hair removal devices face 12-18 month regulatory review periods that freeze product launch schedules.
- Nickel release compliance costs:EU REACH restrictions on metal component leaching force stainless steel substitution with titanium alloys at 3-4x material cost.
Strategic Opportunities
- India's BIS certification pathway:Mandatory safety marking for electronic grooming devices creates first-mover advantage for compliant brands ahead of full enforcement.
- Telemedicine-dermatology convergence:Facial cleansing device manufacturers can integrate imaging sensors that feed remote skin diagnostic platforms.
- Right-to-repair mandates:EU and US state-level legislation is creating aftermarket service revenue pools for battery replacement and component refurbishment.
Industry Challenges
- Firmware-thermal integration complexity:Engineering teams must coordinate embedded software development with heating element physics in compressed release windows.
- Cross-border warranty fulfillment:Multi-country distribution requires localized service networks that strain working capital for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Care Appliances Market |
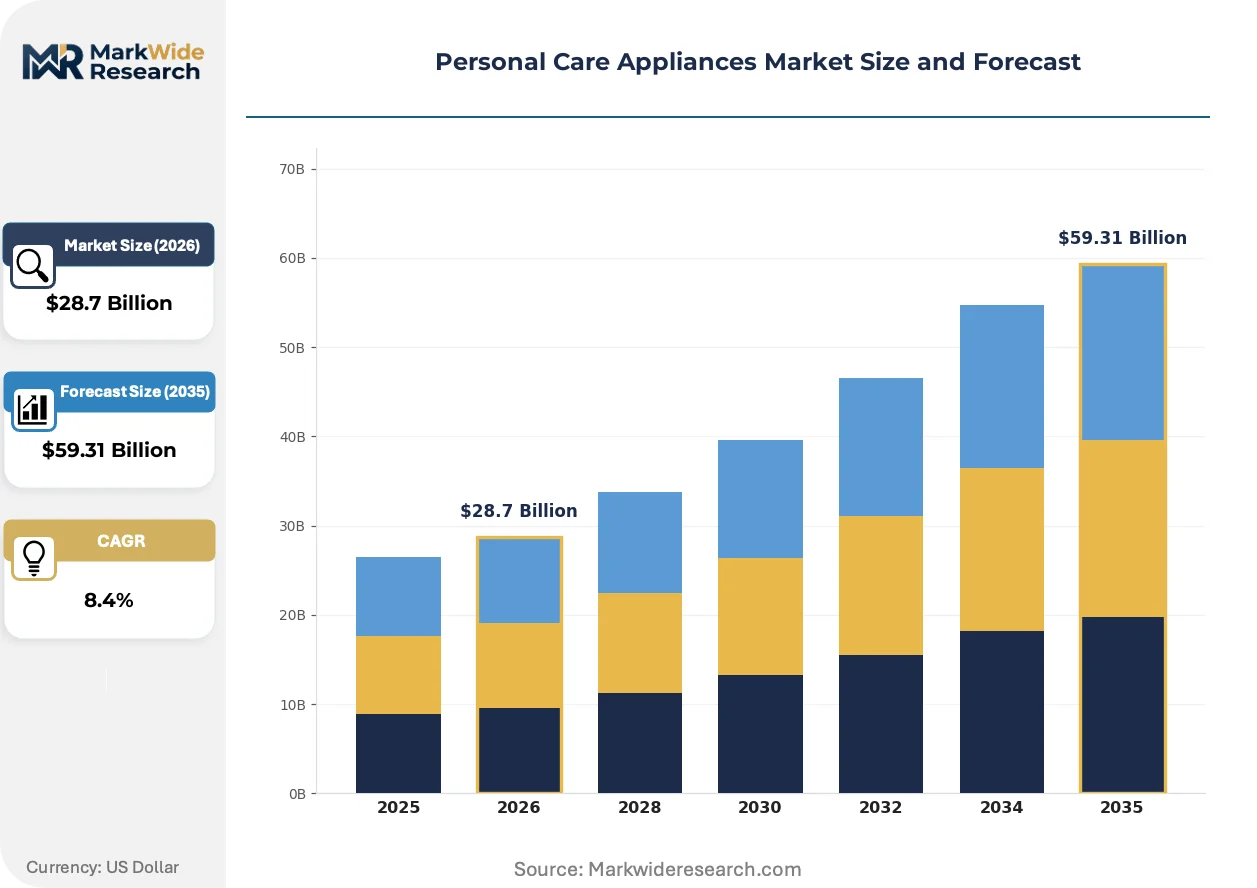
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dryers, Electric Shavers, Hair Straighteners, Facial Cleansing Devices End User: Men, Women, Teenagers, Seniors Technology: Cordless, Infrared, Ceramic, Ionic Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Pharmacies |
| Companies Covered | Koninklijke Philips N.V., Procter & Gamble Co., Panasonic Corporation, Conair Corporation, Dyson Limited, Spectrum Brands, Inc., Colgate-Palmolive Company, Wahl Clipper Corporation, Groupe SEB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Care Appliances Market Emerging Trajectories
Digital layer integration is splitting traditional hardware value chains as appliances become software-defined platforms requiring continuous firmware validation and cybersecurity maintenance.
Solid-state battery prototypes are rendering obsolete conventional cylindrical lithium-ion cell architectures in premium cordless trimmers and shavers. Japanese appliance divisions at Panasonic and domestic competitors are piloting silicon-anode designs that double energy density within identical form factors. This chemistry transition is rendering obsolete the established supply relationships with cylindrical cell suppliers that have dominated portable grooming for two decades.
EU Ecodesign Directive energy efficiency thresholds are forcing hair dryer manufacturers to abandon pure resistive heating in favor of heat pump or infrared emitter architectures. The 2027 compliance deadline compresses redesign timelines for products representing sixty percent of European category volume. Professional salon segments are responding fastest, as efficiency certification becomes a procurement filter for salon chain buyers in Germany and France.
Subscription-based blade replenishment programs are displacing traditional retail replacement purchases in male grooming categories. Dollar Shave Club and Philips have established direct-to-consumer auto-ship models that capture lifetime value through locked-in consumable revenue. This behavioral shift is most visible in the United States, where male grooming subscription penetration now exceeds twenty-five percent among urban millennials.
Personal Care Appliances Market Segmentation
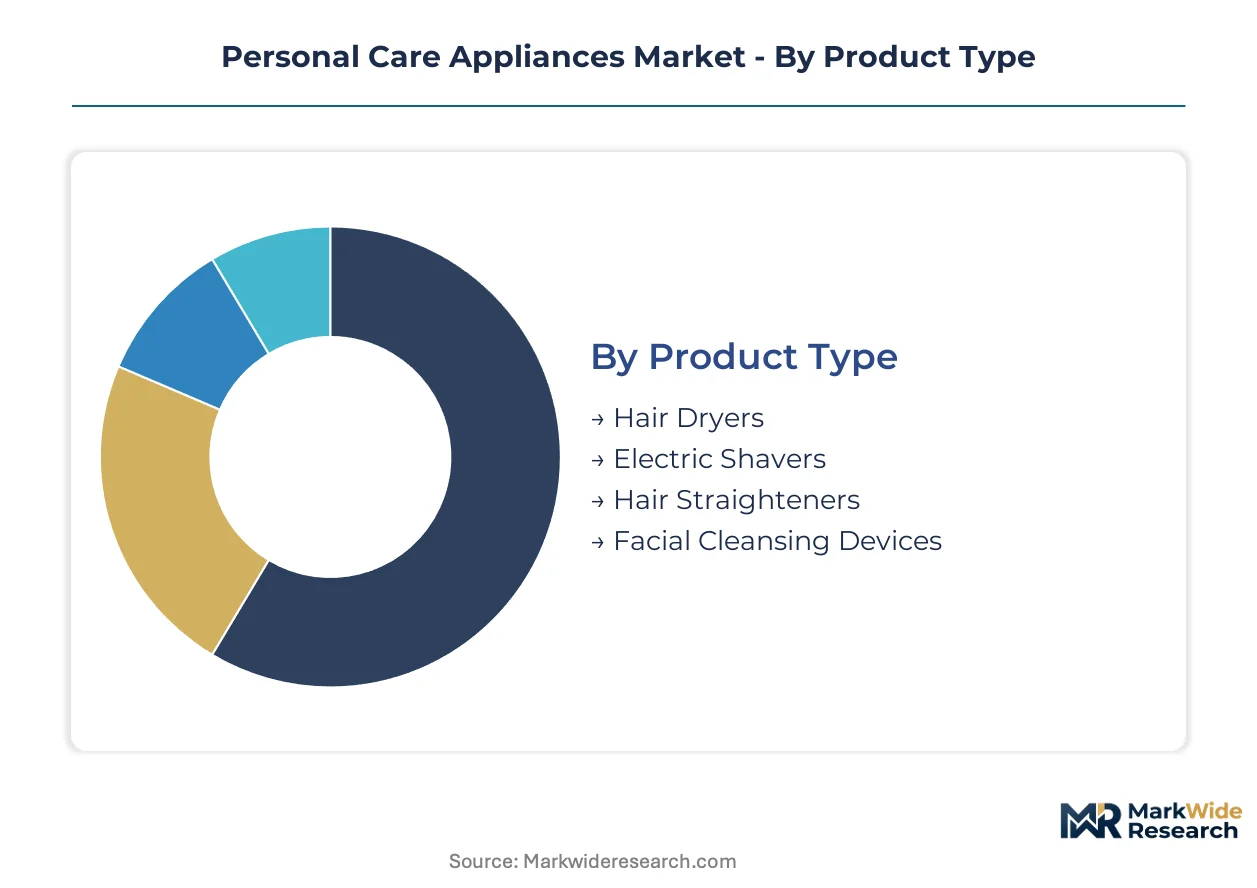
Personal care appliances fragment across four distinct classification axes where technical specifications, user demographics, and channel economics create divergent margin profiles. Each segmentation layer reveals how cordless architectures, professional salon procurement, and direct-to-consumer subscriptions are redistributing value capture across the value chain.
Product Type:
Hair dryers and electric shavers anchor manufacturing scale with predictable replacement cycles, while facial cleansing devices and advanced styling tools command premium positioning through dermatological endorsement and professional-grade specifications.
- Hair Dryers:These appliances incorporate heating elements rated between 1200W and 2200W with DC motors operating at 80,000–110,000 RPM. Demand concentrates among professional stylists in the United States where salon chain procurement now filters for EU Ecodesign Directive efficiency certification. Established volume favors hair dryers; emerging adoption favors facial cleansing devices.
- Electric Shavers:Cordless lithium-ion architectures dominate this segment where Panasonic leverages battery chemistry heritage to sustain technical leadership. Male grooming subscription programs in the United States now capture over twenty-five percent of blade replenishment revenue among urban millennials, locking in lifetime value through auto-ship models.
- Hair Straighteners:Ionic and ceramic technologies concentrate in professional-grade tiers where heat distribution uniformity justifies elevated price positioning.
- Facial Cleansing Devices:Ultrasonic transducers generating 6,000–8,000 vibrations per minute enable spa-at-home positioning with the steepest expansion trajectory across all product types.
Manufacturing scale and replacement predictability favor hair dryers and shavers; margin expansion and dermatological validation favor facial cleansing devices.
End User:
Demographic targeting shapes feature prioritization where runtime specifications, ergonomic design, and price sensitivity diverge sharply across gender and age cohorts.
- Men:Cordless shaving and grooming portfolios dominate male-oriented procurement where portability overrides raw power specifications. Subscription-based blade replenishment programs have displaced traditional retail replacement purchases through Dollar Shave Club and Philips direct-to-consumer auto-ship models.
- Women:Premium styling tool penetration deepens among female home users and professional stylists where AI-driven temperature modulation reduces heat damage claims. FDA oversight of laser and light-based devices creates twelve-to-eighteen month regulatory review periods that freeze launch schedules for hair removal appliances targeting this cohort.
- Teenagers:Entry-point pricing and social media-influenced brand discovery drive acquisition in this segment.
- Seniors:Ergonomic handle designs and simplified control interfaces address dexterity and vision considerations in product development.
Subscription retention economics favor men; professional salon upgrade cycles favor women.
Technology:
Power delivery architectures and thermal management systems differentiate performance tiers while regulatory compliance reshapes material selection and energy efficiency thresholds.
- Cordless:Lithium-ion battery technology is forcing manufacturers to reengineer thermal management systems around chemistry constraints rather than AC power assumptions. Solid-state battery prototypes at Panasonic and domestic Japanese competitors are piloting silicon-anode designs that double energy density within identical form factors.
- Infrared:EU Ecodesign Directive energy efficiency thresholds are forcing manufacturers to abandon pure resistive heating in favor of infrared emitter architectures ahead of the 2027 compliance deadline.
- Ceramic:Heat distribution uniformity in professional-grade segments justifies elevated price tiers through frizz reduction performance.
- Ionic:Frizz reduction technology concentrates in salon-grade specifications where professional stylists validate performance claims.
Regulatory compression favors infrared and cordless; professional validation favors ceramic and ionic.
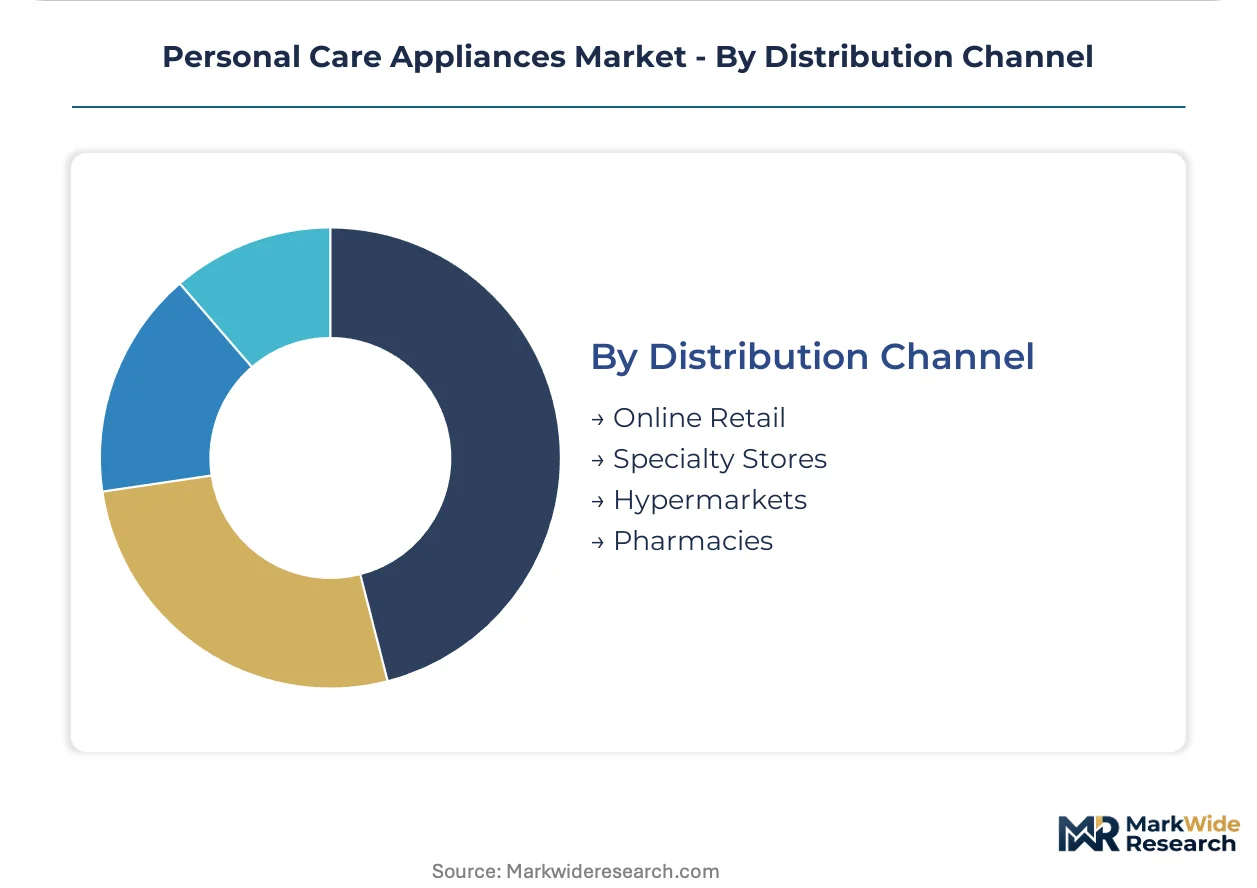
Distribution Channel:
Channel mix determines working capital intensity, warranty fulfillment complexity, and consumer data capture capabilities across fragmented retail architectures.
- Online Retail:Direct-to-consumer models enable subscription-based blade replenishment programs that capture lifetime value through locked-in consumable revenue. Cross-border warranty fulfillment requires localized service networks that strain working capital for mid-tier manufacturers.
- Specialty Stores:Professional salon supply chains in Germany and France now apply efficiency certification as a procurement filter, privileging compliant manufacturers with shelf placement.
- Hypermarkets:Volume-driven placement favors established hair dryer and electric shaver categories with predictable replacement cycles.
- Pharmacies:Dermatological endorsement drives facial cleansing device placement where clinical validation supports premium price positioning.
Data capture and subscription economics favor online retail; professional validation and efficiency certification favor specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics vary sharply across major personal care appliance markets, with manufacturing concentration in East Asia and premium consumption concentrated in Western economies. Trade flows reflect this asymmetry, with finished goods moving toward high-income consumer bases while components and raw materials flow toward production hubs.
United States
Professional salon operators in California and New York Metro are expanding cordless tool procurement as runtime specifications match corded benchmarks. FDA 510(k) clearance timelines for laser hair removal devices extend 12-18 months, freezing launch schedules for light-based appliances. Male grooming subscription penetration exceeds twenty-five percent among urban millennials, concentrating recurring revenue in direct-to-consumer channels.
Germany
EU Ecodesign Directive efficiency certification has become a mandatory procurement filter for salon chain buyers in Bavaria and North Rhine-Westphalia. Extended producer responsibility frameworks under the EU Green Deal are accelerating circular design investments among manufacturers targeting European distribution. Professional supply chains in Hamburg and Berlin privilege compliant brands with premium shelf placement.
Japan
Solid-state battery prototypes utilizing silicon-anode designs are emerging from appliance divisions in the Kanto region around Tokyo. METI standards for battery chemistry and energy efficiency shape domestic product architecture decisions. Osaka-based manufacturing clusters are piloting next-generation cordless architectures that double energy density within existing form factors.
China
Neodymium magnet processing capacity concentrated in Inner Mongolia's refining corridor anchors high-performance DC motor production for export markets. GB standards and MIIT regulations govern domestic appliance safety and electromagnetic compatibility. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta dominate global supply for heating elements and ultrasonic transducers.
India
Mandatory BIS certification for electronic grooming devices creates first-mover positioning for compliant brands ahead of full enforcement. CDSCO oversight applies to laser and light-based devices entering the medical-aesthetic crossover segment. Maharashtra and Karnataka industrial corridors are attracting contract manufacturing investments targeting domestic middle-class expansion and re-export to Middle Eastern markets.
Personal Care Appliances Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability clusters: integrated electronics conglomerates with battery chemistry heritage, specialized motor engineering houses with proprietary air flow architectures, and consumer goods multinationals with subscription platform infrastructure. Strategic archetypes include technology licensors monetizing patent portfolios, vertical integrators controlling rare earth magnet supply chains, and direct-to-consumer specialists capturing lifetime value through blade replenishment programs. Dominant competitive moves span strategic partnerships with dermatology clinics for clinical validation and geographic expansion through localized warranty fulfillment networks.
Within the integrated electronics tier, Koninklijke Philips N.V. and Panasonic Corporation exemplify archetypes built on battery chemistry heritage and thermal management systems. Dyson Limited occupies a position defined by in-house motor design capabilities. Among consumer goods conglomerates, Procter & Gamble Co. and Colgate-Palmolive Company represent scale-driven portfolios with established distribution density. Spectrum Brands, Inc. and Wahl Clipper Corporation sit within specialized grooming segments. Groupe SEB and Conair Corporation anchor mid-market positioning across multiple appliance categories.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Procter & Gamble Co. |
| Panasonic Corporation |
| Conair Corporation |
| Dyson Limited |
| Spectrum Brands, Inc. |
| Colgate-Palmolive Company |
| Wahl Clipper Corporation |
| Groupe SEB |
| Others |
Supply Flow & Price Mechanics
Inner Mongolia's rare earth refining corridor governs neodymium magnet availability for high-performance DC motors, translating upstream processing bottlenecks directly into pricing power for motor manufacturers serving cordless personal care appliances. Battery chemistry transitions and EU Ecodesign Directive compliance deadlines are compressing margin structures across heating element suppliers while professional salon buyers in Germany and France apply efficiency certification as a non-negotiable procurement filter.
Pricing Analysis
Next-generation solid-state battery architectures command 40-60% price premiums over conventional cylindrical lithium-ion cells in premium cordless trimmers and shavers. Three-tier pricing structure across premium, standard, and economy levels separates dermatologist-endorsed facial cleansing devices from mass-market hair dryers and entry-point grooming tools. Cost compression in mid-tier hair dryers is intensifying because EU Ecodesign Directive efficiency thresholds force abandonment of pure resistive heating ahead of the 2027 compliance deadline. Professional stylists demonstrate lowest price sensitivity where runtime specifications and thermal damage reduction justify elevated procurement budgets, while teenage entry-point segments prioritize social media-influenced brand discovery over technical performance metrics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for heating element and ultrasonic transducer sourcing. Manufacturing gravity centers on the Yangtze River Delta and Pearl River Delta for finished appliance assembly, South Korea and Japan for battery cell production, and Germany for precision motor components. Raw material dependencies span neodymium magnets, silicon-anode battery substrates, and titanium alloys substituting stainless steel under EU REACH nickel release restrictions. Single-source vulnerability concentrates in Inner Mongolia's rare earth processing capacity. Distribution runs through direct-to-consumer platforms capturing subscription blade replenishment revenue, specialty salon supply chains applying efficiency certification filters, and hypermarket channels serving replacement cycle predictability in established categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Personal care appliances are crossing into platform-economics territory as firmware-defined thermal systems and subscription-based consumable models restructure value capture around continuous customer relationships rather than discrete hardware transactions. Interoperability between facial cleansing devices and telemedicine-dermatology platforms illustrates this shift.
For Market Incumbents: Insulate premium positioning through proprietary sensor fusion architectures that lock in professional stylist loyalty via AI-driven temperature modulation systems. Secure captive supply of silicon-anode battery capacity through partnerships with Japanese cell manufacturers before solid-state chemistry transitions commoditize existing lithium-ion supplier relationships. Vertical integration into rare earth magnet sourcing mitigates Inner Mongolia processing concentration risk. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification pathway ahead of full enforcement, leveraging mandatory safety marking requirements to capture first-mover positioning in a market where domestic middle-class expansion outpaces organized retail penetration. Target facial cleansing device segments where dermatological endorsement barriers remain lower than laser hair removal's FDA 510(k) clearance timelines. Deploy telemedicine-dermatology convergence as a go-to-market angle integrating imaging sensors with remote diagnostic platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors battery chemistry specialists with solid-state prototyping capabilities and direct-to-consumer subscription infrastructure owners capturing lifetime value through locked-in consumable revenue. Long-term viability over the next decade rests on firmware-thermal integration competencies and circular design investments satisfying EU Green Deal extended producer responsibility mandates. Monitor right-to-repair legislation progression across EU member states and US jurisdictions as an inflection indicator for aftermarket service revenue pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Integration | Silicon-anode designs from Panasonic and domestic Japanese competitors double energy density within existing form factors. |
| Direct-to-Consumer Subscription Launch | Auto-ship blade replenishment models capture over twenty-five percent of male grooming revenue among urban millennials. |
| EU Ecodesign Certification Investment | Efficiency certification has become mandatory procurement filter for salon chain buyers in Germany and France. |
| Telemedicine Platform Partnership | Facial cleansing device manufacturers integrate imaging sensors feeding remote skin diagnostic platforms. |
| Right-to-Repair Service Network Buildout | EU and US state-level legislation creates aftermarket revenue pools for battery replacement and component refurbishment. |
Methodological Framework
Operator-level perspectives from professional salon owners, cordless product engineering leads, dermatology clinic procurement managers, and retail category buyers anchored the qualitative base for this analysis. Primary interview data combined with secondary validation against SEC filings from appliance manufacturers, EU Ecodesign Directive compliance databases, FDA 510(k) clearance records, and BIS certification registries. Bottom-up triangulation across product-level bill-of-materials analysis and top-down reconciliation against trade flow data established volume and value estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing for battery chemistry transition timelines and regulatory enforcement intensity. Segmentation dimensions modeled include product type, end-user demographic, power delivery architecture, and distribution channel structure. CAGRs derived from fitted growth curves applied to replacement cycle data and professional salon procurement expansion rates. Industry-specific forecast inputs encompassed cordless runtime specification benchmarks and EU Green Deal circular design investment trajectories.
Stress conditions across neodymium magnet supply disruptions, FDA clearance timeline extensions, and EU REACH nickel release compliance cost escalations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding solid-state battery commercialization schedules and right-to-repair legislative adoption patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Global Massage Chairs Market
Appliances
Household Vacuum Cleaners Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
North America Washing Machine Market
Appliances
Gas Ranges Market
Appliances
China Induction Hobs Market
Appliances
Laundry Kiosk Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Europe Induction Hobs Market
Appliances
India Washing Machine Market
Appliances
Germany Consumer Appliances Market
Appliances
Europe Microwave Oven Market
Appliances
Water Heater Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Laundry Appliances Market