
 Saudi Arabia Dishwasher Market | 2026-2036
Saudi Arabia Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Dishwasher Market Analytics
Modular rack configurations and flexible interior layouts is hardening as the dominant product-configuration pattern reshaping buyer choice in the Saudi Arabia dishwasher market. LG Electronics leverages its smart-home ecosystem to anchor premium positioning across Riyadh retail channels. Samsung Electronics competes through connected-kitchen integration that extends its appliance interoperability strategy. Bosch specializes in water-efficient engineering that sustains its appeal under tightening Saudi regulatory standards.
A dishwasher is an electromechanical appliance that sprays heated water mixed with detergent across dishware loaded on tiered racks, using wash cycles typically ranging from 45 to 90 minutes with water temperatures between 55°C and 75°C, designed to automate warewashing in residential kitchens and commercial food-service operations. Built-in models dominate Saudi residential installations where permanent kitchen fit-outs align with modern villa and apartment designs. Smart Technology variants represent the fastest-expanding technology segment as Wi-Fi-enabled units gain traction among tech-forward consumers in Jeddah and Khobar. The Commercial end-user category commands higher per-unit pricing and stronger replacement cycles compared to the Residential base.
SFDA oversees product safety compliance for electrical appliances entering the Kingdom, while SASO mandates energy-efficiency labelling that directly shapes import eligibility and consumer-facing product differentiation. The Saudi Building Code introduces water-usage thresholds for kitchen appliances in new construction, pushing developers toward certified efficient models. Stakeholders must monitor how upcoming SASO standard revisions treat connected-appliance cybersecurity and data privacy requirements before committing to smart-platform roadmaps.
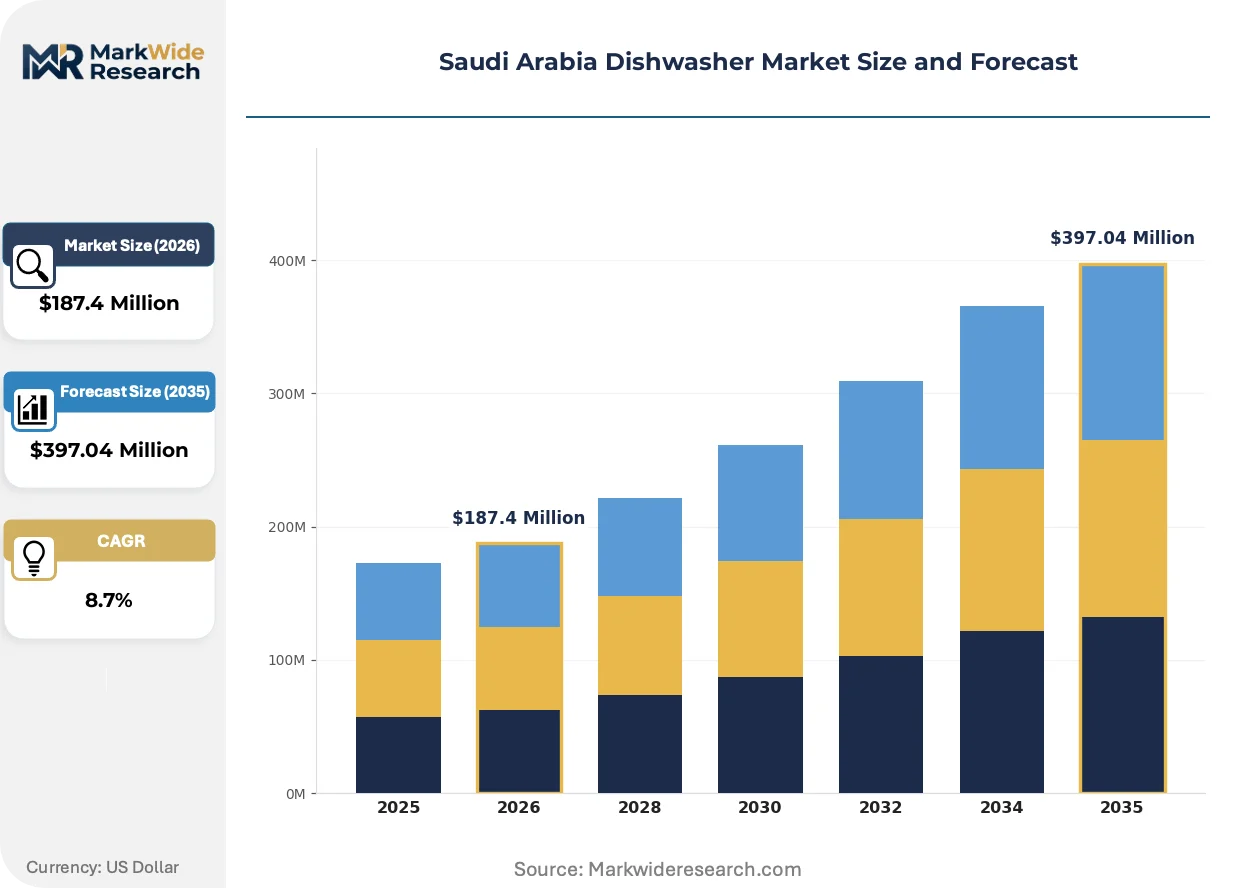
Market Dynamics
SASO energy-labelling mandates and SFDA safety protocols are compressing import eligibility windows while hospitality operators in Riyadh and Jeddah accelerate commercial kitchen upgrades. Water-efficiency thresholds now function as de facto market entry gates for foreign manufacturers.
Growth Catalysts
- SASO Energy Labelling:Mandatory efficiency tiers redirect procurement toward certified models, expanding addressable volume for compliant suppliers.
- Hospitality Expansion:Food-service operators in Riyadh and Jeddah are scaling warewashing capacity to match rising tourism and F&B standards.
- Smart Connectivity:Wi-Fi-enabled dishwashers are capturing tech-forward residential buyers in Khobar and Dammam.
Market Restraints
- Import Compliance Friction:SFDA electrical-safety certification timelines extend product launch cycles by 4-8 months.
- Water Scarcity Economics:Desalination-dependent utilities elevate operating costs for water-intensive commercial units.
- Residential Price Sensitivity:Mid-income villa buyers in secondary cities defer purchases when financing costs tighten.
Strategic Opportunities
- Eastern Province Penetration:Dammam and Khobar residential construction trails Riyadh saturation, offering first-mover positioning.
- Commercial Leasing Models:Hospitality operators prefer operational-expense structures over capital-heavy equipment purchases.
- Saudi Building Code Alignment:New construction mandates for water-efficient appliances create specification-driven demand.
Industry Challenges
- Cybersecurity Certification Gaps:Connected-appliance data protocols lack clear SFDA guidance, delaying smart-product roadmaps.
- Service Network Density:Sparse authorized technician coverage outside Riyadh, Jeddah, and Dammam extends repair lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Dishwasher Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Portable, Compact, Drawer End User: Residential, Commercial, Hospitality, Institutional Technology: Smart Technology, Energy Efficient, Standard, Traditional Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Toshiba, Electrolux, LG Electronics, Samsung Electronics, Arçelik, Bosch, Midea, Haier, Whirlpool, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Dishwasher Market Evolving Landscape
Modular interior configurations and connected-kitchen ecosystems are displacing fixed-rack legacy designs. Manufacturers now compete on software integration and water-recovery engineering rather than mechanical wash performance alone.
Heat-pump drying technology is electrifying residential energy profiles by cutting per-cycle consumption versus conventional resistive heating. Premium villa buyers in Riyadh are specifying these units at accelerating rates. The shift is compressing demand for standard vented models and rewiring supplier R&D priorities toward thermal-efficiency engineering.
SASO's pending revision to energy-labelling protocols will tighten water-consumption thresholds for import eligibility. Appliance distributors are pre-qualifying next-generation models to avoid stock obsolescence. Commercial hospitality procurement teams are front-loading purchases ahead of implementation deadlines.
Direct-to-developer specification contracts are bypassing traditional retail channels for new residential towers. Kitchen-package bundling now locks dishwasher selection at construction phase rather than consumer point-of-sale. This pattern concentrates volume with project-specification teams in Riyadh's Central Region development pipeline.
Saudi Arabia Dishwasher Market Segmentation
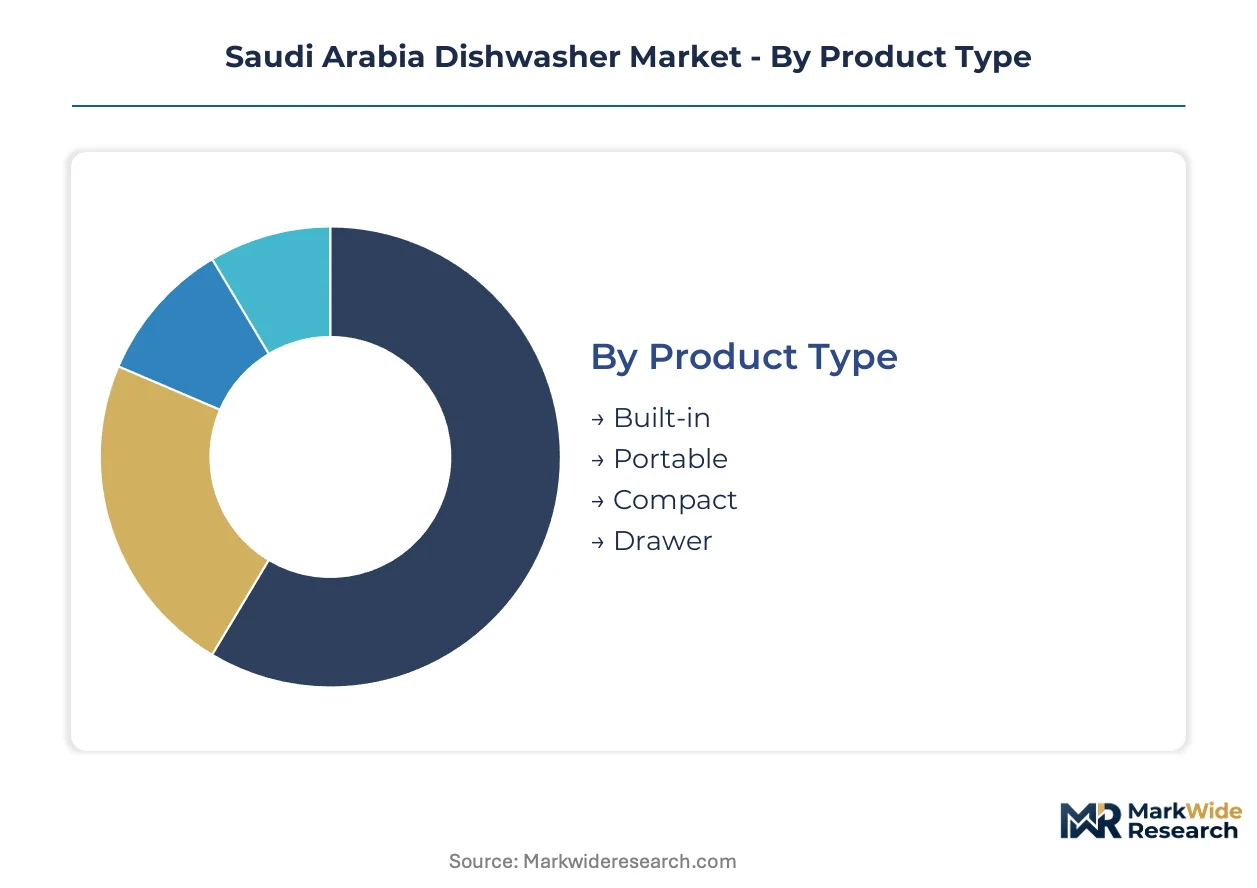
Saudi Arabia's dishwasher market segments along four distinct axes that shape procurement patterns across Riyadh's villa developments and Jeddah's hospitality clusters. Each category reflects divergent technical requirements, regulatory compliance thresholds, and buyer decision hierarchies that manufacturers must navigate.
Product Type:
Built-in models dominate permanent kitchen installations where Saudi villa architecture demands seamless appliance integration.
- Built-in:These units install directly into cabinetry with standardized dimensions matching Saudi kitchen module specifications. Riyadh's Central Region residential pipeline specifies built-in configurations for 80% of new villa developments, driven by developer preference for cohesive interior aesthetics.
- Portable:Freestanding units with caster mobility and temporary water connections serve rental apartments and secondary residences. Demand concentrates among expatriate professionals in Khobar's corporate housing compounds where lease terms discourage permanent modifications.
- Compact:Countertop or narrow-profile designs accommodate space-constrained kitchens in older Jeddah apartment stock. These units appeal to single-person households and domestic worker quarters.
- Drawer:Dual-chamber or single-drawer configurations enable simultaneous wash cycles with reduced water volumes. Premium villa buyers in Riyadh's northern districts specify these for secondary kitchen installations and entertainment prep areas.
Built-in leads on scale; Drawer leads on momentum.
End User:
Commercial deployment patterns diverge sharply from residential procurement cycles across Saudi Arabia's three major urban corridors.
- Residential:Villa and apartment owners purchase through retail channels or developer package deals. Riyadh's construction pipeline locks dishwasher selection at building phase, compressing point-of-sale decision windows.
- Commercial:Independent restaurants and catering operations prioritize throughput capacity and rapid cycle times. Jeddah's Red Sea tourism corridor drives replacement demand as F&B standards tighten.
- Hospitality:Hotel chains and resort operators in Riyadh and Jeddah specify industrial-grade units with 3-5 year replacement cycles. Procurement teams front-load purchases ahead of SASO energy-labelling deadline implementations.
- Institutional:Hospital cafeterias, university dining halls, and government facilities require NSF-equivalent sanitation certification. SFDA oversight extends to these installations through food-service safety protocols.
Hospitality leads on scale; Residential leads on momentum.
Technology:
Regulatory pressure and utility economics are rewiring R&D priorities toward thermal efficiency and connectivity.
- Smart Technology:Wi-Fi-enabled units with app-based cycle programming and consumption monitoring. Tech-forward buyers in Dammam and Khobar adopt these for integration with broader smart-home ecosystems.
- Energy Efficient:Heat-pump drying and optimized spray-arm engineering reduce per-cycle electricity draw. SASO labelling mandates make these de facto market entry requirements for import eligibility.
- Standard:Conventional resistive heating and mechanical controls without connectivity features. Price-sensitive segments in secondary cities select these for basic functionality.
- Traditional:Basic wash systems with minimal electronic components and limited cycle options. Remaining demand concentrates in budget hospitality retrofits and worker accommodation facilities.
Energy Efficient leads on scale; Smart Technology leads on momentum.
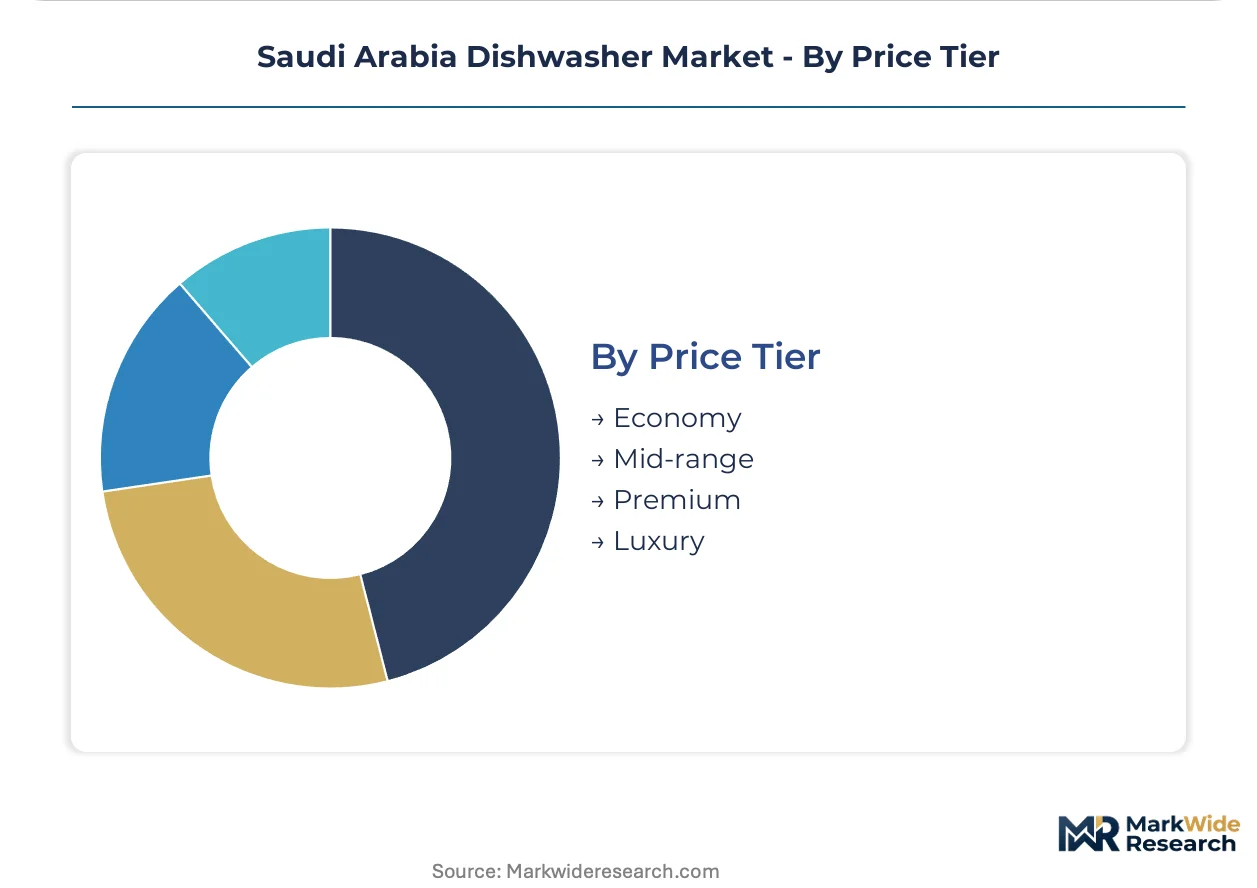
Price Tier:
Financing conditions and construction cost pressures stratify buyer access across Saudi Arabia's income distribution.
- Economy:Entry-level units with plastic interiors and basic wash programs. Domestic worker quarters and rental property investors in Dammam select these for minimal capital outlay.
- Mid-range:Stainless-steel construction with 5-7 cycle options and partial energy efficiency certification. Riyadh's mid-income villa developments specify these in bulk procurement contracts.
- Premium:Advanced drying systems, quiet operation below 45 decibels, and extended warranty coverage. Jeddah's upscale residential towers and boutique hotels favor these for differentiation.
- Luxury:Fully integrated panel-ready designs with custom finish options and connected-kitchen compatibility. Ultra-high-net-worth buyers in Riyadh's Diplomatic Quarter and Khobar's waterfront districts specify these at accelerating rates.
Mid-range leads on scale; Luxury leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saudi dishwasher industry traces its modern procurement foundations to Riyadh's post-2000 residential construction boom, when developer-driven kitchen specifications first systematized built-in appliance demand across the Central Region.
Riyadh
Riyadh's villa construction pipeline and hospitality upgrades drive the bulk of national procurement volume. SASO energy-labelling mandates redirect developer specifications toward certified efficient models. The northern districts and Diplomatic Quarter concentrate luxury-tier demand among ultra-high-net-worth buyers.
Eastern Province
Dammam and Khobar residential construction trails Riyadh saturation, creating first-mover positioning for suppliers targeting tech-forward buyers. Smart Technology variants gain traction among expatriate professionals in corporate housing compounds. The Khobar waterfront districts anchor accelerating luxury specification rates.
Western Region
Jeddah's Red Sea tourism corridor propels commercial kitchen replacements as F&B standards tighten. SFDA food-service safety protocols extend to hospitality procurement teams front-loading purchases ahead of regulatory deadlines. The city's upscale residential towers favor premium-tier differentiation.
NEOM Northwest
The giga-project's smart-city infrastructure embeds connected-kitchen specifications at master-planning stage. Saudi Building Code water-efficiency thresholds shape appliance selection for sustainable construction mandates. Developer-package bundling locks dishwasher procurement during early-phase construction rather than consumer point-of-sale.
Saudi Arabia Dishwasher Market Competitive Landscape
The competitive structure tilts toward diversified appliance conglomerates with cross-category smart-home ecosystems. Korean and European manufacturers anchor premium positioning through connectivity integration and water-efficiency engineering. Three archetypes dominate: ecosystem-integrated technology leaders, regulatory-compliance specialists, and scale-driven volume suppliers. Capacity expansion and strategic partnerships with Saudi distributors constitute the dominant competitive moves.
Among Korean electronics conglomerates, LG Electronics and Samsung Electronics exemplify ecosystem-integrated positioning through smart-home platform anchoring. European specialist Bosch occupies a position emphasizing engineering-driven water efficiency aligned with tightening SASO thresholds. Chinese volume supplier Midea represents scale-driven market penetration across mid-range residential segments.
| Leading Market Players |
|---|
| Toshiba |
| Electrolux |
| LG Electronics |
| Samsung Electronics |
| Arçelik |
| Bosch |
| Midea |
| Haier |
| Whirlpool |
| Others |
Value Network & Pricing Analysis
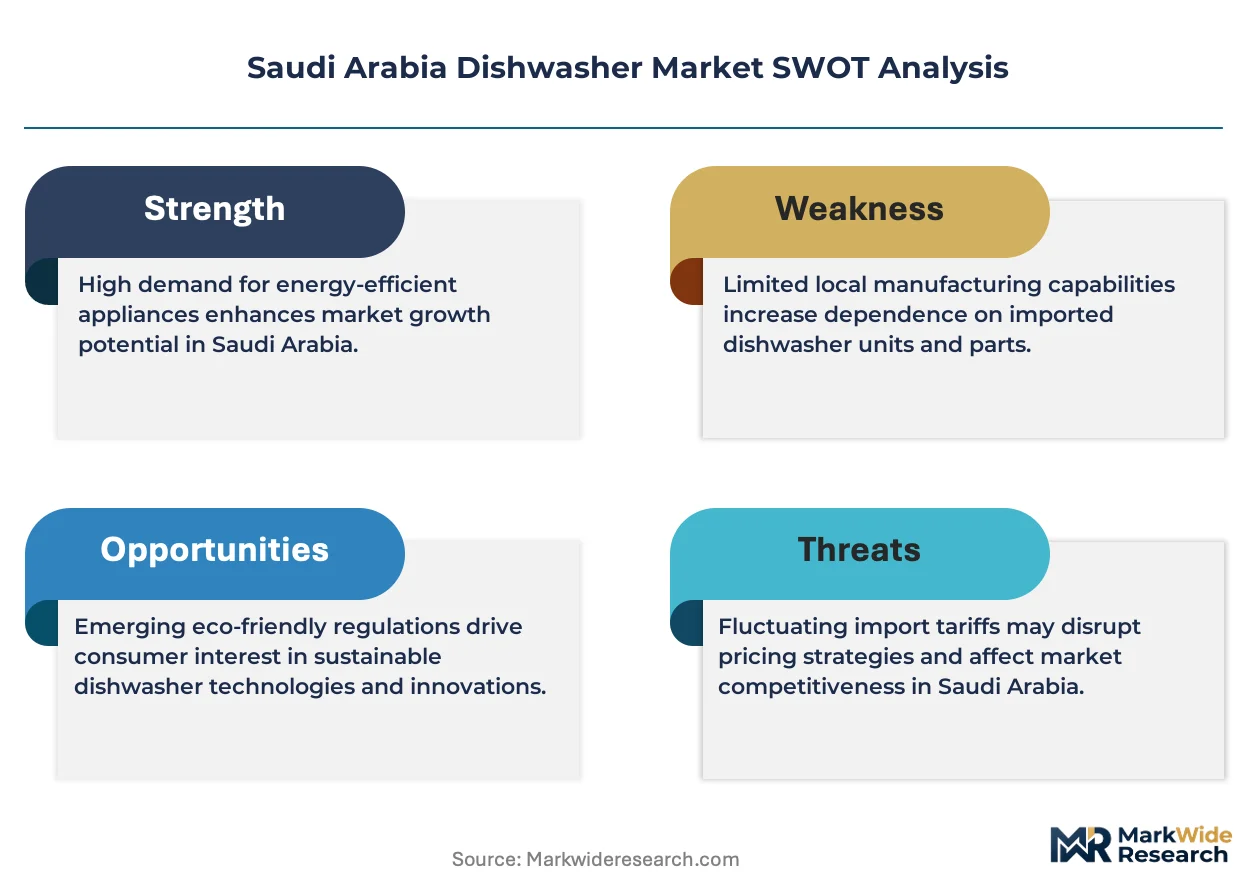
SASO water-efficiency mandates gate qualified supply and premium-tier pricing access by restricting import eligibility to certified models while elevating compliant product positioning. Manufacturers absorb certification costs into landed pricing, compressing margin buffers for uncertified competitors and concentrating pricing power with established suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyer access by certification grade and after-sales service bundling. Price differentiation hinges on SASO energy-label tier and smart-connectivity integration, with premium units commanding substantial markups for connected-kitchen compatibility. Cost compression in the economy tier is intensifying because Chinese volume suppliers are flooding mid-range residential channels. Budget-conscious villa developers in secondary cities exhibit highest price sensitivity, while ultra-high-net-worth buyers in Riyadh's Diplomatic Quarter show minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Jeddah and Dammam anchor hub-and-spoke patterns radiating into secondary cities with sparse technician coverage. Manufacturing concentrates in China, South Korea, and Turkey, with Turkish suppliers gaining share through shorter shipping lanes to Red Sea ports. Stainless steel interiors and heat-pump drying modules draw from specialized component ecosystems in Germany and Japan. Single-source vulnerability around heat-pump compressors threatens supply continuity for premium-tier SKUs. Distribution runs through authorized dealer networks that double as service franchises, locking out pure-play e-commerce challengers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's dishwasher market offers geographic-arbitrage positioning against European markets where energy-labelling thresholds already exceed current SASO tiers, allowing pre-certified inventory redirection.
For Market Incumbents: To counter Midea's volume-driven penetration in mid-range residential segments, LG Electronics and Samsung Electronics should deepen backward integration into heat-pump compressor supply and expand Riyadh-based specification teams to lock developer-package contracts before construction phase. Certification investment in upcoming SASO cybersecurity protocols represents the priority defensive lever. For New Entrants and Emerging Players: The premium-economy price-point gap in smart-enabled compact dishwashers creates entry space for specialized European brands targeting Khobar's expatriate corporate housing compounds. Eastern Province residential construction trails Riyadh saturation, offering first-mover positioning with tech-forward positioning. Direct-to-developer specification bypassing retail channels provides the optimal go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Turkish manufacturers with existing SASO certification because regulatory compliance barriers protect acquired market share from de novo entrants. Platform consolidation across 3-5 certified suppliers captures pricing power in a market where import eligibility windows are compressing. Watch for SASO's pending cybersecurity standard revision as the signal indicating which smart-platform investments will retain compliance value.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Localization | Domestic assembly of drying modules reduces exposure to German-Japanese component bottlenecks. |
| Developer-Package Specification Lock | Kitchen bundling at Riyadh construction phase captures volume before retail competition activates. |
| SASO Cybersecurity Pre-Certification | Early alignment with pending data-privacy protocols secures smart-product roadmap continuity. |
| Eastern Province Distribution Expansion | Dammam and Khobar hub establishment captures tech-forward buyer segments ahead of saturation. |
| Commercial Leasing Model Pilot | Operational-expense structures match hospitality operator preference over capital-heavy purchases. |
Research Methodology
Bottom-up residential and commercial procurement modeling reconciled against top-down import shipment tracking forms the analytical core of this study. Primary interviews with appliance distributor executives, SFDA regulatory affairs specialists, hospitality procurement directors, and Riyadh developer specification teams combined with secondary validation from SASO energy-labelling databases, Saudi Customs import records, and construction permit filings. Triangulation across these sources ensures volume estimates align with actual supply-side flows.
Input-output matrices map dishwasher unit shipments against housing completion data, hospitality room inventory, and commercial kitchen permits across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology tier, and price positioning, with regional splits across Central Region, Eastern Province, Western Region, and NEOM Northwest. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory implementation schedules and construction pipeline visibility. Water-efficiency threshold tightening and smart-connectivity adoption velocity constitute key forecast inputs.
Caveats apply where SASO standard revision timing or NEOM construction delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Qatar Microwave Ovens Market
Appliances
Glass Ceramic Cooktop Market
Appliances
Hair Removal Appliances Market
Appliances
US Portable Washing Machines Market
Appliances
US Washing Machine Parts Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Portable Fridges Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Global Vended Laundry Equipment Market
Appliances
North America Personal Care Appliances Market
Appliances
Household Vacuum Cleaners Market
Appliances
Microwave Market
Appliances
GCC Microwave Oven Market
Appliances
Refrigerator Door Seal Market
Appliances
China Induction Hobs Market