
 Small Appliances Market | 2026-2036
Small Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Small Appliances Market Outlook
Young renters and single-person households is collapsing the traditional family-home buyer archetype that long dominated small appliance purchasing. Groupe SEB leverages its European manufacturing heritage to command premium positioning in coffee preparation equipment. Midea Group anchors global volume through integrated production campuses in Guangdong and Hebei provinces. Haier Smart Home extends its IoT ecosystem strategy by embedding connectivity modules across countertop appliance lines.
Small appliances encompass electrically powered domestic equipment typically operating below fixed installation thresholds, with power ratings generally spanning 50 to 2,000 watts and designed for portable or semi-portable deployment across food preparation, beverage brewing, and climate comfort functions. Cooking appliances incorporate heating elements with precise thermostatic control, while food preparation devices utilize sealed motors and stainless-steel blade assemblies to process raw ingredients. Coffee makers lead product type margins due to recurring consumables attachment and brand loyalty premiums, whereas online retail channels capture the fastest-growing transaction volume as platform logistics penetrate secondary cities. Household end users dominate unit shipments, though restaurant and cafe segments generate disproportionate replacement revenue through commercial-duty specifications.
The EU Ecodesign Directive and REACH chemical compliance framework impose material restrictions and energy-labeling requirements that reshape product development cycles for manufacturers exporting into Europe. The US DOE appliance standards program and FCC electromagnetic emissions rules add parallel certification layers for North American market access. China's GB standards and MIIT energy-efficiency classifications create a third regulatory perimeter that domestic champions navigate with lower compliance friction. Stakeholders must monitor divergence between regional efficiency test protocols, as misaligned measurement methodologies threaten to fragment production platforms and inflate SKU complexity without corresponding price realization.
Market Dynamics
Energy-efficiency mandates from the EU Ecodesign Directive and parallel frameworks in North America are compressing product development cycles while fragmenting certification requirements across export destinations.
Growth Catalysts
- Urban household densification:Asia-Pacific apartment dwellers demand multi-functional countertop devices that replace single-purpose units, accelerating replacement frequency in China, India, and Indonesia.
- REACH chemical compliance:European material restrictions are forcing redesigns that eliminate hazardous substances, creating competitive separation between compliant and non-compliant suppliers.
- Induction heating modules:The technology is penetrating mid-market cooking appliances as coil costs decline and precision control algorithms mature.
Market Restraints
- Copper and rare-earth magnet volatility:Motor assemblies depend on concentrated supply from Chinese processing facilities, exposing margin structures to input price swings.
- Test protocol divergence:Misaligned energy-efficiency measurement methodologies between EU, US, and Chinese regulators inflate SKU complexity without corresponding price realization.
- Manual brewing resurgence:Specialty coffee culture is displacing automated pod systems among enthusiast segments in Western European and North American urban centers.
Strategic Opportunities
- Vietnam and Philippines penetration:Underdeveloped small-appliance ownership rates in Southeast Asian secondary cities offer first-mover positioning before local manufacturing scales.
- IoT ecosystem convergence:Voice-assistant integration and app-based recipe programming are creating attach-rate opportunities for subscription services and consumables.
- US DOE appliance standards:Tightening federal efficiency thresholds will disqualify legacy import portfolios, opening shelf space for compliant domestic and near-shored production.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for connected modules competes with automotive and industrial automation for constrained talent pools.
- Multi-jurisdiction certification timelines:Parallel FCC, CE, and GB standard testing extends product launch windows by 8-14 months.
- Legacy platform integration:Established manufacturers face technical debt in retrofitting connectivity into mechanical-first product architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Appliances Market |
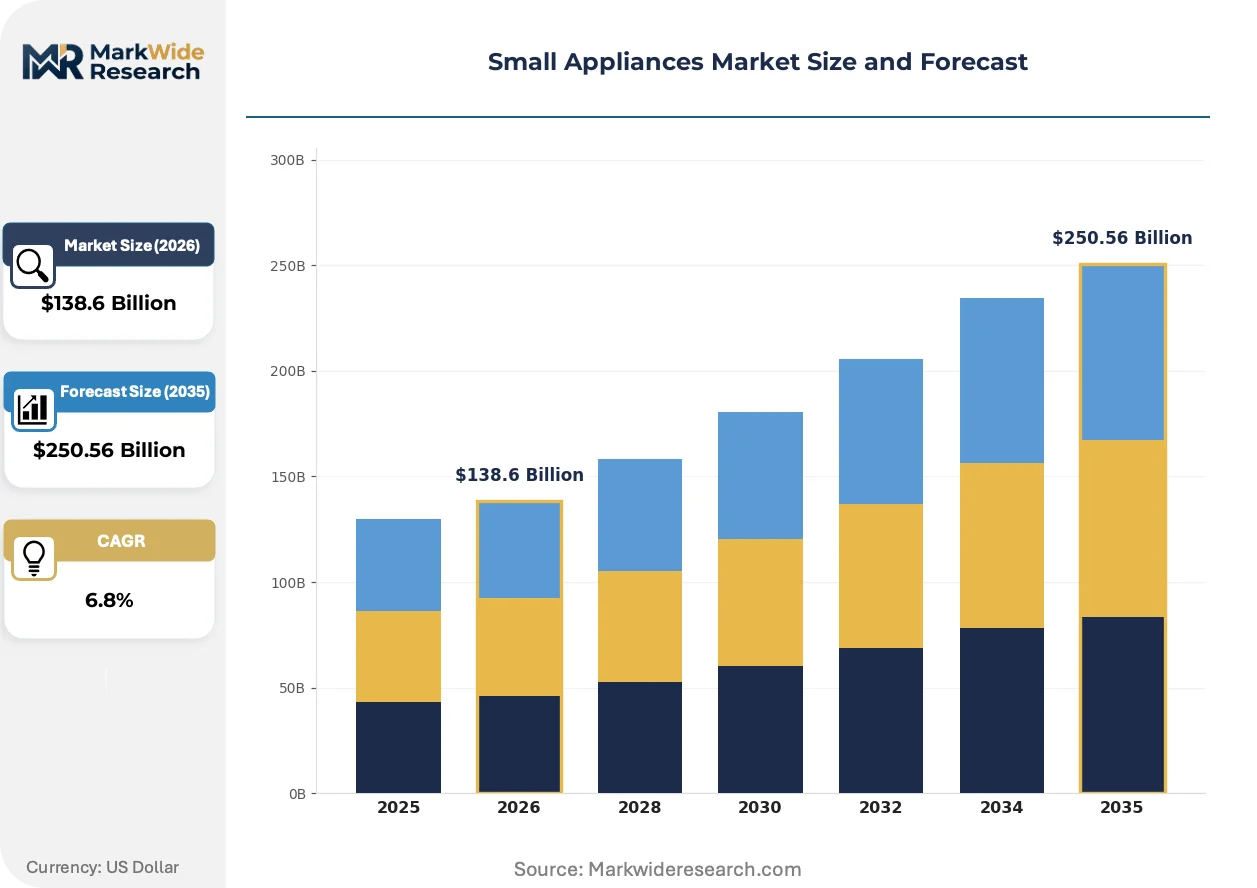
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Toasters, Coffee Makers, Blenders End User: Households, Restaurants, Cafes, Bakeries Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales Application: Cooking, Food Preparation, Beverage Brewing, Food Storage |
| Companies Covered | Haier Smart Home, Panasonic Corporation, Koninklijke Philips, Samsung Electronics, Whirlpool Corporation, Groupe SEB, LG Electronics, Electrolux Group, Midea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Appliances Market Strategic Shifts
Solid-state power electronics and connected intelligence are redefining performance benchmarks while regulatory fragmentation forces modular platform architectures.
Gallium nitride (GaN) semiconductors are replacing silicon-based power management in premium heating and motor control circuits. Appliance engineers at tier-one manufacturers are adopting GaN inverters for induction cooktops and high-speed blenders. The technology is miniaturizing thermal management systems, enabling slimmer form factors that penetrate premium kitchen renovations.
China's MIIT energy-efficiency classifications and GB standards are tightening domestic market access requirements ahead of export parity. Manufacturers serving both domestic and European markets face diverging test protocols that complicate platform standardization. Coffee preparation equipment with standby power optimization is absorbing disproportionate engineering resources to satisfy dual compliance.
Direct-to-consumer subscription models are displacing traditional retail replenishment for consumable-dependent categories. Coffee pod and filtration cartridge brands are building captive customer relationships through auto-ship programs. This pattern concentrates in North American and Western European urban markets where platform logistics penetrate last-mile delivery networks.
Small Appliances Market Segmentation
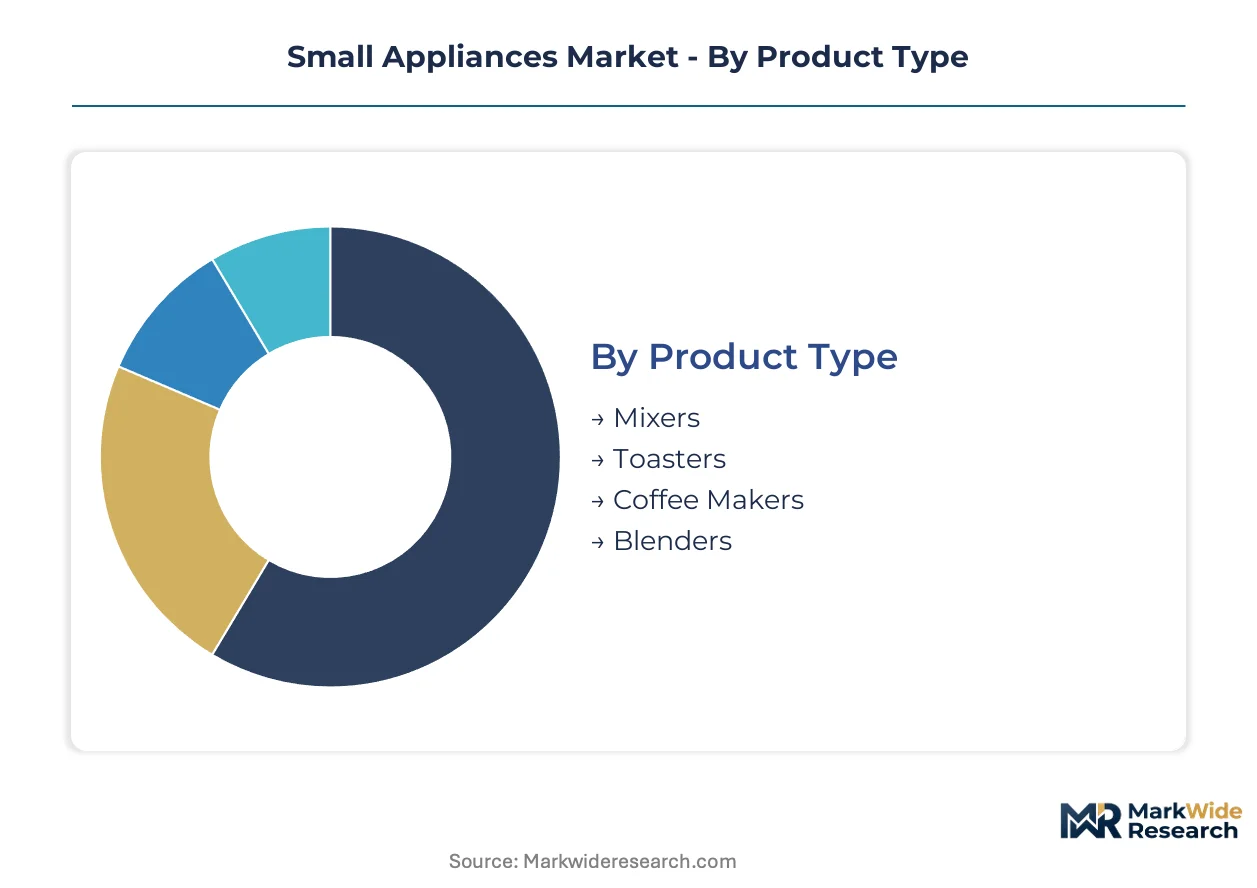
Segmentation in small appliances reveals how substitution pressures reshape category economics. Multi-functional devices cannibalize single-purpose units as urban density rises, forcing manufacturers to defend position through feature integration rather than standalone volume.
Product Type:
Substitution pressure runs strongest through countertop categories where single-function units face displacement by multi-purpose alternatives.
- Coffee Makers:Heating elements with precise thermostatic control and pump-driven pressure systems define espresso and drip configurations. Demand clusters in German and Italian households where beverage preparation rituals sustain premium pricing, though pod system saturation in North American metros constrains expansion.
- Blenders:Sealed motors paired with stainless-steel blade assemblies process raw ingredients through variable speed control. Chinese and Indian urban households drive volume as fresh ingredient consumption rises, with commercial-grade specifications penetrating Southeast Asian juice bar chains.
- Mixers:Planetary gear systems enable dough kneading and emulsification through controlled torque delivery. Stand configurations dominate North American baking culture while handheld variants penetrate Asian apartment kitchens.
- Toasters:Quartz heating elements with timing circuits brown bread surfaces through radiant heat transfer. Replacement demand concentrates in European markets where breakfast preparation maintains traditional appliance deployment.
Coffee makers retain volume leadership; blenders hold the steepest expansion curve.
End User:
Cost tier stratification separates specification requirements across customer types, with commercial duty premiums reshaping manufacturer portfolio priorities.
- Households:Portable configurations with 50-2,000 watt ratings serve food preparation and climate comfort functions across residential deployments. Chinese and Indian middle-class replacement cycles accelerate as appliance ownership penetrates secondary cities.
- Restaurants:Commercial-duty specifications with reinforced motor housings and continuous-duty cycles withstand intensive daily operation. Certification to NSF standards and local food safety codes creates procurement friction for import-dependent operators.
- Cafes:Beverage-focused equipment with rapid recovery heating systems supports high-throughput espresso and alternative milk preparation. Specialty coffee culture in Melbourne and Portland sustains equipment upgrade frequency.
- Bakeries:High-torque mixing platforms with stainless-steel bowls process commercial flour volumes through planetary action. European artisan bakery revival drives demand for heritage-brand equipment with extended warranty terms.
Households dominate unit shipments; cafes command the highest replacement revenue intensity.
Distribution Channel:
Geography of logistics penetration determines channel viability, with platform infrastructure reshaping last-mile economics for bulky appliance categories.
- Online Retail:Platform logistics networks enable penetration of secondary cities previously served only by informal retail. Amazon and regional marketplace infrastructure in Indonesia and Vietnam reshape replacement purchase patterns.
- Specialty Stores:Assisted selling environments with demonstration capabilities support premium positioning for coffee preparation and cooking equipment. European kitchen design studios and Asian appliance malls sustain this channel against digital displacement.
- Hypermarkets:Mass-market volume concentration through price-promotional calendars and seasonal display placement. Walmart and Carrefour networks in Brazil and Mexico capture mid-market replacement demand.
- Direct Sales:Manufacturer-controlled channels bypass retail margin extraction for connected appliance ecosystems with subscription attach opportunities. Dyson and established European brands deploy this model for premium climate comfort devices.
Hypermarkets retain volume leadership; online retail gains share fastest through logistics penetration.
Application:
Margin structure varies by application maturity, with consumable attachment rates determining lifetime customer value capture.
- Beverage Brewing:Pump and heating systems with pressure profiling enable espresso extraction and controlled water temperature for tea preparation. Recurring consumables attachment in pod and filtration categories sustains manufacturer margin structures.
- Cooking:Induction coil and resistive heating elements with precision thermostatic control support countertop food preparation. Efficiency mandates from the EU Ecodesign Directive and US DOE standards reshape product development priorities.
- Food Preparation:Motor-driven blade and mixing systems process raw ingredients through mechanical shear and emulsification. Multi-function convergence threatens standalone category volume as combination appliances penetrate Asian urban households.
- Food Storage:Thermoelectric and compressor-based cooling systems preserve perishables through temperature and humidity control. Portable configurations serve outdoor and vehicle applications with specialized power requirements.
Cooking applications retain volume leadership; beverage brewing holds the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters export finished small appliances to European and North American retail networks, while domestic consumption in Guangdong and Zhejiang provinces absorbs substantial volumes of induction cooktops and multi-functional food processors.
China
Urban household densification in Shanghai and Shenzhen accelerates replacement cycles for multi-functional countertop devices. MIIT energy-efficiency classifications tighten domestic market access requirements ahead of export parity. Guangdong province anchors integrated production campuses serving both domestic platforms and European-bound shipments.
Germany
Beverage preparation rituals sustain premium pricing for espresso equipment across Bavarian and North Rhine-Westphalian households. The EU Ecodesign Directive imposes material restrictions and standby power limits that compress product development cycles. Stuttgart's industrial corridor concentrates engineering talent for precision thermostatic control systems.
United States
Single-person households and young renters reshape demand toward compact, multi-purpose configurations. US DOE appliance standards tighten federal efficiency thresholds that disqualify legacy import portfolios. The Southeast manufacturing corridor scales near-shored assembly to capture shelf space from non-compliant competitors.
India
Middle-class expansion in Maharashtra and Karnataka accelerates first-time ownership of blenders and mixer-grinders. BIS certification requirements create procurement friction for unorganized sector imports. Tamil Nadu's appliance manufacturing belt scales domestic production to serve secondary city penetration.
Indonesia
Platform logistics networks enable online retail penetration of secondary cities previously served only by informal channels. The country's national standards body implements electrical safety classifications that reshape import sourcing patterns. Java's urban corridor concentrates demand for compact cooking appliances suited to apartment kitchens.
Small Appliances Market Competitive Environment
Listed leaders compete with private specialists across capitalization and geographic coverage dimensions. The vendor base stratifies into three tiers: diversified conglomerates with appliance divisions, pure-play small appliance specialists, and private-label contract manufacturers. Strategic archetypes include ecosystem integrators embedding connectivity modules, heritage European brands commanding ritual-based premiums, and scale-driven Asian fabricators optimizing integrated production. Competitive moves concentrate on M&A for regional brand portfolios and capacity expansion into Vietnam and Mexico to navigate tariff and logistics cost pressures.
Among the diversified conglomerates, Haier Smart Home and Samsung Electronics exemplify ecosystem integrators embedding connectivity across countertop lines. Groupe SEB occupies a position within the heritage specialist tier, leveraging European manufacturing provenance for premium positioning in beverage preparation equipment. Midea Group anchors the scale-driven archetype through integrated production campuses in Guangdong and Hebei provinces.
| Leading Market Players |
|---|
| Haier Smart Home |
| Panasonic Corporation |
| Koninklijke Philips |
| Samsung Electronics |
| Whirlpool Corporation |
| Groupe SEB |
| LG Electronics |
| Electrolux Group |
| Midea Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles at major retailers signal pricing power concentration among integrated manufacturers with captive motor production. Asian production clusters leverage component proximity to compress working capital requirements, while European heritage brands extract premiums through certification-tier positioning that downstream distributors cannot replicate.
Pricing Analysis
GaN-enabled premium lines command 40-60% markups over silicon-based equivalents, while prior-generation resistive heating appliances face accelerating price erosion in hypermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates connected ecosystem bundles from basic mechanical units and private-label imports. Pricing pressure stems from copper and rare-earth magnet volatility that compresses margins in motor-dependent categories. Small appliance buyers in Southeast Asian secondary cities exhibit highest price sensitivity, whereas German and Italian households demonstrate lowest sensitivity due to ritual-based beverage preparation loyalty.
Supply Chain Analysis
Inventory buffers at 45-60 days characterize the channel, reflecting ocean freight dependency for finished goods from Guangdong and Hebei provinces. Manufacturing concentrates in China, Vietnam, and Mexico as tariff mitigation reshapes final assembly geography. Motor assemblies draw from Chinese rare-earth processing and Malaysian copper wire drawing facilities. Single-source vulnerability in GaN semiconductor supply threatens premium product ramps. Distribution runs through platform logistics networks penetrating Indonesian and Vietnamese secondary cities alongside traditional hypermarket consolidation in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Small appliances sit in early-cycle expansion as middle-class penetration in Indian and Indonesian secondary cities accelerates first-time ownership rates ahead of replacement saturation.
For Market Incumbents: Consolidate regional brand portfolios through targeted acquisition of heritage European coffee equipment specialists facing succession pressure. Deepen backward integration into motor and heating element production to offset rare-earth price volatility. Defend against connected-appliance ecosystem entrants by accelerating firmware development recruitment from automotive talent pools.
For New Entrants and Emerging Players: Differentiate on IoT-native architecture bypassing legacy mechanical platform technical debt. Target Vietnamese and Philippine secondary cities before local manufacturing scales erode import margins. Pursue direct-to-consumer subscription models with consumable auto-ship programs in North American urban markets where platform logistics penetration enables last-mile economics.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates seeking to divest non-core appliance divisions amid portfolio rationalization pressures. Five-to-ten year viability favors specialists with captive GaN sourcing and certification-ready platforms for EU Ecodesign Directive compliance. Monitor divergence between EU, US, and Chinese energy-efficiency test protocols as inflection signal for SKU complexity winners versus production platform fragmenters.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Integration | Enables slimmer induction cooktop form factors penetrating premium kitchen renovation channels. |
| Southeast Asian Manufacturing Footprint | Vietnamese assembly scales capture tariff-advantaged access to North American retail networks. |
| Subscription Service Launch | Auto-ship coffee pod programs build captive customer relationships in platform-logistics markets. |
| Multi-Jurisdiction Certification Investment | Parallel CE, FCC, and GB testing capability compresses product launch windows by 8-14 months. |
| Voice-Assistant Platform Partnership | Recipe programming integration creates attach-rate opportunities for consumable and service revenue. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with product development executives at tier-one manufacturers, category buyers at Amazon and Carrefour, and channel sales heads in Indonesia and Vietnam; alongside secondary validation through customs records, MIIT energy-efficiency filings, and EU Ecodesign Directive compliance databases. Bottom-up unit shipment modeling triangulated against top-down retail audit data from Nielsen and Circana.
Across the projection horizon, the analytical framework segmented volume and value by product type, end-user tier, distribution channel, and regional regulatory cluster. CAGRs derived from replacement cycle acceleration curves in China, India, and Indonesia cross-referenced against efficiency mandate compliance cost pass-through assumptions. Forecast inputs incorporated copper price volatility bands and GaN semiconductor cost decline trajectories.
Material uncertainties — regulatory test protocol divergence, rare-earth export restriction shocks, and platform logistics penetration variance — sit outside the modeled envelope. Forecasts reflect documented assumptions about middle-class expansion rates and connected-appliance adoption thresholds. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Small Electric Kettles Market
Appliances
Household Vacuum Cleaners Market
Appliances
Global Vended Laundry Equipment Market
Appliances
United States Electric Kettle Market
Appliances
Mini Washing Machine Market
Appliances
Portable Mini Fridge Market
Appliances
North America Personal Care Appliances Market
Appliances
Washing Appliances Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
US Electric Rice Cooker Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
North America Tumble Dryers Market
Appliances
Hair Removal Appliances Market
Appliances
Bathroom Heaters Market
Appliances
Bahrain Microwave Ovens Market
Appliances
Commercial Microwave Ovens Market