
 South Africa Laundry Appliances Market | 2026-2036
South Africa Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Laundry Appliances Market Analytics
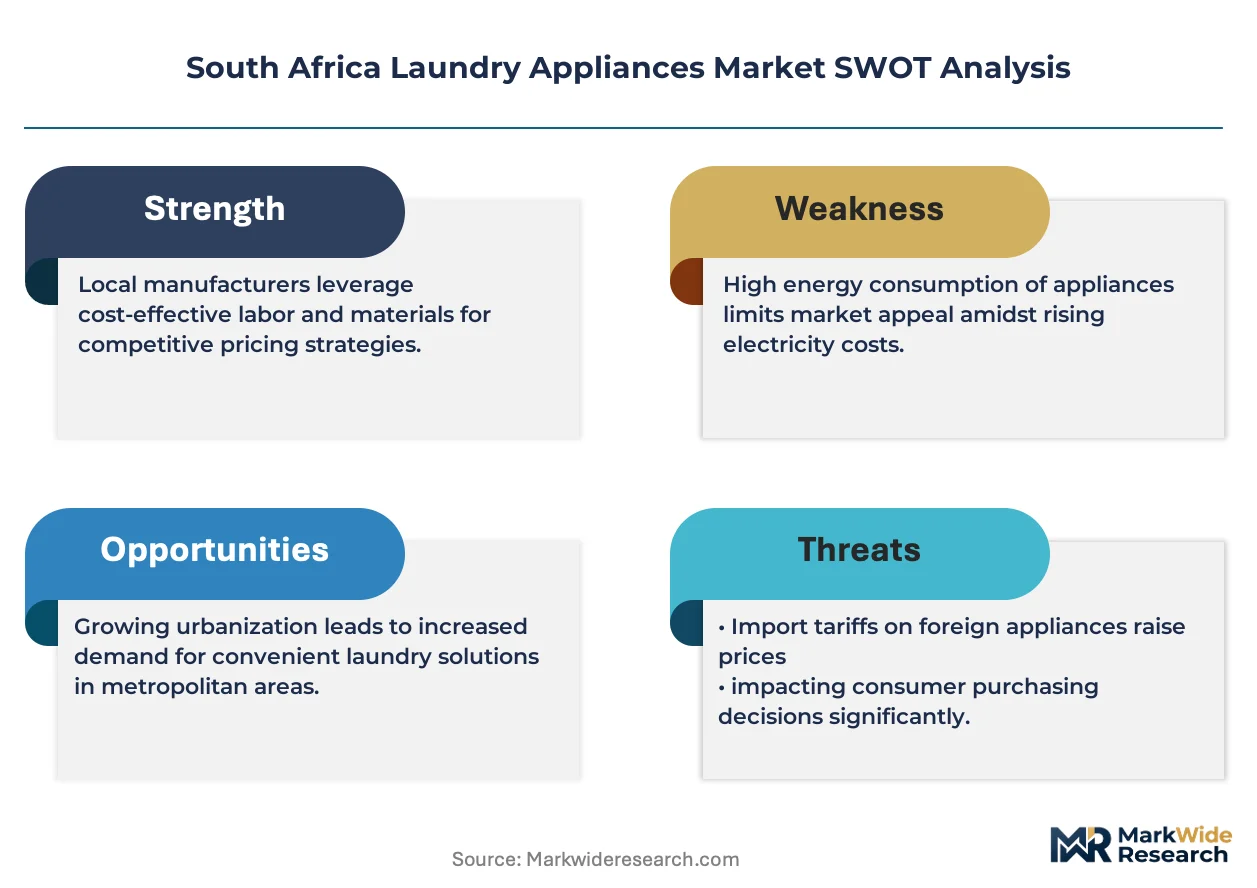
Subscription-based maintenance and software-defined wash cycles is realigning how manufacturers capture lifetime value from each unit deployed. Hisense SA leverages its local assembly footprint to control cost structures in the mass-market tier. Samsung differentiates through connected-home ecosystems that extend appliance functionality beyond core washing tasks. Defy anchors its position via deep distribution into township retail networks and independent appliance dealers.
South Africa laundry appliances encompass electrically powered machines designed for fabric cleaning, dehydration, or combined wash-dry cycles, typically rated between 5 kg and 16 kg capacity for residential units and exceeding 20 kg for commercial installations, operating on 220-240V single-phase or three-phase power. These systems serve households, laundromats, hotels, hospitals, and correctional facilities requiring hygienic textile processing at scale. Front-Load technology leads in water-scarce regions due to lower consumption per cycle, while Smart Appliances represent the fastest-expanding margin pool as Wi-Fi-enabled diagnostics reduce service-call costs. Washer-Dryer Combos occupy a niche among urban consumers facing space constraints in high-density developments.
The National Regulator for Compulsory Specifications enforces safety and energy-performance standards that determine which models qualify for retail, while SABS certification shapes procurement eligibility for institutional buyers. Municipal water restrictions in Cape Town and Gqeberha historically forced rapid adoption of low-water-consumption designs, conditioning consumer expectations nationwide. Stakeholders must monitor how evolving grid reliability and tariff structures influence inverter-motor penetration versus conventional induction-motor inventories.
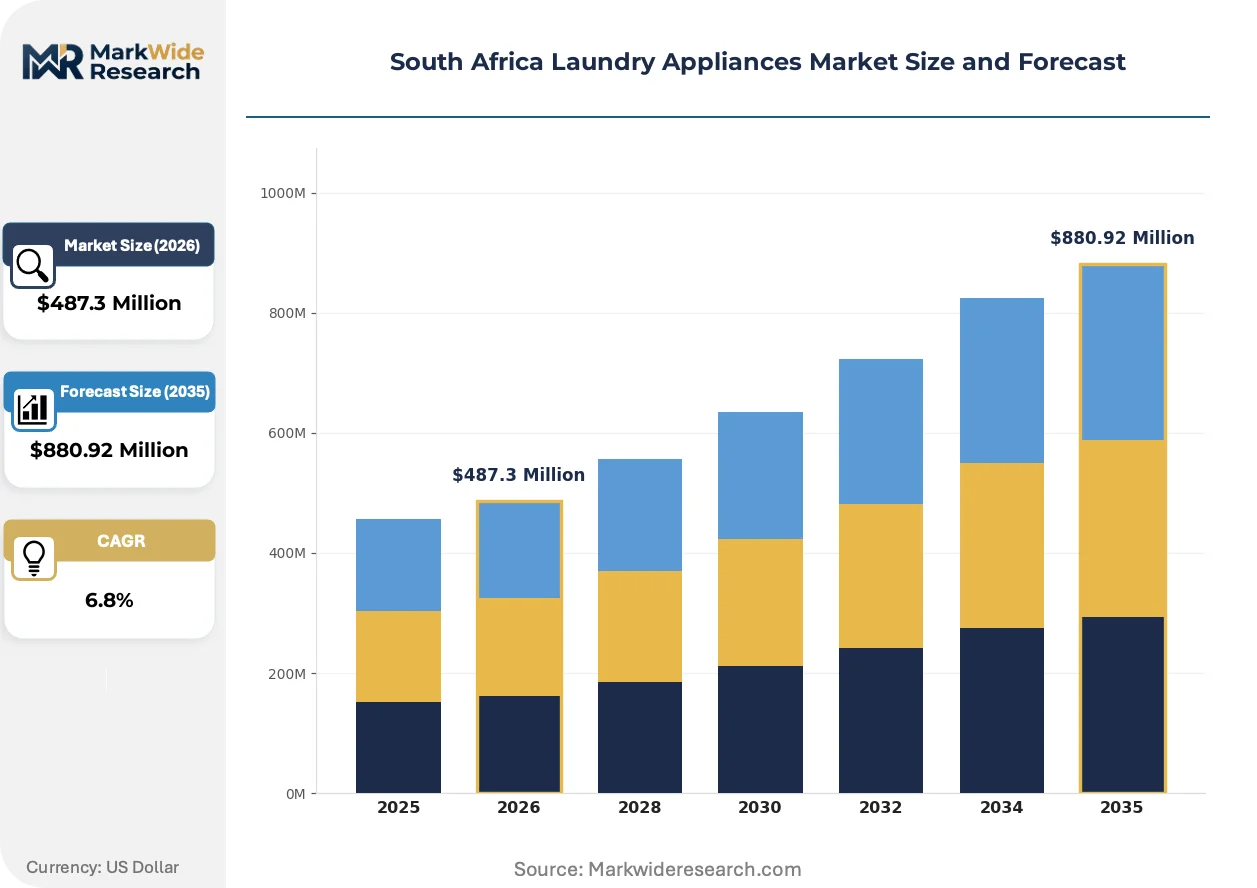
Market Dynamics
Inverter-motor technology is compressing energy consumption benchmarks while NRCS labeling mandates force rapid obsolescence of conventional induction-motor inventories across South African retail channels.
Growth Catalysts
- NRCS Energy-Efficiency Labeling:Compulsory energy-performance tiers accelerate replacement cycles in residential segments and disqualify legacy imports from formal retail.
- Urban Apartment Density:Johannesburg and Cape Town high-rise developments generate concentrated demand for compact washer-dryer combos with sub-60cm depth specifications.
- Commercial Hospitality Procurement:Gauteng-based hotel chains and correctional facilities drive institutional volume for industrial-capacity units exceeding 20 kg load ratings.
Market Restraints
- Copper and Steel Input Volatility:Drum assemblies and motor windings expose manufacturers to commodity price swings that compress margin buffers in the mass-market tier.
- Import Dependency Concentration:Finished-goods inflows from Chinese manufacturing clusters create inventory risk during port congestion at Durban and Cape Town terminals.
- Grid Reliability Constraints:Eskom load-shedding schedules degrade inverter-motor performance advantages when backup power systems revert to modified sine-wave output.
Strategic Opportunities
- Subscription-Based Maintenance Models:Software-defined wash cycles and predictive diagnostics enable recurring revenue streams from deployed unit bases.
- Township Retail Network Penetration:Independent appliance dealers in Soweto and Khayelitsha represent underdeveloped channels for affordable front-load introductions.
- Water-Scarce Region Specialization:Cape Town and Gqeberha municipal restrictions have conditioned consumer preference for sub-50-liter cycles that manufacturers can export to Namibia and Botswana.
Industry Challenges
- SABS Certification Timelines:Institutional procurement eligibility requires extended testing protocols that delay product launches by six to nine months.
- Wi-Fi Module Integration Complexity:Smart appliance connectivity demands alignment with South African spectrum allocations and local ISP authentication standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Laundry Appliances Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Commercial Appliances Technology: Front-Load, Top-Load, Eco-Friendly, Smart Appliances End User: Residential, Commercial, Institutional, Hospitality Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Hisense SA, Miele, Samsung, Electrolux, Whirlpool Corporation, Defy, Bosch, Haier, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Laundry Appliances Market Evolving Landscape
Connected-home ecosystems and predictive maintenance algorithms are redefining value capture beyond hardware margins, while regulatory pressure on water and energy use compresses acceptable performance thresholds.
Inverter-motor variable-frequency drive technology is decentralizing energy consumption patterns across residential installations. Mid-income households in Pretoria and Durban are adopting these systems at accelerating rates despite premium positioning. This diffusion is decentralizing the historical advantage of conventional induction-motor cost structures in the entry-level segment.
NRCS compulsory specifications for safety and energy performance determine retail qualification thresholds. Non-compliant imports face automatic exclusion from formal distribution channels. Domestic manufacturers and authorized distributors are responding by accelerating local assembly investments to maintain shelf access.
After-sales service unbundling is fragmenting traditional warranty bundling. Independent technicians and third-party maintenance platforms are capturing recurring revenue from connected diagnostics. Gauteng province exhibits the most pronounced shift, where urban consumers prioritize subscription-based coverage over manufacturer-direct service networks.
South Africa Laundry Appliances Market Segmentation
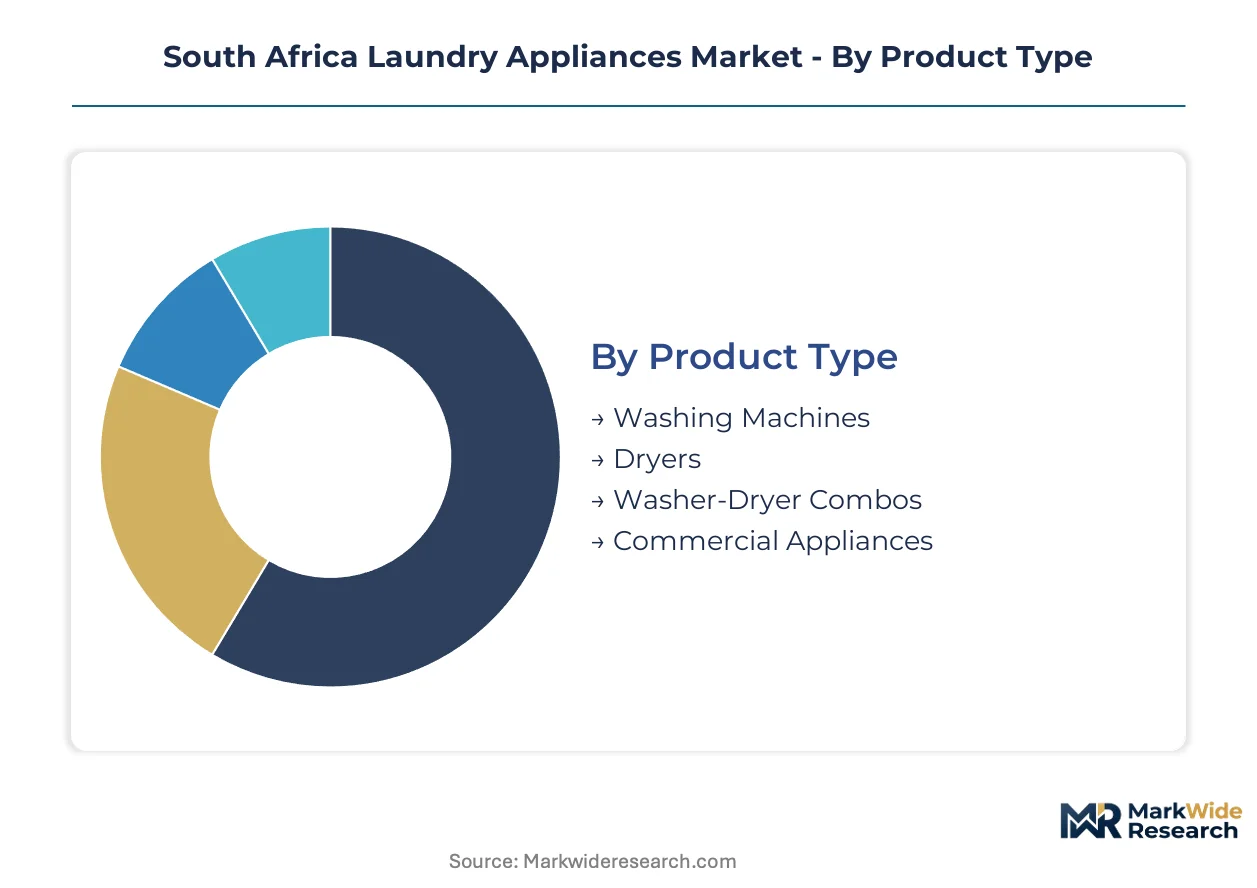
Segmentation in the South Africa laundry appliances market reveals how capital deployment, regulatory compliance, and channel economics concentrate profit pools differently across product configurations and customer types. Manufacturers must align production footprints with the specific technical and certification requirements of each segment to maintain shelf access.
Product Type:
Capital intensity varies sharply across product categories, with commercial appliances demanding the highest upfront tooling investment for drum assemblies and motor windings.
- Washing Machines:Standalone units rated 5-16 kg for residential use and exceeding 20 kg for commercial installations. Demand concentrates in Gauteng province households and Cape Town apartment complexes where NRCS energy-efficiency labeling drives replacement of induction-motor inventories.
- Dryers:Vented and condenser configurations operating on 220-240V single-phase power. Expansion is steepest in Johannesburg high-rise developments where municipal bylaws restrict outdoor clothesline usage.
- Washer-Dryer Combos:Integrated wash-dry cycles in sub-60cm depth enclosures. Urban density in Cape Town and Pretoria generates concentrated procurement from space-constrained consumers.
- Commercial Appliances:Industrial-capacity units exceeding 20 kg load ratings with three-phase power requirements. Gauteng hospitality chains and correctional facilities drive institutional volume.
Most installed capacity flows through Washing Machines. Expansion is steepest in Commercial Appliances.
Technology:
Cost tier stratification separates premium inverter-motor systems from conventional induction-motor price points, with smart connectivity commanding additional hardware premiums.
- Front-Load:Horizontal drum orientation with tumble-action cleaning and reduced water consumption per cycle. Cape Town and Gqeberha municipal restrictions have conditioned consumer preference for sub-50-liter configurations that manufacturers export to Namibia and Botswana.
- Top-Load:Vertical axis drums with agitator or impeller mechanisms. Township retail networks in Soweto and Khayelitsha represent underdeveloped channels for affordable front-load migration.
- Eco-Friendly:Water-recirculation systems and heat-pump drying technology. NRCS labeling mandates accelerate obsolescence of non-compliant imports from formal retail channels.
- Smart Appliances:Wi-Fi-enabled diagnostics and software-defined wash cycles. Predictive maintenance algorithms reduce service-call costs for distributors while enabling subscription-based recurring revenue.
Front-Load systems command the largest installed base. Smart Appliances are climbing the fastest as connectivity modules penetrate mid-income Pretoria and Durban households.
End User:
Application-specific requirements dictate warranty structures, with institutional procurement demanding extended SABS certification timelines that delay product launches.
- Residential:Individual households in urban apartment complexes and suburban developments. Johannesburg and Cape Town high-rise density generates concentrated demand for compact configurations.
- Commercial:Independent laundromats and textile service providers. After-sales service unbundling fragments traditional warranty bundling as third-party maintenance platforms capture recurring revenue.
- Institutional:Correctional facilities and government healthcare sites requiring hygienic textile processing at scale. SABS certification shapes procurement eligibility with six-to-nine month testing protocols.
- Hospitality:Hotel chains and serviced apartment operators. Gauteng province concentrates the highest volume of procurement for industrial-capacity units.
Residential accounts for the majority of units in service. Hospitality is gaining share fastest as tourism infrastructure investment accelerates.
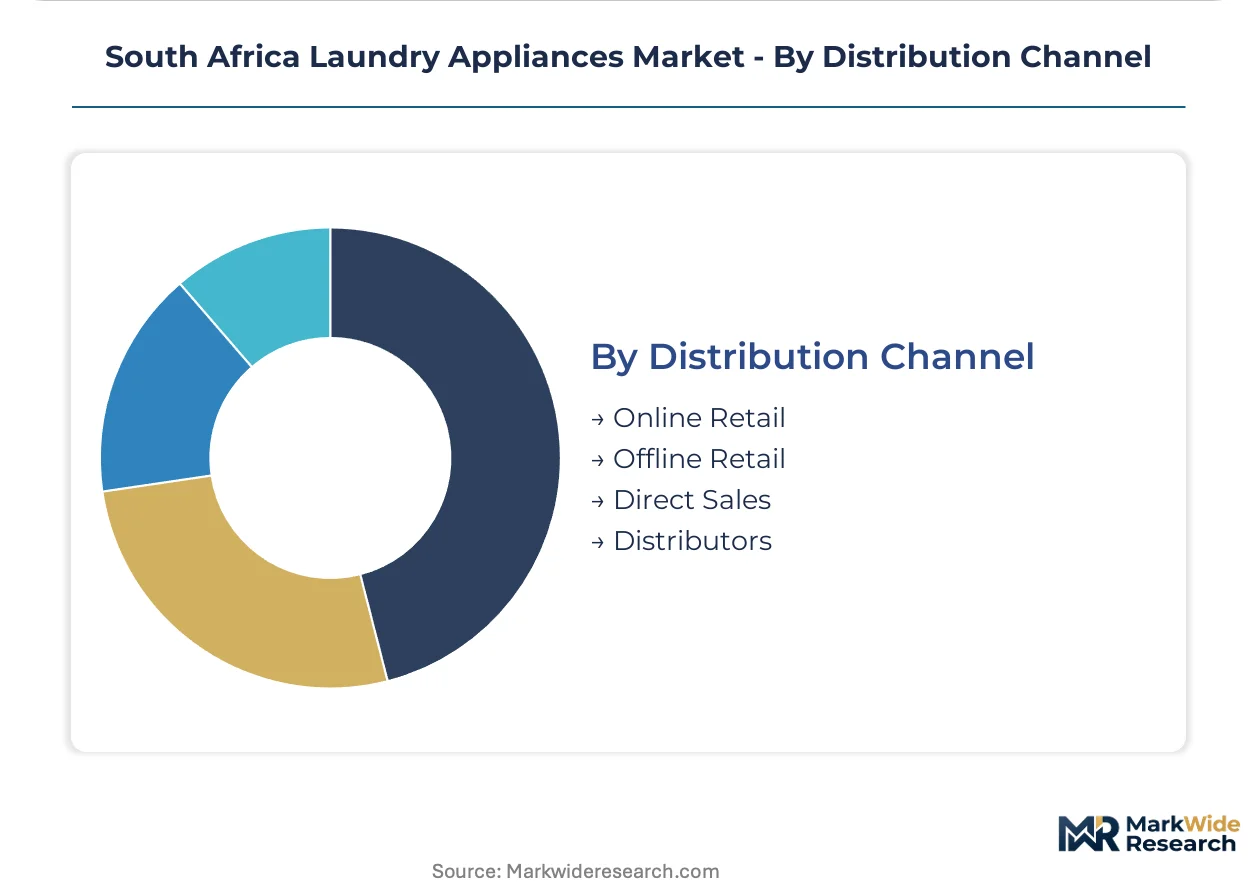
Distribution Channel:
Customer type and purchase frequency determine channel economics, with high-consideration residential buyers favoring physical inspection while institutional procurement runs through formal tender processes.
- Online Retail:E-commerce platforms with delivery logistics for compact residential units. Connectivity module integration demands alignment with South African spectrum allocations and local ISP authentication standards.
- Offline Retail:Appliance dealers and mass-market retailers. Deep distribution into township networks anchors volume for mass-market tier manufacturers.
- Direct Sales:Manufacturer-to-institutional relationships for commercial and hospitality procurement. Extended sales cycles accompany SABS certification requirements.
- Distributors:Regional wholesalers serving independent retailers and service providers. Port congestion at Durban and Cape Town terminals creates inventory risk for import-dependent channels.
Offline Retail handles the largest transaction volume. Online Retail is expanding most quickly as logistics networks improve last-mile coverage in secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban density and regulatory frameworks diverge sharply between Gauteng and Western Cape provinces, while KwaZulu-Natal and Eastern Cape present distinct channel economics for appliance distribution.
Gauteng Province
Johannesburg high-rise developments and Pretoria mid-income households generate concentrated demand for compact washer-dryer combos. The National Regulator for Compulsory Specifications enforces energy-efficiency labeling that accelerates replacement of induction-motor inventories. Industrial procurement clusters in Johannesburg and Tshwane drive institutional volume for commercial-capacity units.
Western Cape
Cape Town municipal water restrictions have conditioned consumer preference for sub-50-liter wash cycles. SABS certification requirements shape eligibility for hospitality procurement from hotel chains operating in the city center and Atlantic Seaboard. Manufacturing and distribution facilities concentrate in Cape Town port zones facing congestion risk.
KwaZulu-Natal
Durban's subtropical climate sustains demand for vented dryer configurations restricted in Johannesburg bylaws. The province's independent retail networks in townships represent underdeveloped channels for front-load migration. Port of Durban throughput constraints create inventory risk for import-dependent distributors.
Eastern Cape
Gqeberha water-scarce conditions mirror Cape Town's regulatory pressure on consumption benchmarks. Correctional facility procurement in the province drives demand for industrial-capacity units exceeding 20 kg ratings. Township retail penetration in Port Elizabeth townships lags Gauteng distribution density.
South Africa Laundry Appliances Market Competitive Landscape
Top-tier vendors anchor premium positioning through connected-home ecosystems, while mass-market specialists compete on assembly footprint and township channel depth. The vendor base stratifies across three tiers: multinational electronics conglomerates with smart appliance portfolios, regional assemblers with cost-controlled local production, and independent distributors serving fragmented retail networks. Two strategic archetypes dominate: ecosystem integrators bundling laundry functions into broader connected-home platforms, and manufacturing specialists leveraging backward integration into motor and drum assembly. Competitive moves concentrate on subscription-based maintenance models and predictive diagnostics to capture recurring revenue.
Among multinational electronics conglomerates, Samsung and LG Electronics exemplify ecosystem-integrator positioning through connected-home platform strategies. Hisense SA and Defy anchor the regional-assembler tier with manufacturing presence calibrated to NRCS compliance and township retail penetration. Miele occupies a premium specialization niche distinct from volume-driven competitors.
| Leading Market Players |
|---|
| Hisense SA |
| Miele |
| Samsung |
| Electrolux |
| Whirlpool Corporation |
| Defy |
| Bosch |
| Haier |
| LG Electronics |
| Others |
Value Network & Pricing Analysis
Copper and steel input volatility cascades from Chinese manufacturing clusters through Durban port congestion into South African retail channels, compressing margin buffers for mass-market tier manufacturers while inverter-motor premium tiers absorb cost shocks through NRCS energy-efficiency certification premiums.
Pricing Analysis
Capacity additions in Chinese motor-winding facilities are reshaping price floors for induction-motor inventories across South African formal retail. Three-tier pricing structure across premium, standard, and economy levels separates smart-connected inverter systems from conventional induction models and entry-level top-load units. Price differentiation hinges on NRCS energy-efficiency grade certification and after-sales service bundling. Cost compression in economy tiers is intensifying because import-dependent distributors face inventory risk during port congestion. Township retail networks in Soweto and Khayelitsha exhibit highest price sensitivity, while Gauteng hospitality chains prioritize total-cost-of-ownership over upfront unit cost.
Supply Chain Analysis
Direct-to-retail channels from Chinese manufacturing clusters handle volume demand for mass-market tier units, while authorized distributor networks manage NRCS compliance documentation for formal retail qualification. Finished-goods inflows draw primarily from China, with secondary sourcing from Turkey and Thailand for regional assembly inputs. Drum assemblies and motor windings rest on copper, cold-rolled steel, and rare-earth magnet dependencies. Single-source vulnerability concentrates in Durban and Cape Town port terminals where congestion creates inventory risk. Distribution runs through regional wholesalers serving independent township retailers and mass-market appliance chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's laundry appliance market represents a late-cycle quality story as NRCS energy-efficiency mandates and water-scarcity regulations shift procurement specifications toward inverter-motor smart systems with predictive maintenance capabilities.
For Market Incumbents: Deepen backward integration into motor and drum assembly to offset copper and steel input volatility threatening mass-market tier margins. Accelerate local assembly investments to maintain shelf access against NRCS labeling disqualification of non-compliant imports. Prioritize certification investment for SABS institutional procurement eligibility to defend against emerging regional assemblers with cost-controlled production footprints. For New Entrants and Emerging Players: The price-point gap between premium smart-connected systems and economy induction-motor units creates white-space opportunity for mid-tier inverter offerings with stripped connectivity features. Target underpenetrated township retail networks in KwaZulu-Natal and Eastern Cape where front-load migration lags Gauteng density. Deploy direct-to-installer go-to-market angles bypassing established distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where import-dependent distributors face margin compression from port congestion and currency volatility alongside NRCS compliance cost escalation. Five-to-ten year viability favors regional assemblers with captive motor production and township channel control over pure-import distribution plays. Monitor inverter-motor penetration rates in Pretoria and Durban mid-income households as inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Footprint Expansion | Hisense SA demonstrates how captive production controls cost structures against import volatility. |
| Subscription-Based Maintenance Launch | Predictive diagnostics enable recurring revenue capture from deployed unit bases in Gauteng. |
| Township Retail Network Penetration | Defy's distribution depth into Soweto and Khayelitsha anchors volume in underdeveloped channels. |
| Smart Appliance Connectivity Integration | Samsung's ecosystem bundling extends functionality beyond core washing tasks into home automation. |
| Water-Scarce Region Product Specialization | Cape Town's sub-50-liter cycle preference exports to Namibia and Botswana as regional standard. |
Research Methodology
Direct dialogue with appliance manufacturing executives, NRCS compliance officers, hospitality procurement managers, and independent township retailers grounded qualitative insights in operational reality. Secondary validation drew from SABS certification databases, NRCS compulsory specifications registers, Eskom grid reliability disclosures, and municipal water restriction records. Bottom-up and top-down triangulation reconciled unit shipment estimates with channel inventory audits and institutional tender documentation.
Bottom-up modeling aggregated segment-level volume and value outputs across product type, technology tier, end-user category, and distribution channel dimensions. Top-down constraints anchored projections to macroeconomic indicators and housing completion data. CAGRs were derived from fitted trend analysis across the projection horizon. Industry-specific forecast inputs included inverter-motor adoption curves conditioned by load-shedding frequency and NRCS labeling enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for heat-pump drying or water-recirculation systems would alter the outlook if NRCS mandates accelerate beyond base-case timelines. Forecasts reflect documented assumptions regarding grid reliability stabilization and port throughput normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Digital Showers Market
Appliances
Smart Dishwasher Market
Appliances
Tumble Dryer Market
Appliances
French Door Refrigerator Market
Appliances
United States Electric Kettle Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Electric Dryers Market
Appliances
Europe Microwave Oven Market
Appliances
Dishwasher Market
Appliances
US Portable Washing Machines Market
Appliances
Large Cooking Appliance Market
Appliances
Turkey Washing Machine Market
Appliances
Consumer Appliances Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
Smart Microwave Oven Market