
 Sanitary Towel Machine Market | 2026-2036
Sanitary Towel Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Towel Machine Market Insights
Contract manufacturers serving private-label brands is collapsing as a buyer archetype while integrated hygiene multinationals expand captive machine procurement. Zuiko leverages deep specialization in ultra-thin converting lines to anchor Japanese supply chains. Jiangsu JWC Machinery Co. Ltd. competes aggressively on automated platform cost structures across Southeast Asia. Fameccanica.Data S.r.l. differentiates through servo-driven web handling precision that reduces substrate waste.
Sanitary towel machines are high-speed converting systems that laminate absorbent cores, apply adhesive patterns, and die-cut individual pads at outputs exceeding 1,000 units per minute. These systems serve consumer hygiene manufacturers producing disposable menstrual products for retail and institutional channels. Automated technology leads installed capacity due to labor cost pressures and throughput requirements, while hybrid configurations capture growing interest among manufacturers balancing flexibility with capital constraints. Biodegradable product types command premium machine specifications as substrate handling complexity rises with sustainable materials.
CE marking under the EU Machinery Directive governs equipment safety and electromagnetic compatibility for European deployments, while China's SAMR enforces GB standards on mechanical reliability and operator protection. India's BIS certification requirements for imported industrial equipment create non-tariff barriers that domestic assemblers exploit. Stakeholders must monitor how evolving polymer substrate regulations across multiple jurisdictions reshape converting line compatibility requirements and retrofit economics.
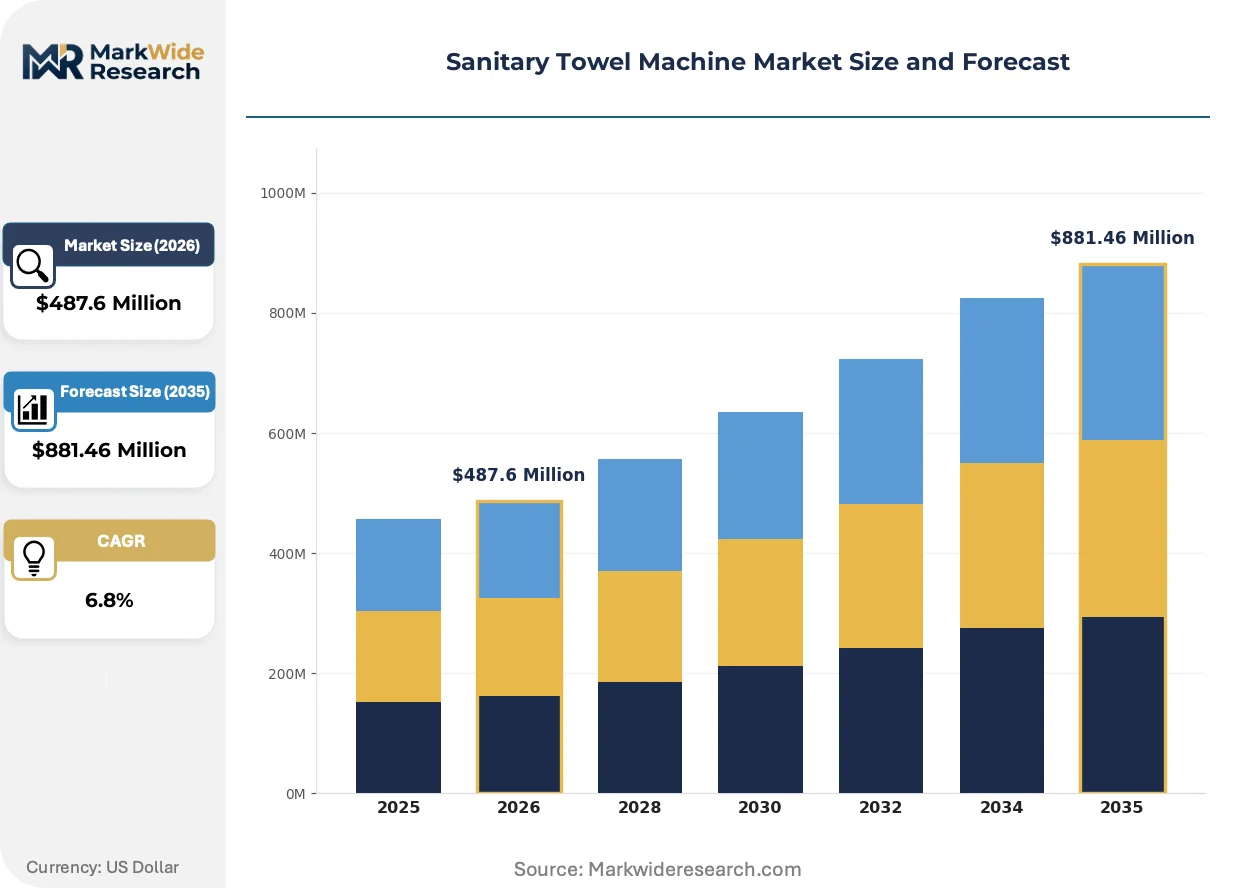
Market Dynamics
India's PLI-linked incentives for domestic hygiene manufacturing are accelerating captive machine procurement and collapsing third-party contract manufacturing relationships across South Asian supply chains.
Growth Catalysts
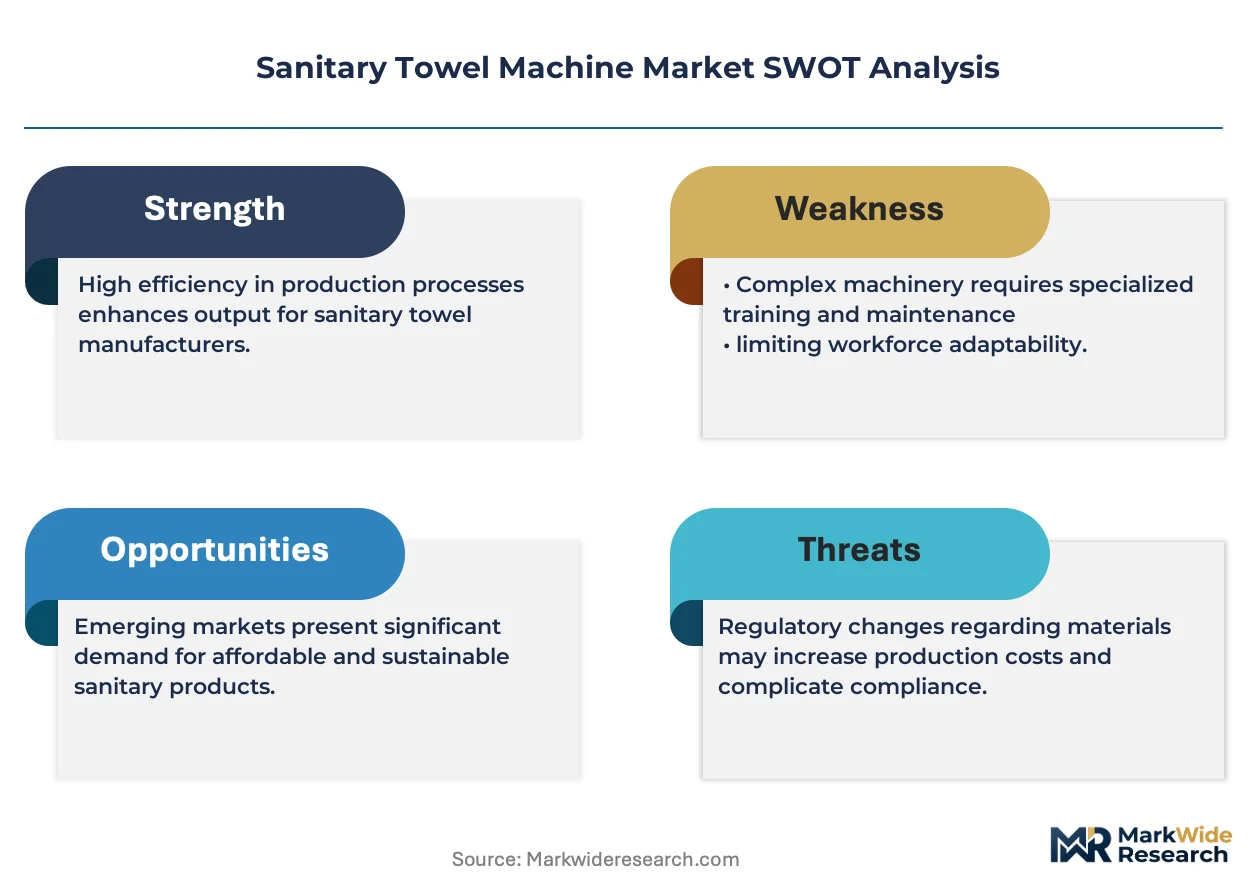
- Biodegradable substrate mandates:China's evolving GB standards on sustainable materials are forcing equipment retrofits that handle cellulose-based absorbent cores.
- India's Production Linked Incentive scheme:Domestic hygiene manufacturers are expanding converting capacity to capture government-backed output subsidies.
- Servo-driven web handling:Precision tension control systems are reducing polymer waste and enabling thinner product specifications.
Market Restraints
- Specialized component supply concentration:Precision die-cutting modules rely heavily on German and Japanese tooling suppliers.
- REACH compliance costs:European chemical safety documentation requirements for adhesive systems add non-recoverable engineering overhead.
- Technical limitation in sustainable materials:Biodegradable films exhibit lower tensile strength, constraining maximum line speeds.
Strategic Opportunities
- Underpenetrated African markets:Local assembly partnerships in Nigeria and Kenya bypass import duties on complete systems.
- Regulatory tailwind from EU Green Deal:Circular economy packaging mandates create retrofit demand for existing European installed base.
- Technology convergence of vision inspection and AI:Real-time defect detection is enabling unattended shift operations.
Industry Challenges
- Electromechanical technician scarcity:Servo system calibration and predictive maintenance require skills concentrated in automotive sector workforces.
- CE marking timeline compression:EU Machinery Directive conformity assessment delays are extending order-to-commission cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Towel Machine Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Biodegradable, Ultra-thin, Organic End User: Manufacturers, Retailers, Distributors, Merchants Technology: Automated, Semi-automated, Manual, Hybrid Material: Non-woven Fabric, Cotton, Adhesive, Polymer |
| Companies Covered | Curt G Joa Inc., MD Viola Macchine, Jiangsu JWC Machinery Co. Ltd., Fameccanica.Data S.r.l., Zuiko, GDM, W+D, SANIMAC SRL, HENGCHANG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Towel Machine Market Trends and Innovations
Converting equipment is pivoting from mechanical cam systems toward digital motion control architectures that compress changeover times and enable lot-size flexibility.
Servo-electric actuation is displacing pneumatic and mechanical drive trains in high-speed lamination stations. Mid-sized hygiene manufacturers in Southeast Asia are adopting these platforms fastest to balance throughput with SKU proliferation. This displacement is compressing the premium commanded by legacy mechanical specialists and flattening vendor tier structures.
REACH chemical registration requirements are expanding documentation burdens for adhesive applicator suppliers serving European deployments. Manufacturers must now trace polymer additive chains through multi-tier substrate suppliers. Equipment buyers in Germany and France are prioritizing vendors with pre-validated material handling configurations to accelerate compliance timelines.
After-sales service unbundling is fragmenting traditional full-service contracts into component-level subscription tiers. Private-label manufacturers in India are purchasing base hardware and sourcing spare parts through independent distributors. This pattern is most visible among first-time machine buyers with limited technical staff who prioritize capital flexibility over vendor loyalty.
Sanitary Towel Machine Market Segmentation
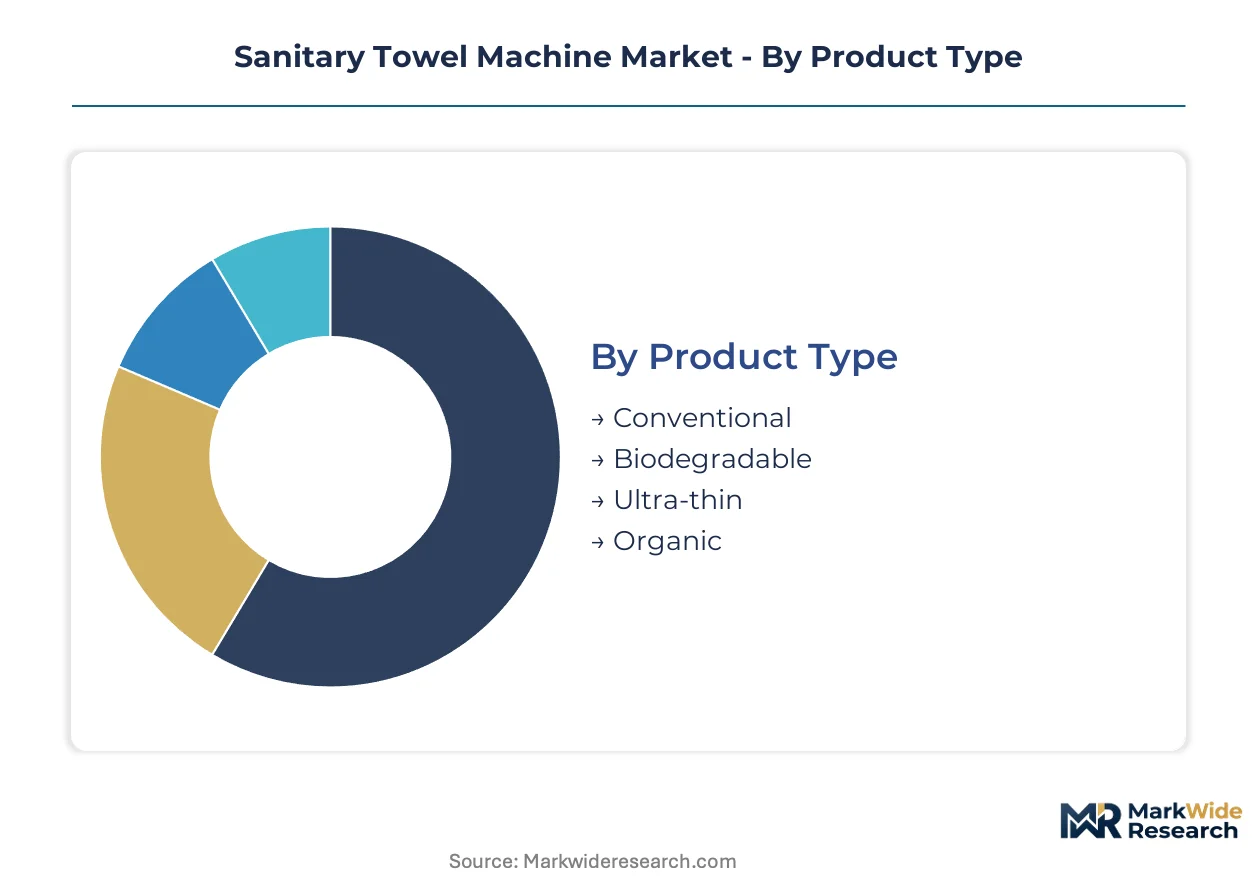
Sanitary towel machine procurement patterns diverge sharply across product specifications and operational scales. Buyers calibrate capital deployment against regulatory mandates, substrate compatibility requirements, and throughput targets that vary by end-use channel.
Product Type:
REACH compliance in Europe and evolving GB standards in China impose distinct material handling specifications on converting equipment across biodegradable and conventional categories.
- Conventional:Machines process petroleum-based absorbent cores and synthetic films at maximum line speeds exceeding 1,000 units per minute. Demand concentrates among established hygiene multinationals in Germany and Japan seeking throughput optimization over substrate flexibility.
- Biodegradable:Equipment incorporates modified tension control systems and gentler die-cutting modules to handle cellulose-based films with lower tensile strength. India's PLI-linked capacity expansion favors this segment as domestic manufacturers target export markets with EU Green Deal-aligned specifications.
- Ultra-thin:Precision lamination stations achieve sub-millimeter core thickness through servo-driven web handling. Japanese supply chains anchor demand for this specification.
- Organic:Specialized substrate feeding mechanisms accommodate natural cotton and unbleached pulp with irregular fiber distribution. Niche positioning limits deployment scale.
Established volume favors conventional platforms; emerging adoption favors biodegradable configurations.
End User:
Customer scale and captive integration depth determine equipment specification complexity and service contract structures.
- Manufacturers:Integrated hygiene producers deploy fully automated converting lines with vision inspection and AI-driven defect detection. Southeast Asian mid-sized manufacturers represent the steepest expansion trajectory for hybrid platform adoption.
- Retailers:Private-label sourcing departments specify machines with rapid changeover capabilities to accommodate SKU proliferation. Indian retailers collapsing contract manufacturing relationships are accelerating direct equipment procurement.
- Distributors:Regional trading houses facilitate machine imports and assembly partnerships in underpenetrated African markets. Nigerian and Kenyan local assembly arrangements bypass complete system import duties.
- Merchants:Independent trading entities source refurbished equipment and spare parts through unbundled after-sales channels. Capital-constrained first-time buyers in India favor this procurement pattern.
Manufacturer dominance persists in automated technology; retailer direct procurement is climbing fastest.
Technology:
Labor cost pressures and changeover flexibility requirements reshape the competitive economics of motion control architectures.
- Automated:Digital motion control systems with servo-electric actuation compress changeover times and enable unattended shift operations. Labor cost pressures in China and Southeast Asia drive replacement of mechanical cam systems.
- Hybrid:Configurations blend automated core forming with manual packaging stations to balance capital constraints against throughput targets. Mid-sized hygiene manufacturers in Southeast Asia adopt these platforms fastest.
- Semi-automated:Pneumatic drive trains persist in secondary markets where technician scarcity limits servo system calibration capabilities. Lower acquisition cost appeals to capital-constrained entrants.
- Manual:Minimal automation restricts output to artisanal or pilot-scale production. Limited commercial relevance outside equipment demonstration and training facilities.
Automated technology commands installed capacity leadership; hybrid configurations are gaining share fastest.
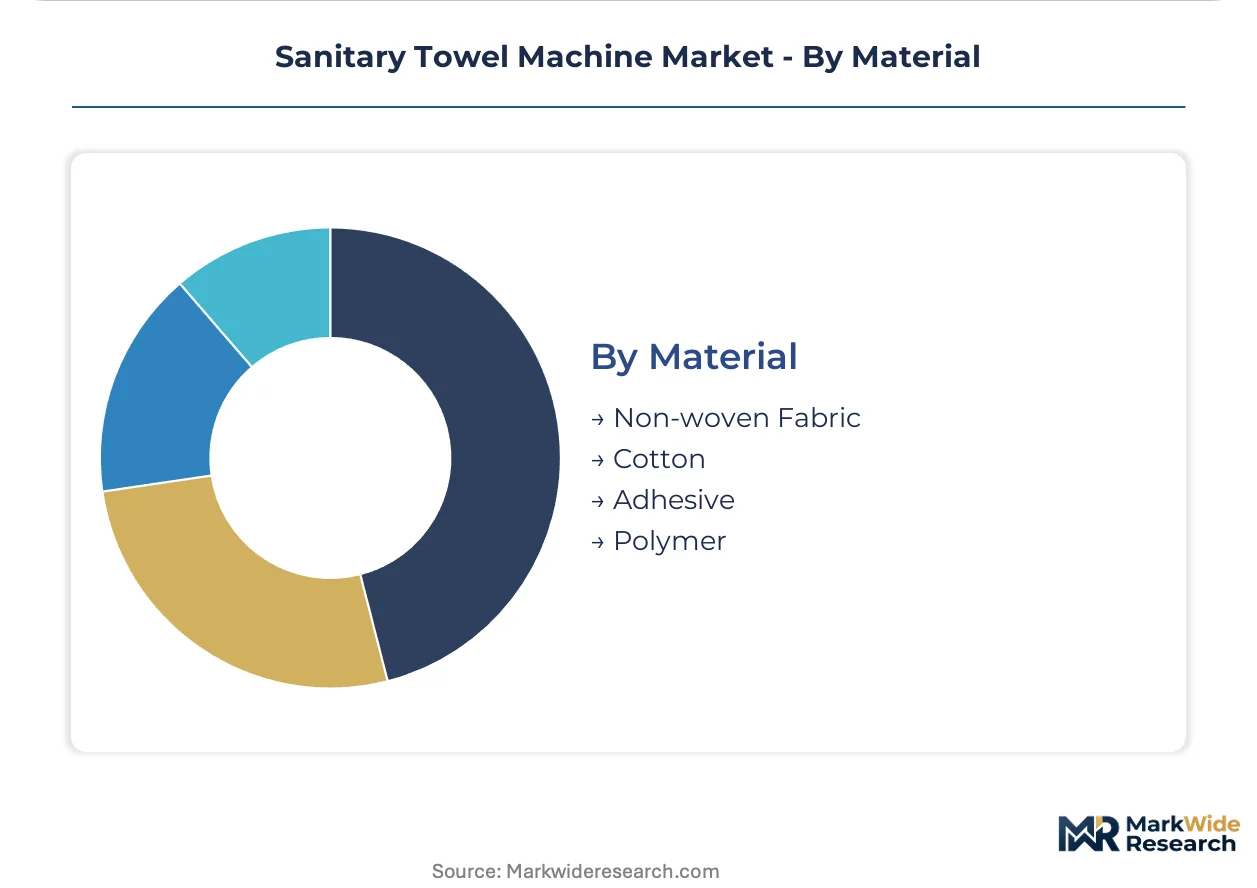
Material:
Substrate supply chain traceability requirements under REACH and GB standards reshape material handling module specifications.
- Non-woven Fabric:High-speed unwinding and tension control systems process spunbond and meltblown layers at outputs matching maximum line speeds. European deployments require ECHA-compliant additive documentation.
- Polymer:Specialized adhesive applicators and release liner handling modules manage polyethylene and polypropylene films. Waste reduction through precision tension control is displacing legacy mechanical systems.
- Cotton:Natural fiber feeding mechanisms accommodate higher variability in basis weight and moisture content. Organic product specifications drive niche demand.
- Adhesive:Hot-melt pattern applicators with rapid switching capability enable complex core-to-cover bonding geometries. REACH registration burdens concentrate engineering overhead on European equipment configurations.
Polymer handling dominates throughput-optimized installations; non-woven fabric compatibility is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated hygiene multinationals in Germany and Japan anchor premium equipment procurement, while mid-sized manufacturers in India and Southeast Asia drive volume expansion through PLI-linked incentives and labor cost arbitrage.
India
Domestic hygiene manufacturers are scaling converting capacity aggressively under Production Linked Incentive schemes that tie government subsidies to output targets. BIS certification requirements for imported industrial equipment create non-tariff barriers that domestic assemblers exploit to capture market share. Maharashtra and Gujarat host the fastest-growing machine procurement clusters as manufacturers target EU Green Deal-aligned export specifications.
China
Mid-sized hygiene product manufacturers are displacing contract manufacturers as primary equipment buyers across the Yangtze River Delta. SAMR-enforced GB standards on mechanical reliability and operator protection are reshaping equipment specifications for both domestic and export-oriented production lines. Zhejiang and Jiangsu provinces concentrate servo-driven platform adoption as labor cost pressures accelerate automation replacement cycles.
Germany
Established hygiene multinationals prioritize throughput optimization over substrate flexibility in conventional platform deployments. REACH compliance costs for adhesive system documentation add non-recoverable engineering overhead that favors vendors with pre-validated material handling configurations. North Rhine-Westphalia anchors precision die-cutting module demand through its concentration of automotive-tier tooling suppliers.
Japan
Ultra-thin converting line specifications dominate procurement patterns as domestic supply chains demand sub-millimeter core thickness capabilities. METI industrial standards shape equipment safety protocols that Japanese manufacturers export as de facto regional benchmarks. Kansai region producers maintain deep specialization in servo-driven web handling precision that reduces substrate waste.
Nigeria
Local assembly partnerships in Lagos and Kano bypass import duties on complete systems while addressing capital constraints among first-time machine buyers. Regional trading houses facilitate equipment imports through unbundled after-sales channels that prioritize spare parts accessibility over vendor loyalty. West African distributor networks are fragmenting traditional full-service contract structures.
Sanitary Towel Machine Market Competitive Landscape
Player mix skews toward specialized converting equipment fabricators with deep mechanical engineering heritage rather than diversified industrial conglomerates. Vendor tier structures are flattening as servo-electric actuation commoditizes precision motion control that previously anchored premium positioning. Strategic archetypes include ultra-thin specialists, automated platform cost leaders, and regional assembly partners. Capacity expansion and technology licensing represent the dominant competitive moves as geographic coverage and substrate flexibility determine procurement decisions.
Within the ultra-thin specialization tier, Fameccanica.Data S.r.l. and Zuiko occupy positions defined by precision web handling heritage. Jiangsu JWC Machinery Co. Ltd. exemplifies the automated platform cost leadership archetype competing across Southeast Asian markets. These three anchors illustrate how competitive positioning stratifies between precision-tier European and Japanese fabricators and scale-oriented Chinese suppliers.
| Leading Market Players |
|---|
| Curt G Joa Inc. |
| MD Viola Macchine |
| Jiangsu JWC Machinery Co. Ltd. |
| Fameccanica.Data S.r.l. |
| Zuiko |
| GDM |
| W+D |
| SANIMAC SRL |
| HENGCHANG |
| Others |
Pricing and Supply Chain Analysis
Servo-electric actuation displacing pneumatic drive trains simultaneously concentrates precision component sourcing in Germany and Japan while compressing the premium once commanded by legacy mechanical specialists. This substitution dynamic flattens vendor tier structures and reshapes how buyers negotiate equipment configurations across Southeast Asian procurement clusters.
Pricing Analysis
Cost-plus contracts with steel and rare-earth magnet indexation dominate equipment procurement between European and Japanese fabricators and integrated hygiene multinationals. Three-tier pricing structure across premium, standard, and economy levels separates servo-driven precision platforms from hybrid configurations and refurbished mechanical systems. Cost compression in mid-tier automated platforms intensifies as Jiangsu JWC Machinery Co. Ltd. and comparable Chinese suppliers compete on capital efficiency. Private-label manufacturers in India exhibit highest price sensitivity, while established hygiene multinationals in Germany prioritize pre-validated REACH-compliant configurations over acquisition cost.
Supply Chain Analysis
Container availability constraints on the Hamburg-Shanghai trade lane elevate inbound logistics costs for precision die-cutting modules sourced from German automotive-tier tooling suppliers. Component concentration rests on Germany and Japan for servo drives and cutting tools, China for structural steel and fabricated assemblies, and Italy for specialized lamination stations. Single-source vulnerability in precision tension control systems creates supply chain risk as semiconductor shortages persist in motion control chipsets. Distribution runs through regional trading houses in underpenetrated African markets and direct vendor relationships with integrated multinationals in established manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable menstrual product substitution threatens disposable sanitary towel volume growth, forcing incumbents to defend positioning through substrate innovation and sustainability-aligned equipment specifications.
For Market Incumbents: Secure captive supply of precision die-cutting modules through backward integration into German and Japanese tooling supplier networks. Anchor positioning by pre-validating equipment configurations for REACH compliance and EU Green Deal-aligned biodegradable substrate handling, neutralizing the regulatory threat from emerging Chinese platform competitors. For New Entrants and Emerging Players: BIS certification fast-tracks for domestic Indian assemblers exploit non-tariff barriers against imported complete systems. Target local assembly partnerships in Nigeria and Kenya where import duty avoidance and unbundled after-sales channels enable capital-flexible entry. Lead with spare parts accessibility and technician training programs rather than full-service vendor loyalty. For Investors and Strategic Acquirers: The market sits at a technology convergence phase that favors servo-electric automation specialists with proven biodegradable substrate handling capabilities. Long-term viability over a multi-year window hinges on equipment retrofit demand from Europe's circular economy mandates. Watch for inflection in Indian PLI scheme output targets as the signal indicating accelerated captive machine procurement versus contract manufacturing collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Handling Retrofit | EU Green Deal mandates drive equipment upgrades for cellulose-based film compatibility. |
| Servo-Electric Platform Standardization | Digital motion control architectures compress changeover times for SKU proliferation. |
| Local Assembly Partnership in Africa | Nigerian and Kenyan arrangements bypass complete system import duties. |
| REACH Pre-Validation Investment | Pre-certified adhesive handling configurations accelerate European deployment timelines. |
| After-Sales Service Unbundling | Component-level subscription tiers capture price-sensitive first-time buyers in India. |
Research Methodology
Cross-validation between equipment procurement databases and regulatory filing repositories anchors the qualitative findings on vendor positioning and compliance requirements. Primary interviews with converting line engineers, hygiene product procurement directors, aftermarket service heads, and plant managers at integrated multinationals combined with secondary validation from SAMR GB standard disclosures, ECHA REACH registration databases, Indian BIS certification records, and customs import data. Bottom-up unit economics triangulate against top-down market sizing from machinery production statistics.
Sensitivity analysis across servo system adoption rates, biodegradable substrate penetration scenarios, and PLI scheme participation levels shapes the analytical framework. Segmentation dimensions modeled include product type, technology architecture, end-user integration depth, and material handling specification across the projection horizon. CAGRs derive from equipment replacement cycle analysis, capacity expansion announcements, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporate polymer substrate price volatility and technician wage inflation in Southeast Asian manufacturing clusters.
Decision-makers should treat outputs as directional under assumptions of continued PLI scheme funding, stable EU-Asia trade lane capacity, and incremental rather than disruptive biodegradable material performance improvements; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Global Electric Water Heaters Market
Appliances
Microwave Market
Appliances
Electric Iron Market
Appliances
Israel Laundry Appliances Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
UAE Gas Hobs Market
Appliances
Smart Microwave Oven Market
Appliances
Induction Cooktops Market
Appliances
North America Microwave Oven Market
Appliances
Saudi Arabia Microwave Ovens Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Lightwave Microwave Oven Market
Appliances
Mobile Refrigerators Market
Appliances
Residential Vacuum Cleaners Market
Appliances
Small Appliances Market
Appliances
North America Washing Machine Market