
 United States Multi-Functional Oven Market | 2026-2036
United States Multi-Functional Oven Market Size, Share, and Industry Trends Forecast 2026-2036
United States Multi-Functional Oven Market Analytics
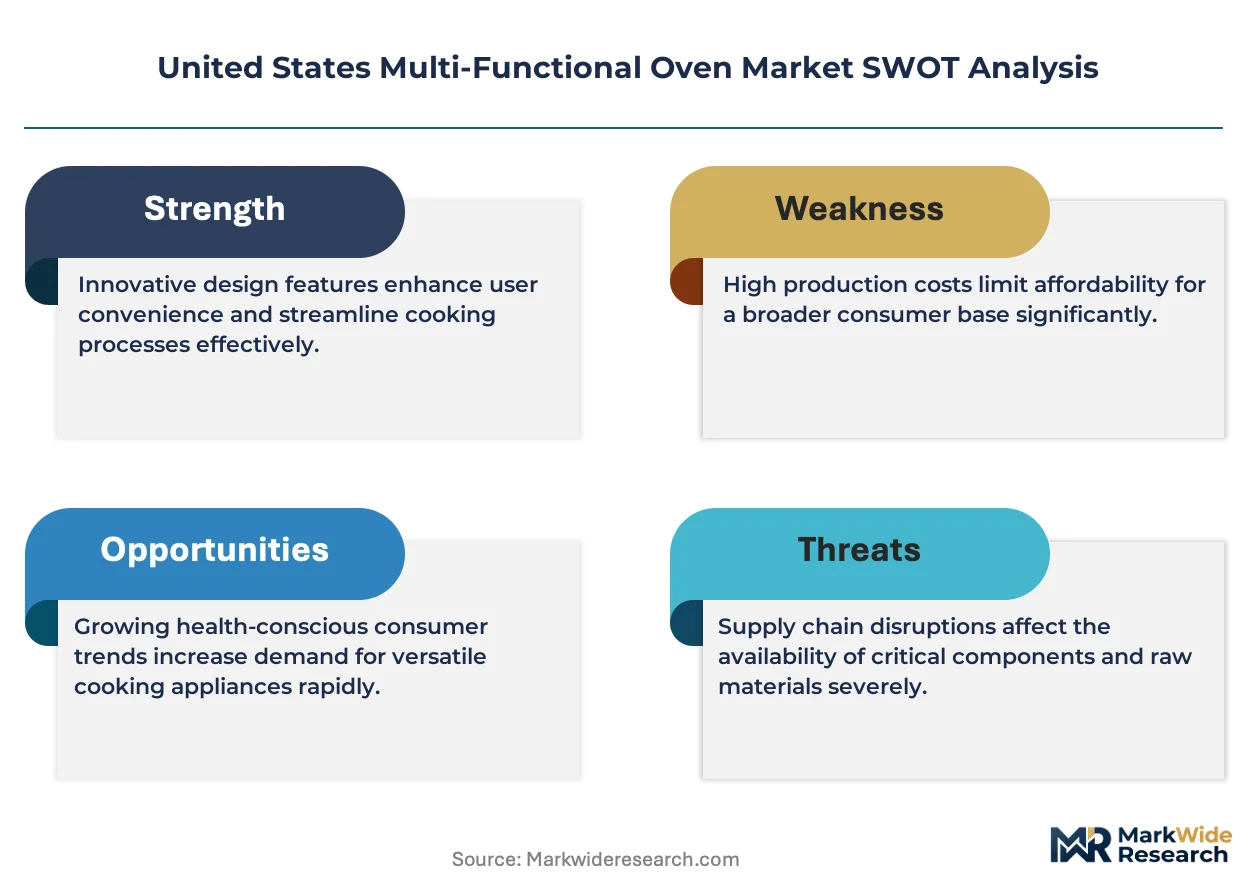
Restaurant end-use is pivoting toward hybrid cooking platforms that compress prep times across high-volume chains. Whirlpool Corporation leverages its distribution depth to anchor positions in built-in residential channels. Rational specializes in precision steam-convection systems for commercial kitchens. Middleby Corporation extends its portfolio breadth across catering and bakery segments through manufacturing scale.
Multi-functional ovens combine two or more heating modalities—convection, steam, microwave, or induction—within a single cavity rated between 2,400 and 15,000 watts depending on installation class. These units serve commercial foodservice and residential users seeking to consolidate equipment footprint while maintaining output versatility. Convection ovens occupy the largest installed base among product types due to decades of standardization in professional kitchens. Smart ovens represent the fastest-expanding technology segment as connectivity protocols enable remote monitoring and recipe automation. Built-in installations command premium positioning through cabinetry integration and permanent electrical connections.
DOE test procedures and ENERGY STAR certification requirements shape product efficiency benchmarks and eligibility for utility rebate programs. The FDA Food Code and state-level health department regulations govern commercial oven sanitation standards and operator training protocols. Stakeholders must monitor pending DOE rulemakings on standby power and active mode efficiency that could force redesign cycles before compliance deadlines solidify.
Market Dynamics
Restaurant chains are compressing equipment replacement cycles from seven to four years as labor scarcity forces kitchen automation investments. This acceleration is absorbing capital that previously flowed to single-function equipment, redirecting procurement toward platforms that consolidate steaming, convection, and microwave modalities into single footprints.
Growth Catalysts
- Texas and California commercial construction:Elevated kitchen permit issuance in these states is pulling demand for built-in installations ahead of national averages.
- DOE appliance efficiency standards:Tightening test procedures for cooking products are pushing manufacturers toward multi-modal designs that score better on integrated efficiency metrics.
- Steam-convection convergence:Precision humidity control technology is enabling faster protein cook times without moisture loss, appealing to high-volume catering operations.
Market Restraints
- Electrical infrastructure retrofit costs:15,000-watt commercial units require 240V three-phase connections that many legacy buildings lack, forcing expensive electrical upgrades.
- Supply concentration in induction componentry:Domestic sourcing of high-frequency power electronics remains limited, creating vulnerability to semiconductor foundry allocation decisions.
- Technician certification fragmentation:No unified EPA or OSHA pathway covers combined microwave-radiation and high-voltage training, lengthening service response times.
Strategic Opportunities
- Smart oven connectivity:IoT-enabled recipe automation and remote diagnostics are creating recurring revenue streams through subscription-based fleet management tools.
- Utility rebate capture:ENERGY STAR certification eligibility opens state-level efficiency incentive programs that offset premium pricing for efficiency-optimized models.
- Cloud kitchen penetration:Ghost kitchen operators in secondary metros are adopting compact multi-functional units to maximize output per square foot in leased spaces.
Industry Challenges
- Cross-training complexity:Kitchen staff must master simultaneous control of steam, convection, and microwave modalities, extending onboarding timelines.
- Sanitation protocol standardization:FDA Food Code variations across state health departments create compliance documentation burdens for national chain rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Multi-Functional Oven Market |
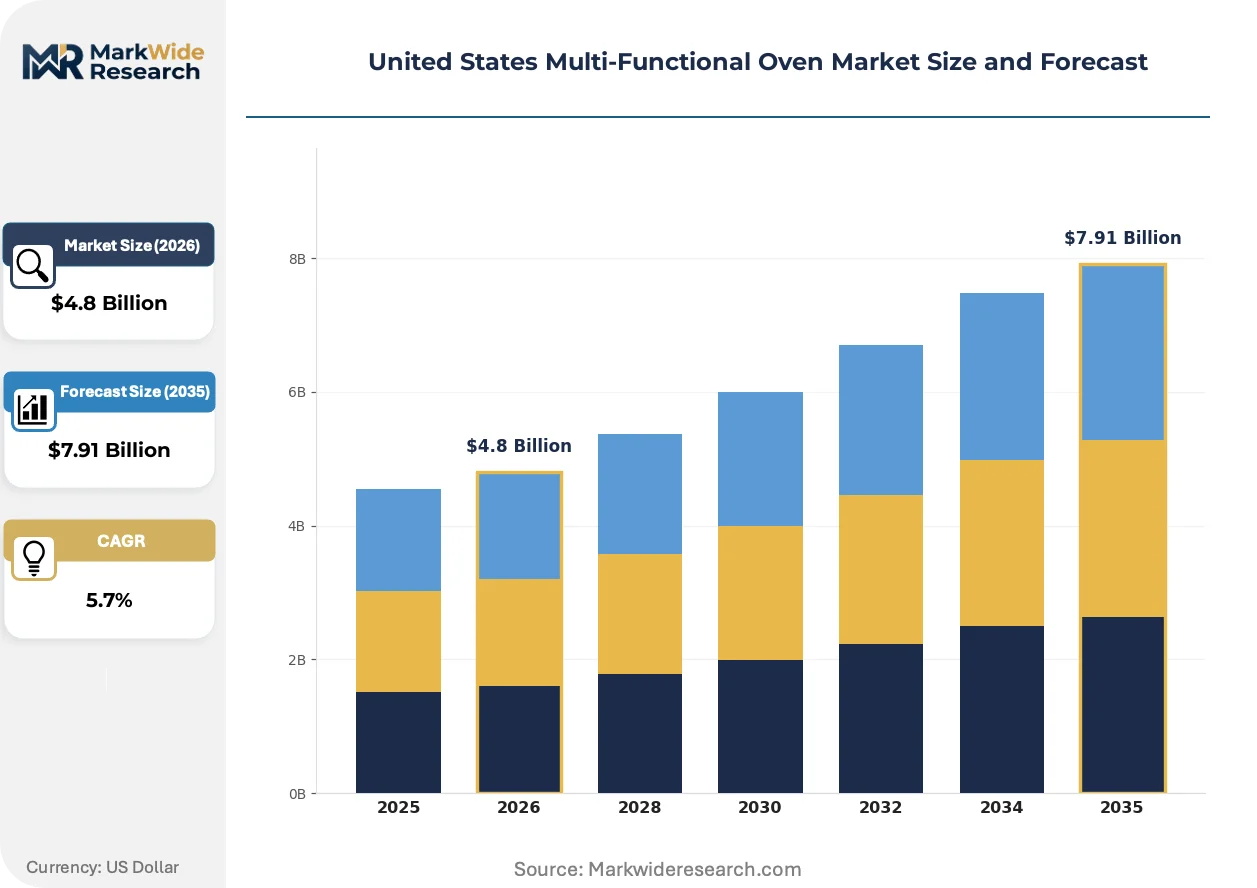
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Ovens, Microwave Ovens, Toaster Ovens, Steam Ovens End User: Households, Restaurants, Catering Services, Bakeries Technology: Smart Ovens, Conventional Ovens, Hybrid Ovens, Induction Ovens Installation Type: Built-in Ovens, Freestanding Ovens, Countertop Ovens, Under-Counter Ovens |
| Companies Covered | Frigidaire, Siemens, Whirlpool Corporation, Rational, Middleby Corporation, GE Appliances, Asko Appliances, Alto-Shaam Inc., Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Multi-Functional Oven Market Evolving Landscape
Equipment manufacturers are racing to embed predictive maintenance algorithms before competitors establish platform loyalty. The convergence of thermal sensing and machine learning is compressing the window between equipment anomaly detection and service dispatch.
Hybrid steam-convection systems are absorbing market share from standalone convection ovens as QSR chains prioritize protein yield consistency. Chili's and similar mid-casual operators are retrofitting line kitchens with these units to reduce ticket times during peak hours. The technology is absorbing capital previously allocated to separate holding cabinets and finishing ovens, consolidating vendor relationships.
DOE standby power rulemakings are forcing redesign cycles ahead of compliance deadlines. Manufacturers must reduce idle-state consumption without compromising preheat responsiveness. Commercial product lines face the steepest engineering constraints, as residential exemptions narrow and test procedures expand to capture parasitic loads from always-on connectivity modules.
Buying committees at regional restaurant groups are consolidating vendor relationships around single-source kitchen platforms. Distributors that previously sold equipment category-by-category are losing access to procurement decisions. This concentration is most visible in the Southeast, where private-equity-backed rollups are standardizing equipment specifications across acquired brands to simplify training and maintenance contracts.
United States Multi-Functional Oven Market Segmentation
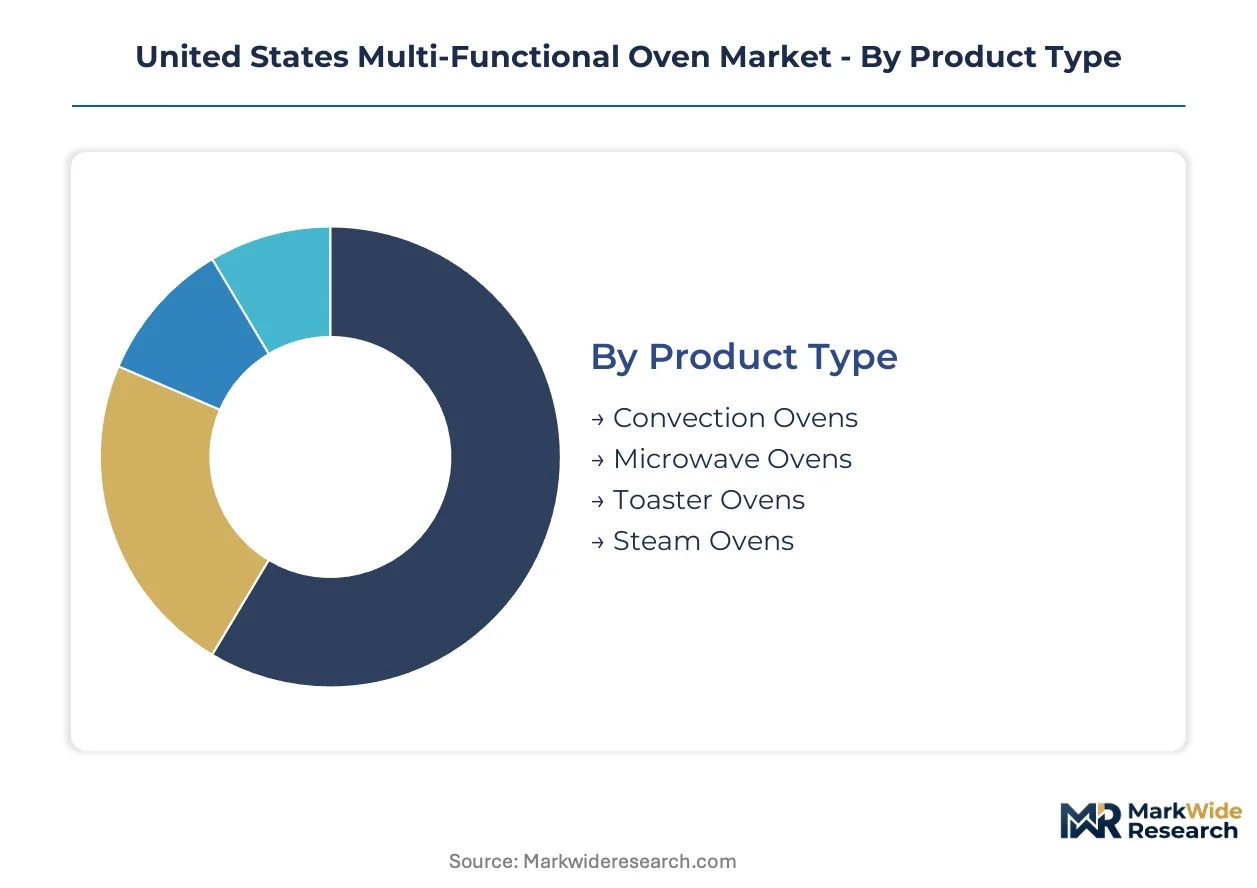
Segmentation in the United States Multi-Functional Oven Market reveals how certification requirements, installation constraints, and end-use intensity fragment procurement patterns. Understanding these divisions exposes where DOE efficiency standards and FDA sanitation protocols apply differentially.
Product Type:
DOE test procedure compliance varies sharply across heating modalities, with convection and steam platforms facing distinct efficiency benchmarking requirements under current rulemakings.
- Convection Ovens:These units circulate heated air via fan-driven systems to accelerate cook times and improve temperature uniformity. Demand concentrates in Texas and California restaurant chains where high-volume protein production requires consistent browning across batch loads. ENERGY STAR certification eligibility opens utility rebate programs that offset premium equipment costs.
- Steam Ovens:Precision humidity control systems enable protein cookery without moisture loss, preserving yield in catering operations. California health departments favor these units for their reduced grease vapor generation, simplifying hood ventilation compliance in urban kitchen retrofits. FDA Food Code alignment on internal temperature verification protocols accelerates adoption.
- Microwave Ovens:Magnetron-based rapid heating systems serve quick-service applications requiring minimal preheat latency. FCC emissions compliance adds certification overhead distinct from thermal oven categories.
- Toaster Ovens:Compact radiant heating platforms target residential countertop installations with lower electrical draw requirements. Residential exemptions from commercial DOE standby power rules narrow design constraints.
Convection ovens sit at the top of the volume ranking, with steam ovens climbing the fastest.
End User:
Capital deployment intensity and replacement cycle compression create divergent demand profiles across user categories, with commercial operators absorbing equipment at triple the per-unit wattage of residential installations.
- Restaurants:High-volume chains in Texas and California are compressing replacement cycles from seven to four years as labor scarcity forces kitchen automation investments. These operators prioritize hybrid platforms that consolidate steaming, convection, and microwave modalities into single footprints to reduce equipment counts and training burden.
- Households:Built-in residential channels in premium housing markets favor cabinetry-integrated designs with permanent electrical connections. Whirlpool Corporation leverages distribution depth to anchor positions in this segment through contractor relationships and home builder specifications.
- Catering Services:Mobile and event-based operations demand portable configurations with rapid setup protocols. Steam-convergence technology enables faster protein cook times without moisture loss, appealing to high-volume catering operations serving compressed service windows.
- Bakeries:Precision humidity and temperature control requirements drive specification toward steam-convection hybrids. Middleby Corporation extends its portfolio breadth across this segment through manufacturing scale and specialized deck configurations.
Restaurants command the largest installed base, while catering services are expanding most quickly as event volume rebounds.
Technology:
Connectivity module integration is reshaping warranty structures and service revenue models, with smart platforms requiring distinct FCC certification pathways for IoT radio emissions.
- Smart Ovens:IoT-enabled units with embedded sensors and cloud connectivity support remote diagnostics, recipe automation, and predictive maintenance algorithms. Rational specializes in precision steam-convection systems with fleet management capabilities for commercial kitchen networks. These platforms create recurring revenue streams through subscription-based monitoring tools.
- Hybrid Ovens:Multi-modal systems combining convection, steam, and microwave heating within single cavities maximize output versatility per square foot. Cloud kitchen operators in secondary metros adopt compact versions to maximize leased space productivity. DOE integrated efficiency metrics favor these designs in rebate eligibility calculations.
- Conventional Ovens:Single-modality thermal platforms without connectivity modules face narrowing residential exemptions as standby power regulations tighten. These units avoid FCC certification burdens but sacrifice remote monitoring capabilities.
- Induction Ovens:High-frequency magnetic field heating delivers rapid temperature response with minimal thermal mass. Supply concentration in domestic high-frequency power electronics creates vulnerability to semiconductor foundry allocation decisions, lengthening lead times for 15,000-watt commercial units.
Conventional ovens retain the deepest installed base, though smart ovens are gaining share fastest through connectivity-enabled service contracts.
Installation Type:
Electrical infrastructure requirements stratify procurement decisions, with built-in and under-counter configurations demanding 240V connections that trigger expensive retrofit costs in legacy buildings.
- Built-in Ovens:Permanent cabinetry integration with dedicated electrical circuits commands premium positioning in residential new construction and full-gut commercial renovations. These installations require professional electrical work and health department plan review in commercial applications, extending project timelines.
- Countertop Ovens:Plug-and-play 120V configurations avoid electrical upgrade costs and health department permitting burdens. Ghost kitchen operators in secondary metros favor these units for rapid deployment in leased spaces with minimal landlord coordination.
- Freestanding Ovens:Mobile configurations on casters support flexible kitchen layouts and equipment relocation. These units bypass permanent installation permitting but sacrifice integrated ventilation and plumbing connections.
- Under-Counter Ovens:Space-efficient designs fit beneath work surfaces to maximize vertical kitchen utilization. ADA compliance requirements and clearance specifications add design constraints distinct from countertop alternatives.
Built-in ovens lead value concentration, while countertop configurations are expanding most quickly among cloud kitchen operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in this market, as DOE efficiency standards and FDA sanitation protocols apply uniformly across state lines. Equipment procurement instead concentrates where commercial kitchen construction permits and electrical infrastructure investments align with chain expansion timelines.
Texas
High-volume restaurant chains in Dallas-Fort Worth and Houston are compressing equipment replacement cycles from seven to four years. Texas health department alignment with FDA Food Code streamlines multi-unit rollout compliance. Permitting velocity in these metros outpaces national averages, pulling built-in installation demand forward.
California
Steam-convection hybrid adoption accelerates in Los Angeles and San Francisco Bay Area catering operations seeking protein yield consistency. State-level efficiency incentive programs reward ENERGY STAR certification with utility rebates. Urban kitchen retrofits favor reduced grease vapor generation to simplify hood ventilation compliance.
Florida
Ghost kitchen operators in Miami and Orlando are deploying compact countertop configurations to maximize leased space productivity. Electrical infrastructure limitations in older strip malls constrain 15,000-watt three-phase installations. Private-equity-backed restaurant rollups in the Southeast are standardizing equipment specifications across acquired brands.
Illinois
Chicago's catering corridor demands portable steam-convection units for rapid event setup protocols. City health department plan review requirements extend timelines for permanent commercial installations. Distribution networks anchored here serve mid-continent chain expansion with consolidated vendor relationships.
New York
Manhattan and Brooklyn cloud kitchens adopt under-counter designs to maximize vertical utilization in constrained real estate. ADA compliance specifications add design constraints distinct from countertop alternatives. Secondary metro ghost kitchen penetration in upstate cities follows the compact equipment template established in primary markets.
United States Multi-Functional Oven Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with residential channels favoring established appliance brands and commercial foodservice tilting toward specialized kitchen equipment fabricators. The market exhibits moderate consolidation at the top tier, with three to four holding companies controlling broad portfolio umbrellas while mid-scale specialists defend niche positions. Strategic archetypes include full-line appliance conglomerates, precision cooking technology specialists, and foodservice equipment holding companies. Competitive moves center on portfolio diversification through manufacturing scale expansion and distribution depth consolidation.
Within the precision cooking tier, Rational exemplifies technology-forward positioning through its steam-convection specialization. Whirlpool Corporation anchors residential channel presence through contractor relationships and home builder specifications. Middleby Corporation occupies a position as a foodservice equipment holding company with manufacturing scale across catering and bakery segments. These three entities represent distinct strategic archetypes rather than direct substitutes, each defending share through channel-specific distribution advantages.
| Leading Market Players |
|---|
| Frigidaire |
| Siemens |
| Whirlpool Corporation |
| Rational |
| Middleby Corporation |
| GE Appliances |
| Asko Appliances |
| Alto-Shaam Inc. |
| Bosch |
| Others |
Value Network & Pricing Analysis
ENERGY STAR certification gates both qualified supply and premium-tier pricing access in the United States Multi-Functional Oven Market. DOE efficiency standards tighten test procedure requirements for cooking products, forcing manufacturers to redesign platforms to maintain eligibility for utility rebate programs that offset equipment costs.
Pricing Analysis
Distributor margin compression reshapes channel economics as buying committees consolidate vendor relationships around single-source kitchen platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by ENERGY STAR certification status and installation complexity, with built-in configurations commanding substantial premiums over countertop alternatives. Pricing pressure stems from electrical infrastructure retrofit costs for 15,000-watt commercial units, forcing expensive upgrades in legacy buildings. Regional restaurant groups exhibit highest price sensitivity due to capital allocation constraints, while private-equity-backed rollups absorb premium pricing for standardized fleet specifications.
Supply Chain Analysis
High-frequency power electronics supply rests on semiconductor foundries concentrated in Taiwan, South Korea, and China. Magnetron assemblies, precision humidity sensors, and IoT connectivity modules feed from Asian component clusters with limited domestic alternatives. Single-source vulnerability in induction componentry creates exposure to foundry allocation decisions and tariff exposure on imported power electronics. Distribution runs through foodservice equipment distributors losing access to procurement decisions as chain buyers consolidate direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Multi-Functional Oven Market functions as a regulatory compounder where DOE standby power rulemakings force redesign cycles ahead of compliance deadlines, accelerating replacement demand across commercial and residential channels.
For Market Incumbents: Deepen backward integration into high-frequency power electronics to reduce exposure to semiconductor foundry allocation volatility. Anchor positions in steam-convection convergence technology as QSR chains prioritize protein yield consistency, while consolidating distribution depth to defend against direct manufacturer relationships that bypass traditional channels. For New Entrants and Emerging Players: Begin with cloud kitchen operators in secondary metros seeking compact countertop configurations for rapid leased-space deployment. Target catering services expanding most quickly as event volume rebounds, offering portable steam-convection units with rapid setup protocols. Pursue ENERGY STAR certification early to unlock utility rebate capture as a go-to-market wedge against established competitors. For Investors and Strategic Acquirers: Roll-up economics work for precision cooking technology specialists because FDA Food Code variations across state health departments create compliance documentation burdens that favor consolidated vendor relationships. Five-to-ten-year viability hinges on IoT-enabled fleet management capabilities generating recurring revenue streams. Watch DOE rulemaking velocity on standby power and active mode efficiency as the inflection indicator forcing accelerated replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Steam-Convection Technology Convergence | QSR chains like Chili's retrofit line kitchens to reduce ticket times during peak hours. |
| IoT Connectivity Platform Development | Rational embeds predictive maintenance algorithms creating subscription-based fleet management revenue. |
| ENERGY STAR Certification Investment | Utility rebate eligibility offsets premium pricing for efficiency-optimized models in California. |
| Electrical Infrastructure Partnership | Collaboration with contractors reduces retrofit cost barriers for 15,000-watt commercial installations. |
| Cloud Kitchen Distribution Expansion | Compact multi-functional units maximize output per square foot in Miami and Orlando ghost kitchens. |
Research Methodology
Multiple input streams — equipment manufacturer production data, commercial kitchen construction permit filings, and utility rebate program records — were reconciled with primary interviews across restaurant chain procurement directors, foodservice equipment distributors, and electrical contractor networks. Secondary validation drew from DOE rulemaking dockets, FDA Food Code state adoption matrices, ENERGY STAR certified product listings, and commercial real estate permit databases. Bottom-up unit shipment estimates and top-down market value reconstructions were triangulated against manufacturer revenue disclosures.
Data-stream reconciliation anchored analytical framework development across the projection horizon. Segmentation dimensions modeled include heating modality, end-use intensity, installation type, and technology tier. CAGRs were derived from fitted growth curves applied to permit-velocity trends and replacement cycle compression patterns. Forecast inputs incorporated DOE compliance deadline schedules and state-level efficiency incentive program budgets.
Caveats apply where DOE rulemaking delays or electrical infrastructure retrofit cost volatility could materially shift the outlook. Forecasts reflect assumptions about chain expansion timelines and semiconductor supply normalization. A small set of named triggers — standby power regulation finalization, foundry allocation shocks, and health department code harmonization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Glass Ceramic Cooktop Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
UAE Gas Hobs Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Germany Consumer Appliances Market
Appliances
India Washing Machine Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Smart Microwave Oven Market
Appliances
Commercial Microwave Ovens Market
Appliances
Oman Microwave Ovens Market
Appliances
Global Electric Water Heaters Market
Appliances
Cooker Hoods Market
Appliances
Refrigerator Repair Service Market
Appliances
Japan Laundry Appliances Market
Appliances
Refrigerated Cabinet Market
Appliances
UAE Dishwasher Market