
 US Electric Rice Cooker Market | 2026-2036
US Electric Rice Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Rice Cooker Market Insights
Premium induction heating tier is bifurcating the US electric rice cooker landscape into performance-focused and value-focused buyer pools. Zojirushi America Corporation leverages its Japanese engineering heritage to dominate the high-end induction segment with microcomputer-controlled models. Tiger Corporation anchors its position through specialized thermal sensor technology that sustains repeat purchases among culinary enthusiasts. Panasonic Holdings Corporation competes across multiple price bands with a manufacturing scale that extends its retail shelf presence nationwide.
US electric rice cookers are countertop appliances employing resistive or electromagnetic induction heating elements, typically operating between 500-1,350 watts, designed to automate rice preparation through thermostatic or fuzzy logic control systems. The multi-cooker segment leads volume sales by consolidating rice cooking with pressure cooking and slow cooking functions that reduce single-purpose appliance clutter in American kitchens. Fuzzy logic technology commands the highest margin pools by using microprocessors to adjust temperature curves dynamically, while standard rice cookers remain the mature, price-sensitive baseline. Capacity segmentation tilts toward 3-5 cup and 6-8 cup models that match average US household sizes.
Department of Energy appliance efficiency regulations and FCC electromagnetic emissions standards shape product development cycles and market access requirements for electric rice cookers sold in the United States. Underwriters Laboratories (UL) safety certification operates as a de facto gatekeeper for retail distribution, with major retailers requiring UL listing before shelf placement. California Title 20 appliance efficiency rules create additional compliance layers that manufacturers must navigate for access to the country's largest state market. Stakeholders should monitor how evolving federal efficiency mandates and state-level energy programs reshape the cost structure of induction versus traditional heating platforms.
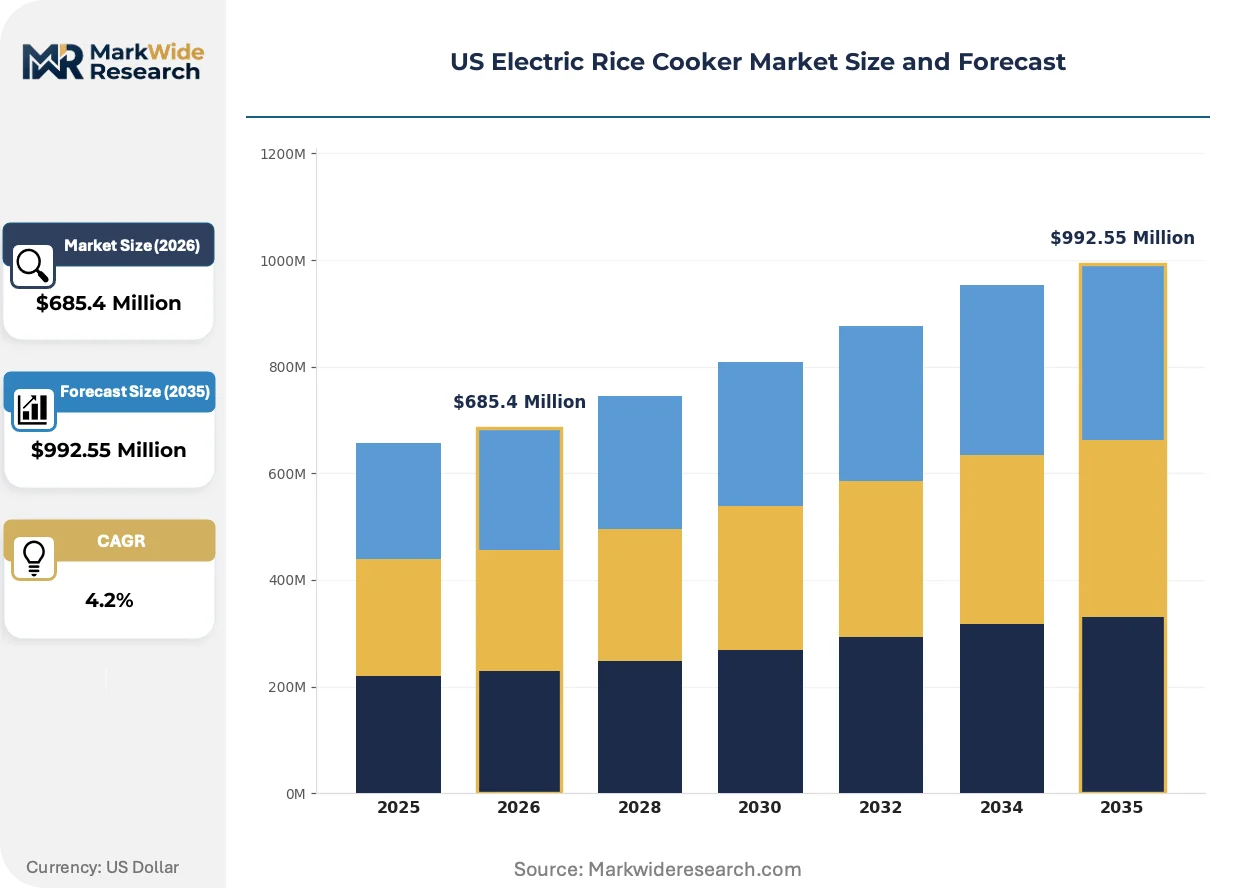
Market Dynamics
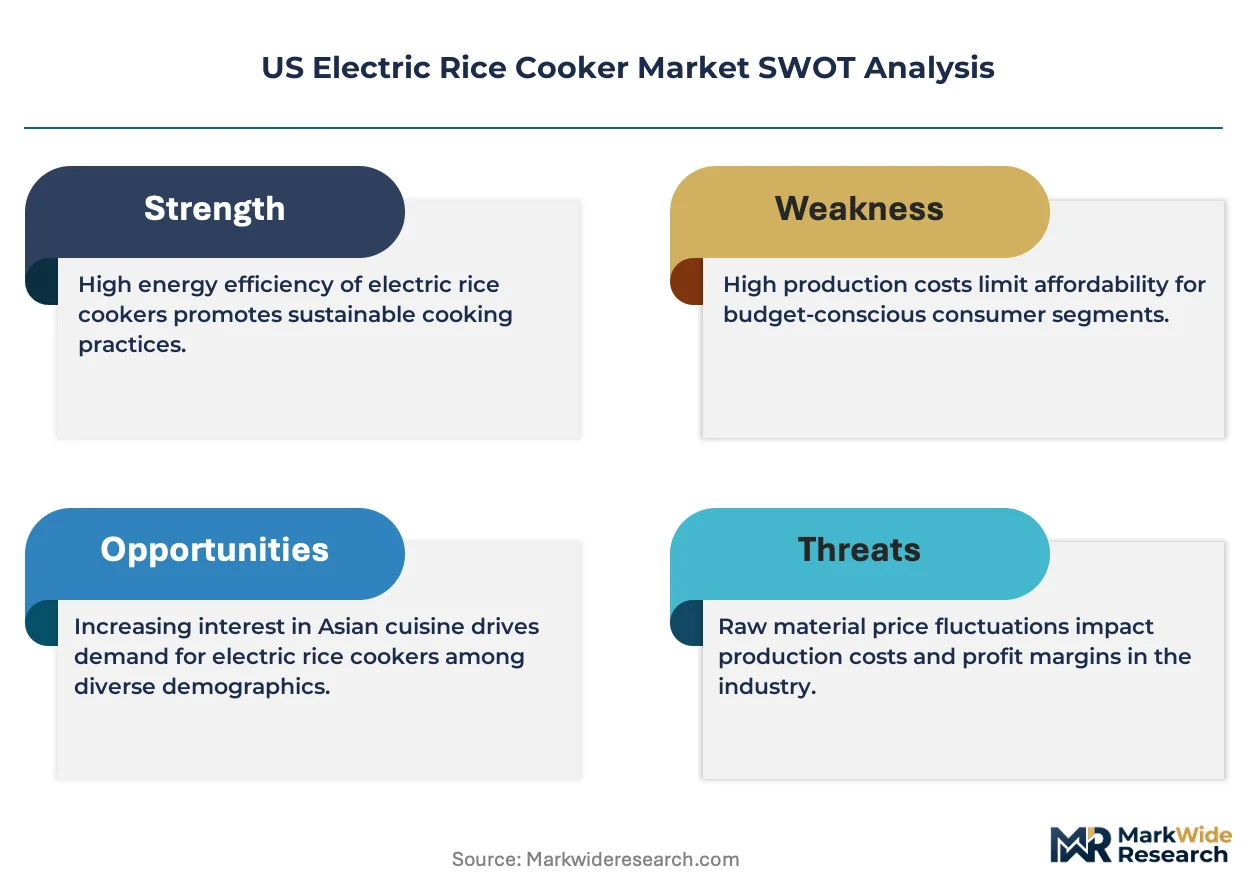
Department of Energy efficiency mandates are compressing margins on traditional resistive heating platforms while elevating induction heating architectures to compliance necessity status across the US market.
Growth Catalysts
- Appliance efficiency standards:DOE regulations are accelerating manufacturer R&D investment in induction heating platforms that exceed baseline energy performance thresholds.
- College dormitories:Campus housing expansion programs in Texas and California are generating concentrated demand for compact multi-function cooking appliances.
- Fuzzy logic microprocessors:Dynamic temperature curve adjustment technology commands premium positioning among culinary enthusiasts seeking precision rice preparation.
Market Restraints
- Copper coil cost volatility:Induction heating component input prices fluctuate with commodity markets, compressing gross margins on mid-tier product lines.
- California Title 20 compliance:State-level efficiency rules create fragmented certification requirements that add fixed cost burden for national distribution.
- Multi-cooker substitution:Pressure cooking and slow cooking consolidation in single appliances threatens dedicated rice cooker volume in space-constrained kitchens.
Strategic Opportunities
- Small apartment households:Urban density trends in New York and California metros create white space for 3-cup capacity models with smart home integration.
- FCC emissions certification:WiFi-enabled rice cookers with app control represent an emerging premium tier requiring electromagnetic compliance investment.
- Asian-American population corridors:Demographic concentration in Texas metro areas supports specialized retail distribution and community-targeted marketing.
Industry Challenges
- UL safety certification timelines:Underwriters Laboratories listing requirements create 4-6 month product launch delays that compress selling seasons.
- Embedded systems engineering talent:Fuzzy logic algorithm development requires scarce firmware expertise that concentrates in consumer electronics hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Rice Cooker Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Cooker, Pressure Cooker, Steam Cooker, Standard Rice Cooker End User: Households, Restaurants, Cafeterias, Institutions Capacity: 1-2 Cups, 3-5 Cups, 6-8 Cups, 10+ Cups Technology: Induction Heating, Traditional Heating, Fuzzy Logic, Programmable |
| Companies Covered | Panasonic Holdings Corporation, Zojirushi America Corporation, Tiger Corporation, Cuckoo Electronics Co., Ltd., Aroma Housewares, Hamilton Beach Brands, Inc., Midea America Corp., Black+Decker Inc., Town Food Service Equipment Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Rice Cooker Market Trends and Innovations
Induction heating platforms are splitting the US electric rice cooker market into performance-tier and value-tier buyer pools with divergent feature expectations and price elasticity profiles.
Electromagnetic induction heating is replacing resistive coil elements in premium US electric rice cooker designs by generating precise, uniform thermal distribution through copper coil magnetic field generation. Culinary enthusiasts and Asian-American households with heritage cooking practices are adopting these models despite 40-60% price premiums over standard platforms. This technology is bifurcating the competitive landscape into engineering-intensive premium specialists and cost-optimized volume manufacturers with limited feature differentiation.
California Title 20 appliance efficiency regulations are mandating standby power consumption limits and active mode energy metrics that exceed federal DOE baselines for electric rice cookers sold in the state. Manufacturers must maintain dual SKU inventories or redesign platforms to meet the strictest standard, raising compliance costs for nationwide retail distribution. Induction heating product lines gain relative advantage under these rules while traditional resistive models face margin compression or market exit in the country's largest state economy.
Smart home integration is reshaping buyer expectations as WiFi-connected rice cookers with app-based recipe libraries and remote start functionality penetrate premium and mid-tier segments. Amazon and direct-to-consumer channels are displacing traditional brick-and-mortar appliance retail for these connected models, altering manufacturer go-to-market economics and warranty service structures. California and New York urban households demonstrate highest adoption velocity for app-controlled kitchen appliances with voice assistant compatibility.
US Electric Rice Cooker Market Segmentation
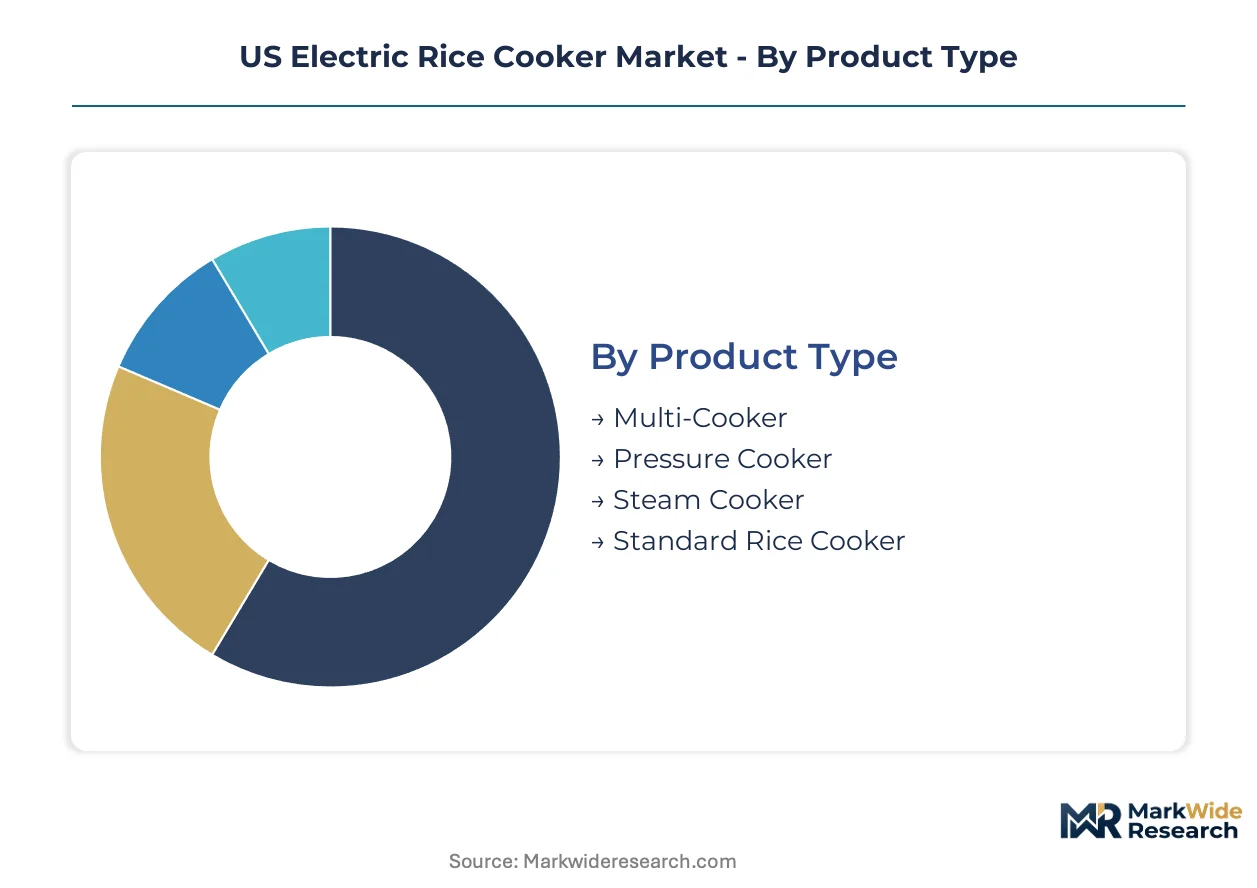
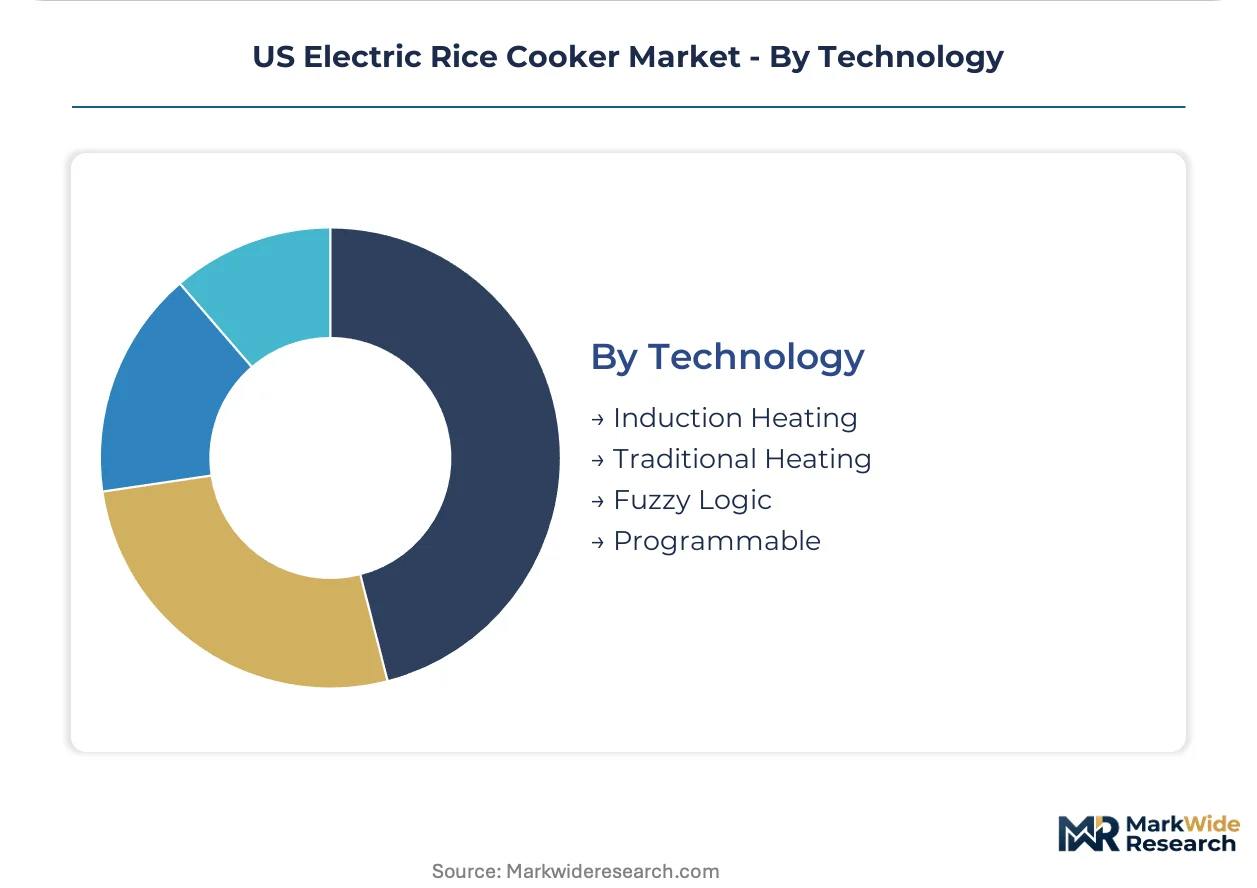
US electric rice cooker segmentation reveals concentrated margin pools in premium heating technologies and multi-function configurations. Manufacturers optimize SKU portfolios across four intersecting dimensions that reshape channel economics and warranty service requirements.
Product Type:
Margin pools concentrate in multi-function appliances that consolidate single-purpose devices into premium-priced kitchen centerpieces.
- Multi-Cooker:Combines rice cooking with pressure cooking, slow cooking, and sauté functions through modular heating algorithms. Demand clusters in California and New York metro apartments where countertop space constraints drive consolidation preferences.
- Pressure Cooker:Sealed-vessel designs accelerate rice preparation through elevated boiling points while reducing energy consumption. Texas college dormitories and small apartment households represent the fastest-expanding buyer segment for compact pressure-capable models.
- Steam Cooker:Dedicated steaming chambers preserve nutrient profiles in specialty rice varieties.
- Standard Rice Cooker:Single-function resistive heating platforms dominate mass retail channels with price-sensitive positioning.
Multi-cooker holds installed capacity. Pressure cooker is rotating up the share rankings.
End User:
Application concentration determines service infrastructure investments and warranty claim patterns across the value chain.
- Households:Residential buyers drive volume through 3-5 cup and 6-8 cup configurations matching average US family sizes. Asian-American population corridors in California, Texas, and New York generate disproportionate demand for induction heating and fuzzy logic precision.
- Restaurants:Commercial kitchens require 10+ cup capacities with rapid cycle times and NSF sanitation certification. High-throughput operations in urban ethnic restaurant clusters sustain replacement demand for durable heating elements.
- Cafeterias:Institutional feeding operations demand batch-capacity models with simplified controls.
- Institutions:University housing and corporate dining facilities specify commercial-grade durability standards.
Households anchor volume throughput. Restaurants command the steepest expansion trajectory in absolute dollar terms.
Capacity:
SKU proliferation economics favor mid-range capacities that minimize inventory carrying costs while maximizing addressable demand.
- 3-5 Cups:Matches nuclear family meal preparation requirements with compact footprint suitability for apartment kitchens. California and New York urban density trends sustain premium pricing power for this segment.
- 6-8 Cups:Accommodates multi-generational households and batch cooking practices prevalent in Asian-American communities. Texas metro areas with expanding immigrant populations drive above-average growth.
- 1-2 Cups:Targets single-person households and secondary kitchen installations.
- 10+ Cups:Serves commercial and institutional batch preparation requirements.
3-5 cups maintains shelf dominance. 6-8 cups is gaining share fastest among new product introductions.
Technology:
Heating platform selection determines compliance positioning against DOE efficiency mandates and California Title 20 thresholds.
- Induction Heating:Electromagnetic copper coil systems generate precise thermal distribution through magnetic field induction. Culinary enthusiasts accept 40-60% price premiums for uniform heating performance that exceeds federal efficiency baselines.
- Fuzzy Logic:Microprocessor-controlled temperature curve adjustment commands the highest margin pools through dynamic cooking phase optimization. Premium positioning targets heritage cooking practitioners seeking precise texture control.
- Traditional Heating:Resistive coil elements face margin compression under tightening efficiency regulations.
- Programmable:Timer-based delayed start functionality adds convenience features without heating platform upgrades.
Induction heating holds technology leadership. Fuzzy logic is climbing the fastest in revenue per unit metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese engineering houses export precision heating platforms to California and Texas distribution hubs, where Asian-American population density sustains premium-tier demand for induction-equipped models.
California
Urban apartment density in Los Angeles and San Francisco drives compact multi-cooker adoption among space-constrained households. Title 20 appliance efficiency rules mandate standby power limits that favor induction heating architectures over resistive coil designs. Silicon Valley tech workers accelerate smart home integration demand for WiFi-enabled models with app-based recipe libraries.
Texas
Campus housing expansion across Austin and Houston college districts generates concentrated demand for 3-5 cup capacity units with pressure cooking functions. Federal DOE efficiency baselines apply statewide, though Texas lacks California's supplemental efficiency layers. Dallas-Fort Worth metro Asian-American community growth supports specialized retail distribution for heritage cooking practitioners.
New York
Manhattan and Brooklyn small apartment households prioritize countertop consolidation, elevating multi-function appliances over single-purpose rice cookers. FCC electromagnetic emissions standards govern WiFi-connected model certification for smart home ecosystems. Queens and northern New Jersey Asian-American corridors sustain above-average induction heating penetration.
Illinois
Chicago metro nuclear family configurations anchor 6-8 cup capacity segment volume through Midwest retail channels. DOE appliance efficiency regulations shape product availability without state-level supplementation. Suburban Asian-American population clusters in Schaumburg and Naperville drive fuzzy logic technology adoption for precision texture control.
Washington
Seattle tech sector households demonstrate early smart home appliance adoption, including voice assistant-compatible rice cookers with remote start functionality. Washington State energy codes align with federal DOE baselines, avoiding California's compliance fragmentation. Bellevue and Redmond Asian-American professional communities sustain premium-tier demand for Japanese-engineered induction models.
US Electric Rice Cooker Market Competitive Landscape
Listed leaders compete with private specialists across heating technology tiers, creating a bifurcated structure where engineering-intensive premium platforms coexist with cost-optimized volume manufacturing. Publicly traded appliance conglomerates leverage manufacturing scale for nationwide retail shelf presence, while private specialists concentrate on heritage cooking practitioners and culinary enthusiasts. Three archetypes dominate: Japanese engineering specialists, diversified Asian appliance conglomerates, and North American mass-market brands. Competitive moves center on induction heating R&D investment and smart home integration partnerships.
Within the Japanese engineering tier, Zojirushi America Corporation and Tiger Corporation exemplify heritage-driven positioning that commands sustained price premiums. Panasonic Holdings Corporation anchors the diversified conglomerate archetype with cross-category manufacturing scale. Cuckoo Electronics Co., Ltd. represents the Korean specialist model competing on pressure cooking integration.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Zojirushi America Corporation |
| Tiger Corporation |
| Cuckoo Electronics Co., Ltd. |
| Aroma Housewares |
| Hamilton Beach Brands, Inc. |
| Midea America Corp. |
| Black+Decker Inc. |
| Town Food Service Equipment Co., Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with Japanese and Korean component suppliers lock in copper coil access and cost visibility for US-bound induction heating platforms. These contractual structures insulate premium-tier manufacturers from commodity volatility while compressing margins for spot-market-dependent value-tier producers.
Pricing Analysis
Current-generation induction heating models command 40-60% premiums over prior-generation resistive coil platforms, while next-generation WiFi-enabled fuzzy logic units are establishing a super-premium tier above both. Three-tier pricing structure across premium, standard, and economy levels separates Japanese-engineered induction systems from mid-market programmable units and mass-market basic cookers. Price differentiation rests on UL safety certification tier and heating platform efficiency grade. Cost compression in the resistive heating tier is intensifying because DOE efficiency mandates accelerate platform obsolescence. College dormitory buyers exhibit highest price sensitivity, while culinary enthusiasts in Asian-American households demonstrate lowest elasticity.
Supply Chain Analysis
Japan and South Korea anchor precision heating component fabrication, while China dominates resistive element and plastic housing production. Copper coil windings, microprocessor controllers, and thermal sensor assemblies draw from East Asian manufacturing clusters. Single-source vulnerability concentrates in advanced induction coil suppliers serving Zojirushi and Tiger production lines. Distribution runs through big-box retail partnerships, Amazon marketplace direct-to-consumer channels, and specialty Asian grocery retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US electric rice cooker market sits in early-cycle expansion as smart home integration and induction heating adoption accelerate penetration beyond heritage cooking households into mainstream apartment and dormitory segments.
For Market Incumbents: Shield premium positioning by accelerating FCC certification timelines for WiFi-enabled models before multi-cooker substitution erodes dedicated rice cooker shelf space. Deepen backward integration into microprocessor firmware development to reduce dependency on scarce embedded systems engineering talent. Prioritize UL pre-certification investments to compress 4-6 month listing delays that truncate selling seasons.
For New Entrants and Emerging Players: Differentiate on compact 3-cup capacity smart home integration for New York and California urban apartments where space constraints and tech-sector incomes overlap. Target Texas college dormitory procurement channels with pressure-cooking multi-function units. Pursue direct-to-Amazon launch strategies to bypass traditional retail slotting fee barriers.
For Investors and Strategic Acquirers: Korean pressure-cooking specialists with established US distribution infrastructure represent the most attractive acquisition archetype for platform consolidation plays. Long-term viability hinges on induction heating technology ownership and smart home ecosystem partnerships. Watch for DOE efficiency mandate acceleration as the critical inflection signal that would force resistive-platform exits and reshape competitive tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Induction Heating R&D Investment | Positions manufacturers ahead of DOE efficiency compliance thresholds that will obsolete resistive platforms. |
| Smart Home Ecosystem Partnership | Unlocks Amazon and direct-to-consumer channel access for WiFi-enabled premium tier expansion. |
| UL Pre-Certification Program | Compresses 4-6 month safety listing timelines that currently delay product launches past peak selling seasons. |
| Compact Capacity SKU Development | Captures New York and California urban apartment demand where countertop space constraints dominate purchase decisions. |
| Texas Distribution Infrastructure | Establishes presence in fastest-expanding college dormitory and Asian-American demographic corridor. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with appliance engineering directors, retail category buyers, and regulatory compliance officers; and secondary validation against DOE appliance standards filings, FCC equipment authorization databases, and UL certification records. The research triangulated bottom-up SKU-level demand modeling with top-down household penetration benchmarks across the analysis window.
The projection horizon spans the full forecast period with segmentation across heating technology tier, capacity configuration, end-use application, and regional state cluster. CAGRs were derived from installed base replacement cycles, demographic penetration curves, and efficiency mandate compliance timelines. Fuzzy logic adoption velocity and induction heating cost curves served as industry-specific demand shapers.
The analysis sits within stated boundaries; outcomes outside current DOE regulatory trajectory or copper commodity price bands would require recalibration. Forecasts embed assumptions around Title 20 compliance continuity and smart home integration adoption curves. Recalibration cycles align with material shifts in federal efficiency mandates and copper coil input pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Saudi Arabia Dishwasher Market
Appliances
Saudi Arabia Water Heater Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Electric Ranges Market
Appliances
Global Home Ice Maker Market
Appliances
Household Vacuum Cleaners Market
Appliances
Asia Pacific Water Heater Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Under Counter Dishwasher Market
Appliances
Induction Cooktops Market
Appliances
China Induction Hobs Market
Appliances
Laundry Kiosk Market
Appliances
Bahrain Dishwashers Market
Appliances
Electric Iron Market
Appliances
Europe Induction Hobs Market
Appliances
Large Cooking Appliance Market