
 Automatic Dishwasher Market | 2026-2036
Automatic Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Dishwasher Market Outlook
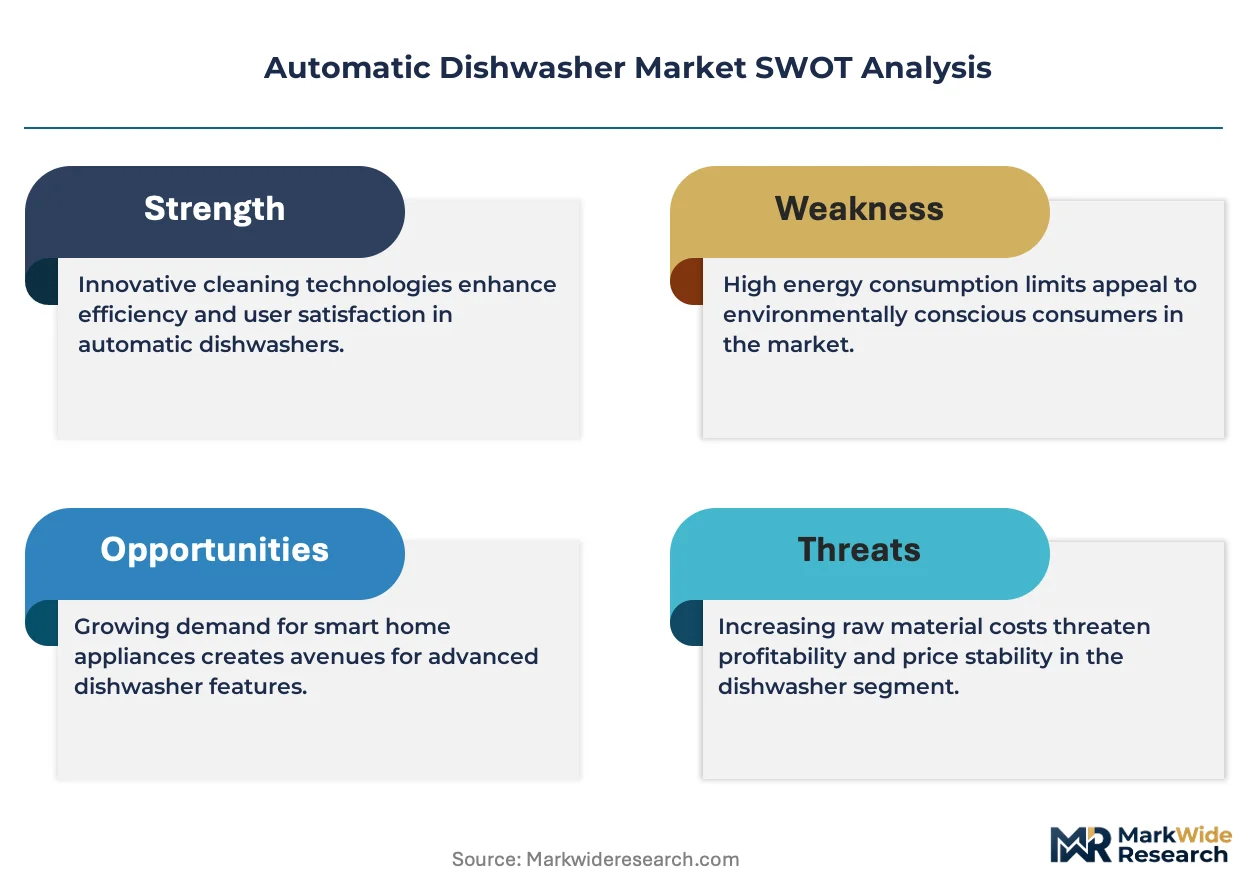
The capital-intensity divergence between in-house motor production and outsourced assembly is unwinding competitive dynamics among established appliance manufacturers. Bosch leverages its captive supply of European-built circulation pumps to sustain margin control across premium built-in lines. Miele differentiates through extended-cycle engineering and stainless-steel tub construction, anchoring its position in the luxury price tier. Whirlpool competes on manufacturing scale, operating multi-brand distribution that spans budget through mid-range channels in North America.
An automatic dishwasher is a plumbed appliance that sprays heated water and detergent across dishware racks using rotating wash arms, then drains and dries loads through resistive heating or condensation methods; typical units operate at water temperatures between 45°C and 75°C and consume 6–15 liters per cycle depending on efficiency class. The primary commercial purpose is to sanitize tableware and cookware at scale while reducing manual labor and water usage relative to hand washing. Built-in models dominate residential new construction and kitchen renovation flows, while portable and compact variants serve rental markets and urban dwellings with spatial constraints. Energy Star and high-efficiency classifications command price premiums and increasingly determine retail placement, particularly in regions with tiered utility rebate programs.
EPA Energy Star certification and EU Ecodesign requirements constrain allowable water and energy consumption per cycle, directly influencing pump design, heating element specification, and control board programming across manufacturers. The EU F-Gas Regulation and REACH chemical restrictions further shape detergent formulation and drying system choices for products sold in European markets. Stakeholders must monitor evolving efficiency benchmarks and utility incentive structures to align product roadmaps with jurisdiction-specific compliance thresholds.
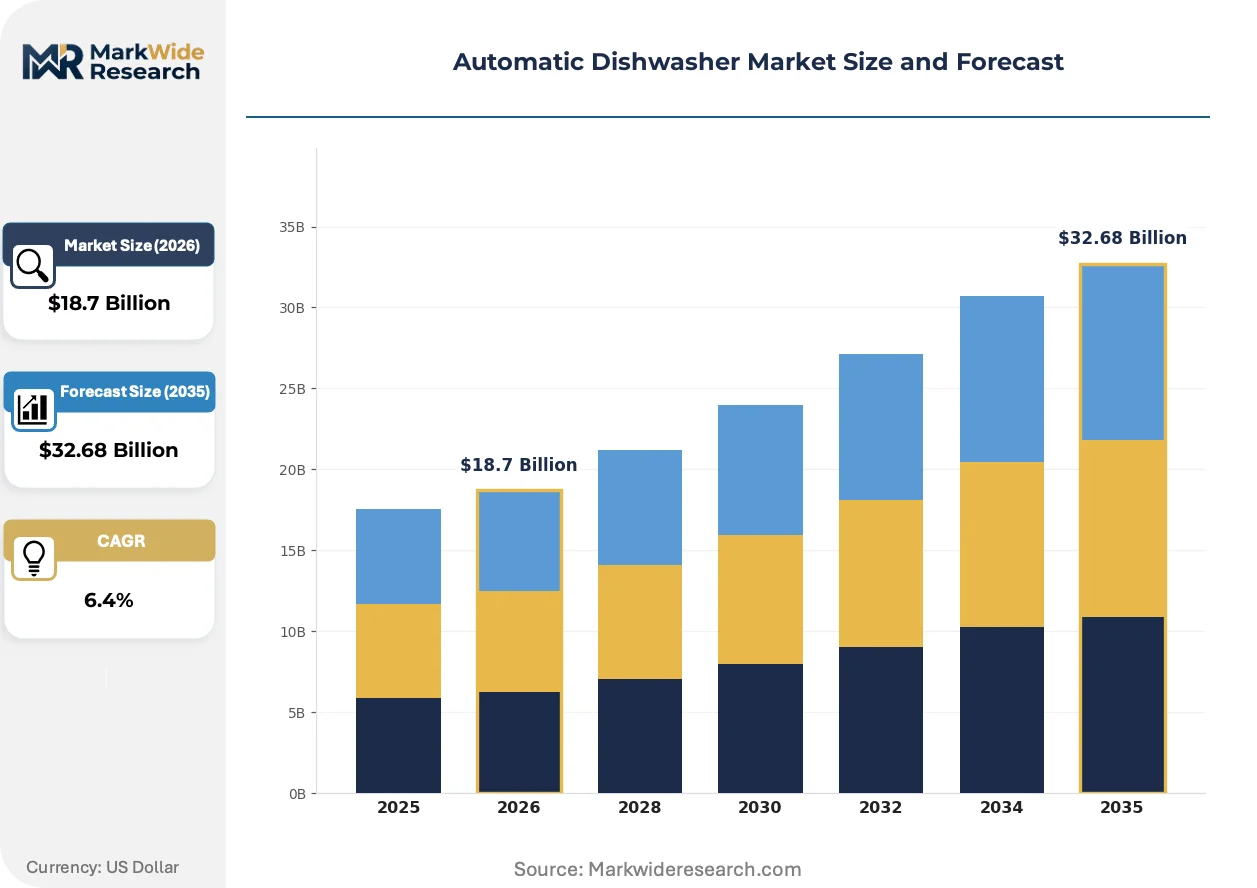
Market Dynamics
Water-efficiency mandates from EPA Energy Star and EU Ecodesign are compressing allowable consumption thresholds per cycle, forcing recalibration of pump engineering, heating element sizing, and control firmware across the supply base. This regulatory tightening is the dominant structural force reshaping competitive positioning and manufacturing economics.
Growth Catalysts
- Commercial kitchen labor inflation:Hospitality chains in the United States and Germany are accelerating dishwasher procurement to offset wage pressure and reduce manual dishwashing headcount.
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon refrigerants is driving demand for condensation-drying systems that eliminate heat-pump dependency in European markets.
- Heat pump circulation technology:Advanced pump designs that recover waste heat are enabling sub-10-liter cycles while maintaining sanitization temperatures required by health codes.
Market Restraints
- Stainless steel input volatility:Tub and rack fabrication depends on nickel-alloy sheet pricing, which fluctuates with Indonesian and Philippine ore export policies.
- Pump motor supply concentration:High-efficiency brushless DC motor production clusters in China and Germany, creating single-source vulnerability for mid-tier assemblers.
- REACH chemical restrictions:Detergent enzyme and surfactant formulations face recurring reauthorization cycles that delay product launches in European markets.
Strategic Opportunities
- Indian urban kitchen retrofit:Compact countertop units targeting Mumbai and Bangalore apartment dwellers remain underpenetrated relative to washing machine ownership rates.
- Utility rebate stacking:Tiered incentive programs in California and New York reward simultaneous Energy Star and WaterSense certification with accelerated payback periods.
- Sensor-driven load optimization:Integration of turbidity and soil-level sensors with cloud-connected diagnostics enables usage-based service contracting for commercial operators.
Industry Challenges
- Embedded systems firmware talent:Control board programming for variable-speed pumps and adaptive heating cycles requires scarce expertise in motor control algorithms and thermal modeling.
- Cross-border certification timelines:Simultaneous EPA WaterSense and EU Ecodesign validation extends development cycles by 8-14 months for multi-region product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Dishwasher Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Portable, Drawer, Compact End User: Residential, Commercial, Institutional, Hospitality Energy Efficiency: Standard, Energy Star, High-Efficiency, Eco-Friendly Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | LG, Thermador, Bosch, Midea, Whirlpool, Miele, GE, Frigidaire, KitchenAid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Dishwasher Market Strategic Shifts
Smart connectivity and adaptive wash algorithms are redefining how manufacturers differentiate beyond water and energy efficiency metrics. The competitive frontier is shifting toward predictive maintenance and usage-pattern optimization.
Ultrasonic soil detection is decomposing the traditional fixed-cycle paradigm by enabling real-time adjustment of spray intensity, duration, and temperature based on load-specific contamination levels. Commercial operators in Germany and the United States are piloting these systems to reduce rewash rates and detergent overuse. The technology is decomposing standardized cycle menus into dynamic, sensor-calibrated sequences that compress operating costs while extending hardware lifespan.
EU Ecodesign requirements for standby power consumption below 0.5 watts are forcing redesign of control board architecture and display systems. Manufacturers must eliminate always-on clock circuits and migrate to capacitive touch interfaces that activate only on proximity detection. Built-in premium lines sold across Germany, France, and Italy face the steepest compliance costs, with redesign cycles now synchronized to the regulation's 2027 enforcement window.
Buying patterns among North American hospitality chains are consolidating procurement through national equipment lessors rather than direct manufacturer relationships. These lessors bundle installation, maintenance, and detergent supply into single-source contracts, displacing traditional distributor networks. The shift is most visible in the United States, where REIT-owned hotel portfolios now specify lessor-managed dishwasher fleets as a condition of capital improvement approvals.
Automatic Dishwasher Market Segmentation
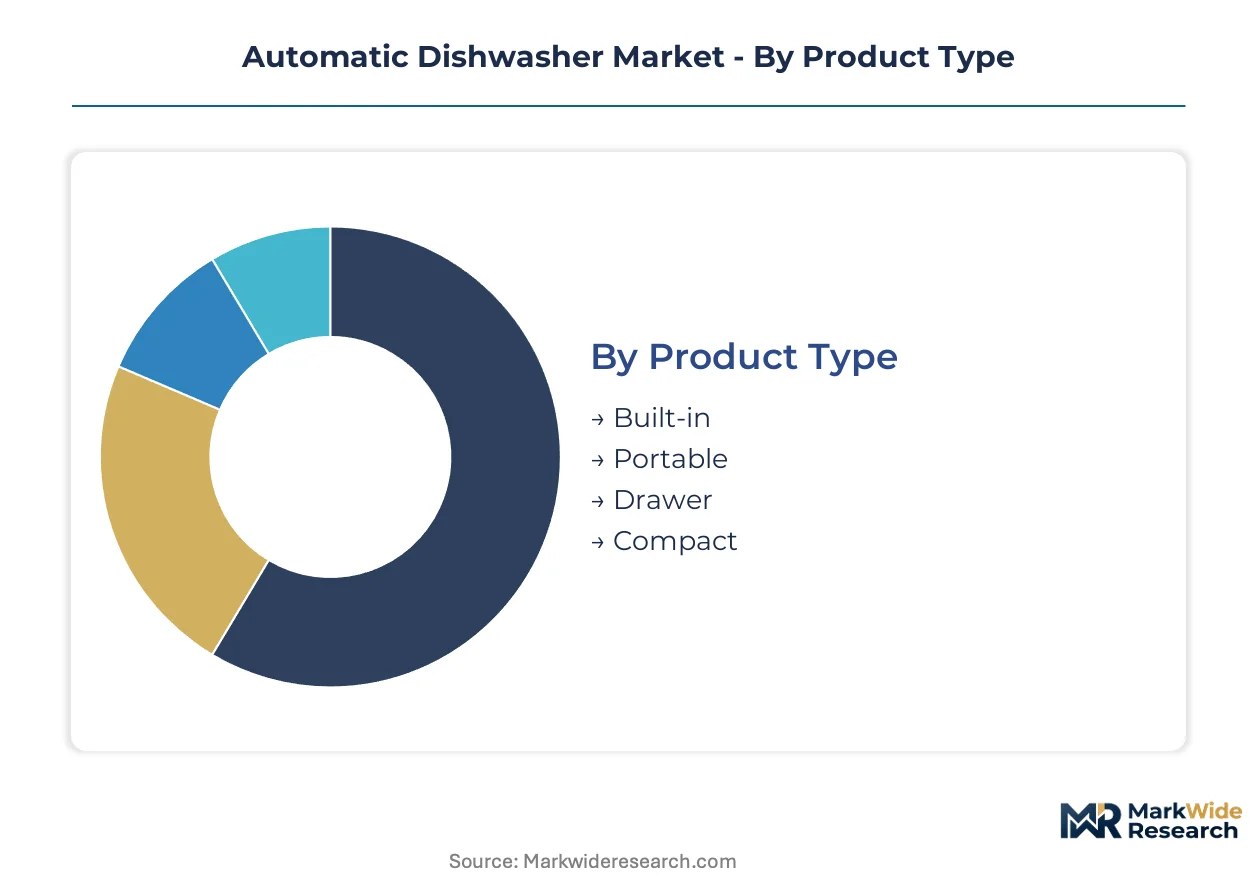
Segmentation in the automatic dishwasher market reveals how regulatory pressure and installation constraints fragment demand across distinct hardware configurations. Manufacturers calibrate pump engineering, tub dimensions, and control systems differently for each product category to match jurisdiction-specific efficiency mandates and end-use sanitation requirements.
Product Type:
Portable and compact variants face intensifying substitution pressure from countertop washing appliances and shared-service kitchen models in dense urban housing markets.
- Built-in:Permanent under-counter installation with integrated plumbing and hardwired electrical connections. Demand concentrates in Germany and the United States where kitchen renovation cycles and new residential construction sustain replacement volume. EPA Energy Star and EU Ecodesign compliance costs are absorbed most easily at this scale.
- Portable:Freestanding units with caster mobility and temporary faucet hookups. Adoption clusters in rental markets and urban apartments across the United States where permanent installation is restricted by lease terms. Water consumption penalties in California and New York utility districts compress margins on budget-tier models.
- Drawer:Dual-chamber vertical configuration enabling simultaneous or independent cycle operation. Space-efficient design targets premium kitchen retrofits in Japanese and Australian metropolitan markets.
- Compact:Reduced-capacity units typically 18 inches wide or countertop height. Growth corridors include Mumbai and Bangalore apartment conversions where washing machine ownership far exceeds dishwasher penetration.
Built-in retains volume leadership; compact holds the steepest expansion curve.
End User:
Cost tier differentiation separates procurement patterns across customer categories, with capital expenditure authority and operating cost accountability diverging sharply between residential and institutional buyers.
- Residential:Individual household purchase decisions driven by kitchen renovation timing and utility rebate eligibility. Installation concentrates in owner-occupied housing in Germany, the United States, and France where mortgage refinancing cycles unlock discretionary appliance spending.
- Commercial:Independent restaurants and catering operations purchasing through equipment lessors or distributor networks. Labor cost inflation in the United States and Germany is accelerating procurement to reduce manual dishwashing headcount.
- Institutional:Schools, hospitals, and government facilities with mandated competitive bidding and extended depreciation schedules. EU public procurement directives favor Ecodesign-compliant models with documented lifecycle cost analysis.
- Hospitality:Hotel and resort chains consolidating procurement through national lessor contracts. REIT-owned portfolios in the United States increasingly specify lessor-managed fleets as a condition of capital improvement approvals.
Residential commands absolute unit volume; hospitality is climbing the fastest as procurement consolidates.
Energy Efficiency:
Margin structure varies dramatically across efficiency tiers, with certification premiums capturing differential utility rebate values and retail placement priority.
- Standard:Baseline models meeting minimum federal efficiency requirements without third-party certification. Price competition dominates in budget retail channels where upfront cost sensitivity overrides operating expense consideration.
- Energy Star:EPA-certified performance meeting strict water and energy consumption thresholds. Tiered utility rebate programs in California and New York reward this classification with accelerated payback periods.
- High-Efficiency:Sub-10-liter cycles achieved through heat pump circulation and adaptive load sensing. German and French markets show concentration due to EU Ecodesign enforcement and elevated electricity tariffs.
- Eco-Friendly:Extended criteria encompassing biodegradable detergent compatibility and recyclable component share. Niche positioning in Nordic markets and LEED-certified commercial installations.
Energy Star holds installed base dominance; high-efficiency is gaining share fastest on regulatory tailwinds.
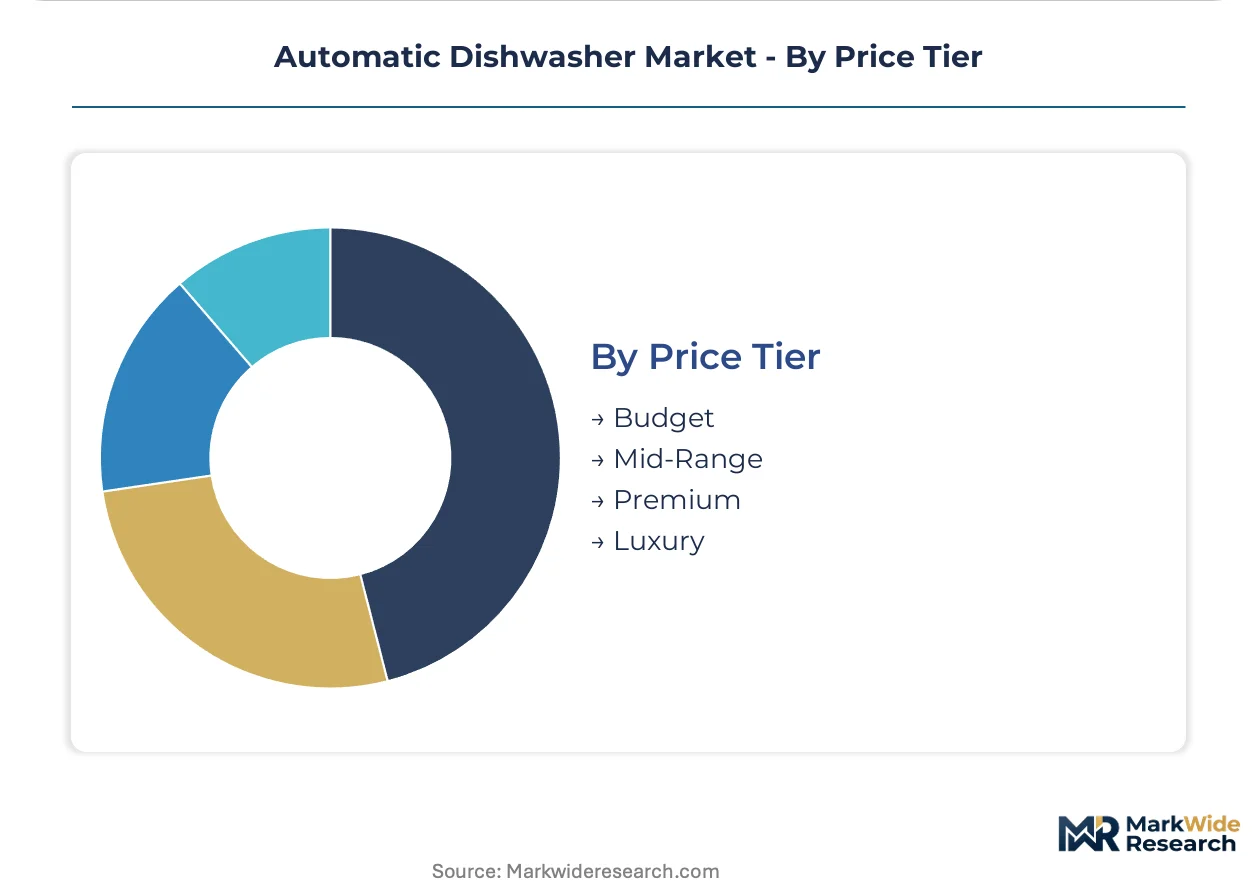
Price Tier:
Supply concentration in motor and pump production creates asymmetric margin pressure across price tiers, with captive manufacturing capabilities determining competitive viability.
- Budget:Entry-level specifications with plastic tub construction and fixed-cycle controls. Distribution concentrates in big-box retail and online marketplaces where landed cost from Chinese assembly determines shelf placement.
- Mid-Range:Stainless-steel tubs with basic soil sensors and delayed start functionality. Volume leadership in replacement markets across the United States and Germany where feature-to-price ratios drive selection.
- Premium:Quiet operation below 44 decibels, third rack configurations, and WiFi connectivity. Kitchen renovation flows in France, Italy, and the United States sustain demand.
- Luxury:Extended engineering cycles, custom panel integration, and commercial-grade sanitization. Miele anchors this tier through stainless-steel tub construction and proprietary pump design.
Mid-range captures the largest unit flow; luxury maintains the most defensible margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States consume built-in units through kitchen renovation cycles, while India and urban China absorb compact variants in space-constrained apartments. This consumption-mix differential fragments manufacturing priorities across geographies.
Germany
Kitchen renovation flows and premium replacement demand sustain built-in volume in owner-occupied housing. EU Ecodesign regulations enforce sub-10-liter water consumption thresholds, compressing development timelines for domestic manufacturers. Industrial concentration clusters in Baden-Württemberg, where pump engineering and stainless-steel fabrication supply chains serve pan-European distribution.
United States
REIT-owned hospitality portfolios and independent restaurant chains accelerate commercial procurement to offset wage inflation. EPA Energy Star certification unlocks tiered utility rebates in California and New York districts. Manufacturing and distribution gravity centers on the Midwest appliance corridor, with assembly operations feeding big-box retail and national equipment lessor networks.
India
Mumbai and Bangalore apartment dwellers drive underpenetrated demand for compact countertop units relative to washing machine ownership rates. Bureau of Indian Standards efficiency labeling creates compliance barriers for imported budget-tier models. Distribution concentrates in Maharashtra and Karnataka urban corridors, where modern retail formats expand appliance penetration.
China
Urban kitchen retrofits in Shanghai and Beijing absorb compact and drawer-configured variants for space-efficient installation. MIIT energy efficiency standards and GB national standards constrain allowable standby power and water consumption. Manufacturing clusters in the Yangtze River Delta produce motors and control systems for domestic brands and export assembly.
France
Île-de-France and Auvergne-Rhône-Alpes sustain premium built-in demand through high-end kitchen renovation activity. EU F-Gas Regulation phase-down drives specification of condensation-drying systems eliminating heat-pump refrigerant dependency. Retail placement prioritizes Ecodesign-compliant models with documented lifecycle cost analysis for public procurement channels.
Automatic Dishwasher Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive pump production and multi-brand distribution determining margin control. The structure compresses mid-tier assemblers between scale-driven volume players and engineering-intensive premium positions. Three archetypes dominate: European engineering-led manufacturers with in-house component supply, North American scale operators running multi-brand portfolios, and Asian cost-optimized assemblers serving budget retail channels. Competitive moves center on backward integration into motor production and strategic bundling with national equipment lessors.
Among the integrated engineering tier, Bosch and Miele exemplify divergent approaches to premium positioning—Bosch through captive circulation pump supply and Miele through extended-cycle stainless-steel construction. Whirlpool occupies the scale-driven North American position with multi-brand distribution spanning budget through mid-range channels. LG represents the Korean diversified electronics conglomerate archetype, leveraging display and control system competencies across appliance categories.
| Leading Market Players |
|---|
| LG |
| Thermador |
| Bosch |
| Midea |
| Whirlpool |
| Miele |
| GE |
| Frigidaire |
| KitchenAid |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between national equipment lessors and circulation pump manufacturers lock in supply access and price visibility across the hospitality procurement channel. These arrangements insulate lessor-managed fleets from nickel-alloy sheet volatility while compressing margins for independent distributors locked into spot-market component sourcing.
Pricing Analysis
After-sales service revenue from multi-year maintenance contracts drives lifetime value for commercial-grade units. Pricing stratifies across premium, standard, and economy tiers based on Energy Star certification grade and stainless-steel tub construction. Pricing pressure stems from Chinese motor exports flooding budget retail channels. Residential buyers in owner-occupied housing show lowest price sensitivity; rental-market portable purchasers exhibit highest.
Supply Chain Analysis
Strategic stockpiling of brushless DC motors prevails among German and Chinese manufacturers facing extended lead times from single-source suppliers. Component production clusters in China, Germany, and South Korea. Stainless-steel sheet, electronic control boards, and circulation pumps constitute critical inputs. Single-source vulnerability in high-efficiency motor production creates structural risk. Distribution runs through national equipment lessors and big-box retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automatic dishwasher penetration remains below washing machine ownership rates across Indian and Chinese urban households, positioning the market for early-cycle expansion as kitchen renovation flows accelerate in dense metropolitan corridors.
For Market Incumbents: Compound captive pump production advantages by extending heat pump circulation technology into mid-range product lines. Consolidate procurement relationships with REIT-owned hospitality portfolios before national lessor contracts harden into exclusive supply arrangements. Certification investment in simultaneous EPA WaterSense and EU Ecodesign validation defends against cross-border product launch delays.
For New Entrants and Emerging Players: Differentiate on sensor-driven load optimization and cloud-connected diagnostics to capture commercial operator contracts outside consolidated lessor networks. White-space targets include Mumbai and Bangalore compact countertop segments and tier-two US hospitality chains bypassing national procurement consolidation. Direct-to-commercial distribution through regional equipment distributors offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with captive pump production and multi-year service contracts with institutional buyers. Long-term viability over a five-to-ten year window favors integrated engineering-led manufacturers with backward integration into motor production. Acquisition target archetype: mid-tier assemblers with established distribution but vulnerable to single-source pump supply. Watch for inflection when utility rebate stacking programs expand beyond California and New York into additional state jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Bosch and Miele anchor margins through captive circulation pump supply chains. |
| Heat Pump Circulation Technology Deployment | Sub-10-liter cycles meet EU Ecodesign thresholds while reducing operating costs. |
| Sensor-Driven Load Optimization | Ultrasonic soil detection enables usage-based service contracting for commercial operators. |
| Multi-Region Certification Investment | Simultaneous EPA WaterSense and EU Ecodesign validation accelerates product launch timelines. |
| National Equipment Lessor Partnership | REIT-owned hotel portfolios increasingly mandate lessor-managed dishwasher fleets. |
Study Parameters
The analysis maps built-in, portable, drawer, and compact product categories, each validated through appliance manufacturing executives, national equipment lessor procurement directors, and commercial kitchen operations managers. Primary interviews with pump engineering specialists and control board firmware developers combined with secondary validation from EPA Energy Star certification databases, EU Ecodesign regulatory filings, and customs trade data. Bottom-up unit shipment modeling and top-down value triangulation cross-checked against utility rebate program disclosures and hospitality capital expenditure surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user category, energy efficiency tier, and price positioning. CAGRs derived from regression analysis of replacement cycle timing, new construction flows, and regulatory compliance cost absorption. Industry-specific forecast inputs incorporated stainless-steel price indices and brushless DC motor production capacity utilization.
Forecasts assume regulatory continuity in EPA Energy Star and EU Ecodesign enforcement regimes; material policy shifts would require re-modeling of pump engineering and heating element specifications. Revision becomes warranted when nickel-alloy export restrictions or F-Gas Regulation phase-down timelines cross thresholds that alter manufacturing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Colombia Laundry Appliances Market
Appliances
China Induction Hobs Market
Appliances
Smart Microwave Oven Market
Appliances
Household Vacuum Cleaners Market
Appliances
France Household Electric Grills Market
Appliances
North America Washing Machine Market
Appliances
US Electric Rice Cooker Market
Appliances
Wall Oven Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
Europe Garment Steamers Market
Appliances
Tumble Dryer Market
Appliances
North America Compact Dishwasher Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Portable Mini Fridge Market
Appliances
Asia-Pacific Tumble Dryers Market