
 Conveyor Dishwasher Market | 2026-2036
Conveyor Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Dishwasher Market Outlook
Commercial kitchen technician shortages are reorganizing how foodservice operators evaluate capital equipment, pushing automated conveyor systems higher on replacement timelines. Hobart Corporation leverages its captive service network to anchor aftermarket revenue streams across North American institutional accounts. Meiko Maschinenbau GmbH & Co. KG specializes in heat-recovery engineering that sustains premium positioning in European hospital and hotel installations. Electrolux Professional competes through modular platform architectures that reduce field installation labor requirements.
A conveyor dishwasher is a continuous-feed warewashing machine employing a motorized belt to transport racks or loose items through sequential wash, rinse, and sanitize zones operating at temperatures between 150°F and 180°F; its primary purpose is sanitizing high volumes of dishware, glassware, and utensils in commercial foodservice and healthcare environments. Energy-efficient product types now capture the dominant margin pool as operators face escalating utility costs and code compliance deadlines, while high-temperature configurations lead in hospital end-user segments where thermal sanitization eliminates chemical residue concerns. Steam cleaning technology is maturing in European installations where water hardness and detergent regulations favor reduced chemical dependency, whereas hybrid cleaning systems represent the fastest-growing technology category by blending aqueous and chemical stages for variable soil loads.
The EPA ENERGY STAR program and NSF/ANSI 3 standards govern equipment efficiency and sanitation performance in the United States, while the EU Ecodesign Directive and CE marking requirements shape European market access and product development roadmaps. The FDA Food Code provisions on warewashing temperatures and the OSHA bloodborne pathogen standards for healthcare foodservice further constrain equipment specification in institutional settings. Stakeholders must monitor evolving state-level water restriction codes and building electrification mandates that could disqualify gas-heated conveyor models from new construction specifications.
Market Dynamics
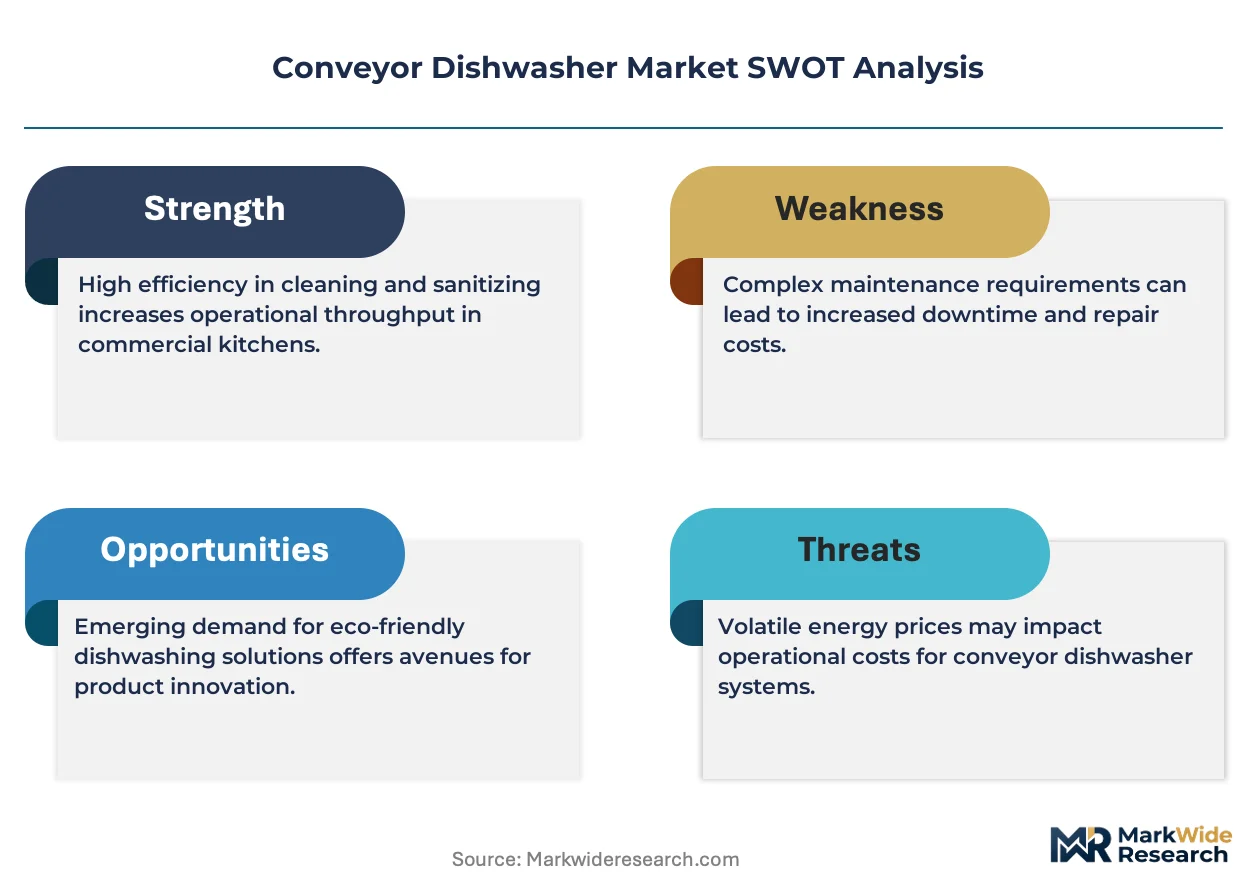
Commercial kitchen labor shortages are compressing equipment replacement cycles as operators prioritize automated warewashing systems that reduce manual intervention and technician dependency. The EPA ENERGY STAR program and escalating state water codes are simultaneously reshaping procurement specifications toward heat-recovery and low-consumption configurations.
Growth Catalysts
- Hospital construction pipelines:Florida and Georgia healthcare facility expansions are driving institutional-grade conveyor dishwasher installations with thermal sanitization capabilities that satisfy FDA Food Code temperature requirements.
- EPA ENERGY STAR mandates:Efficiency certification requirements are disqualifying legacy gas-heated models from new construction specifications and accelerating replacement demand in full-service restaurant chains.
- Steam cleaning maturation:European water hardness regulations and detergent restrictions favor reduced chemical dependency, expanding adoption of steam-based sanitization in German and Swiss hospital installations.
Market Restraints
- Stainless steel input volatility:Conveyor belt and wash tank fabrication depends on nickel-alloy pricing swings that compress equipment margin structures during commodity spikes.
- Gas heating disqualification risk:California and Texas building electrification mandates threaten to exclude gas-heated conveyor models from new commercial kitchen specifications within two code cycles.
- Commercial kitchen technician scarcity:Qualified service labor shortages extend mean-time-to-repair for automated warewashing systems and elevate total cost of ownership calculations.
Strategic Opportunities
- Hybrid cleaning convergence:Blending aqueous and chemical treatment stages creates variable soil-load flexibility that opens penetration in quick-service restaurant segments with inconsistent dishware contamination profiles.
- Modular platform architectures:Field-installation labor reduction through pre-configured subassemblies addresses contractor availability constraints in US Southeast hospital and hotel construction markets.
- Aftermarket service unbundling:Captive technician networks generate recurring revenue streams from institutional accounts seeking guaranteed uptime commitments and preventive maintenance contracts.
Industry Challenges
- NSF/ANSI 3 certification timelines:Sanitation performance validation for new heat-recovery configurations extends product launch schedules and delays revenue recognition.
- Legacy system integration friction:Retrofitting automated conveyor systems into existing commercial kitchen layouts requires custom electrical and plumbing reconfiguration that elevates project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Dishwasher Market |
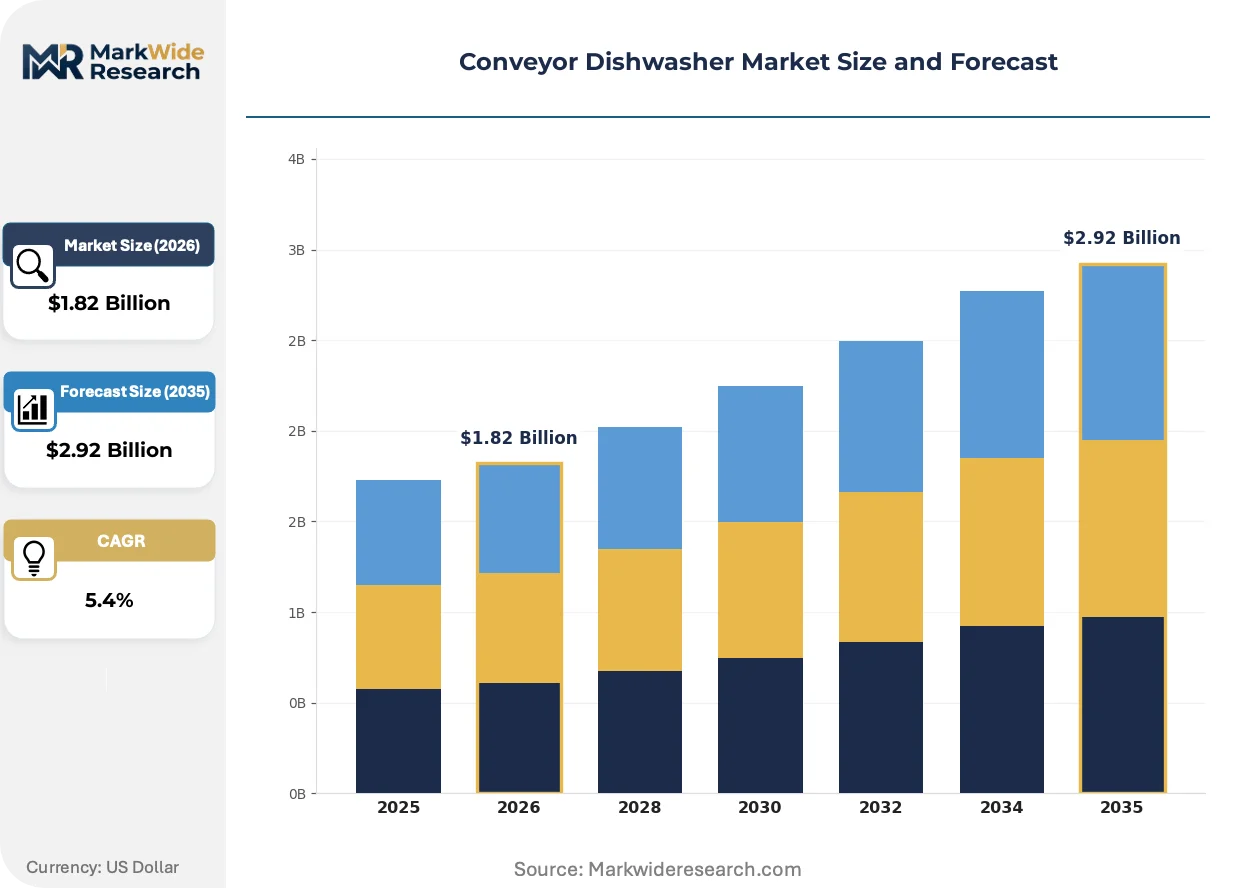
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Conveyor, Energy-Efficient, High-Temperature, Compact End User: Restaurants, Cafeterias, Hotels, Hospitals Technology: Steam Cleaning, Chemical Cleaning, Aqueous, Hybrid Cleaning Installation: Built-In, Modular, Standalone, Integrated |
| Companies Covered | Hobart Corporation, Winterhalter Group, Meiko Maschinenbau GmbH & Co. KG, Electrolux Professional, Jackson WWS, Champion Industries, CMA Dishmachines, Miele Professional, Fagor Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Dishwasher Market Strategic Shifts
Heat-recovery engineering and modular system architectures are actively reshaping competitive positioning in commercial warewashing equipment. Technology convergence between aqueous and chemical treatment stages is creating new performance categories that address variable operational demands.
Steam cleaning technology is decomposing traditional high-temperature sanitization configurations in European installations. German hospital foodservice operators are adopting steam-based systems at accelerating pace to satisfy Ecodesign Directive water efficiency requirements. This technology is decomposing the historical dominance of chemical sanitization in hard-water regions and compressing the addressable market for conventional booster-heater configurations.
REACH chemical restrictions and EU F-Gas Regulation phase-down schedules are constraining refrigerant-based heat-pump options in European conveyor dishwasher designs. Equipment manufacturers are pivoting toward alternative thermal recovery methods that bypass synthetic refrigerant dependency. Hospital and hotel operators in France and Italy are responding by specifying air-source heat recovery and exhaust-gas recapture systems that maintain efficiency ratings without regulatory exposure.
Buying committees in US full-service restaurant chains are consolidating vendor relationships and demanding outcome-based performance guarantees rather than transactional equipment purchases. Multi-unit operators are replacing fragmented regional supplier contracts with national service agreements that bundle equipment, installation, and maintenance. This pattern is most visible in Florida and Georgia, where private equity-backed restaurant groups are standardizing warewashing specifications across acquired portfolios to reduce operational variability.
Conveyor Dishwasher Market Segmentation
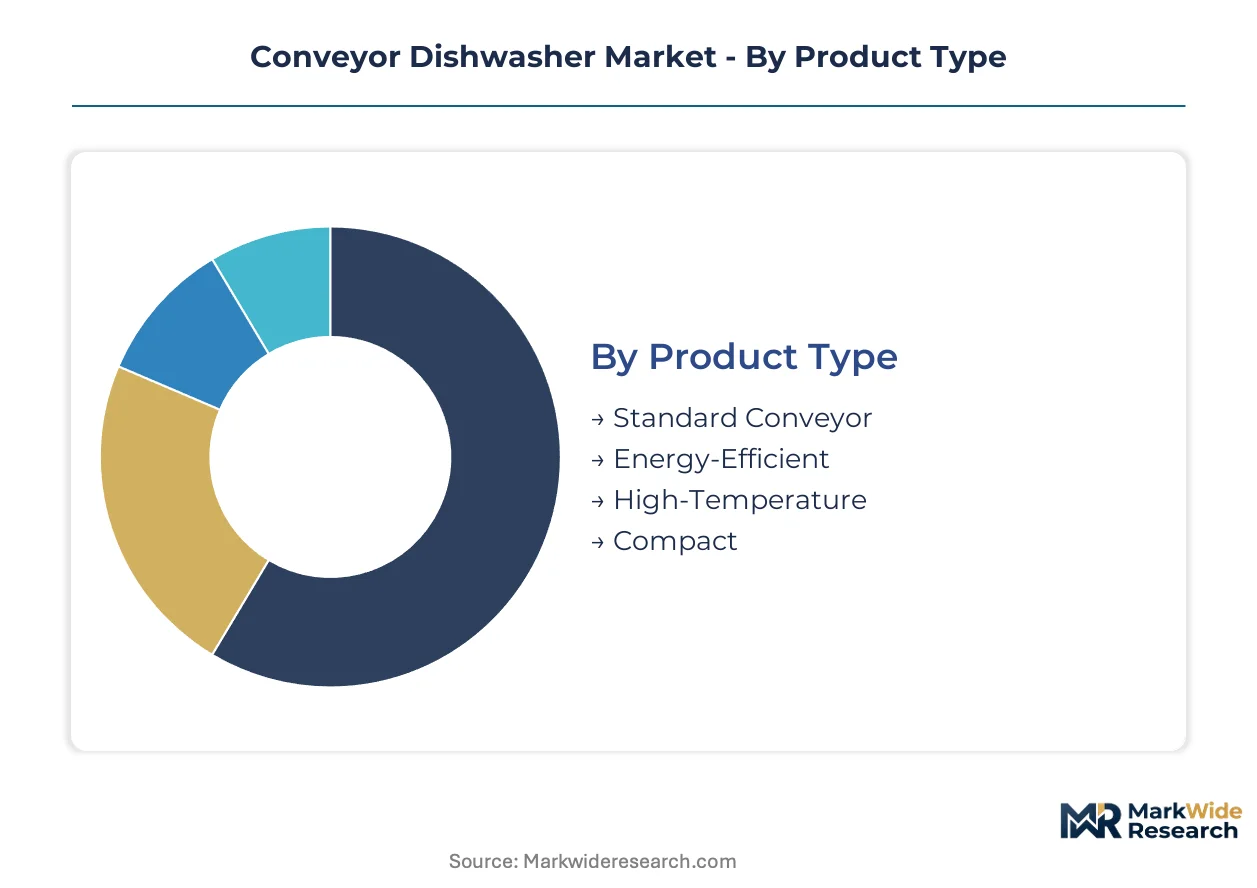
Segmentation in the conveyor dishwasher market determines equipment specification pathways, with regulatory compliance and operational throughput requirements driving category selection across foodservice and healthcare verticals.
Product Type:
EPA ENERGY STAR certification thresholds and state-level water efficiency codes differentiate equipment procurement eligibility across product categories.
- Standard Conveyor:Baseline motorized belt systems operating at fixed wash-rinse-sanitize temperatures without heat-recovery mechanisms. Full-service restaurant chains in Texas and Florida specify these for high-volume throughput where utility costs remain secondary to capital expenditure constraints.
- Energy-Efficient:Heat-recovery engineering and low-consumption spray architectures that capture exhaust thermal energy to preheat incoming water. California and Texas building codes are accelerating replacement demand as gas-heated models face electrification mandates.
- High-Temperature:Thermal sanitization systems maintaining 180°F final rinse temperatures that eliminate chemical residue. Hospital foodservice departments specify these configurations to satisfy FDA Food Code requirements and OSHA bloodborne pathogen standards.
- Compact:Reduced-footprint belt systems designed for kitchens with spatial constraints. Urban quick-service operators deploy these where floor space commands premium lease rates.
Energy-Efficient configurations handle the majority of new procurement volume; Compact systems are gaining share fastest in urban restaurant construction.
End User:
Sanitation performance requirements and operational scale determine equipment specification intensity across customer verticals.
- Restaurants:Full-service and quick-service chains with variable dishware contamination profiles. Florida and Georgia private equity-backed restaurant groups are consolidating vendor relationships and demanding bundled service agreements.
- Cafeterias:Institutional feeding operations with predictable volume patterns and extended service windows. School and corporate campus operators prioritize uptime guarantees over capital cost minimization.
- Hotels:Hospitality foodservice with fluctuating banquet and room-service demands. Georgia and Florida hotel construction pipelines specify modular architectures that reduce field installation labor requirements.
- Hospitals:Healthcare foodservice where thermal sanitization eliminates chemical residue concerns. FDA Food Code temperature provisions and OSHA bloodborne pathogen standards constrain equipment selection to high-temperature configurations.
Restaurants absorb the largest equipment volume; Hospitals are climbing the fastest on specification intensity.
Technology:
Regional water hardness regulations and detergent restriction frameworks determine technology adoption patterns across geographies.
- Steam Cleaning:Vapor-phase sanitization reducing chemical dependency in hard-water installations. German and Swiss hospital operators are adopting these systems to satisfy EU Ecodesign Directive water efficiency requirements.
- Chemical Cleaning:Sanitizer-based final rinse configurations using chlorine or quaternary ammonium compounds. Soft-water regions with relaxed detergent regulations maintain specification share for cost-sensitive operators.
- Aqueous:Water-only wash cycles with mechanical soil removal through high-pressure spray patterns. Baseline technology for standard conveyor configurations in cost-optimized restaurant chains.
- Hybrid Cleaning:Blended aqueous and chemical treatment stages with programmable soil-load detection. Quick-service restaurant segments with inconsistent dishware contamination profiles are driving steepest expansion trajectory.
Aqueous technology handles baseline throughput requirements; Hybrid Cleaning is expanding most quickly in quick-service penetration.
Installation:
Construction labor availability and kitchen retrofit complexity determine installation architecture selection.
- Built-In:Custom-integrated systems requiring structural kitchen modifications and permanent utility connections. New hospital construction in Florida and Georgia specifies these for seamless workflow integration.
- Modular:Pre-configured subassemblies reducing field installation labor and contractor dependency. US Southeast construction markets facing technician scarcity are prioritizing these architectures.
- Standalone:Self-contained units with minimal utility interconnection requirements. Smaller cafeteria and restaurant operators favor these for deployment flexibility.
- Integrated:Systems combining conveyor washing with adjacent preparation or storage equipment. Large hotel banquet facilities specify these for operational flow optimization.
Modular architectures are capturing the largest share of new construction specifications; Built-In configurations face pressure from labor availability constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss hospital installations where EU Ecodesign Directive compliance commands premium positioning, while US Southeast markets compete on installation speed and service network density. This asymmetry shapes divergent competitive strategies across Atlantic basin demand centers.
United States
Florida and Georgia healthcare construction pipelines drive institutional-grade conveyor dishwasher specifications with thermal sanitization requirements. The EPA ENERGY STAR program disqualifies legacy gas-heated models from new construction bids in California and Texas. Atlanta and Miami hospital clusters specify modular architectures to circumvent commercial kitchen technician shortages.
Germany
Hospital foodservice operators in Bavaria and Baden-Württemberg adopt steam-based sanitization systems at accelerating pace. REACH chemical restrictions and EU F-Gas Regulation phase-down schedules constrain refrigerant-based heat-pump designs. Munich and Stuttgart industrial zones anchor heat-recovery engineering development for European export markets.
France
Hotel construction in Île-de-France and Provence-Alpes-Côte d'Azur specifies air-source heat recovery systems that bypass synthetic refrigerant dependency. The EU Ecodesign Directive shapes procurement criteria for water efficiency compliance. Lyon and Marseille hospitality clusters drive demand for exhaust-gas recapture configurations.
Switzerland
German-speaking cantons lead European adoption of steam cleaning technology for hard-water hospital installations. Swissmedic sanitation standards exceed baseline EU requirements and sustain premium equipment specifications. Zurich and Basel healthcare foodservice operations prioritize reduced chemical dependency under cantonal environmental ordinances.
United Kingdom
London and Southeast England hotel renovations prioritize compact footprint systems where floor space commands premium lease rates. NHS procurement frameworks emphasize NSF/ANSI 3-equivalent sanitation performance for thermal sanitization. Birmingham and Manchester institutional feeding operations consolidate vendor relationships under national framework agreements.
Conveyor Dishwasher Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the conveyor dishwasher market. The vendor base stratifies into three tiers: integrated multinational equipment manufacturers with captive service networks, specialized regional fabricators with heat-recovery engineering expertise, and modular platform specialists addressing labor-constrained installation markets. Strategic differentiation centers on aftermarket service unbundling and pre-configured subassembly architectures that reduce field technician dependency.
Among Germany-based engineering specialists, Meiko Maschinenbau GmbH & Co. KG exemplifies the heat-recovery technology archetype, while Electrolux Professional occupies a position within the modular platform tier. Hobart Corporation anchors the integrated multinational segment with North American institutional account density. These three company structures represent the dominant competitive positioning vectors in commercial warewashing equipment procurement.
| Leading Market Players |
|---|
| Hobart Corporation |
| Winterhalter Group |
| Meiko Maschinenbau GmbH & Co. KG |
| Electrolux Professional |
| Jackson WWS |
| Champion Industries |
| CMA Dishmachines |
| Miele Professional |
| Fagor Industrial |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts with bundled preventive maintenance clauses lock in supply access for institutional buyers while anchoring price visibility across multi-year equipment lifecycles. This contract architecture insulates hospital and hotel operators from nickel-alloy volatility in stainless steel fabrication while compressing margin exposure for manufacturers during commodity spikes.
Pricing Analysis
German and Swiss hospital installations command pricing spreads exceeding those in US Southeast construction markets by substantial margins. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ENERGY STAR certification tier and heat-recovery engineering intensity. Cost compression in standard conveyor configurations is intensifying because Florida and Georgia contractors prioritize installation speed over feature depth. Quick-service restaurant chains exhibit highest price sensitivity; Bavarian healthcare foodservice departments show lowest.
Supply Chain Analysis
Nickel-alloy procurement from Indonesian and Philippine mining operations underwrites stainless steel input stability for conveyor belt and wash tank fabrication. Equipment manufacturing draws from German heat-recovery engineering, Chinese electrical component sourcing, and domestic stainless steel fabrication. Single-source vulnerability concentrates in specialized pump and motor assemblies from select European suppliers. Distribution runs through manufacturer-direct service networks for institutional accounts and regional equipment distributors for independent restaurant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flight-type warewashing systems and autonomous robotic cleaning platforms pose substitution threats that incumbent conveyor manufacturers must neutralize through service bundling and thermal efficiency leadership.
For Market Incumbents: Consolidate captive technician networks into multi-year preventive maintenance contracts that raise switching costs for hospital and hotel accounts. Deepen backward integration into heat-recovery engineering development to defend margin position against modular platform specialists. Anchor aftermarket revenue streams through guaranteed uptime commitments that robotic alternatives cannot yet match. For New Entrants and Emerging Players: Differentiate on hybrid cleaning convergence for quick-service restaurant segments with inconsistent soil-load profiles. Target California and Texas replacement markets where electrification mandates disqualify legacy gas-heated inventory. Penetrate through outcome-based performance guarantees rather than capital equipment transactions. For Investors and Strategic Acquirers: Capital is best deployed toward modular platform specialists with pre-configured subassembly capabilities that address US Southeast labor scarcity. Five-to-ten year viability hinges on regulatory tailwinds for energy efficiency and water conservation. Monitor state-level building electrification mandate adoption as inflection indicator for gas-heated model obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Recovery Engineering Investment | Captures EPA ENERGY STAR compliance premiums in California and Texas hospital specifications. |
| Modular Platform Expansion | Reduces field installation labor dependency in Florida and Georgia construction pipelines. |
| Aftermarket Service Unbundling | Generates recurring revenue from institutional accounts seeking guaranteed uptime commitments. |
| Hybrid Cleaning Technology Development | Addresses variable soil-load flexibility for quick-service restaurant penetration. |
| Steam Cleaning Portfolio Addition | Satisfies EU Ecodesign Directive water efficiency requirements in German hospital installations. |
Study Parameters
A standing panel of hospital foodservice directors, commercial kitchen contractors, equipment procurement managers, and aftermarket service technicians provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against EPA ENERGY STAR certification databases, NSF/ANSI 3 sanitation performance records, state-level building code filings, and hospital construction permit data. Bottom-up equipment shipment analysis and top-down foodservice operator expenditure estimates underwent cross-triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, end-user vertical, technology category, and installation architecture. CAGRs derived from regression analysis of historical shipment data and forward-looking replacement cycle assumptions incorporated hospital construction pipeline tracking and restaurant chain expansion plans as industry-specific inputs.
Material uncertainties — nickel-alloy price volatility, state electrification mandate acceleration, and commercial kitchen technician availability — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory adoption timelines and equipment replacement elasticity. Practitioners should keep alternative scenarios live as building electrification code cycles and labor market conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Clothing Iron Market
Appliances
North America Compact Dishwasher Market
Appliances
Middle East Water Heater Market
Appliances
Personal Care Appliances Market
Appliances
Europe Household Electric Grills Market
Appliances
Egypt Dishwashers Market
Appliances
North America Washing Machine Market
Appliances
Kuwait Microwave Ovens Market
Appliances
Global Massage Chairs Market
Appliances
Electric Fan Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Garments Steamer Market
Appliances
Under Counter Dishwasher Market
Appliances
Glass Ceramic Cooktop Market
Appliances
French Door Refrigerator Market
Appliances
AI Washing Machine Market