
 US Portable Washing Machines Market | 2026-2036
US Portable Washing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
US Portable Washing Machines Market Insights
Multi-source component procurement is realigning how US portable washing machine manufacturers manage supply chains. Whirlpool Corporation leverages its domestic manufacturing footprint to control distribution costs across the Midwest and Southeast. Samsung Electronics competes through vertical integration in motor and control systems, sustaining margin resilience despite import tariff exposure.
US portable washing machines are self-contained laundry units typically weighing under 100 pounds, operating on standard 120V residential outlets with load capacities ranging from 0.9 to 2.5 cubic feet, designed for spaces lacking permanent washer-dryer hookups. Compact and twin tub configurations dominate unit shipments among RV owners and students where space constraints and mobility requirements override cycle-speed preferences. Smart technology integration represents the fastest-growing technology segment as Wi-Fi-enabled diagnostics and app-based cycle control command premium positioning in the domestic channel.
DOE appliance efficiency standards, ENERGY STAR certification, and FTC energy labeling rules collectively shape product design requirements and market access thresholds for portable washing machines sold in the United States. EPA water efficiency guidelines increasingly influence consumer-facing marketing claims and retail placement decisions. Stakeholders must monitor evolving federal efficiency rulemakings and state-level water restriction policies to anticipate compliance cost shifts and product line reconfiguration needs.
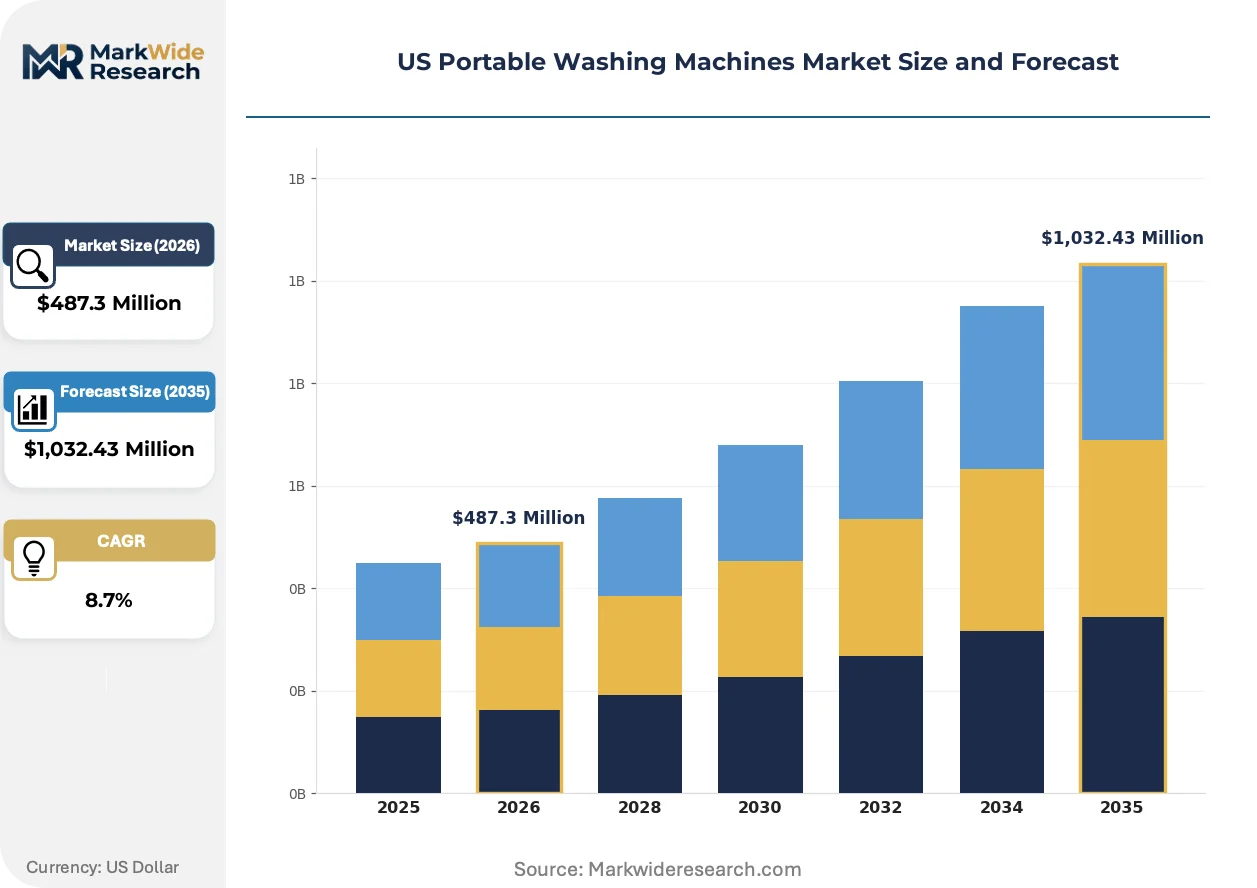
Market Dynamics
DOE appliance efficiency standards and ENERGY STAR certification requirements are compressing product development cycles while reshaping manufacturer R&D allocation across the US portable washing machines market.
Growth Catalysts
- RV ownership expansion:Texas, Florida, and Arizona population inflows intersect with recreational vehicle culture, creating concentrated demand corridors for compact laundry solutions.
- ENERGY STAR certification pull:Retail placement algorithms at major home improvement chains prioritize certified units, channeling procurement toward compliant manufacturers.
- Smart technology integration:Wi-Fi-enabled diagnostics and app-based cycle control command premium positioning, expanding average selling prices in domestic channels.
Market Restraints
- Import tariff exposure:Motor and control system sourcing from Asian manufacturing clusters faces duty volatility, compressing margin buffers for non-vertically integrated assemblers.
- Copper and steel input costs:Commodity price swings in electrical wiring and drum materials create quarterly cost reforecasting burdens.
- 120V power limitation:Standard residential outlet constraints cap heating element wattage, extending cycle times versus full-size alternatives.
Strategic Opportunities
- Sun Belt state penetration:Arizona, Nevada, and New Mexico sub-markets remain underdeveloped relative to Texas and Florida, offering whitespace for distribution expansion.
- Student housing procurement:University facilities departments are consolidating vendor relationships, creating multi-unit contract opportunities for compliant suppliers.
- EPA WaterSense alignment:Voluntary certification programs enable marketing differentiation in drought-prone municipalities with active conservation mandates.
Industry Challenges
- Embedded software compliance:FCC Part 15 testing for Wi-Fi modules adds certification timelines and recertification costs for firmware updates.
- Retrofit installation skill gaps:Drainage adapter compatibility across aging plumbing infrastructure requires field technician training investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Portable Washing Machines Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top-Load, Front-Load, Compact, Twin Tub End User: Residential, RV Owners, Small Apartments, Students Technology: Energy Efficient, Traditional, High-Efficiency, Smart Technology Market Segment: Domestic, Commercial, Rental Services, E-commerce |
| Companies Covered | Whirlpool Corporation, Samsung Electronics, GE Appliances, Haier, Electrolux AB, Speed Queen, IFB, Amana Corporation, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Portable Washing Machines Market Trends and Innovations
Technology convergence, regulatory stringency, and buyer mobility requirements are simultaneously compressing traditional product lifecycles and opening premium positioning avenues for adaptive manufacturers.
Sensor-driven load balancing is converging with vibration dampening algorithms to enable second-floor installation without structural reinforcement. Apartment dwellers in multi-story buildings are adopting these units at accelerating rates. The technology is converging with space-constrained urban housing stock, displacing laundromat dependency in dense metropolitan cores.
DOE test procedure updates for clothes washer energy consumption measurement are tightening allowable standby power thresholds. Manufacturers must redesign control boards and display systems to meet revised compliance windows. Compact and twin tub configurations face disproportionate engineering burden given their lower absolute energy footprints.
Direct-to-consumer channel expansion is fragmenting traditional big-box dependency among younger buyer cohorts. Specialty RV equipment retailers and online marketplaces are capturing share from home improvement chains. This pattern concentrates in western states where dispersed populations and digital-native demographics overlap.
US Portable Washing Machines Market Segmentation
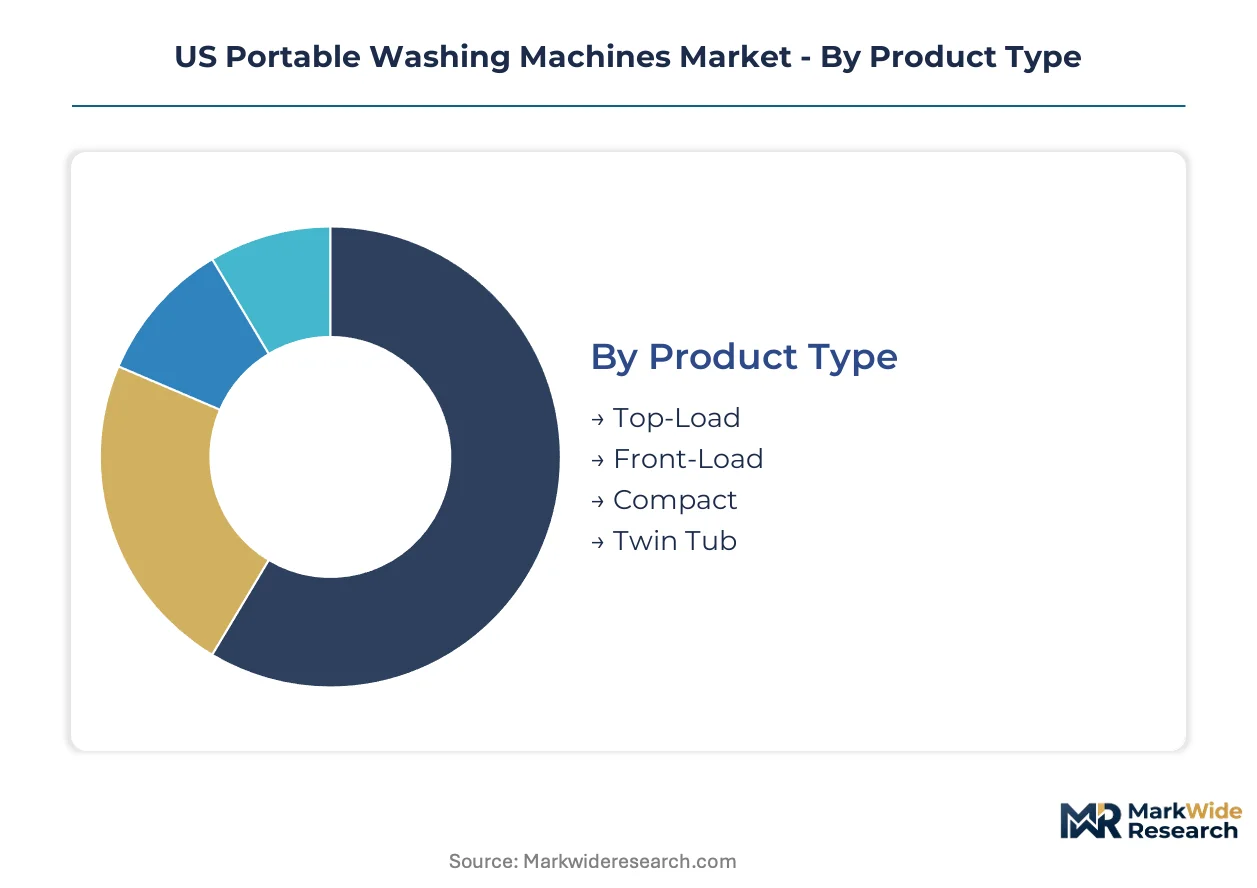
Segmentation reveals how portable washing machines serve fundamentally different use cases—from permanent apartment installations to mobile RV applications. Each category exposes distinct technical requirements, distribution channels, and regulatory compliance burdens that shape manufacturer portfolio decisions.
Product Type:
Standalone units dominate residential and RV applications where mobility or space constraints prevent built-in installation, while compact formats increasingly embed into multi-function furniture systems for urban micro-units.
- Top-Load:Vertical drum orientation enables faster load access and simpler mechanical construction. Demand concentrates among RV owners in Texas and Florida where vibration tolerance and ease of repair outweigh water efficiency concerns.
- Front-Load:Horizontal drum configuration extracts more water per cycle, reducing drying time. Small apartment dwellers in Sun Belt states favor these units where ENERGY STAR certification influences utility rebate eligibility and resale value.
- Compact:Under-24-inch width specifications fit closet and bathroom alcove installations. Students in university housing clusters drive procurement volumes through facilities consolidation contracts.
- Twin Tub:Separate washing and spinning chambers enable simultaneous operations without plumbing connections. Manual water filling requirements limit adoption to off-grid RV applications and international migrant worker housing.
Top-Load configurations lead volumes today; Front-Load is gaining share fastest.
End User:
Cost tier stratification separates price-sensitive student segments from premium-positioned RV owners willing to pay for durability certifications and extended warranties.
- Residential:Homeowners in accessory dwelling units and basement conversions seek permanent-installation alternatives to full-size appliances. DOE efficiency standards and local plumbing codes shape product eligibility.
- RV Owners:Mobile lifestyle requirements prioritize weight reduction, 120V power compatibility, and secure transport latching. Arizona and Nevada desert camping corridors concentrate aftermarket demand.
- Small Apartments:Space-constrained urban renters in multi-story buildings favor vibration-dampening models for second-floor installation without structural reinforcement.
- Students:University procurement departments negotiate multi-year vendor contracts with bulk pricing and centralized maintenance provisions.
Residential users anchor current revenue; RV Owners are expanding most quickly.
Technology:
Margin structure separates commodity traditional designs from premium smart-enabled units commanding price premiums through app-based diagnostics and remote cycle management.
- Energy Efficient:Designs meeting baseline DOE standards without ENERGY STAR certification occupy entry price tiers. Cost-conscious buyers in student and rental markets prioritize upfront acquisition over lifecycle operating costs.
- Traditional:Conventional agitator mechanisms without electronic controls dominate replacement markets for aging RV fleet retrofits. Simpler repairability sustains aftermarket parts demand.
- High-Efficiency:ENERGY STAR-compliant designs with optimized water and electricity consumption. Retail placement algorithms at home improvement chains prioritize these units, channeling procurement toward compliant manufacturers.
- Smart Technology:Wi-Fi-enabled diagnostics, app-based cycle control, and usage analytics command premium positioning. Younger buyer cohorts in digital-native demographics drive adoption through direct-to-consumer channels.
High-Efficiency units dominate shipment value; Smart Technology shows the steepest expansion trajectory.
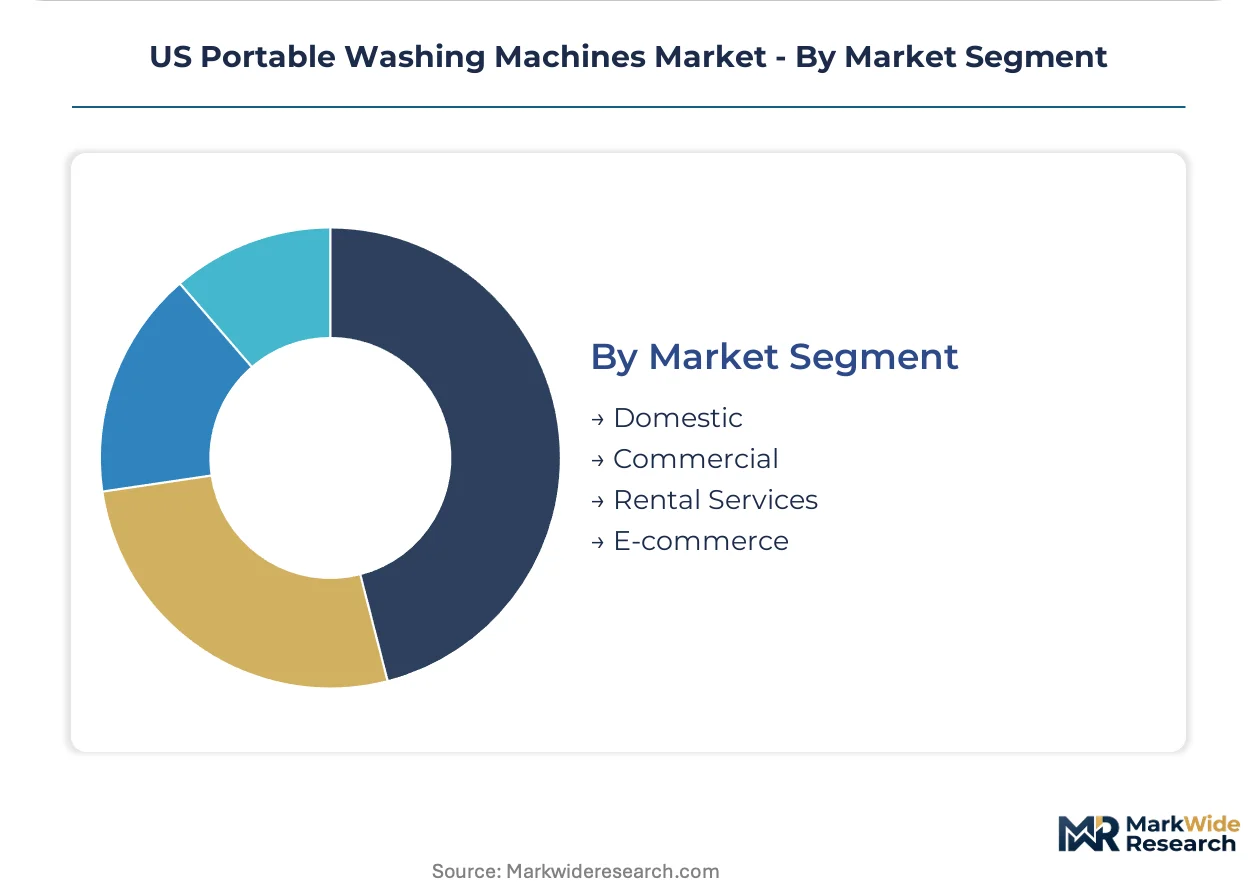
Market Segment:
Supply concentration varies sharply between channel types, with domestic retail requiring regional distribution infrastructure while e-commerce enables direct manufacturer-to-consumer fulfillment bypassing traditional wholesale markups.
- Domestic:Brick-and-mortar home improvement chains and appliance specialty retailers. Physical inspection requirements sustain this channel for first-time buyers evaluating build quality and noise levels.
- Commercial:Hospitality properties, extended-stay hotels, and workforce housing operators. Bulk procurement contracts emphasize durability warranties and standardized maintenance protocols.
- Rental Services:Appliance-as-a-service models for temporary housing and corporate relocation packages. Monthly fee structures shift capital burden from consumers to fleet operators.
- E-commerce:Online marketplaces and direct-to-consumer brand sites. Western states with dispersed populations and limited retail density show highest penetration rates.
Domestic retail maintains volume leadership; E-commerce is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in this market given DOE efficiency standards apply uniformly across US states, yet cost-of-living differentials and housing density variations create distinct regional demand patterns that manufacturers must navigate through targeted distribution investments.
Texas
RV ownership rates in Texas exceed national averages by substantial margins, driving concentrated aftermarket demand for 120V-compatible portable units. The Texas Commission on Environmental Quality enforces water efficiency guidelines that influence municipal rebate programs in drought-prone counties. Dallas-Fort Worth and Houston metropolitan corridors host the densest clusters of RV dealerships and mobile home distributors, creating integrated sales channels for compact laundry equipment.
Florida
Snowbird migration patterns generate seasonal demand spikes for rental-property portable appliances in Florida's Gulf Coast and Atlantic Coast corridors. The Florida Department of Environmental Protection coordinates with EPA WaterSense initiatives to promote conservation-certified equipment in water-stressed southern counties. Miami-Dade and Orange County housing authorities specify portable washing machines for workforce housing retrofits where permanent hookups are structurally impractical.
Arizona
Desert camping culture and extreme heat conditions in Arizona prioritize water-efficient designs with minimal electrical draw for off-grid compatibility. The Arizona Department of Water Resources administers municipal conservation mandates that elevate ENERGY STAR and WaterSense certified units in retail placement algorithms. Phoenix and Tucson metropolitan areas concentrate demand among accessory dwelling unit owners and mobile home communities seeking alternatives to shared laundry facilities.
California
Housing affordability constraints in California accelerate adoption of portable units in garage conversions, basement apartments, and backyard cottage configurations. The California Energy Commission maintains appliance efficiency regulations that exceed federal DOE baselines, requiring manufacturer-specific product line adaptations for state market access. Los Angeles County and Bay Area sub-markets show highest penetration of smart-enabled models among digitally-native renter demographics.
Nevada
Las Vegas metropolitan expansion and Reno-Tahoe recreational corridor development create emerging demand nodes for portable laundry solutions in Nevada's transient-worker housing and vacation-rental markets. The Nevada Division of Environmental Protection aligns with regional drought response frameworks that incentivize low-water-consumption appliances through utility rebate structures. Clark County and Washoe County housing stock conversions represent whitespace opportunities for distribution network expansion.
US Portable Washing Machines Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channels and smart-technology differentiation. The US portable washing machines market structures around three maturity tiers: legacy appliance conglomerates with domestic manufacturing footprints, Asian electronics groups with vertical control over motor and control systems, and specialized compact-equipment fabricators serving RV and student housing niches. Dominant competitive moves include backward integration into component sourcing to buffer tariff exposure, and strategic partnerships with university procurement departments and RV dealership networks to secure multi-year volume contracts.
Among the legacy conglomerate tier, Whirlpool Corporation and GE Appliances exemplify domestic manufacturing archetypes with regional distribution infrastructure optimized for Midwest and Southeast market penetration. Samsung Electronics and LG Electronics represent vertically integrated electronics groups with captive supply chains for motor assemblies and digital control modules. Haier occupies a distinct position bridging Chinese manufacturing scale with North American brand recognition through its historical appliance portfolio acquisitions.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics |
| GE Appliances |
| Haier |
| Electrolux AB |
| Speed Queen |
| IFB |
| Amana Corporation |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
ENERGY STAR certification mandates from the DOE are compressing development timelines and forcing manufacturers to absorb compliance costs or pass them through to retail channels. This regulatory pressure concentrates pricing power among vertically integrated producers with captive motor and control system production, while tariff-exposed assemblers face margin compression.
Pricing Analysis
Copper and steel input volatility passes through unevenly across manufacturer tiers, with commodity-exposed assemblers absorbing quarterly cost swings while integrated producers buffer through in-house component production. Pricing stratifies across ENERGY STAR-certified premium units, baseline DOE-compliant standard models, and entry-tier traditional agitator designs. Price erosion runs through the traditional tier as import-dependent assemblers compete on upfront acquisition cost. Student housing procurement departments exhibit highest price sensitivity, while RV owners purchasing through specialty retailers show lowest sensitivity due to durability and warranty priorities.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Atlanta anchor hub-and-spoke fulfillment patterns serving Sun Belt demand corridors with 48-hour restock capabilities. Motor and control system production concentrates in China, South Korea, and Mexico, with final assembly distributed across domestic Midwest facilities and maquiladora operations. Supply chains draw from copper wiring, cold-rolled steel drums, and injection-molded plastic housings. Single-source vulnerability in semiconductor-based control modules creates qualification bottlenecks for firmware updates. Distribution runs through home improvement chain regional DCs, RV dealership networks, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart technology integration and EPA WaterSense alignment are expanding premium-tier addressable market, while component standardization across product lines is compressing per-unit production cost. Margin expansion hinges on capturing certification-driven retail placement premiums.
For Market Incumbents: Extend ENERGY STAR certification coverage across compact and twin tub configurations to lock in retail placement algorithms at major home improvement chains. Deepen backward integration into motor assemblies to buffer Section 301 tariff exposure on Chinese-sourced control systems. Prioritize firmware architecture standardization to streamline FCC Part 15 recertification cycles. For New Entrants and Emerging Players: Begin with direct-to-consumer channel penetration in Arizona and Nevada sub-markets where dispersed populations and limited retail density create whitespace. Target student housing procurement departments consolidating vendor relationships through multi-year maintenance-inclusive contracts. Lead with app-based cycle control and Wi-Fi diagnostics to differentiate from commodity traditional designs. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized compact-equipment fabricators serving RV and student housing niches with established dealership or university procurement relationships. Long-term viability favors manufacturers with domestic assembly footprints and captive supply over motor components. Watch DOE test procedure updates for clothes washers as signal for compliance cost inflection and product line reconfiguration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Assemblies | Captive production of control systems buffers Section 301 tariff exposure and sustains margin resilience. |
| ENERGY STAR Certification Expansion | Retail placement algorithms at Home Depot and Lowe's prioritize certified units, channeling procurement toward compliant manufacturers. |
| Smart Technology Platform Development | Wi-Fi-enabled diagnostics and app-based cycle control command premium positioning among digital-native buyer cohorts. |
| University Procurement Partnership | Multi-year vendor contracts with facilities departments secure volume commitments and centralized maintenance revenue streams. |
| EPA WaterSense Alignment | Voluntary certification enables marketing differentiation in drought-prone municipalities with active conservation mandates. |
Research Methodology
Multiple input streams — manufacturer production data, retail shipment audits, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary interviews with RV dealership procurement managers, university facilities directors, home improvement chain category buyers, and compact appliance product engineers were cross-validated against secondary sources including DOE appliance efficiency rulemakings, ENERGY STAR certification databases, EPA WaterSense program documentation, and customs import records for motor and control system classifications.
Data-stream reconciliation across shipment volumes, average selling price trajectories, and channel mix distributions informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type configuration, end-user archetype, technology tier, and market channel. CAGRs were derived from curve-fitting approaches applied to historical shipment data and elasticity-adjusted demand projections. Forecast inputs incorporated DOE test procedure update timelines and Sun Belt state population migration patterns.
Several conditions sit outside the modeled scope, including potential retaliatory tariff escalations, abrupt copper price shocks, and state-level water restriction policy shifts beyond current conservation mandate trajectories. Forecasts reflect documented assumptions regarding regulatory compliance windows and buyer technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Asia-Pacific Microwave Oven Market
Appliances
Household Beauty Appliances Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
UAE Microwave Ovens Market
Appliances
China Induction Hobs Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Small Electric Kettles Market
Appliances
Large Cooking Appliance Market
Appliances
Middle East Water Heater Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Egypt Microwave Ovens Market
Appliances
Clothing Iron Market
Appliances
Cooler Connected to the Mains Market
Appliances
APAC White Goods Market
Appliances
North America Microwave Oven Market