
 Smart Crane Market | 2026-2036
Smart Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Crane Market Insights
Buyer concentration among infrastructure developers is shifting as port operators and renewable energy contractors fragment procurement across specialized fleet managers. Konecranes leverages its port automation expertise to anchor long-term service contracts in European shipping terminals. XCMG competes on manufacturing scale, sustaining cost advantages in mobile crane production for Asian construction markets.
A smart crane integrates load sensors, variable-frequency drives, and programmable logic controllers to enable real-time load monitoring, anti-collision routing, and automated positioning with millimetre precision for heavy-lift operations. Tower cranes equipped with IoT-based control systems dominate new installations in high-rise construction, while predictive maintenance modules capture expanding margin pools through recurring software subscriptions. AI-powered automation in port handling applications represents the fastest-growing technology segment, displacing manual operator dependency in container terminals.
FAA crane operation standards near airport zones, OSHA workplace lifting regulations, and EU machinery safety directives with CE marking requirements collectively shape equipment certification timelines and sensor integration mandates. The EU AI Act adds compliance layers for autonomous crane decision systems, extending product development cycles for European-bound manufacturers. Stakeholders must weigh regulatory divergence against platform standardization when selecting control system architectures for multi-region deployment.
Market Dynamics
Port operators are consolidating control system procurement around predictive maintenance platforms, compressing vendor margins while extending software subscription lifecycles across container terminal fleets.
Growth Catalysts
- EU machinery safety directives:CE marking mandates for sensor-integrated lifting equipment accelerate replacement cycles in European construction and logistics sectors.
- Offshore wind installation:Floating turbine assembly creates specialized demand for millimetre-precision positioning systems in North Sea and Baltic Sea development zones.
- 5G-enabled remote operation:Ultra-low latency networks allow crane control from centralized command centers, reducing on-site staffing requirements in hazardous environments.
Market Restraints
- Semiconductor supply concentration:PLC and VFD component sourcing remains concentrated among East Asian foundries, exposing lead time volatility for European and North American crane manufacturers.
- EU AI Act compliance friction:Autonomous decision system certification extends product development timelines by 12-18 months for AI-equipped port handling equipment bound for European terminals.
- Skilled technician scarcity:Mechatronics specialists capable of integrating IoT sensors with legacy hydraulic systems command premium wages, inflating field service costs.
Strategic Opportunities
- India port modernization:Sagarmala infrastructure investments create first-mover advantage for automation vendors targeting Jawaharlal Nehru Port and Visakhapatnam container terminals.
- Green hydrogen construction:Electrolyzer facility builds in Saudi Arabia and UAE require heavy-lift systems with explosion-proof certification, opening premium equipment segments.
- Digital twin convergence:Integration of physics-based simulation with real-time operational data enables outcome-based maintenance contracts, shifting revenue from hardware to recurring software services.
Industry Challenges
- Retrofit integration complexity:Tower crane fleets with 15-20 year service lives require custom sensor mounting and control interface adaptation, fragmenting project economics.
- Cybersecurity certification gaps:ISO 27001 compliance for connected crane systems lacks harmonized testing protocols across national maritime safety regulators, delaying deployment approvals.
- Operator retraining burden:Semi-autonomous control interfaces demand simulator-based certification programs that strain training infrastructure at unionized port authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Crane Market |
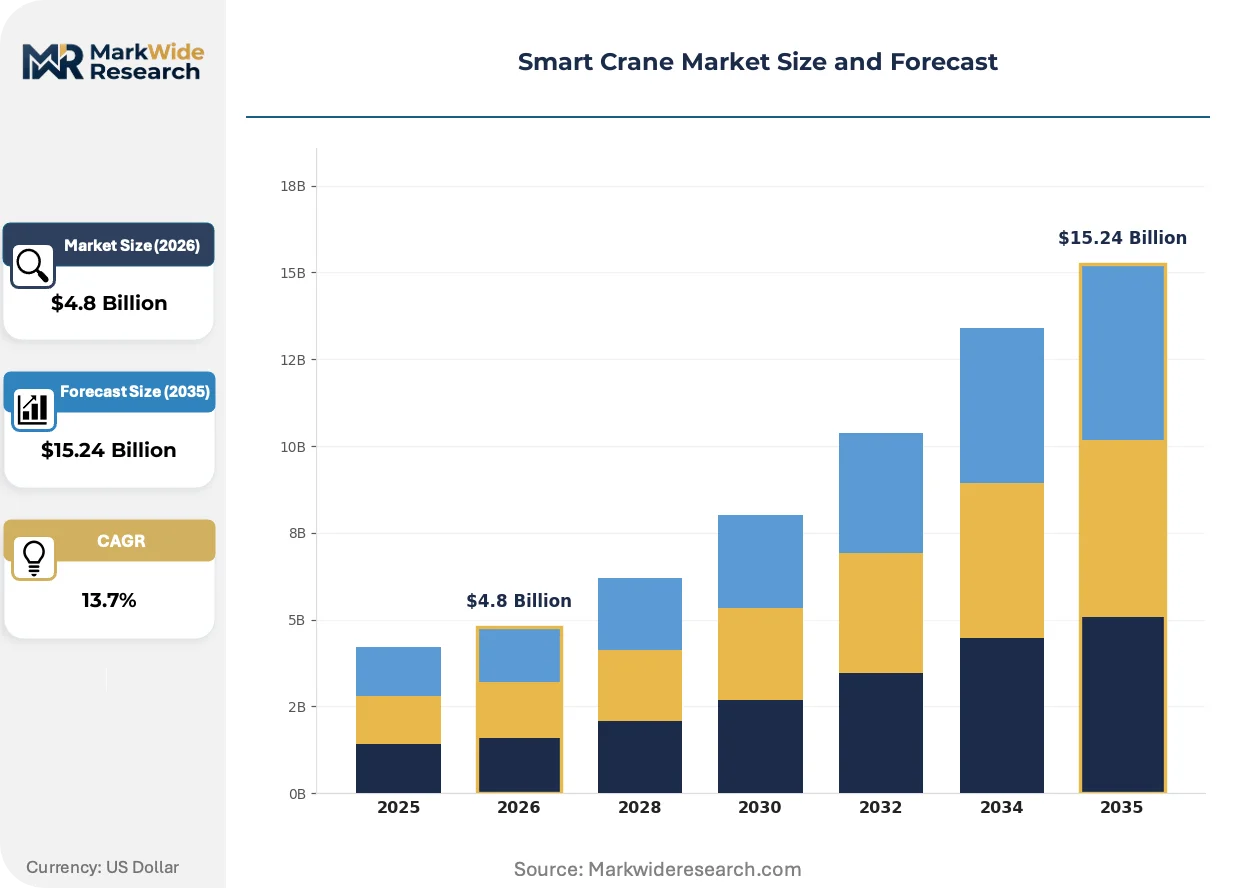
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Crane Type: Tower Crane, Mobile Crane, Overhead Crane, Jib Crane, Gantry Crane Technology: IoT-Based Control, Remote Monitoring, Predictive Maintenance, AI-Powered Automation, Wireless Communication Application: Construction Projects, Port Handling, Warehouse Management, Mining Operations, Renewable Energy Setup End User Industry: Infrastructure Developers, Shipping Terminals, Logistics Providers, Mining Corporations, Energy Producers |
| Companies Covered | Liebherr, Konecranes, Manitowoc, XCMG, SANY Group, Tadano, Terex Corporation, Zoomlion, Palfinger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Crane Market Trends and Innovations
Edge computing architectures are displacing cloud-dependent control systems, enabling real-time collision avoidance without latency vulnerability. This shift rewrites hardware specifications and service delivery models simultaneously.
LiDAR-based anti-collision systems are decentralizing safety responsibility from human operators to distributed sensor networks. Tower crane fleets in Singapore and Dubai are adopting these systems fastest, with installation rates doubling annually. The technology is decentralizing risk management across construction sites, reducing insurance premiums for fully automated fleets.
OSHA crane safety directives are tightening operator certification requirements for conventional equipment while exempting certified autonomous systems from staffing minimums. This regulatory asymmetry accelerates automation investment in US Gulf Coast petrochemical construction. Contractors in Texas and Louisiana are prioritizing AI-equipped mobile cranes to bypass union labor constraints.
Consolidated fleet management is displacing single-project crane procurement among European infrastructure developers. Specialized equipment lessors in Germany and the Netherlands now bundle predictive maintenance with short-term rental contracts. The model concentrates most visibly in offshore wind supply chain logistics, where project developers lack in-house heavy-lift expertise.
Smart Crane Market Segmentation
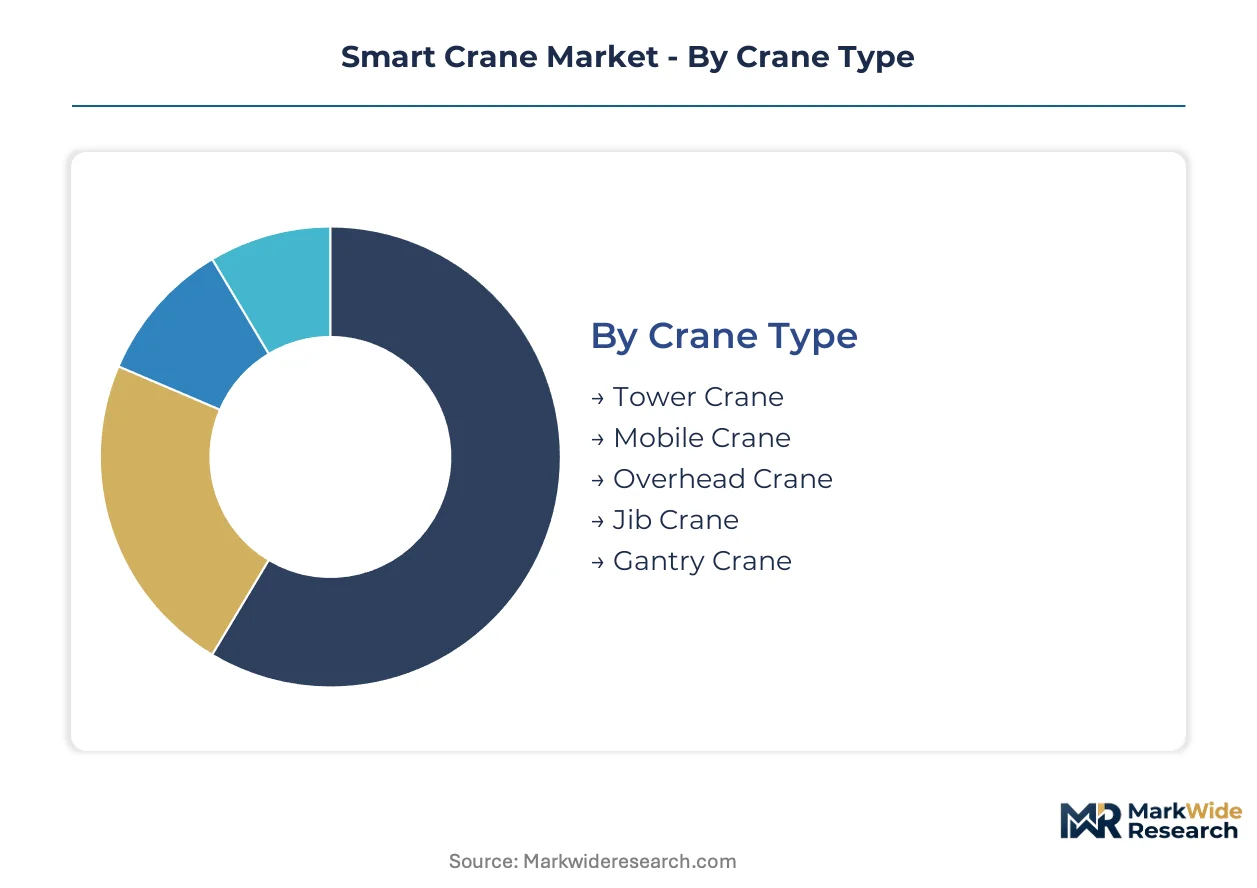
Equipment replacement cycles and control system upgrade timelines fragment procurement patterns across crane types and end-use verticals. Segmentation reveals where sensor integration commands premium pricing versus where retrofit economics stall adoption.
Crane Type:
Replacement cycles vary sharply by structural complexity and duty intensity, with port automation driving shorter upgrade intervals than construction tower fleets.
- Tower Crane:Fixed-base structures dominate high-rise construction with integrated load moment indicators and anti-collision zoning. Demand concentrates in Singapore and Dubai where skyscraper density justifies permanent installation; regulatory mandates for operator visibility systems accelerate control system refresh cycles.
- Mobile Crane:Self-propelled units with telescopic booms serve project-based deployment where fleet flexibility outweighs automation depth. All-terrain variants capture expanding share in German wind farm construction where roadability constraints dictate specification; CE marking for sensor-integrated stability control extends replacement timelines.
- Overhead Crane:Bridge-mounted systems serve manufacturing and warehouse verticals with precision positioning requirements.
- Jib Crane:Articulated boom configurations address confined workspace applications in shipbuilding and maintenance bays.
- Gantry Crane:Rail-mounted portal structures dominate container terminal operations where span width determines throughput capacity.
Volume placements concentrate in Tower Crane; the faster expansion belongs to Mobile Crane.
Technology:
Technology selection follows end-use risk tolerance, with hazardous environment applications demanding redundant control architectures that inflate system costs.
- IoT-Based Control:Distributed sensor networks enable real-time load monitoring and equipment health telemetry through edge computing architectures. Port operators in Rotterdam and Hamburg deploy these systems to consolidate fleet visibility; 5G network availability determines deployment feasibility in remote construction sites.
- AI-Powered Automation:Machine vision and path-planning algorithms displace operator intervention in repetitive container handling cycles. North Sea offshore wind installers specify these systems for turbine component positioning where millimetre tolerances exceed human precision; EU AI Act compliance documentation extends procurement lead times.
- Remote Monitoring:Cloud-connected diagnostics platforms aggregate operational data for centralized maintenance scheduling.
- Predictive Maintenance:Vibration analysis and thermal imaging algorithms forecast component failure before operational interruption.
- Wireless Communication:Mesh networking protocols replace cable-based control in applications requiring operator mobility.
Technology adoption concentrates in IoT-Based Control; the steepest expansion trajectory belongs to AI-Powered Automation.
Application:
Application-specific duty cycles determine sensor durability specifications and software customization requirements.
- Construction Projects:Temporary installation patterns favor rental fleet models where predictive maintenance subscriptions bundle with equipment lease. Urban megaprojects in Shenzhen and Mumbai specify anti-collision systems for dense site conditions; OSHA crane safety directives tighten operator certification requirements that automation bypasses.
- Port Handling:Continuous operation regimes demand 99.9% uptime guarantees that shift vendor liability toward outcome-based service contracts. European container terminals consolidate procurement around integrated automation platforms; labor union agreements constrain deployment speed at unionized US Gulf Coast facilities.
- Warehouse Management:Overhead crane networks serve distribution centers where inventory velocity dictates retrieval speed.
- Mining Operations:Dust and vibration exposure requires hardened sensor enclosures and extended calibration intervals.
- Renewable Energy Setup:Offshore wind turbine assembly commands specialized heavy-lift capacity with explosion-proof certification for floating platform work.
Deployment volume concentrates in Construction Projects; the fastest share gain belongs to Port Handling.
End User Industry:
Customer sophistication with automation technology fragments procurement authority between fleet managers and project contractors.
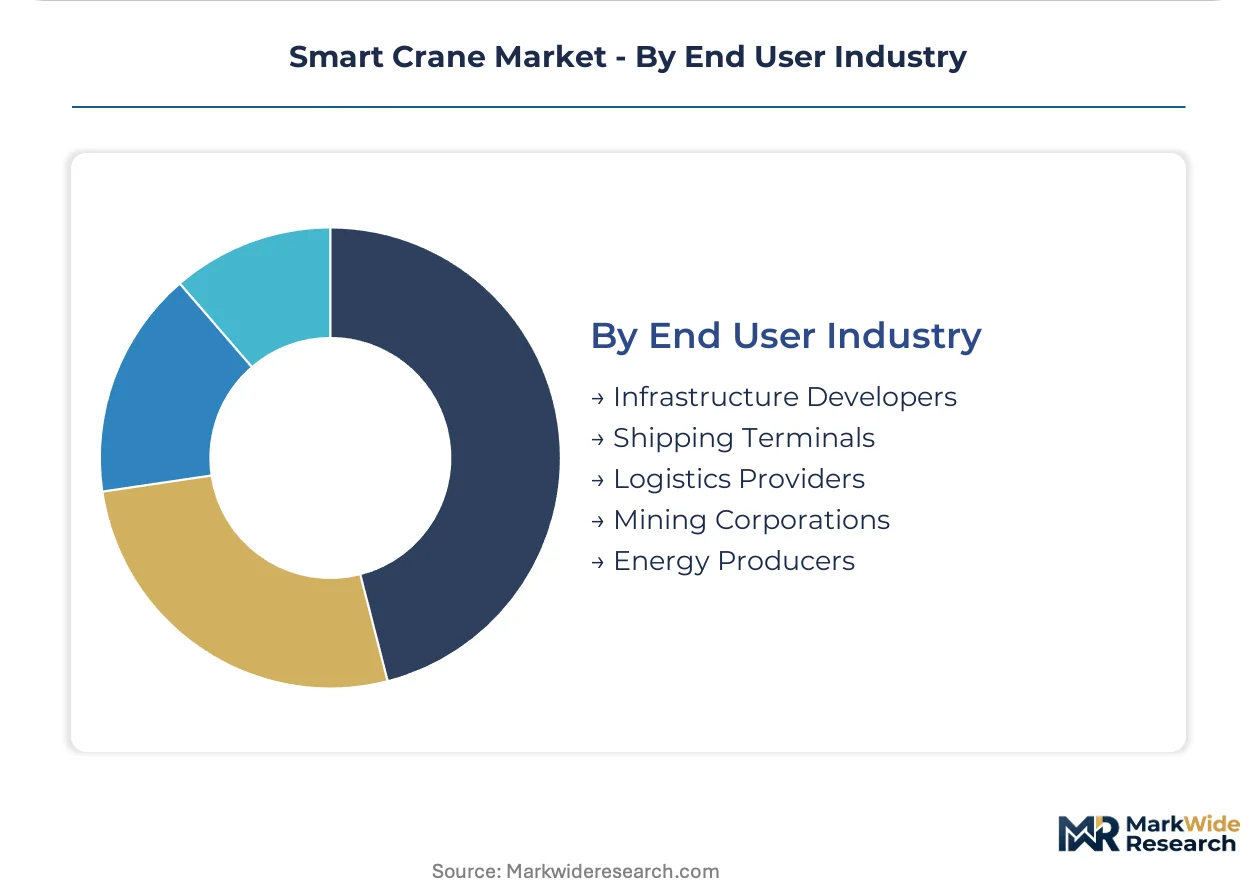
- Infrastructure Developers:Long-horizon project pipelines justify captive crane fleets with dedicated maintenance infrastructure. State-backed developers in China consolidate demand across provincial high-speed rail and airport construction; financing availability through policy banks accelerates smart equipment procurement.
- Shipping Terminals:Volume-based throughput metrics drive automation investment with payback calculations tied to labor cost avoidance. PSA International and DP World standardize control platforms across multi-port networks; equipment lessors in Germany bundle short-term rental with predictive maintenance subscriptions.
- Logistics Providers:Third-party warehouse operators prioritize equipment interoperability across multi-client facilities.
- Mining Corporations:Pit extraction operations demand ruggedized systems with remote diagnostics for geographically dispersed sites.
- Energy Producers:Utility-scale renewable developers lack in-house heavy-lift expertise, outsourcing to specialized contractors.
Procurement volume concentrates in Infrastructure Developers; the most rapid customer base expansion belongs to Shipping Terminals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volume through state-backed port modernization and renewable energy construction, while European shipping terminals and US Gulf Coast petrochemical developers fragment demand across specialized automation vendors.
China
State policy banks finance smart crane deployment across coastal provinces for container terminal automation and offshore wind turbine assembly. MIIT industrial upgrading directives mandate sensor integration for heavy equipment in strategic sectors. Shanghai Yangshan Port and Shenzhen Shekou Terminal anchor automation adoption, with provincial state-owned enterprises consolidating fleet procurement under integrated service contracts.
Germany
Offshore wind installation in the North Sea and Baltic Sea creates specialized demand for millimetre-precision positioning systems. CE marking requirements under EU machinery safety directives compress replacement cycles for sensor-integrated lifting equipment. Port operators in Hamburg and Bremerhaven consolidate control system procurement around predictive maintenance platforms, extending software subscription lifecycles across container terminal fleets.
United States
OSHA crane safety directives tighten operator certification requirements while exempting certified autonomous systems from staffing minimums, accelerating automation investment in Texas and Louisiana petrochemical construction. FAA crane operation standards near airport zones shape equipment certification timelines for sensor integration. Gulf Coast contractors prioritize AI-equipped mobile cranes to bypass union labor constraints in hazardous environments.
Singapore
Skyscraper density in the city-state justifies permanent tower crane installation with integrated anti-collision zoning and load moment indicators. The country's national workplace safety regulator mandates operator visibility systems that accelerate control system refresh cycles. PSA International standardizes automation platforms across its container terminal network, concentrating vendor relationships around long-term service agreements.
India
Sagarmala infrastructure investments create first-mover opportunity for automation vendors targeting Jawaharlal Nehru Port and Visakhapatnam container terminals. The Central Electricity Authority mandates grid-scale renewable integration that drives heavy-lift demand for solar and wind component installation. Maharashtra and Gujarat coastal zones concentrate port modernization activity, with state maritime boards streamlining environmental clearances for automated terminal equipment.
Smart Crane Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-powered automation and predictive maintenance software as differentiation vectors. The vendor base organizes around three archetypes: European port automation specialists with service-contract anchoring, Chinese manufacturing-scale competitors with cost advantages in mobile crane production, and diversified industrial conglomerates with cross-sector control system platforms. Competitive moves concentrate on strategic partnerships for 5G-enabled remote operation capabilities and backward integration into sensor and PLC component supply.
Within the port automation tier, Konecranes and Liebherr exemplify European specialists anchoring long-term service relationships in shipping terminals. XCMG occupies a position among Chinese manufacturing-scale competitors, sustaining cost advantages in mobile crane production for Asian construction markets. Terex Corporation sits within the diversified industrial conglomerate archetype, with control system platforms spanning multiple heavy equipment categories.
| Leading Market Players |
|---|
| Liebherr |
| Konecranes |
| Manitowoc |
| XCMG |
| SANY Group |
| Tadano |
| Terex Corporation |
| Zoomlion |
| Palfinger |
| Others |
Pricing and Supply Chain Analysis
Steel price indices and rare earth magnet costs cascade through smart crane manufacturing into tiered equipment pricing, with sensor-integrated tower cranes commanding substantial premiums over conventional mobile units while semiconductor-laden control systems expose buyers to volatile component pass-through.
Pricing Analysis
Volume placements concentrate in standard-tier mobile cranes serving Asian construction markets, while margin pools accrue to premium-tier port automation systems with embedded predictive maintenance subscriptions. Price differentiation rests on CE marking certification and AI-powered automation depth, with EU-bound equipment carrying substantial compliance premiums. Cost compression in standard-tier mobile cranes is intensifying because Chinese manufacturing-scale competitors sustain aggressive export pricing. Infrastructure developers in emerging markets exhibit highest price sensitivity, whereas European shipping terminals prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale port operator demand, while specialized equipment lessors intermediate project-based construction procurement. Manufacturing concentrates in China, Germany, and Finland, with PLC and VFD component sourcing anchored in Taiwan and South Korea. Supply chains draw from high-grade structural steel, rare earth permanent magnets, and silicon carbide semiconductors. Single-source vulnerability in advanced sensor modules exposes European and North American crane builders to lead time volatility. Distribution runs through captive service networks for port automation and rental fleet intermediaries for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart crane markets are transitioning from hydraulic-mechanical systems to AI-powered autonomous platforms, with edge computing architectures displacing legacy cloud-dependent control systems across container terminals and high-rise construction sites.
For Market Incumbents: Extend predictive maintenance subscription coverage to capture recurring revenue streams and offset hardware margin compression. Consolidate sensor and PLC component supply through backward integration or long-term offtake agreements with Taiwanese foundries to mitigate semiconductor supply concentration risks. Defend against emerging AI-native automation vendors by embedding machine vision capabilities into existing port handling equipment fleets. For New Entrants and Emerging Players: Enter via India's Sagarmala port modernization program, where Jawaharlal Nehru Port and Visakhapatnam container terminals lack entrenched automation vendors. Target green hydrogen construction verticals in Saudi Arabia and UAE, where explosion-proof certification requirements create barrier-protected premium segments. Pursue outcome-based maintenance contracts with state-owned infrastructure developers in Maharashtra and Gujarat coastal zones. For Investors and Strategic Acquirers: Distressed-cycle entries favor European port automation specialists with anchored service contracts in Hamburg and Rotterdam terminal networks. Long-term viability hinges on software-defined revenue mix exceeding hardware sales across the projection horizon. Monitor 5G network deployment timelines in remote construction zones as inflection indicator for remote operation capability monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive PLC sourcing mitigates Taiwan foundry lead time volatility for European crane builders. |
| Predictive Maintenance Platform Launch | Software subscriptions shift revenue from hardware sales to recurring services at Rotterdam terminals. |
| 5G-Enabled Remote Operation Partnership | Ultra-low latency networks reduce on-site staffing requirements in North Sea offshore wind zones. |
| CE Marking Fast-Track Investment | Accelerated EU machinery safety compliance captures replacement cycles in German construction markets. |
| Digital Twin Convergence Development | Physics-based simulation integration enables outcome-based contracts with PSA International terminal networks. |
Research Methodology
Independent corroboration across equipment procurement directors at European shipping terminals, automation engineers at Chinese port authorities, and aftermarket service heads at German crane lessors underwrites the qualitative findings. Primary fieldwork encompassed maintenance directors at Singapore high-rise developers, plant engineers at US Gulf Coast petrochemical contractors, and OEM procurement teams at Indian infrastructure conglomerates. Secondary validation drew from MIIT industrial equipment databases, EU machinery safety directive implementation records, OSHA crane incident reports, and customs trade data for sensor-integrated lifting equipment. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separated equipment replacement cycle dynamics from technology upgrade adoption curves throughout the forecast period. Segmentation dimensions encompassed crane type, control system architecture, end-use application, and regional regulatory cluster. CAGRs were derived from installed base growth projections and average selling price trajectories. Forecast inputs incorporated 5G network deployment schedules, EU AI Act compliance timeline assumptions, and Sagarmala infrastructure investment disbursement patterns.
Revisions become necessary when semiconductor supply chain disruptions exceed historical volatility bands or when EU machinery safety directives introduce unanticipated sensor integration mandates. Forecasts reflect documented assumptions regarding port automation adoption rates and offshore wind installation activity levels. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Backhoes Market
Construction Equipment
Powered Screed Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Global Light Towers Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
Grinding Machinery Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Construction Lasers Market