
 India Construction Equipment Rental Market | 2026-2036
India Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
India Construction Equipment Rental Market Outlook
Modular equipment bundling—combining excavators with operator and maintenance services into single contracts—is realigning procurement preferences across India's construction sector. Sanghvi Movers Limited anchors its position through specialized crane fleet depth across heavy-lift infrastructure sites. ABC Infra Equipment differentiates via technology leadership in telematics-enabled fleet tracking for remote project monitoring. Equipment Rentals India leverages its digital platform to control channel access across tier-2 and tier-3 city contractors.
Construction equipment rental denotes the commercial provision of heavy machinery—typically rated by engine horsepower, operating weight, and lift capacity—on temporary contractual terms rather than outright purchase, serving project-based demand with capital efficiency. Excavators dominate rental volumes due to versatility across earthmoving, trenching, and demolition phases, while cranes command premium rate structures owing to specialized operator certification requirements and higher insurance thresholds. Infrastructure Projects represent the fastest-growing end-user segment as government-funded highways, railways, and urban transit schemes multiply project pipelines nationwide.
BIS certification mandates for construction machinery safety standards shape equipment eligibility for government contract participation, while CEA electrical safety protocols govern powered rental assets deployed on electrified work sites. The PLI scheme for infrastructure equipment manufacturing is restructuring domestic supply availability and import dependency ratios for rental fleet operators. Stakeholders must monitor evolving emission norms from the Ministry of Environment and Forests as diesel-powered fleet compliance costs reshape rental rate structures and replacement timelines.
Market Dynamics
Modular equipment bundling is compressing procurement cycles across India's construction sector, forcing rental operators to restructure fleet deployment around integrated service contracts rather than standalone asset provision.
Growth Catalysts
- PLI Scheme for Infrastructure Manufacturing:Domestic production incentives under India's PLI scheme are expanding local equipment availability and reducing import dependency for rental fleet operators.
- Metro Rail Expansion:Urban transit projects in Maharashtra, Karnataka, and Tamil Nadu are generating concentrated demand for specialized crane and piling equipment rentals.
- Telematics Penetration:IoT-enabled fleet tracking systems are improving asset utilization rates and enabling predictive maintenance scheduling across remote project sites.
Market Restraints
- Diesel Emission Compliance:Ministry of Environment and Forests norms are elevating retrofit costs for existing fleet assets and accelerating replacement timelines.
- Specialized Operator Scarcity:Crane and heavy-lift equipment faces certified operator shortages that constrain fleet expansion regardless of capital availability.
- Steel Price Volatility:Input cost fluctuations for equipment manufacturing are transmitting into higher rental rate floors and compressed operator margins.
Strategic Opportunities
- Tier-2 and Tier-3 City Penetration:Digital platform expansion into secondary urban centers is unlocking contractor segments previously underserved by organized rental channels.
- Electrified Fleet Transition:CEA electrical safety protocol alignment for battery-powered equipment is creating first-mover advantages for operators with certified electric assets.
- Highway Maintenance Contracts:Post-concession road rehabilitation work is generating recurring rental demand distinct from project-based cyclicality.
Industry Challenges
- BIS Certification Timelines:Construction machinery safety standard approvals are creating equipment eligibility gaps that delay government contract participation.
- Telematics-Legacy System Integration:Retrofitting older fleet assets with remote monitoring capabilities requires capital outlays that conflict with utilization-focused business models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Construction Equipment Rental Market |
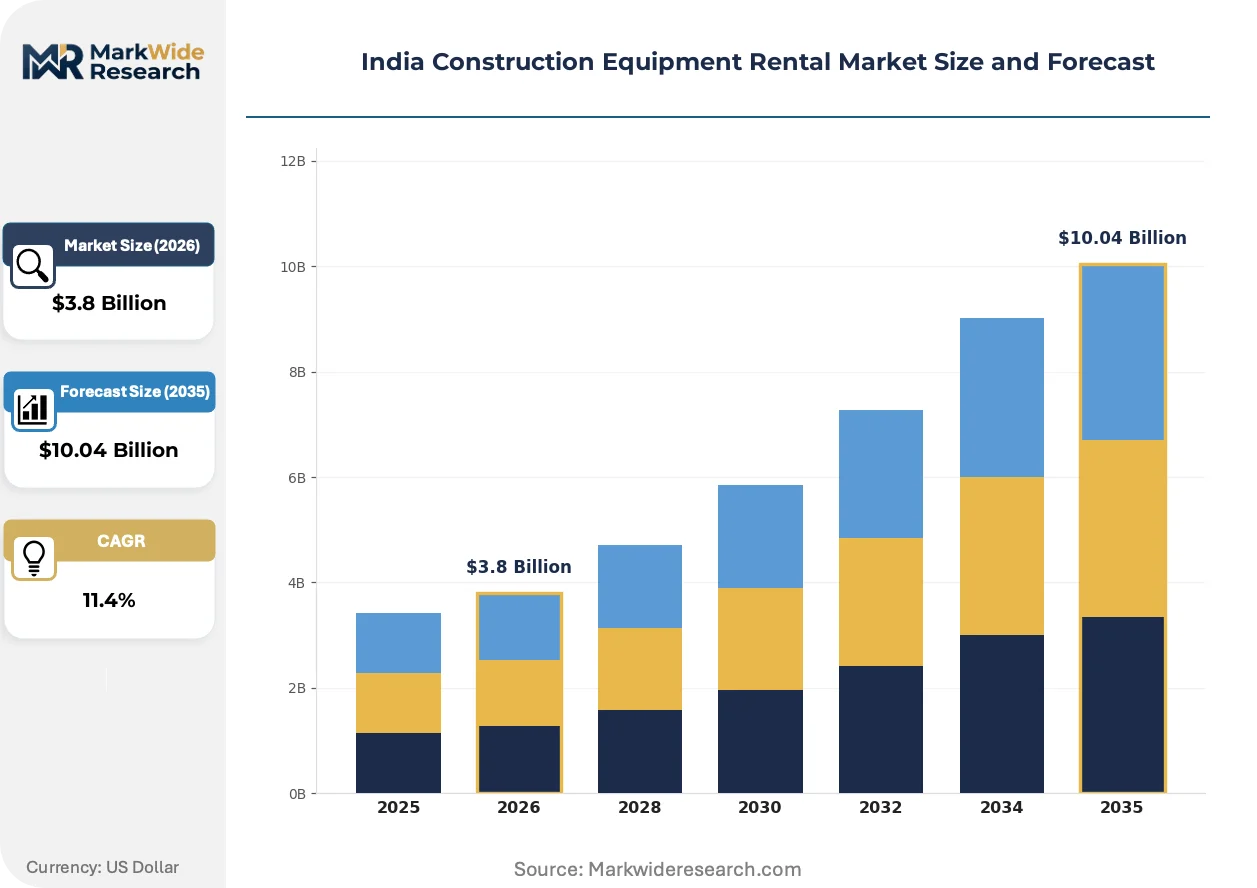
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Backhoe Loaders End User: Residential Projects, Commercial Projects, Infrastructure Projects, Industrial Projects Deployment Model: On-Site Rentals, Long-Term Rentals, Short-Term Rentals, Lease Agreements Service Type: Operator Services, Maintenance Services, Delivery Services, Training Services |
| Companies Covered | Indiabulls Store One, Jindal Infrastructure, Sanghvi Movers Limited (SML), Mahindra Construction Equipment, All India Crane Hiring Co, Volvo Construction Equipment, ABC Infra Equipment, Equipment Rentals India (ERI), Quippo Construction Equipment Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Construction Equipment Rental Market Strategic Shifts
Telematics and predictive maintenance systems are fundamentally altering how rental operators manage asset lifecycles and price risk across fragmented project pipelines.
IoT-enabled fleet management platforms are integrating real-time location tracking, fuel consumption monitoring, and predictive failure alerts into unified dashboards. Highway contractors and metro rail developers are adopting these systems fastest, demanding remote visibility over equipment deployed across dispersed sites. The technology is integrating maintenance scheduling with project timelines, compressing downtime windows and enabling outcome-based contract structures.
India's BIS certification mandates for construction machinery safety standards are tightening equipment eligibility criteria for government infrastructure tenders. Rental operators must now maintain documented compliance trails for entire fleet segments to participate in public sector contracts. Metro rail and port modernization projects in Maharashtra are experiencing the steepest compliance cost escalations as certification renewal cycles compress.
Contractors are consolidating procurement relationships around single-source rental partners capable of bundling equipment, certified operators, and maintenance into unified contracts. Road and highway construction firms are abandoning fragmented multi-vendor arrangements that fragment accountability. The Mumbai-Pune industrial corridor exhibits this pattern most acutely, where project cycle compression leaves no margin for coordination failures between separate equipment and service providers.
India Construction Equipment Rental Market Segmentation
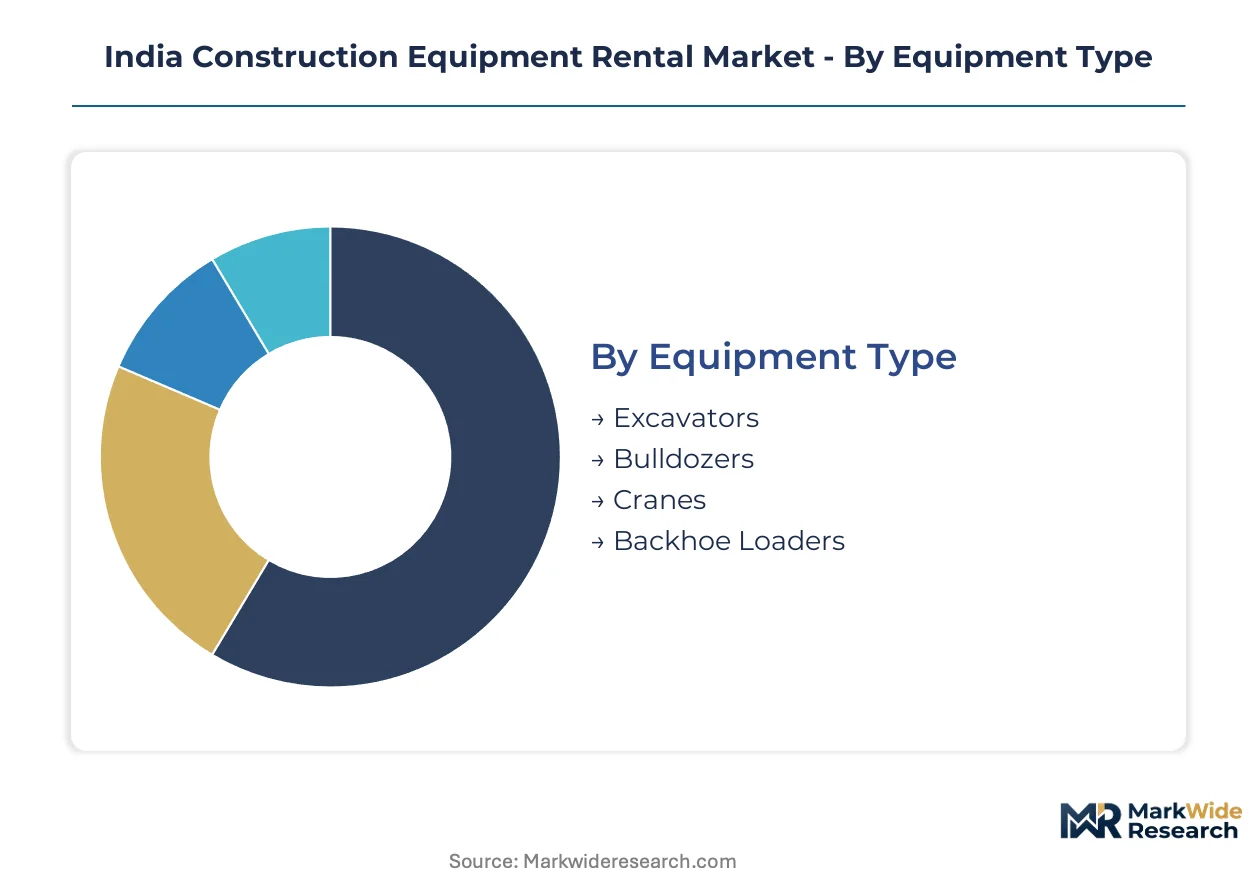
Segmentation in India's construction equipment rental market reveals how procurement complexity varies dramatically across project types and contract structures. Rental operators configure service bundles differently depending on whether contractors seek capital efficiency for short-cycle highway work or predictable costs for multi-year metro rail developments.
Equipment Type:
Standardization dominates high-volume earthmoving categories while specialized lifting equipment demands customized fleet configurations and certified operator pairings.
- Excavators:Hydraulic machines rated by operating weight and bucket capacity serve trenching, demolition, and material handling across project phases. Demand concentrates in Maharashtra's Mumbai-Pune corridor where metro rail earthworks and port modernization require versatile fleet deployment with rapid mobilization capabilities.
- Cranes:Tower and mobile cranes classified by lift capacity and boom configuration command premium rate structures due to specialized operator certification requirements and elevated insurance thresholds. Infrastructure Projects in Karnataka and Tamil Nadu generate concentrated demand for heavy-lift equipment serving urban transit schemes.
- Bulldozers:Tracked dozers with blade-rated horsepower handle bulk earthmoving and grading operations across highway construction sites.
- Backhoe Loaders:Dual-function machines combining loader and excavator capabilities serve smaller-scale residential and commercial project sites with lower mobilization costs.
Most installed capacity flows through Excavators. Expansion is steepest in Cranes.
End User:
Project scale and funding source create distinct rental procurement patterns across customer segments.
- Infrastructure Projects:Government-funded highways, railways, and urban transit schemes drive the steepest equipment demand trajectory. Metro rail developments in Maharashtra, Karnataka, and Tamil Nadu require specialized crane and piling equipment with extended rental tenures.
- Commercial Projects:Private sector developments across office, retail, and hospitality verticals favor flexible short-term arrangements with rapid equipment rotation between sites.
- Residential Projects:Housing construction and urban redevelopment generate consistent demand for compact excavators and backhoe loaders.
- Industrial Projects:Manufacturing facility construction and port modernization require heavy-lift crane capacity with BIS-certified safety compliance documentation.
Revenue concentration sits with Infrastructure Projects. Commercial Projects show the most volatile demand cyclicality.
Deployment Model:
Contract duration and asset control terms segment procurement preferences across contractor risk appetites.
- On-Site Rentals:Equipment remains dedicated to single project locations with full operator and maintenance support included. Highway contractors in the Mumbai-Pune corridor favor this model for complex earthworks with unpredictable duration.
- Long-Term Rentals:Extended contracts spanning 12-36 months provide cost predictability for multi-phase metro rail and port modernization developments.
- Short-Term Rentals:Daily or weekly arrangements serve peak demand periods and equipment breakdown coverage with premium rate structures.
- Lease Agreements:Operating leases transfer maintenance liability to rental operators while preserving contractor balance sheet flexibility.
Transaction volume peaks in Short-Term Rentals. Margin stability concentrates in Long-Term Rentals.
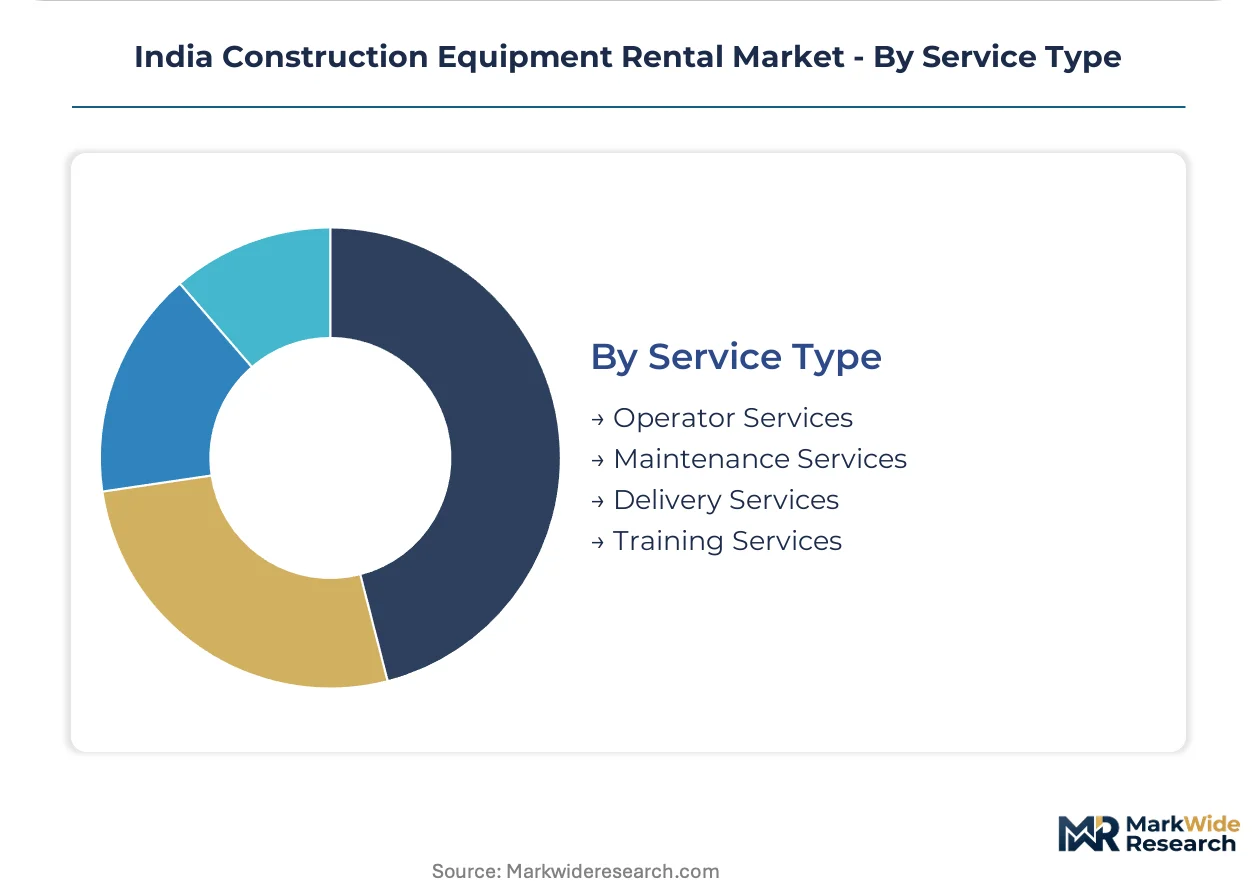
Service Type:
Service bundling intensity separates premium rental providers from commodity equipment suppliers.
- Operator Services:Certified equipment operation with specialized crane and heavy-lift credentials addresses acute skilled labor scarcity constraining fleet expansion regardless of capital availability.
- Maintenance Services:Preventive and corrective maintenance bundled into rental rates reduces contractor downtime risk across dispersed project sites.
- Delivery Services:Lowbed transportation and site mobilization logistics enable rapid equipment positioning for time-sensitive highway and metro rail schedules.
- Training Services:Operator skill development and safety certification programs support contractor compliance with BIS machinery safety standards and CEA electrical protocols.
Attachment rates are highest for Operator Services. Training Services show the lowest penetration but steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's construction equipment rental industry traces its modern scale to the post-liberalization infrastructure push of the 1990s, when highway privatization created the first organized rental demand clusters around Mumbai and Delhi.
Maharashtra
The Mumbai-Pune corridor generates India's densest crane rental demand as metro rail earthworks and Jawaharlal Nehru Port Trust modernization compress project timelines. BIS certification requirements for construction machinery safety standards elevate compliance costs for fleet operators serving state government contracts. Sanghvi Movers Limited anchors heavy-lift capacity across the region's infrastructure sites.
Karnataka
Bengaluru's suburban rail expansion and peripheral ring road projects drive specialized piling equipment rentals with extended tenures. The state's urban development authorities mandate CEA electrical safety protocols for powered assets deployed on electrified transit corridors. Equipment Rentals India controls digital channel access across tier-2 city contractors in the Mysuru-Belagavi belt.
Tamil Nadu
Chennai Metro Phase II and Ennore port expansion create concentrated demand for telescopic crawler cranes with certified operators. PLI scheme incentives for infrastructure manufacturing are expanding domestic equipment availability for Chennai-based rental operators. ABC Infra Equipment deploys telematics-enabled fleets across the state's dispersed project sites.
Gujarat
Dholera Special Investment Region and Ahmedabad-Mumbai high-speed rail construction require modular equipment bundling with integrated maintenance services. DGFT import regulations shape fleet composition for operators dependent on foreign-manufactured heavy-lift assets. Surat and Vadodara industrial corridors exhibit the fastest adoption of long-term rental contracts with outcome-based pricing.
Telangana
Hyderabad Regional Ring Road and metro extension projects generate volatile short-term rental spikes with premium rate structures. State pollution control board emission norms are accelerating diesel fleet replacement timelines beyond national mandates. The Hyderabad-Warangal industrial corridor attracts new rental entrants targeting highway maintenance contract recurring revenue.
India Construction Equipment Rental Market Competitive Environment
Premium-margin players sit above commodity-margin players across service bundling intensity, with integrated operator-maintenance contracts commanding rate spreads of 15-25% over standalone equipment provision. The market structures around three tiers: national fleet operators with telematics infrastructure, regional specialists with crane-heavy portfolios, and digital platforms controlling tier-2 channel access. Strategic moves concentrate on fleet electrification alignment with CEA protocols and backward integration into certified operator training to address skilled labor scarcity.
Within the national fleet tier, Sanghvi Movers Limited exemplifies crane-specialist depth across heavy-lift infrastructure sites. Equipment Rentals India occupies the digital platform archetype with channel control across secondary urban markets. ABC Infra Equipment represents technology-led positioning through telematics-enabled fleet tracking capabilities. These three anchors illustrate how competitive differentiation fragments across equipment specialization, digital infrastructure, and service integration rather than scale alone.
| Leading Market Players |
|---|
| Indiabulls Store One |
| Jindal Infrastructure |
| Sanghvi Movers Limited (SML) |
| Mahindra Construction Equipment |
| All India Crane Hiring Co |
| Volvo Construction Equipment |
| ABC Infra Equipment |
| Equipment Rentals India (ERI) |
| Quippo Construction Equipment Limited |
| Others |
Value Chain & Pricing Dynamics
Backward integration into certified operator training anchors both supply security and rate-setting power for rental operators serving BIS-mandated government contracts. This captive capability insulates premium service tiers from skilled labor scarcity while compressing procurement cycles for contractors bundling equipment with compliance documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by service bundling intensity and certification grade. Premium tiers command spreads over standalone equipment through integrated operator-maintenance contracts, while price erosion runs through economy tiers as digital platforms compress channel margins. Infrastructure Projects exhibit lowest price sensitivity due to BIS compliance requirements, whereas Residential Projects drive hardest bargain on mobilization fees.
Supply Chain Analysis
Refurbishment flows from end-of-lease assets back into short-term rental pools extend fleet economic life and buffer new equipment procurement cycles. Domestic manufacturing under India's PLI scheme draws from steel, hydraulics, and engine component suppliers concentrated in Maharashtra, Gujarat, and Tamil Nadu. Single-source vulnerability sits with imported crane sub-assemblies subject to DGFT licensing delays. Distribution runs through direct sales forces for large infrastructure contractors and digital platforms for tier-2 city penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's construction equipment rental market functions as a regulatory compounder where BIS certification mandates for construction machinery safety standards continuously restructure competitive access to government-funded infrastructure pipelines.
For Market Incumbents: To counter telematics-enabled new entrants, Sanghvi Movers Limited and ABC Infra Equipment should deepen captive operator training capacity and secure multi-year maintenance contracts with metro rail developers. Certification investment in CEA electrical safety protocols for battery-powered fleets creates switching costs against commodity rental challengers. For New Entrants and Emerging Players: The 15-25% rate spread between premium bundled services and standalone equipment provision opens white-space in tier-2 city contractor segments underserved by organized channels. Equipment Rentals India's digital platform model demonstrates channel control viability across the Mysuru-Belagavi belt. Target highway maintenance contracts with recurring revenue profiles distinct from project-based cyclicality. For Investors and Strategic Acquirers: Roll-up economics work for regional crane specialists because BIS compliance documentation creates intangible asset value transferable across acquirer platforms. Long-term viability hinges on electrified fleet alignment with Ministry of Environment and Forests emission trajectories. Monitor PLI scheme disbursement velocity as inflection indicator for domestic supply expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Deployment | IoT-enabled fleet tracking compresses downtime windows for metro rail contractors. |
| Certified Operator Training Expansion | BIS-mandated credentials address skilled labor scarcity constraining crane fleet growth. |
| Electric Fleet Certification | CEA electrical safety protocol alignment secures first-mover positioning for battery-powered assets. |
| Tier-2 Digital Channel Buildout | Platform access controls procurement relationships across previously fragmented secondary markets. |
| Highway Maintenance Contract Aggregation | Recurring revenue streams reduce exposure to project-based demand cyclicality. |
Study Parameters
Coverage spans Maharashtra, Karnataka, Tamil Nadu, Gujarat, and Telangana, with primary inputs from each state's infrastructure development authorities and rental operator networks. The analysis combines structured interviews with fleet managers, project procurement officers at highway and metro rail developers, and maintenance directors at EPC contractors with secondary validation from BIS certification records, CEA electrical safety filings, and PLI scheme disbursement disclosures. Bottom-up equipment deployment estimates triangulate against top-down infrastructure budget allocations.
Rate-of-change decomposition separates volume expansion from mix-shift effects across the projection horizon. The analytical framework models equipment type, end-user segment, deployment model duration, and service bundling intensity as core segmentation dimensions. CAGRs derive from fitted growth curves applied to project pipeline data from state urban development authorities and National Highways Authority of India tender announcements.
Caveats apply where Ministry of Environment and Forests emission norm revisions or BIS certification timeline extensions could materially shift the outlook for diesel fleet replacement economics. Practitioners should monitor PLI scheme domestic production incentive disbursements and CEA protocol updates for battery-powered equipment for early signals of supply-side restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hoist and Winches Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
North America Drilling Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
Snow Pushers Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Metal Machinery Market